
 AEC Market | 2026-2036
AEC Market Size, Share, and Industry Trends Forecast 2026-2036
AEC Market Analysis
The capital-intensity divergence between asset-heavy contractors and lean design specialists is bifurcating competitive dynamics across the AEC landscape. Bechtel Corporation leverages its self-perform construction capability to anchor margins on complex industrial and energy projects. WSP Global differentiates through engineering-led consulting across transit and environmental infrastructure in North America and Europe. Jacobs Solutions sustains R&D intensity in digital delivery platforms that integrate design with operational technology.
Architecture, engineering, and construction (AEC) encompasses the integrated planning, design, and physical realization of buildings and infrastructure, spanning structural engineering, MEP systems, geotechnical analysis, and construction management with specifications often governed by ISO 19650 for information management. Its primary purpose is translating owner requirements into safe, cost-controlled, and code-compliant built assets across asset lifecycles. Construction services command the largest revenue pool given fixed-cost exposure and bonding requirements, while BIM technology represents the fastest-expanding segment as owners mandate federated digital twins for facility handover. Consulting and design services occupy higher-margin positions where specialized technical expertise limits competitive entry.
The EU Green Deal and F-Gas Regulation shape European demand by mandating embodied carbon disclosure and low-GWP material selection in new buildings, while the US EPA and OSHA frameworks govern site remediation protocols and worker safety standards that affect project sequencing and cost. China's MIIT and GB standards enforce domestic digital construction mandates that restrict market access without localized platform compliance. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs become a decisive bid-factor in cross-border project competition.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are compressing project timelines and forcing design-stage digital verification across commercial developments, creating a structural premium on BIM-enabled delivery capability.
Growth Catalysts
- ISO 19650 compliance mandates:Government-backed megaprojects in the United Arab Emirates now require federated digital twins for facility handover, accelerating software procurement cycles.
- Smart city infrastructure programs:Middle East sovereign wealth funds are digitizing procurement workflows across transit, energy, and municipal assets.
- Building energy codes:The F-Gas Regulation and EU Green Deal standards mandate low-GWP material selection and digital design verification for new commercial buildings.
Market Restraints
- Specialized labor scarcity:Geotechnical analysis and MEP systems engineering face acute talent shortages in high-growth Gulf markets.
- Platform compliance barriers:China's MIIT and GB standards enforce domestic digital construction mandates that restrict market access without localized certification.
- Bonding cost escalation:Fixed-cost exposure on complex industrial projects requires escalating surety capacity that squeezes mid-tier contractors.
Strategic Opportunities
- Saudi Arabia giga-project pipeline:NEOM and Red Sea developments represent underpenetrated demand for integrated design-build-digital delivery.
- Operational technology convergence:Federated digital twins merging BIM with IoT sensor networks create new recurring revenue streams.
- CSRD-aligned carbon accounting:The EU's Corporate Sustainability Reporting Directive creates service demand for embodied carbon tracking and verification.
Industry Challenges
- Interoperability fragmentation:Proprietary BIM platforms create data silos that complicate multi-stakeholder project handovers.
- Skill-set displacement:Traditional drafting and manual quantity surveying face compression as generative design tools automate routine tasks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AEC Market |
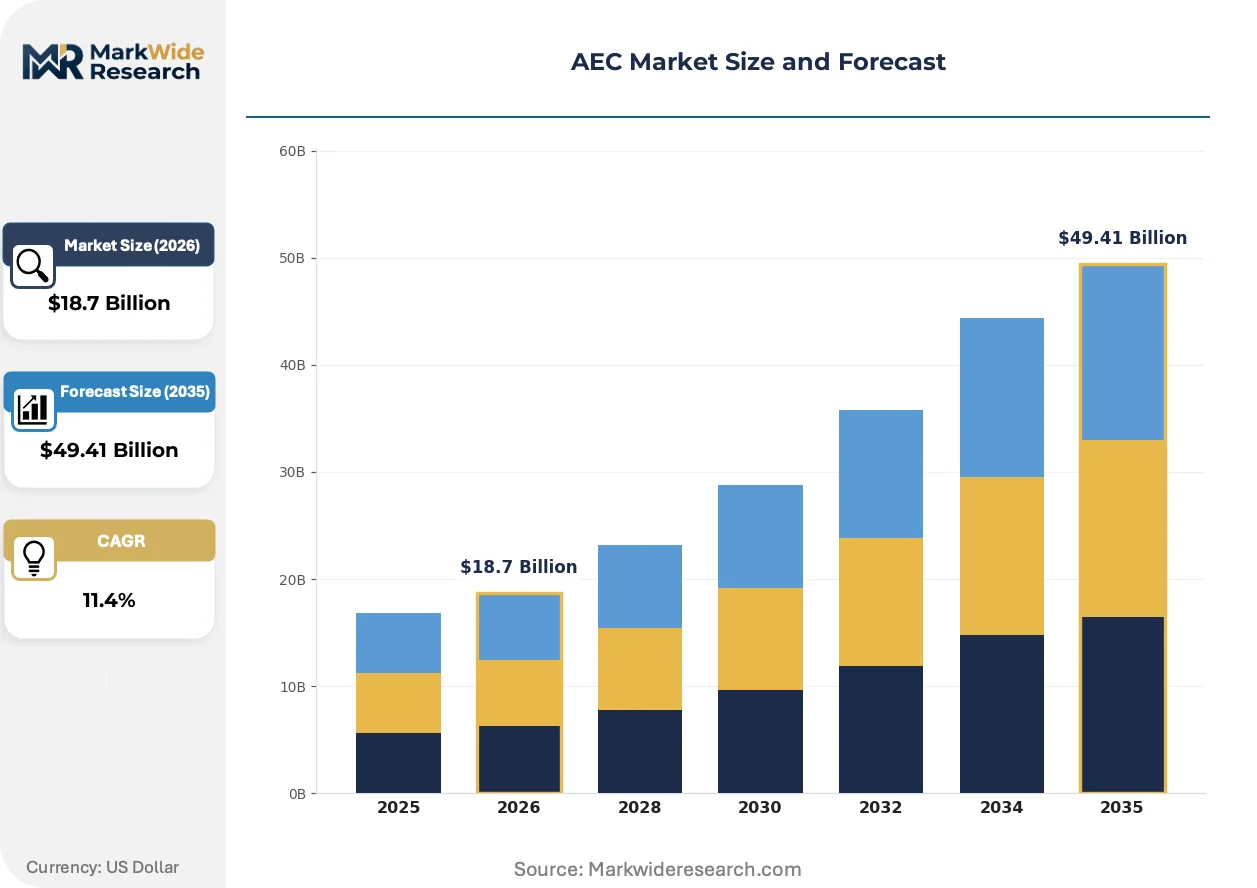
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Design, Construction, Project Management Application: Residential, Commercial, Infrastructure, Industrial Technology: BIM, CAD, Virtual Reality, Drones End User: Architects, Engineers, Contractors, Developers |
| Companies Covered | AECOM, Bechtel Corporation, Fluor Corporation, Vinci, Skanska, WSP Global, Jacobs Solutions, China State Construction Engineering Corporation, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AEC Market Emerging Trajectories
Digital fabrication workflows and generative design algorithms are compressing traditional design-review cycles while embedding performance optimization earlier in project development. Three distinct forces are restructuring competitive capability requirements.
Generative design software is miniaturizing the role of human iteration in structural optimization. Engineering consultancies in Germany and the Netherlands deploy these tools to evaluate thousands of design permutations against carbon and cost constraints. The technology is compressing schematic design phases from months to weeks while elevating parametric modeling skills above traditional drafting competency.
The EU AI Act's risk-classification framework for automated decision-making systems now governs construction robotics and AI-enabled safety monitoring deployed on European job sites. Contractors must document algorithmic transparency and human oversight protocols for machinery operating in high-risk environments. German and French infrastructure projects are requiring AI conformity assessments as pre-qualification criteria.
Asset owners in the United Arab Emirates and Saudi Arabia now mandate openBIM deliverables with COBie data drops at defined project milestones. This specification shift forces design firms to restructure compensation around information deliverables rather than drawing packages. Engineering consultancies are unbundling traditional design services from digital asset management to capture recurring facility data revenue.
AEC Market Segmentation
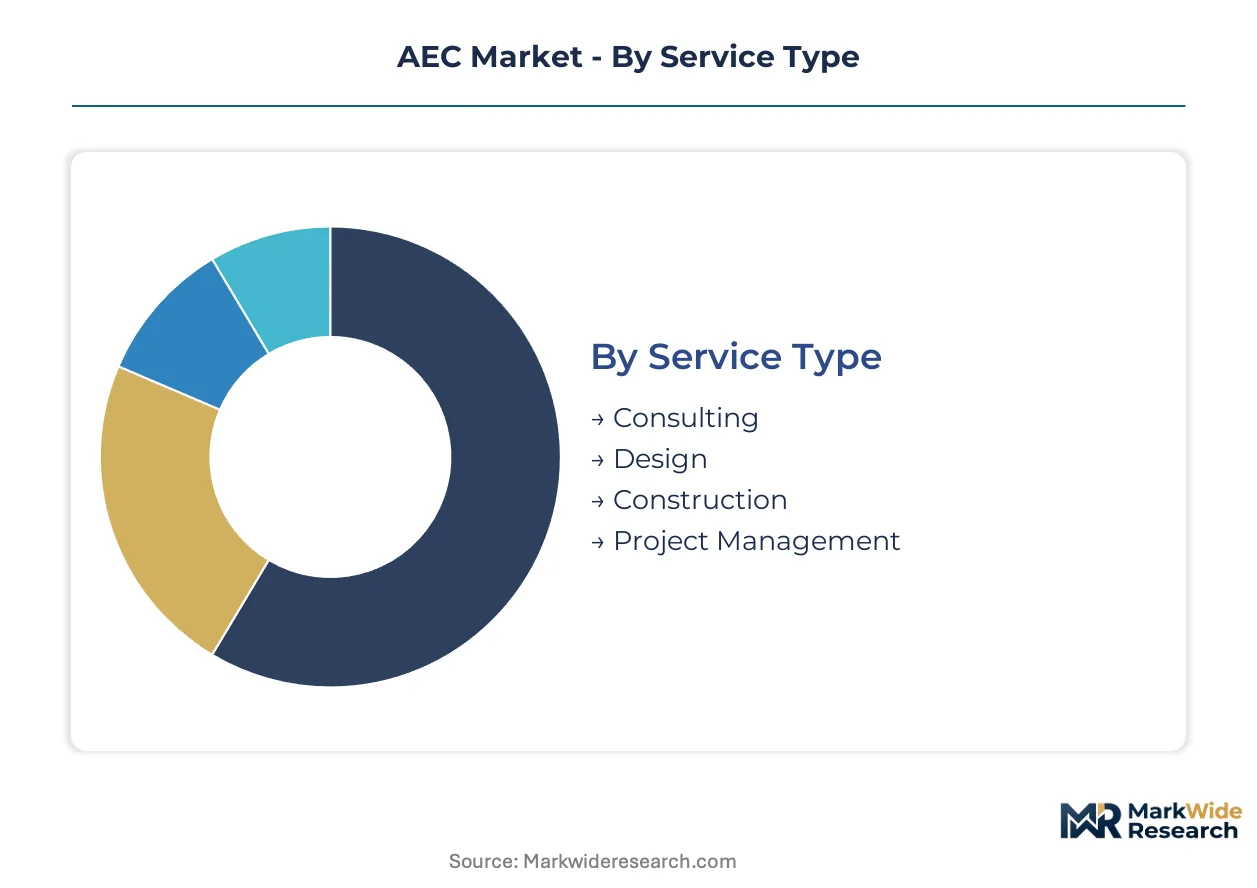
Segmentation in the AEC market reveals how procurement workflows, regulatory mandates, and technology adoption cluster differently across service delivery modes and stakeholder types. Understanding these divisions exposes where margin pools concentrate and where digitization investments yield competitive separation.
Service Type:
Service type determines contract structure, bonding requirements, and the degree of fixed-cost exposure that shapes channel economics and risk allocation.
- Construction:Fixed-price contracting with surety bonding dominates this segment, absorbing the largest revenue pool due to material procurement scale and labor mobilization intensity. Demand concentrates in Saudi Arabia's NEOM and Red Sea giga-projects where sovereign wealth funding enables lump-sum turnkey awards.
- Design:Fee-based professional services governed by ISO 19650 information management standards, occupying higher-margin positions where specialized technical expertise limits competitive entry. German and Dutch engineering consultancies deploy generative design tools to compress schematic phases from months to weeks.
- Consulting:Advisory services spanning feasibility, carbon accounting, and regulatory compliance, expanding under EU CSRD-aligned embodied carbon disclosure mandates.
- Project Management:Owner-representative oversight and schedule-risk management, gaining traction as complex multi-stakeholder developments proliferate across the United Arab Emirates.
By volume, Construction leads. By growth pace, Design is ahead.
Application:
Application segments diverge sharply in regulatory exposure, with infrastructure and industrial projects facing stricter digital verification mandates than private commercial development.
- Infrastructure:Transit, energy, and municipal assets requiring federated digital twins for facility handover under UAE government mandates. Middle East sovereign wealth funds digitize procurement workflows across this segment.
- Industrial:Complex energy and manufacturing facilities where Bechtel Corporation anchors margins through self-perform construction capability and operational technology integration.
- Commercial:Office, retail, and hospitality developments facing EU Green Deal embodied carbon disclosure requirements that compress project timelines.
- Residential:Single and multi-family construction with lighter regulatory burden but acute pressure from skilled labor scarcity in high-growth Gulf markets.
Infrastructure commands the largest project scale. Industrial exhibits the steepest expansion trajectory as operational technology convergence accelerates.
Technology:
Technology segments stratify by maturity curve, with established platforms defending installed bases while emerging tools reshape competency requirements.
- BIM:Federated digital twin platforms mandated for facility handover on UAE government-backed megaprojects, representing the fastest-expanding segment as owners unbundle information deliverables from drawing packages.
- CAD:Traditional drafting and documentation tools facing compression as generative design automates routine tasks, though remaining entrenched in legacy project workflows.
- Virtual Reality:Immersive design review and stakeholder visualization, deployed by European consultancies to accelerate client decision cycles.
- Drones:Aerial surveying and construction progress monitoring, governed by EU AI Act risk-classification frameworks when coupled with automated analytics.
CAD retains the deepest installed base. BIM is climbing the fastest as openBIM deliverables with COBie data drops become standard.
End User:
End user categories reflect distinct procurement authority patterns and technical sophistication levels that shape vendor engagement strategies.
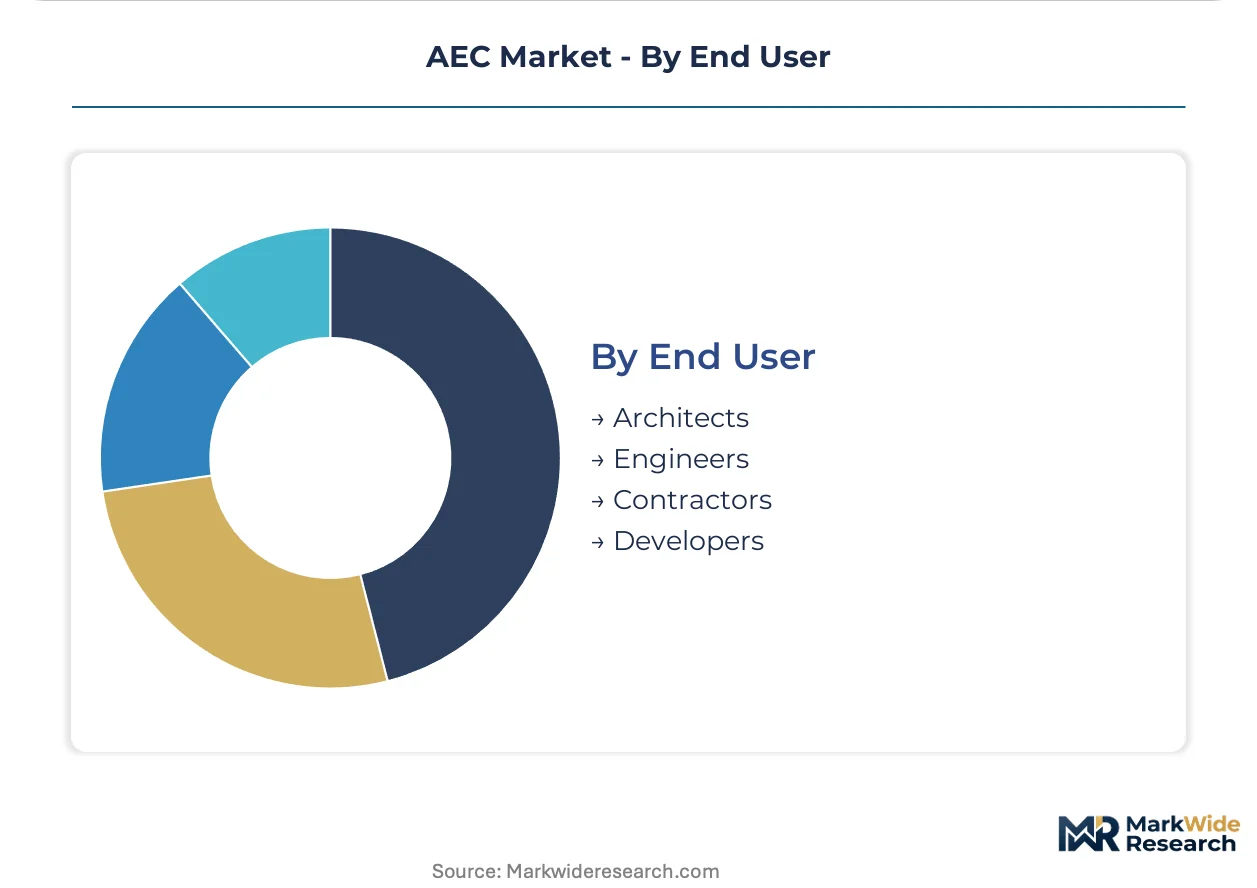
- Contractors:Asset-heavy builders managing fixed-cost exposure and bonding requirements, with tier-one firms integrating digital delivery platforms to differentiate on complex industrial awards.
- Engineers:Technical specialists in structural, MEP, and geotechnical disciplines where Jacobs Solutions sustains R&D intensity in design-operational technology convergence.
- Architects:Design authorities increasingly compensated around information deliverables rather than drawing packages as Saudi and UAE owners mandate openBIM specifications.
- Developers:Capital sponsors driving procurement decisions on giga-project pipelines, prioritizing integrated design-build-digital delivery to compress time-to-revenue.
Contractors represent the largest addressable spend. Developers are gaining share fastest as sovereign wealth direct investment reshapes procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Middle Eastern sovereign wealth corridors while European markets absorb compliance cost premiums. German engineering consultancies command margin premiums on carbon-verified deliverables. UAE-based contractors capture volume through lump-sum giga-project awards.
United States
Industrial energy retrofits and data center construction drive demand across Texas and Virginia corridors. The EPA and OSHA frameworks govern site remediation protocols and worker safety standards that compress project sequencing. Houston anchors self-perform construction capability for complex petrochemical facilities.
Germany
Transit infrastructure decarbonization and railway modernization absorb engineering capacity across the Rhine-Ruhr and Bavarian clusters. The EU Green Deal and F-Gas Regulation mandate embodied carbon disclosure and low-GWP material selection. Stuttgart engineering consultancies deploy generative design tools for parametric structural optimization.
China
Urban rail transit expansion and smart city districts absorb construction volume across the Yangtze River Delta. MIIT and GB standards enforce domestic digital construction mandates that restrict platform access without localized certification. Shenzhen clusters concentrate BIM platform development for state-backed megaprojects.
United Arab Emirates
Sovereign wealth-funded developments digitize procurement workflows across transit, energy, and municipal assets. Government mandates now require federated digital twins for facility handover on megaprojects. Dubai concentrates design-build-digital integration for Expo legacy districts and port modernization.
Saudi Arabia
NEOM and Red Sea giga-projects represent underpenetrated demand for integrated design-build-digital delivery. MOHAP and municipal authorities enforce progressive building codes that accelerate BIM adoption. Riyadh anchors procurement authority for linear infrastructure and entertainment district developments.
AEC Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the AEC landscape. The market structure separates asset-heavy contractors with bonding capacity from lean engineering specialists with digital delivery platforms. Three archetypes dominate: integrated design-build operators, engineering-led consultancies, and sovereign-backed construction conglomerates. Competitive moves concentrate on operational technology convergence and strategic partnerships for digital twin deployment.
Among North American integrated operators, Bechtel Corporation and Fluor Corporation exemplify self-perform construction capability anchored to complex industrial and energy project awards. WSP Global occupies a position within the engineering consultancy tier, differentiated through transit and environmental infrastructure specialization across European and North American markets. These three represent divergent capability configurations rather than direct segment overlap.
| Leading Market Players |
|---|
| AECOM |
| Bechtel Corporation |
| Fluor Corporation |
| Vinci |
| Skanska |
| WSP Global |
| Jacobs Solutions |
| China State Construction Engineering Corporation |
| Larsen & Toubro |
| Others |
Supply Flow & Price Mechanics
Generative design software substitution for traditional drafting labor is compressing fee structures in European consultancies while expanding procurement geography toward Indian engineering centers. This dual shift simultaneously deflates schematic-phase pricing in Germany and the Netherlands and elevates value capture for firms controlling parametric modeling IP.
Pricing Analysis
The customization-premium spread separates configured-to-order BIM deliverables from standardized CAD documentation. Project-based fee structures dominate, with price differentiation driven by ISO 19650 certification tier and after-sales digital twin maintenance bundling. Cost compression in standard documentation tiers is intensifying because generative design tools automate routine quantity surveying. Mid-tier contractors exhibit highest price sensitivity due to bonding cost escalation, while sovereign wealth-backed developers show lowest sensitivity on giga-project awards.
Supply Chain Analysis
Inbound logistics costs through Jebel Ali port congestion and Red Sea container availability constrain material procurement timelines for UAE-based contractors. Geographic supply concentration centers on China for steel and MEP components, Germany for engineering software licensing, and India for structural steel detailing labor. Raw material dependencies include structural steel, concrete admixtures, and low-GWP refrigerants under F-Gas Regulation. Single-source vulnerability in BIM platform licensing creates supply chain risk. Distribution runs through lump-sum turnkey contracts with sovereign wealth direct awards.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AEC market sits in early-cycle expansion as EU Green Deal mandates force design-stage digital verification adoption ahead of compliance deadlines.
For Market Incumbents: Shield proprietary digital delivery platforms through deeper backward integration into IoT sensor networks for operational technology convergence. Fortify bonding capacity relationships as mid-tier contractor failures create acquisition opportunities. The priority lever rests on federated digital twin IP that locks in recurring facility data revenue streams. For New Entrants and Emerging Players: Carbon accounting advisory services represent an under-served layer where incumbents lack CSRD-aligned embodied carbon verification capability. Target Saudi Arabia's NEOM and Red Sea developments as the most penetrable geography with sovereign wealth funding enabling new vendor qualification. Pursue a go-to-market angle anchored to openBIM deliverable restructuring that unbundles information management from traditional design fees. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors engineering-led consultancies with generative design competency over asset-heavy contractors facing fixed-cost exposure. Long-term viability hinges on recurring revenue from digital twin maintenance rather than one-time construction awards. The acquisition target archetype is mid-tier European engineering firms with ISO 19650 certification depth. Watch BIM platform interoperability standardization as the inflection signal that determines winner-take-most dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Merges BIM with IoT sensor networks to capture recurring facility management revenue from UAE sovereign wealth assets. |
| Backward Integration into Generative Design | Captures parametric modeling IP that compresses schematic phases from months to weeks for German transit infrastructure. |
| CSRD-Aligned Carbon Accounting Service Launch | Addresses EU Green Deal embodied carbon disclosure mandates that compress commercial development timelines. |
| Strategic Partnership for openBIM Certification | Secures vendor qualification on Saudi giga-projects mandating COBie data drops at defined milestones. |
| Acquisition of MEP Systems Specialist | Resolves acute talent scarcity in high-growth Gulf markets while adding technical expertise barriers to entry. |
Methodological Framework
Cross-validation between primary interviews with EPC contractors and secondary validation through municipal procurement databases anchors the qualitative findings. Construction directors, BIM platform engineers, sovereign wealth fund procurement officers, and geotechnical specialists provided operational perspectives. Secondary sources include ISO 19650 implementation filings, EU Green Deal regulatory texts, SEC 10-K disclosures from listed engineering firms, and UAE government tender portals. Bottom-up project pipeline aggregation and top-down macroeconomic factor weighting complete the triangulation.
Sensitivity analysis across multiple demand scenarios tests forecast robustness. The analytical framework segments by service type, application, technology, and end user across the projection horizon. CAGRs derive from regression against historical BIM adoption curves and sovereign wealth capital deployment patterns. Industry-specific inputs include smart city infrastructure program budgets and F-Gas Regulation compliance cost estimates.
Underlying assumptions cover continued sovereign wealth funding commitment and EU regulatory enforcement timelines, with deviation risk concentrated in Chinese platform access restrictions and geotechnical labor migration patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Signage Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
Collapsible Gates Market