
 Engraver Machine Market | 2026-2036
Engraver Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Engraver Machine Market Foresight
Fiber laser integration with automated material handling is narrowing the performance gap between benchtop and industrial engraving systems. Trumpf leverages its photonics heritage to sustain leadership in high-wattage fiber platforms for metal marking. Gravotech anchors the European personalization segment through specialized rotary and laser configurations for signage and awards. Han's Laser dominates China's domestic supply chain, controlling cost-engineered CO2 and fiber systems for electronics and packaging applications.
An engraver machine is a precision material removal device that employs laser beams, rotating cutters, or chemical processes to incise permanent markings, text, or graphics onto substrates ranging from metals and plastics to wood and glass, with fiber laser systems typically operating at 1064 nm wavelength and power densities exceeding 10^6 W/cm² for industrial throughput. Laser engravers command the largest installed base due to speed and repeatability, while rotary engravers retain margin pools in deep-cut metal applications where thermal distortion must be avoided. UV laser technology is displacing CO2 systems in electronics micromarking, as shorter wavelengths enable damage-free processing of sensitive polymers and ceramics.
The US Occupational Safety and Health Administration enforces laser safety standards under 21 CFR 1040 that classify engraving equipment by hazard level, directly influencing enclosure design and interlock requirements for domestic manufacturers. The European Union's REACH regulation restricts hexavalent chromium in chemical etching baths, compelling gravure shops to adopt laser-based alternatives or closed-loop processing. China's Standardization Administration maintains GB laser equipment standards that align with IEC 60825 for export certification. Stakeholders must monitor evolving RoHS substance restrictions and fiber source efficiency benchmarks to preserve market access and cost competitiveness.
Market Dynamics
Fiber laser systems are digitizing production workflows across contract manufacturing clusters, compressing setup times from hours to minutes while REACH compliance redirects European investment away from chemical etching infrastructure.
Growth Catalysts
- REACH chemical restrictions:European gravure shops face mandatory phase-out of hexavalent chromium baths, accelerating capital redeployment into mechanical and laser engraving platforms.
- Jewelry manufacturing clusters:India's Surat and Thailand's Bangkok drive fiber laser adoption for precision gold and platinum marking, replacing manual rotary methods.
- UV wavelength technology:355 nm solid-state sources enable damage-free micromarking of ceramic substrates and sensitive polymers for electronics packaging.
Market Restraints
- Fiber source supply concentration:High-power pump diodes and rare-earth doped fibers concentrate among German and Japanese component suppliers, creating input vulnerability.
- Technical limitation in deep metal cutting:Thermal distortion thresholds prevent fiber lasers from displacing mechanical rotary engravers in mold and die applications exceeding 2 mm depth.
- Substitution threat from direct part marking:Pin marking and dot peen systems compete on capital cost for low-aesthetics industrial traceability applications.
Strategic Opportunities
- Underpenetrated Vietnamese electronics:Contract manufacturers in Bac Ninh province lack localized laser marking service infrastructure, creating equipment and service white space.
- Regulatory tailwind from EU CSRD:Corporate sustainability reporting mandates push brands toward permanent laser marking for supply chain traceability and circular economy compliance.
- Technology convergence of vision and motion:Integrated machine vision with real-time galvo correction enables on-the-fly marking of moving parts, opening continuous production line applications.
Industry Challenges
- Laser safety engineering talent gap:IEC 60825 compliance documentation and interlock system design require specialized photonics safety expertise that machine builders struggle to recruit.
- Capex intensity of automation integration:Robotic material handling and conveyor systems for high-throughput fiber platforms demand additional capital equal to 40-60 percent of base laser system cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engraver Machine Market |
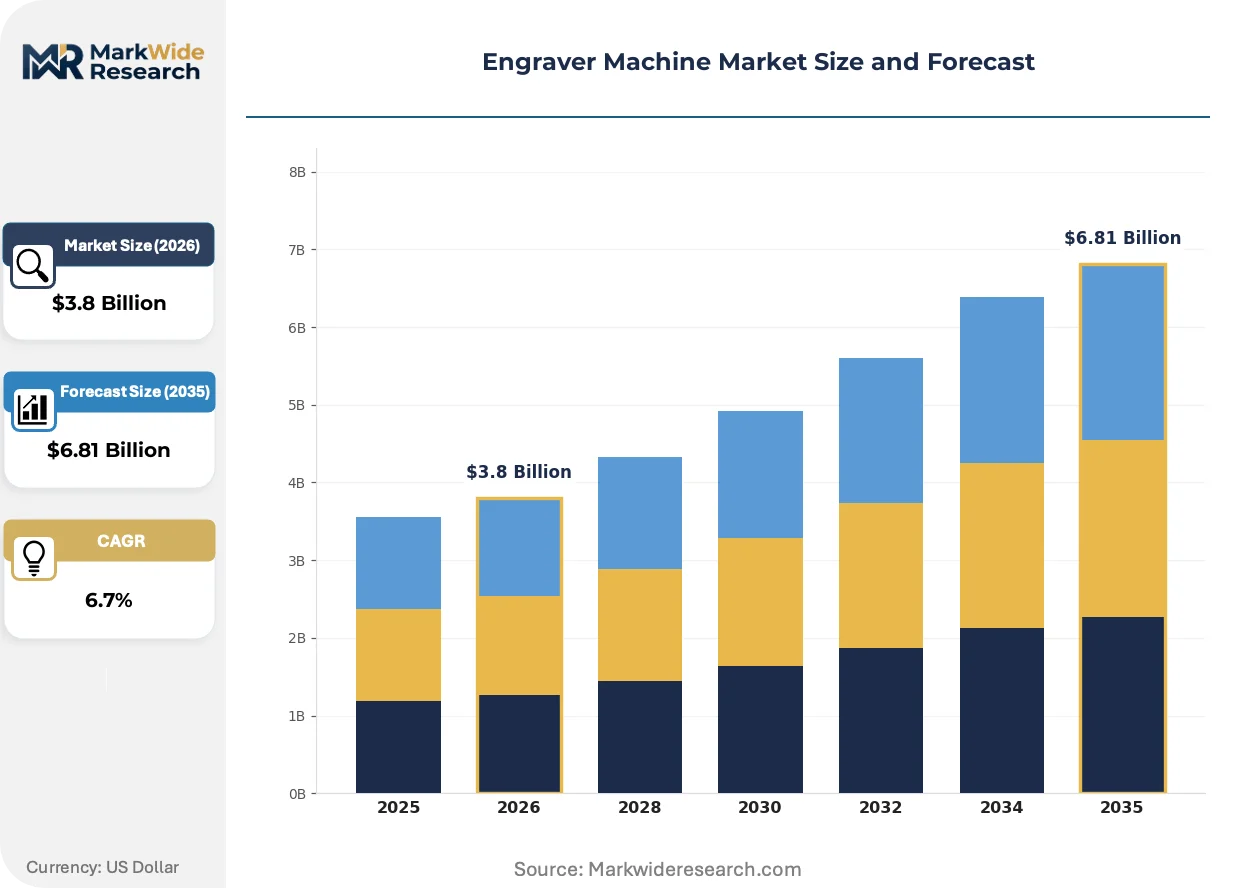
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Engravers, Rotary Engravers, Chemical Etchers, Mechanical Engravers Technology: Fiber Laser, CO2 Laser, UV Laser, Diode Laser End User: Manufacturers, Artists, Jewelers, Educational Institutions Application: Signage, Personalization, Industrial Marking, Awards and Trophies |
| Companies Covered | Trotec Laser, Universal Laser Systems, Trumpf, Blue Elephant CNC, Gravotech, Coherent, Epilog Laser, GCC, Han's Laser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engraver Machine Market Shifts & Advancements
Digital workflow integration is compressing the traditional separation between design software and production equipment, enabling real-time pattern adjustment without mechanical retooling. Three developments are reshaping competitive positioning.
Galvo-controlled fiber lasers with embedded FPGA controllers are digitizing beam path programming, eliminating mechanical fixture dependencies. Electronics contract manufacturers in Guangdong province adopt these systems for same-day prototype-to-production transitions. The technology is digitizing job shop economics by collapsing setup labor from skilled technician hours to automated file transfers.
REACH Annex XVII restrictions on chromium trioxide are forcing gravure operations across Germany and France into laser conversion or closed-loop chemical recovery investments. Metal decorating and packaging print cylinders represent the most affected equipment category, with Heidelberg and other gravure press operators accelerating fiber platform trials to preserve EU market access.
After-sales service unbundling is fragmenting traditional OEM revenue models. Independent laser source refurbishers and third-party galvo repair specialists in Shenzhen and Dallas now capture maintenance spend that previously flowed to original equipment manufacturers. Electronics packaging buyers in Malaysia and Mexico increasingly source consumables and spare optics through distributor channels rather than factory-direct contracts.
Engraver Machine Market Segmentation
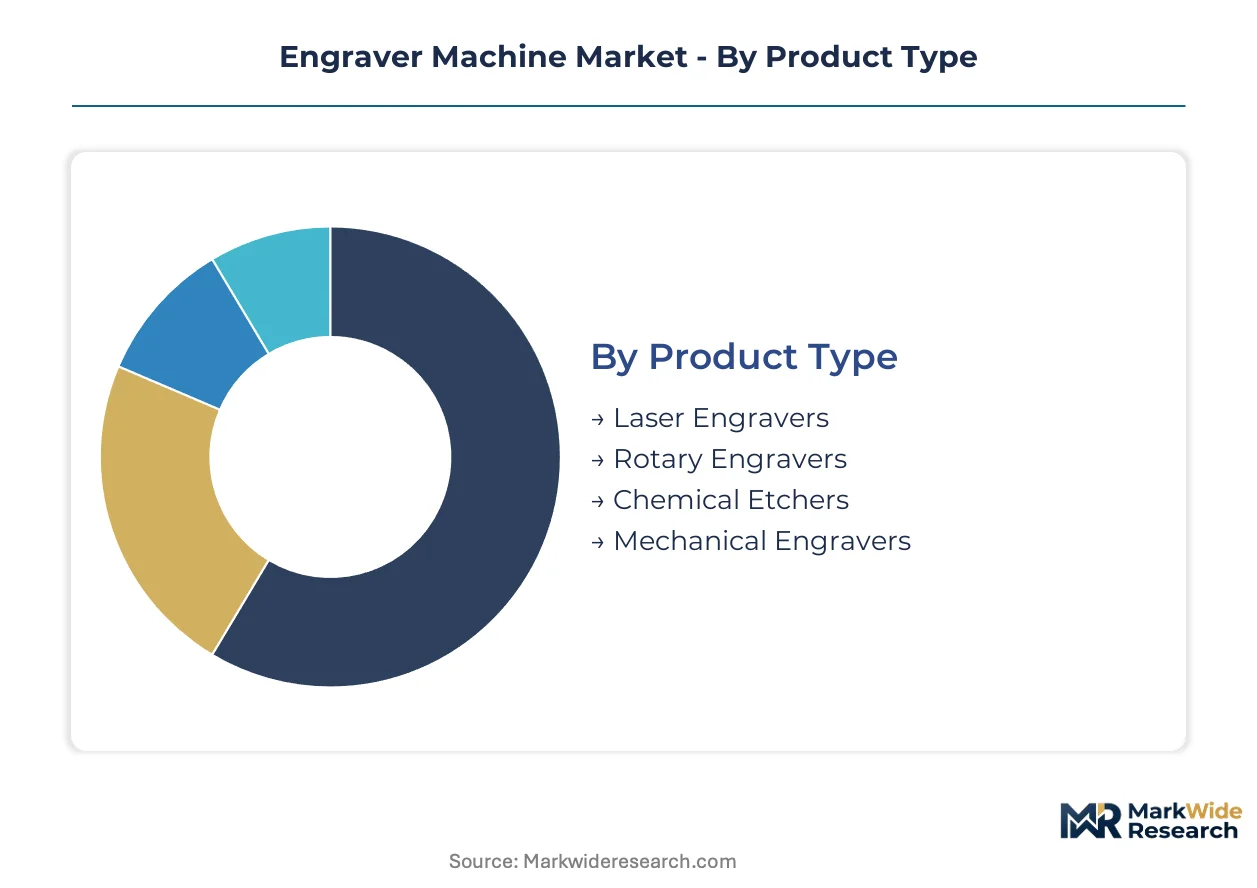
Segmentation in the engraver machine market reveals how technology choices cascade through end-use economics. Product type and laser source decisions determine capital intensity, operating cost structure, and regulatory exposure across diverging customer workflows.
Product Type:
Laser engravers span benchtop units to industrial fiber platforms, while mechanical and chemical alternatives retain defensible niches where thermal or environmental constraints apply.
- Laser Engravers:Fiber and CO2 sources dominate this category, with galvo-steered beams achieving marking speeds exceeding 700 characters per second on metal substrates. Electronics contract manufacturers in China's Guangdong province drive fiber laser demand for PCB serialization and component traceability, though high-power pump diode supply concentration among German and Japanese vendors creates input vulnerability.
- Rotary Engravers:Diamond-tipped cutters and spindles execute deep material removal without thermal distortion, preserving dimensional accuracy in mold and die applications. European gravure shops facing REACH Annex XVII chromium trioxide restrictions are redeploying capital toward mechanical platforms as chemical etching becomes non-viable.
- Chemical Etchers:Acid-based processes using ferric chloride or cupric chloride solutions persist in PCB fabrication and decorative metal finishing where laser capital costs prove prohibitive.
- Mechanical Engravers:Pantograph and CNC routing systems serve woodworkers and stone carvers requiring tactile depth control unavailable from laser ablation.
The dominant share belongs to Laser Engravers, while Rotary Engravers is closing the gap fastest as European regulatory pressure accelerates chemical-to-mechanical conversion.
Technology:
Source wavelength and power architecture segment customers by material compatibility and throughput requirements, with fiber platforms commanding premium positioning in metal-marking applications.
- Fiber Laser:Ytterbium-doped fiber amplifiers at 1064 nm wavelength deliver power densities exceeding 10^6 W/cm² for industrial metal marking throughput. India's Surat jewelry cluster and Thailand's Bangkok manufacturing district are displacing manual rotary methods with fiber systems for precision gold and platinum inscription.
- CO2 Laser:Gas-discharge tubes emitting at 10.6 µm wavelength excel in organic material processing—wood, acrylic, leather—where fiber sources prove ineffective. Packaging converters in Vietnam's Bac Ninh province deploy CO2 systems for date coding and lot marking on corrugated and flexible films.
- UV Laser:Frequency-tripled solid-state sources at 355 nm enable cold ablation of ceramics and sensitive polymers without thermal damage. Electronics micromarking applications are climbing the fastest as shorter wavelengths penetrate ceramic substrates and thermally sensitive polymers for semiconductor packaging.
- Diode Laser:Direct-emitting semiconductor bars at 808-980 nm offer lowest capital entry point for hobbyist and educational markets, though beam quality limitations restrict industrial adoption.
Fiber Laser holds the installed base leadership, though UV Laser is expanding most quickly in electronics micromarking where thermal damage thresholds constrain legacy alternatives.
End User:
Customer sophistication and batch size requirements fragment demand across industrial, artisanal, and institutional buyer archetypes with diverging service and financing expectations.
- Manufacturers:Electronics, automotive, and medical device producers mandate ISO-compliant traceability marking with machine-readable codes. Contract manufacturers in Malaysia and Mexico increasingly source consumables through distributor channels rather than factory-direct contracts, fragmenting traditional OEM revenue models.
- Artists:Studio practitioners prioritize software workflow integration and material versatility over raw throughput, driving demand for hybrid CO2-fiber platforms with rotary attachment compatibility.
- Jewelers:Precision metal marking requirements in India's Surat and Thailand's Bangkok clusters favor fiber lasers for karat stamping and custom design inscription.
- Educational Institutions:Vocational training centers and university maker spaces constitute price-sensitive demand for entry-level diode and CO2 systems with enclosed safety interlocks compliant with OSHA 21 CFR 1040.
Manufacturers command the revenue concentration, yet Jewelers are gaining share fastest as Asian precious metals processing clusters automate precision marking workflows.
Application:
End-use purpose determines marking depth, durability, and aesthetic requirements, with industrial traceability applications imposing the most stringent technical specifications.
- Signage:Architectural and wayfinding applications combine rotary depth cutting for tactile braille compliance with laser surface marking for high-contrast graphics. Gravotech's European positioning leverages specialized rotary-laser configurations for this segment.
- Personalization:Consumer goods customization—mobile devices, drinkware, accessories—demands rapid job changeover and design-on-demand capabilities. After-sales service unbundling is fragmenting OEM revenue as independent refurbishers in Shenzhen and Dallas capture maintenance spend.
- Industrial Marking:Component serialization, date coding, and compliance labeling require permanent, machine-readable marks resistant to harsh environments. EU CSRD corporate sustainability reporting mandates are pushing brands toward laser marking for supply chain traceability and circular economy compliance.
- Awards and Trophies:Recognition products combine rotary engraving for deep-cut metal plates with laser marking for acrylic and glass elements, serving recognition programs and corporate incentive markets.
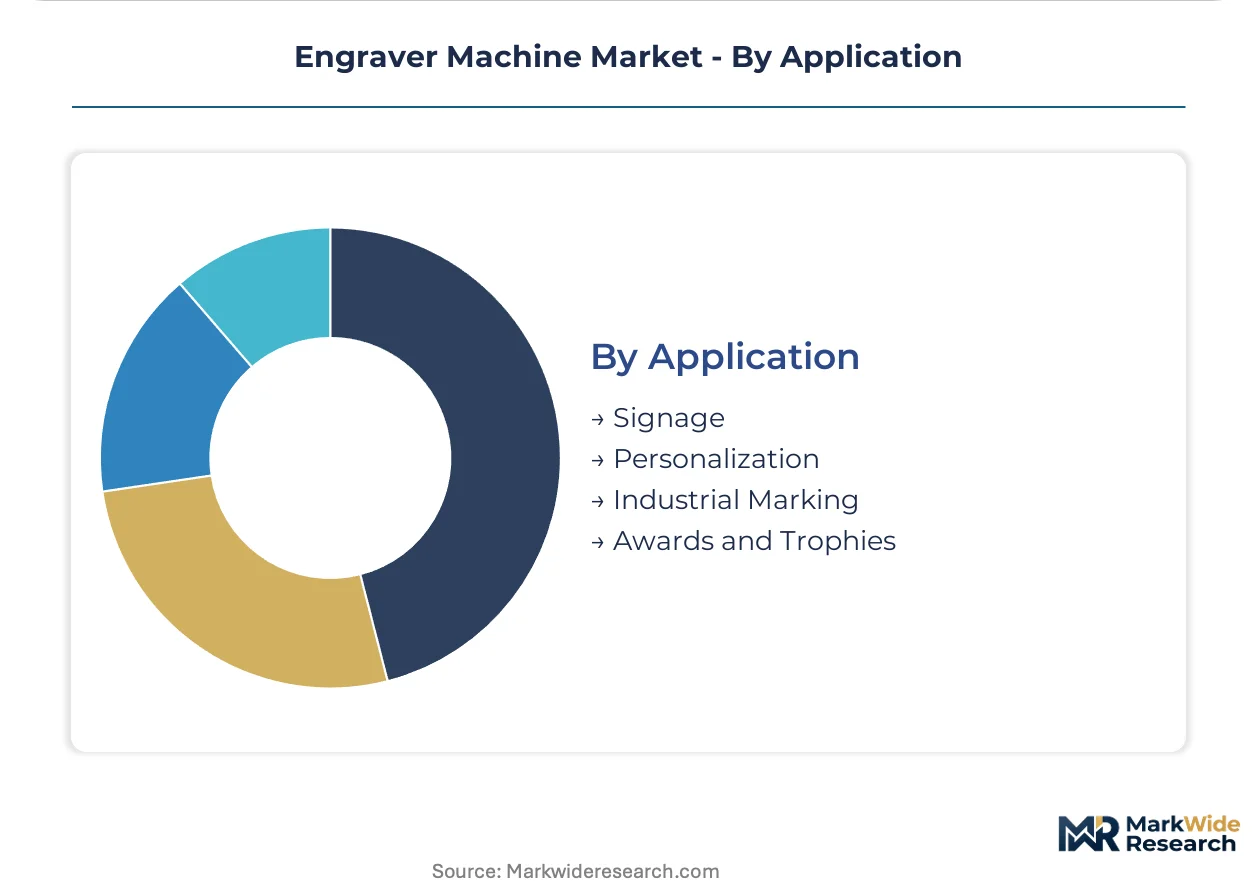
Industrial Marking generates the volume concentration, while Personalization is climbing fastest as digital workflow integration collapses setup times from hours to minutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics contract manufacturers and jewelry processing clusters concentrate equipment procurement across four distinct national markets, each shaped by divergent regulatory exposure and supply chain positioning.
China
Guangdong province hosts the world's densest concentration of electronics contract manufacturing, driving fiber laser demand for PCB serialization and component traceability. China's Standardization Administration maintains GB laser equipment standards aligned with IEC 60825 for export certification. Shenzhen's independent galvo repair specialists and laser source refurbishers now capture aftermarket spend that previously flowed to original equipment manufacturers.
Germany
Gravure press operators and metal decorating shops face REACH Annex XVII restrictions on chromium trioxide, forcing capital redeployment into laser and mechanical alternatives. ECHA enforcement timelines are compressing investment decisions across Heidelberg's industrial print corridor. Bavaria's precision engineering clusters supply high-power pump diodes and rare-earth doped fibers that concentrate among German component vendors.
United States
OSHA enforces laser safety standards under 21 CFR 1040 that classify engraving equipment by hazard level, directly influencing enclosure design and interlock requirements for domestic manufacturers. Dallas-based third-party galvo repair specialists fragment traditional OEM revenue models through after-sales service unbundling. Electronics packaging buyers in Mexico increasingly source consumables through cross-border distributor channels rather than factory-direct contracts.
India
Surat's diamond and jewelry processing cluster displaces manual rotary methods with fiber laser systems for precision gold and platinum karat stamping. BIS certification requirements for industrial laser equipment create compliance barriers for imported systems. Mumbai's precious metals finishing houses automate precision marking workflows as labor costs rise in traditional artisanal methods.
Thailand
Bangkok's manufacturing district drives fiber laser adoption for custom design inscription in platinum and gold jewelry exports to European luxury brands. The country's national industrial standards regulator aligns laser safety protocols with IEC frameworks to preserve market access. Contract manufacturers in Eastern Economic Corridor zones lack localized UV laser micromarking infrastructure for electronics packaging applications.
Engraver Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure concentrates around German photonics heritage, Chinese cost engineering, and European personalization expertise. Strategic archetypes include high-wattage fiber platform specialists, rotary-laser hybrid configurators, and independent aftermarket service providers. Dominant competitive moves encompass vertical integration into pump diode supply and geographic expansion through distributor channel capture.
Within the photonics heritage tier, Trumpf and Coherent exemplify high-power fiber platform positioning anchored by component-level control. Among Asia-Pacific cost-engineered fabricators, Han's Laser occupies a position representing domestic supply chain dominance for CO2 and fiber systems. On the European personalization vector, Gravotech and Trotec Laser sit within specialized rotary and laser configurations for signage, awards, and architectural applications. Epilog Laser and Universal Laser Systems represent the mid-market benchtop segment where software workflow integration determines competitive differentiation.
| Leading Market Players |
|---|
| Trotec Laser |
| Universal Laser Systems |
| Trumpf |
| Blue Elephant CNC |
| Gravotech |
| Coherent |
| Epilog Laser |
| GCC |
| Han's Laser |
| Others |
Supply & Pricing Matrix
German and Japanese suppliers of high-power pump diodes and rare-earth doped fibers anchor upstream concentration, allowing these component vendors to extract margin while downstream OEMs compete on system integration and service bundling. This supply asymmetry pushes pricing power toward the fiber source tier and forces engraving equipment manufacturers to differentiate through software workflow integration and aftermarket service capture.
Pricing Analysis
Cost-plus contracts with pump diode indexation dominate fiber laser system procurement, with pricing stratifying across premium, standard, and economy tiers based on wattage output and automation integration depth. ISO 11553 safety certification and IEC 60825 compliance documentation create measurable price premiums for export-qualified systems. Cost compression in benchtop CO2 segments is intensifying because Chinese domestic suppliers are flooding educational and hobbyist channels with unbundled diode platforms. Educational institutions exhibit the highest price sensitivity, while electronics contract manufacturers in Guangdong province prioritize throughput reliability over capital cost minimization.
Supply Chain Analysis
Electronics contract manufacturers in China's Guangdong province, Germany's precision engineering clusters around Munich and Stuttgart, and Vietnam's emerging Bac Ninh electronics corridor concentrate downstream demand. Fiber laser system assembly draws from ytterbium-doped fiber amplifiers, galvo scanning heads, and FPGA motion controllers as critical inputs. Single-source vulnerability in high-power pump diode supply from German and Japanese vendors creates structural risk for fiber platform OEMs. Distribution runs through factory-direct contracts for large electronics packaging buyers and specialized industrial distributors serving jewelry and signage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engraver machine demand sits in early-cycle expansion as REACH chemical restrictions and CSRD traceability mandates trigger replacement investment across European gravure operations and global electronics supply chains.
For Market Incumbents: Build captive service networks as the primary moat against independent refurbishers in Shenzhen and Dallas who are fragmenting aftermarket revenue. Secure backward integration into galvo controller firmware development to differentiate motion precision from commodity fiber platforms. The threat of UV laser substitution for electronics micromarking demands accelerated R&D in 355 nm solid-state source integration. Channel control through distributor exclusivity agreements in Southeast Asian electronics corridors represents the critical defensive lever. For New Entrants and Emerging Players: Mid-market rotary-laser hybrid configurators for European signage and awards applications represent the most penetrable entry point, as Gravotech's specialized positioning leaves price-sensitive segments underserved. Vietnamese electronics contract manufacturers in Bac Ninh province lack localized UV laser micromarking infrastructure, creating equipment-plus-service white space. A go-to-market angle anchored by ISO 11553 compliance documentation and rapid spare optics availability can displace factory-direct incumbents in procurement decisions. For Investors and Strategic Acquirers: Capital is best deployed toward component-level specialists with captive pump diode or rare-earth fiber technology, as upstream supply concentration will persist across the analysis window. Acquisition targets should demonstrate installed base scale in jewelry or electronics verticals with recurring consumables attachment. The signal to watch is REACH enforcement acceleration in Germany and France, which would compress chemical-to-laser conversion timelines and revalue fiber platform manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Diode Supply | German and Japanese component concentration creates margin capture opportunity for OEMs with captive sourcing. |
| UV Laser Platform Launch | 355 nm solid-state sources enable penetration of electronics micromarking segments previously served by CO2 systems. |
| Aftermarket Service Network Expansion | Independent refurbishers in Shenzhen and Dallas threaten OEM revenue, demanding direct service channel buildout. |
| REACH Compliance Certification Investment | ECHA enforcement timelines accelerate gravure shop conversion, privileging suppliers with validated chemical-free platforms. |
| Southeast Asian Distributor Channel Capture | Vietnam and Thailand electronics clusters lack localized infrastructure, creating first-mover advantage for established brands. |
Research Methodology
The analysis maps fiber laser, CO2 laser, UV laser, and rotary engraving sub-sectors, each validated through plant engineers at electronics contract manufacturers, procurement leads at jewelry processing clusters, aftermarket service heads at distributor networks, and regulatory affairs specialists at OEMs. Primary interview findings were cross-referenced with customs and trade data for laser equipment imports, SEC filings for publicly listed photonics suppliers, IEC 60825 certification registries, and REACH Annex XVII enforcement notices. Bottom-up equipment shipment estimates and top-down end-use demand aggregation were triangulated to converge on market sizing.
Forecast assumptions held regulatory enforcement timelines and fiber source supply concentration fixed while varying electronics production migration patterns and jewelry automation penetration rates. The modeling framework projects demand across product type, laser source technology, end-user archetype, and application purpose dimensions, with regional splits calibrated to electronics manufacturing cluster concentration. CAGRs were derived from fitted adoption curves for fiber laser displacement of rotary methods in precious metals processing and UV laser penetration in semiconductor packaging.
Practitioners should monitor ECHA enforcement acceleration, pump diode supply disruptions from German or Japanese vendors, and electronics production relocation to Vietnam for early signals of forecast revision. Quarterly review of REACH compliance certification timelines and fiber source spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gouging Torch Market
Tools
Garden Digging Tools Market
Tools
Gas Cutting Machine Market
Tools
Reamer Market
Tools
Digital Laser Levels Market
Tools
Thickness Planers Market
Tools
Pneumatic Bolting Tools Market
Tools
Manual Cutting Equipment Market
Tools
Stationary Wood Planer Market
Tools
Woodworking Tools Market
Tools
Boring Tools Market
Tools
Power Nibbler Market
Tools
Lathe Machines Market
Tools
Pneumatic Tools Market
Tools
Jade Engraving Machines Market
Tools
Portable Tools Market