
 Signage Market | 2026-2036
Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Signage Market Outlook
The shift from single-source panel procurement to multi-source LED module sourcing is rebalancing supply chain risk across the signage industry. Samsung Electronics leverages captive semiconductor capacity to secure display driver ICs for high-brightness outdoor installations. Daktronics anchors its position through in-house engineering of sports-venue scoreboard systems. LG Electronics competes aggressively in transparent OLED signage for luxury retail environments.
Signage encompasses visual communication systems engineered from substrates, illumination sources, and electronic control modules to direct, inform, or advertise audiences in commercial and public spaces. Modern digital variants integrate pixel pitches below 1mm for close-viewing indoor applications and operate through networked content management platforms. LED Signs command the largest installed base due to lumen efficiency and durability in outdoor exposure, while Digital Displays capture premium margin pools through software-recurring revenue models. Wayfinding Signs benefit from transit authority modernization cycles, and the Plastic material segment faces displacement pressure from recycled aluminum frameworks in sustainability-sensitive bids.
The EPA enforces energy conservation standards affecting illuminated sign power draw, while FCC certification governs wireless content distribution in connected displays. CE marking under EU electromagnetic compatibility directives restricts market access for non-compliant imports. Stakeholders must monitor evolving e-waste recovery mandates and embedded carbon disclosure rules as procurement criteria harden across municipal and corporate buyers.
Market Dynamics
Retail chains are consolidating digital display procurement into centralized content management platforms, compressing vendor relationships from dozens per territory to single-source national contracts. This procurement compression is redistributing margin pools toward software-integrated hardware providers while squeezing pure-play substrate manufacturers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in illuminated sign cooling systems is accelerating LED retrofits across European commercial districts.
- Smart city infrastructure programs:Municipal transit authorities in the United States, China, and Germany are modernizing wayfinding networks with networked digital totems.
- Pixel pitch compression below 1mm:Fine-pitch LED modules are enabling close-viewing indoor applications in luxury retail and corporate lobbies previously served by LCD videowalls.
Market Restraints
- Display driver IC concentration:Taiwan and South Korea foundries control captive semiconductor capacity for high-brightness outdoor modules, creating supply vulnerability during fab loading cycles.
- Aluminum substrate cost volatility:Recycled aluminum frameworks face price pressure from energy-intensive smelting inputs, squeezing margin on sustainability-sensitive municipal bids.
- CE marking electromagnetic compatibility:Non-compliant imports from unregistered manufacturers face port-of-entry detention, fragmenting supply chain options for budget-tier distributors.
Strategic Opportunities
- Transparent OLED deployments:Luxury retail environments in Dubai, London, and Tokyo are adopting see-through displays for storefront product visualization without obscuring interior sightlines.
- Software-recurring revenue models:Cloud-based content management platforms are unbundling hardware sales from ongoing subscription services, capturing lifetime value from franchise networks.
- E-waste recovery mandates:Extended producer responsibility frameworks in California, France, and Japan are creating certified recycling partnerships as competitive differentiators.
Industry Challenges
- Embedded carbon disclosure compliance:Corporate procurement teams now require ISO 14040 lifecycle assessments for aluminum and semiconductor inputs, extending qualification timelines.
- Legacy fluorescent sign retrofit integration:Electrical contractors face skill gaps in networked control system programming when replacing neon tube installations with addressable LED arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Signage Market |
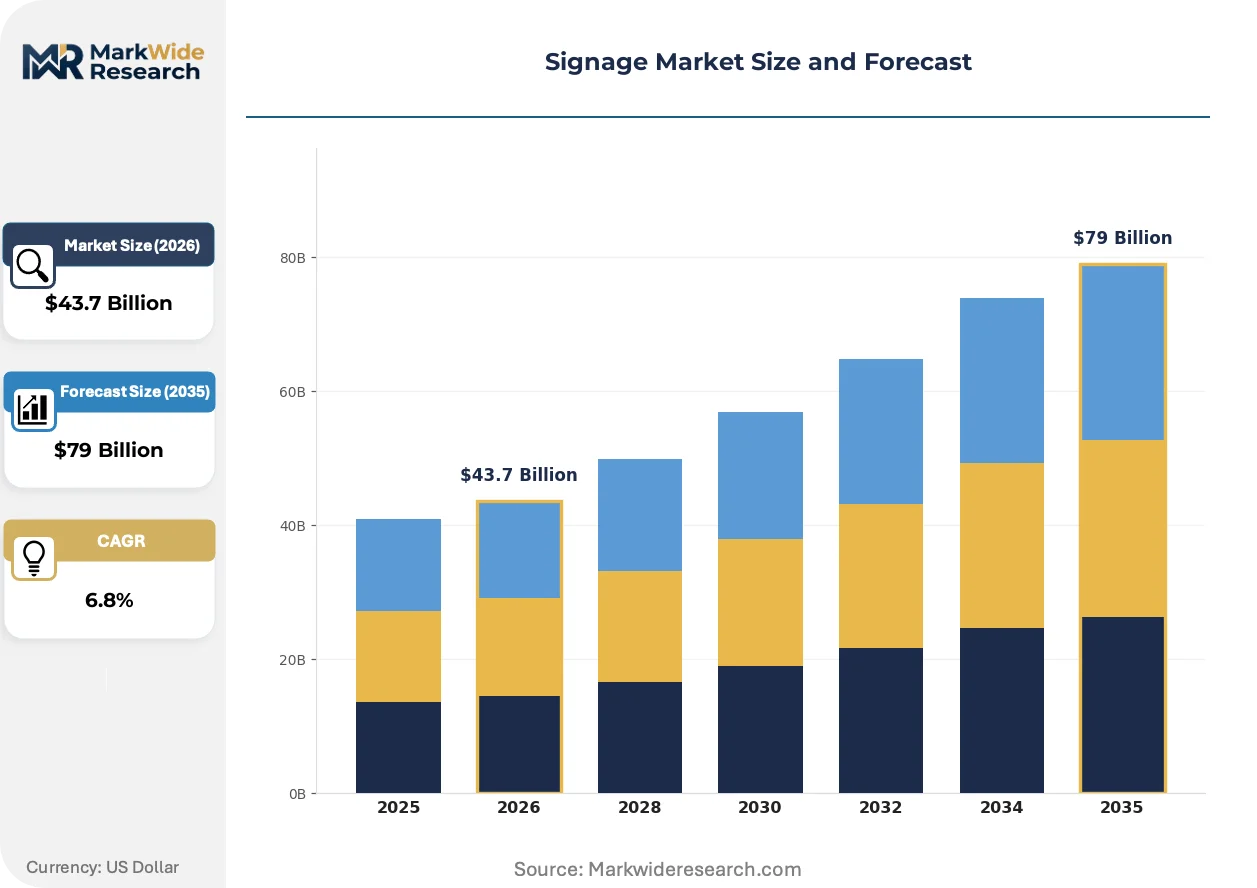
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Displays, Billboards, LED Signs, Wayfinding Signs End User: Retail, Transportation, Education, Healthcare Material: Wood, Metal, Plastic, Glass Installation Type: Indoor, Outdoor, Mounted, Freestanding |
| Companies Covered | Samsung Electronics, LG Electronics, NEC Display Solutions, Daktronics, Panasonic Corporation, Sharp Corporation, Planar Systems, Sony Corporation, Leyard Optoelectronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Signage Market Strategic Shifts
Networked content management platforms are collapsing the traditional separation between hardware installation and creative services. This convergence is redistributing value capture toward integrated solution providers while commoditizing standalone panel sales.
Edge-computing content players are decentralizing rendering workloads from centralized servers to local display nodes. Sports venues and transit hubs are adopting these distributed architectures to reduce latency for real-time data feeds. The shift is compressing infrastructure requirements for 4K playback while raising cybersecurity exposure at device endpoints.
EPA energy conservation standards are tightening maximum allowable power draw for illuminated exterior signs. The regulation is forcing manufacturers to redesign thermal management systems and driver efficiency circuits. Outdoor advertising operators in California and Texas are responding by accelerating LED retrofit schedules ahead of enforcement deadlines.
Subscription-based hardware-as-a-service contracts are displacing capital expenditure models among franchise retail chains. QSR networks and convenience store operators are adopting per-location monthly fees covering panels, installation, content management, and maintenance. The model is most visible in the United States, where tax treatment favors operating lease structures over depreciation schedules.
Signage Market Segmentation
Signage procurement decisions pivot on illumination technology, substrate durability, and content management integration. Buyers weight total cost of ownership against regulatory compliance timelines across municipal, retail, and institutional verticals.
Product Type:
Buyers prioritize pixel density, brightness calibration, and software ecosystem compatibility when selecting display hardware for specific viewing distances and ambient light conditions.
- Digital Displays:These integrate LCD, OLED, or micro-LED panels with networked content management platforms for real-time scheduling and remote monitoring. Demand concentrates in luxury retail flagship stores across Dubai, London, and Tokyo, where transparent OLED storefront installations command premium positioning without obstructing interior sightlines. Software-recurring revenue models attached to these deployments capture lifetime value from franchise networks.
- LED Signs:Modular LED arrays with pixel pitches ranging from 0.9mm for indoor close-viewing to 16mm for highway visibility dominate outdoor advertising and sports venue applications. Municipal transit authorities in the United States, China, and Germany are modernizing wayfinding networks with these systems to meet smart city infrastructure mandates.
- Billboards:Large-format static or digital structures positioned along high-traffic corridors for mass audience reach.
- Wayfinding Signs:Directional systems deployed in airports, hospitals, and transit hubs to guide pedestrian flow.
Volume sits with LED Signs; growth tilts toward Digital Displays.
End User:
Procurement scale and specification complexity vary sharply across verticals, with retail chains consolidating national contracts while transportation authorities navigate extended public tender cycles.
- Retail:Franchise networks and department stores deploy coordinated digital display fleets across storefronts and in-store networks. Centralized content management platforms compress vendor relationships from dozens per territory to single-source national agreements, redistributing margin pools toward software-integrated hardware providers.
- Transportation:Airports, rail terminals, and municipal transit authorities require ruggedized displays with 24/7 operational ratings and ADA-compliant wayfinding. EU F-Gas Regulation phasedown of hydrofluorocarbon refrigerants in illuminated sign cooling systems accelerates LED retrofits across European commercial districts serving these hubs.
- Education:K-12 districts and university campuses install digital signage for emergency notification, campus navigation, and event promotion.
- Healthcare:Hospitals and clinic networks deploy patient-facing displays for queue management, wayfinding, and health education content.
Transportation anchors procurement volume; retail drives specification innovation fastest.
Material:
Substrate selection balances structural integrity, weight constraints, and sustainability disclosure requirements increasingly embedded in municipal and corporate RFPs.
- Metal:Aluminum and steel frameworks provide structural stability for large-format outdoor installations exposed to wind load and thermal cycling. Recycled aluminum faces displacement pressure from energy-intensive smelting input costs, squeezing margins on sustainability-sensitive municipal bids requiring ISO 14040 lifecycle assessments.
- Plastic:Acrylic, polycarbonate, and PVC substrates offer lightweight fabrication for interior wayfinding and illuminated channel letters. EPA energy conservation standards tightening maximum allowable power draw for illuminated exterior signs are forcing manufacturers toward alternative thermal management materials.
- Wood:Sustainable timber and engineered wood products serve boutique retail and hospitality environments seeking warm aesthetic differentiation.
- Glass:Tempered and laminated glass panels enable premium transparent OLED mounting structures and protective display enclosures.
Metal dominates structural applications; plastic faces regulatory headwinds fastest.
Installation Type:
Environmental exposure ratings and mounting infrastructure requirements dictate thermal management design and service access protocols.
- Outdoor:Displays rated for IP65+ environmental sealing and 5,000+ nit brightness combat direct sunlight exposure and precipitation. FCC certification governs wireless content distribution in connected displays deployed across highway corridors and urban advertising networks.
- Indoor:Climate-controlled environments enable finer pixel pitches below 1mm for close-viewing corporate lobby and luxury retail applications previously served by LCD videowalls.
- Mounted:Wall-affixed and ceiling-suspended installations optimize floor space in congested retail and transit environments.
- Freestanding:Kiosks, totems, and monument structures provide flexible repositioning for temporary promotional campaigns and evolving wayfinding requirements.
Outdoor commands replacement cycle volume; indoor captures specification premium fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting capacity in China, semiconductor foundry output in Taiwan, and LED module assembly in South Korea anchor the upstream supply geography for signage manufacturing.
United States
Municipal transit authorities in New York, Chicago, and Los Angeles are modernizing wayfinding networks with networked digital totems. EPA energy conservation standards tightening maximum allowable power draw for illuminated exterior signs are accelerating LED retrofits across California and Texas ahead of enforcement deadlines. Dallas-Fort Worth anchors outdoor advertising replacement cycles for highway corridor billboards.
China
Smart city infrastructure programs in Beijing, Shanghai, and Shenzhen are driving procurement of fine-pitch LED modules for transit hubs and commercial districts. MIIT certification requirements for networked display equipment restrict market access for non-compliant imports. The Pearl River Delta concentrates module assembly capacity serving domestic and export demand.
Germany
Retail chains in Berlin, Munich, and Hamburg are consolidating digital display procurement into centralized content management platforms. EU F-Gas Regulation phasedown of hydrofluorocarbon refrigerants in illuminated sign cooling systems is accelerating LED retrofits across European commercial districts. Bavaria hosts engineering clusters for sports-venue scoreboard systems.
Japan
Luxury retail environments in Tokyo, Osaka, and Yokohama are adopting transparent OLED storefront installations for product visualization without obscuring interior sightlines. METI efficiency standards for commercial display equipment influence specification requirements. The Kanto region concentrates system integration expertise for corporate lobby deployments.
South Korea
Display driver IC foundries in Seoul and Suwon control captive semiconductor capacity for high-brightness outdoor modules. MFDS-equivalent certification frameworks govern electromagnetic compatibility for networked installations. The Seoul Capital Area anchors both component supply and domestic deployment of close-viewing indoor applications.
Signage Market Competitive Environment
Global majors compete with regional champions across technology integration and software platform development. The vendor base separates into three tiers: integrated electronics conglomerates with captive semiconductor capacity, specialized display manufacturers with in-house engineering capabilities, and regional fabricators serving price-sensitive municipal contracts. Strategic archetypes include software-integrated hardware providers capturing recurring revenue, pure-play substrate manufacturers facing margin compression, and captive IC suppliers securing component allocation. Competitive moves center on backward integration into semiconductor supply and geographic expansion through certified recycling partnerships.
Among integrated electronics conglomerates, Samsung Electronics and LG Electronics occupy positions exemplifying the captive capacity archetype, while Daktronics represents the specialized engineering tier. Samsung Electronics anchors the high-brightness outdoor segment through semiconductor self-sufficiency. LG Electronics exemplifies transparent OLED positioning for luxury retail environments. Daktronics sits within the sports-venue specialization cluster with in-house scoreboard engineering.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| NEC Display Solutions |
| Daktronics |
| Panasonic Corporation |
| Sharp Corporation |
| Planar Systems |
| Sony Corporation |
| Leyard Optoelectronic |
| Others |
Value Chain & Pricing Dynamics
Control system programmers in the Pearl River Delta command wage premiums that widen spreads between premium-tier digital display bundles and economy LED module transactions. Labor-cost differentials in software-integrated hardware versus pure-play substrate manufacturing feed directly into three-tier pricing structures across the signage industry.
Pricing Analysis
Warranty and service bundling separates premium digital display providers from unbundled LED module vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with CE-marked networked systems commanding positioning above FCC-only hardware. Cost compression in economy-tier substrates intensifies because recycled aluminum input volatility squeezes municipal bid margins. Franchise retail chains show least price sensitivity given operating-lease tax advantages, while regional fabricators serving public tenders face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for sports-venue scoreboard systems, while distributor networks serve fragmented municipal procurement. Geographic concentration centers on Taiwan and South Korea for display driver ICs, China for aluminum smelting and module assembly, and Germany for engineering clusters. Raw material dependencies span semiconductor wafers, recycled aluminum frameworks, and LED phosphor substrates. Single-source vulnerability in Taiwan foundry capacity for high-brightness outdoor modules creates allocation risk during fab loading cycles. Distribution runs through certified systems integrators for smart city deployments and direct manufacturer relationships for national retail contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
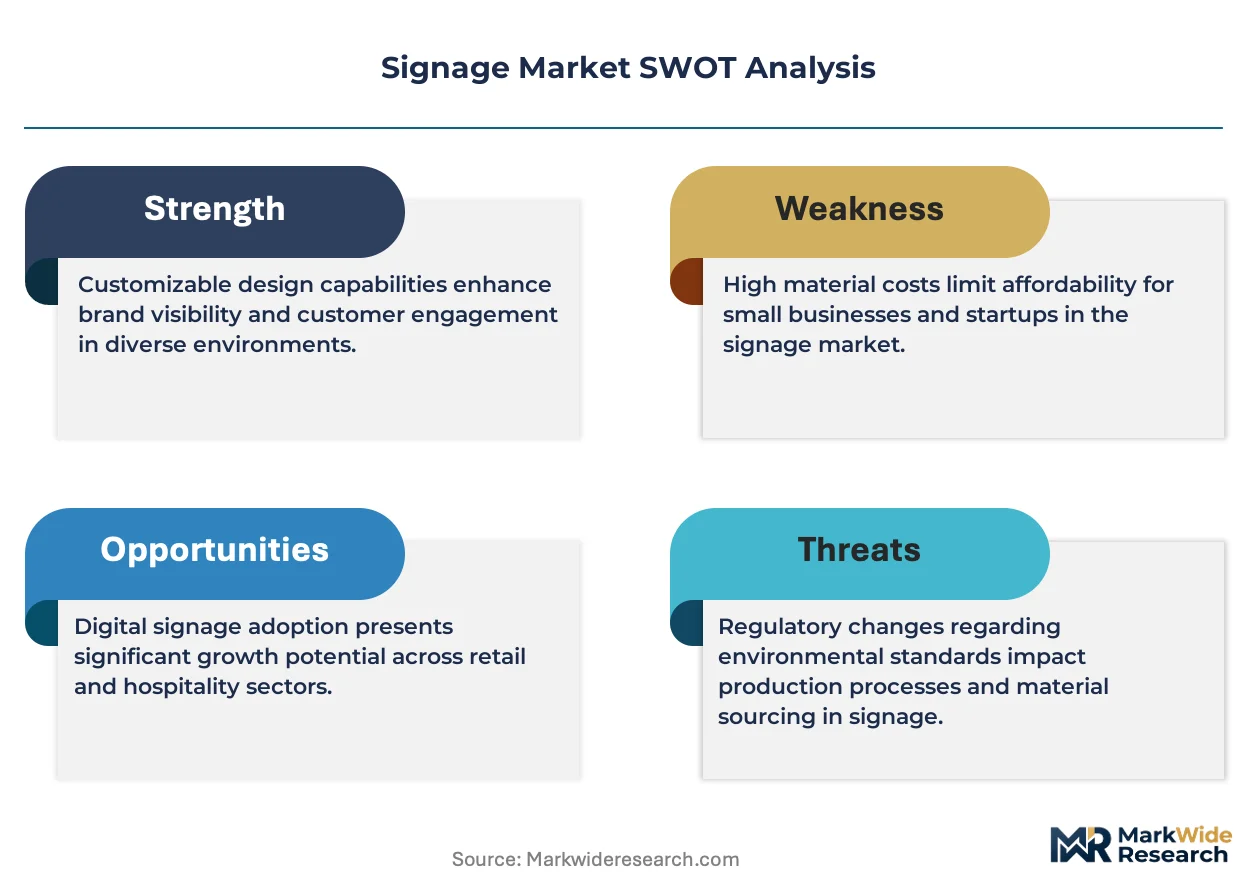
The signage sector sits in a technology-transition phase as addressable LED arrays displace legacy fluorescent tube installations. This replacement cycle favors vendors with networked control system programming capabilities over electrical contractors facing skill gaps.
For Market Incumbents: Acquire captive semiconductor capacity to secure display driver IC allocation during Taiwan and South Korea foundry loading cycles. Samsung Electronics exemplifies this defensive posture through in-house production of high-brightness outdoor components. Incumbents must also consolidate content management platform subscriptions to counter software-integrated hardware providers redistributing margin pools away from pure-play substrate manufacturers.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in transparent OLED storefront installations offers white-space entry for specialized system integrators. Luxury retail environments in Dubai, London, and Tokyo represent the most penetrable segment given specification complexity that deters commodity panel vendors. New entrants should pursue certified recycling partnerships under California, French, and Japanese extended producer responsibility frameworks as a go-to-market differentiator.
For Investors and Strategic Acquirers: Re-rating potential sits with software-integrated hardware providers given cloud-based content management platform adoption accelerating recurring revenue capture from franchise networks. Long-term viability across the analysis window favors vendors with backward integration into semiconductor supply and geographic diversification beyond single-source foundry dependence. Investors should monitor LED retrofit enforcement timelines under EPA energy conservation standards and EU F-Gas Regulation as inflection indicators for replacement cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Captive display driver IC capacity insulates Samsung Electronics from Taiwan foundry allocation cycles. |
| Certified Recycling Partnership Expansion | Extended producer responsibility compliance in France and Japan differentiates municipal bid positioning. |
| Cloud Content Management Platform Launch | Subscription unbundling from hardware sales captures lifetime value from QSR franchise networks. |
| Transparent OLED Product Line Extension | See-through display installations in Tokyo luxury retail command specification premiums over LCD videowalls. |
| Sports-Venue Scoreboard System Acquisition | In-house engineering capabilities anchor Daktronics positioning against integrated electronics conglomerates. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with display procurement directors at retail chains, transit authority technology officers, electrical contractor project managers, and content management platform engineers combined with EPA enforcement documentation, EU F-Gas Regulation implementation schedules, and semiconductor trade flow statistics. Bottom-up triangulation across module shipment volumes and top-down validation through installed base estimates ensured cross-verification.
Granularity-level modeling addressed product type at the pixel pitch and illumination technology tier, end user at the vertical procurement consolidation stage, material at the recycled content certification level, and installation type at the IP rating and brightness specification tier. CAGRs derived from replacement cycle timing under energy-efficiency mandates and smart city infrastructure program commitments. Forecast inputs incorporated EU electromagnetic compatibility directive enforcement trajectories and embedded carbon disclosure rule adoption curves across corporate procurement teams.
Inputs from EPA enforcement timelines and EU regulatory implementation schedules were available through the study window; gaps in real-time foundry loading cycle data introduce uncertainty bands around display driver IC supply assumptions. Forecasts reflect base-case assumptions regarding LED retrofit acceleration and software-recurring revenue model adoption. Periodic stress-testing of base assumptions is recommended given regulatory enforcement variability and semiconductor capacity expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building Management System Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Asia-Pacific Building Automation System Market