
 Building Information Management System Market | 2026-2036
Building Information Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Building Information Management System Market Insights
The gap between premium digital-twin platforms and commodity modeling tools is expanding as enterprise buyers demand real-time IoT integration and predictive maintenance analytics. Autodesk Inc. leverages its construction cloud ecosystem to anchor large infrastructure contracts across North America. Nemetschek Group sustains a federated portfolio strategy that competes across architectural and engineering verticals without full-stack dependency. Bentley Systems Inc. specializes in heavy civil and industrial applications where geospatial precision dominates procurement criteria.
A building information management system comprises software infrastructure that aggregates architectural, engineering, and operational data into interoperable digital representations of physical facilities, typically utilizing Industry Foundation Classes for geometric data exchange and COBie standards for asset handover. Its primary commercial purpose is to reduce capital project waste and extend facility lifecycle performance through centralized information governance. Cloud-based deployment now leads adoption among multi-site facility operators seeking elastic compute for real-time collaboration, while asset management modules capture expanding margin pools as owners prioritize operational-phase digital continuity over construction-phase visualization alone. Project collaboration tools remain mature with slower growth, though hybrid architectures gain traction where data sovereignty requirements conflict with pure SaaS models.
ISO 19650 series standards shape cross-border deliverable requirements for managed information environments, while the EU Green Deal and national building performance certificates in France and Germany mandate energy-modeled asset data that only integrated BIM platforms can generate cost-effectively. The US General Services Administration embeds BIM deliverables into federal project contracts, creating de facto procurement filters that exclude non-compliant vendors. Stakeholders must monitor how emerging AI code-checking modules and embodied-carbon calculation requirements reshape platform evaluation criteria before vendor selections lock in multi-year implementation cycles.
Market Dynamics
Cloud-native architecture is compressing deployment cycles from months to weeks, forcing incumbent vendors to restructure pricing around consumption rather than perpetual licenses. The EU Green Deal's embodied-carbon disclosure requirements now mandate that facility data platforms calculate lifecycle emissions, embedding compliance logic directly into procurement specifications.
Growth Catalysts
- Germany's digital building mandate:Federal requirements for BIM deliverables on public infrastructure projects above €5 million create mandatory procurement volume for integrated asset management platforms.
- COBie standard adoption:The Construction Operations Building information exchange specification is becoming a contractual deliverable in UK and Nordic facility handovers, forcing contractor investment in compatible data infrastructure.
- IoT sensor density:Real-time building performance monitoring through wireless sensor networks generates continuous data streams that legacy CAFM systems cannot process, accelerating replacement cycles.
Market Restraints
- Specialized labor scarcity:Qualified BIM managers command premium compensation in Germany and the Netherlands, inflating implementation costs for mid-market facility operators.
- Data sovereignty fragmentation:France's CNIL guidance on cloud data localization conflicts with pure SaaS architectures, forcing hybrid deployments that increase operational complexity.
- OpenBIM interoperability gaps:Proprietary data formats from dominant design software vendors create translation friction during asset handover, degrading operational-phase data quality.
Strategic Opportunities
- Retrofit-dense urban clusters:Milan and Barcelona's century-old building stocks require non-invasive digital surveying and as-built modeling services that mobile LiDAR and photogrammetry platforms can address.
- AI code-checking modules:Automated compliance verification against national building codes reduces engineering review cycles, creating attach revenue for platforms integrating regulatory logic.
- Performance-based service contracts:Energy savings guarantees from facility management providers require continuous digital twin calibration, embedding platform vendors in long-term operational relationships.
Industry Challenges
- Legacy CAFM migration complexity:Decades of unstructured maintenance records in incumbent systems resist automated extraction, requiring manual data cleansing that delays cloud transitions.
- Multi-stakeholder governance alignment:Architects, engineers, contractors, and facility operators maintain conflicting data priorities, complicating single-source-of-truth implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Information Management System Market |
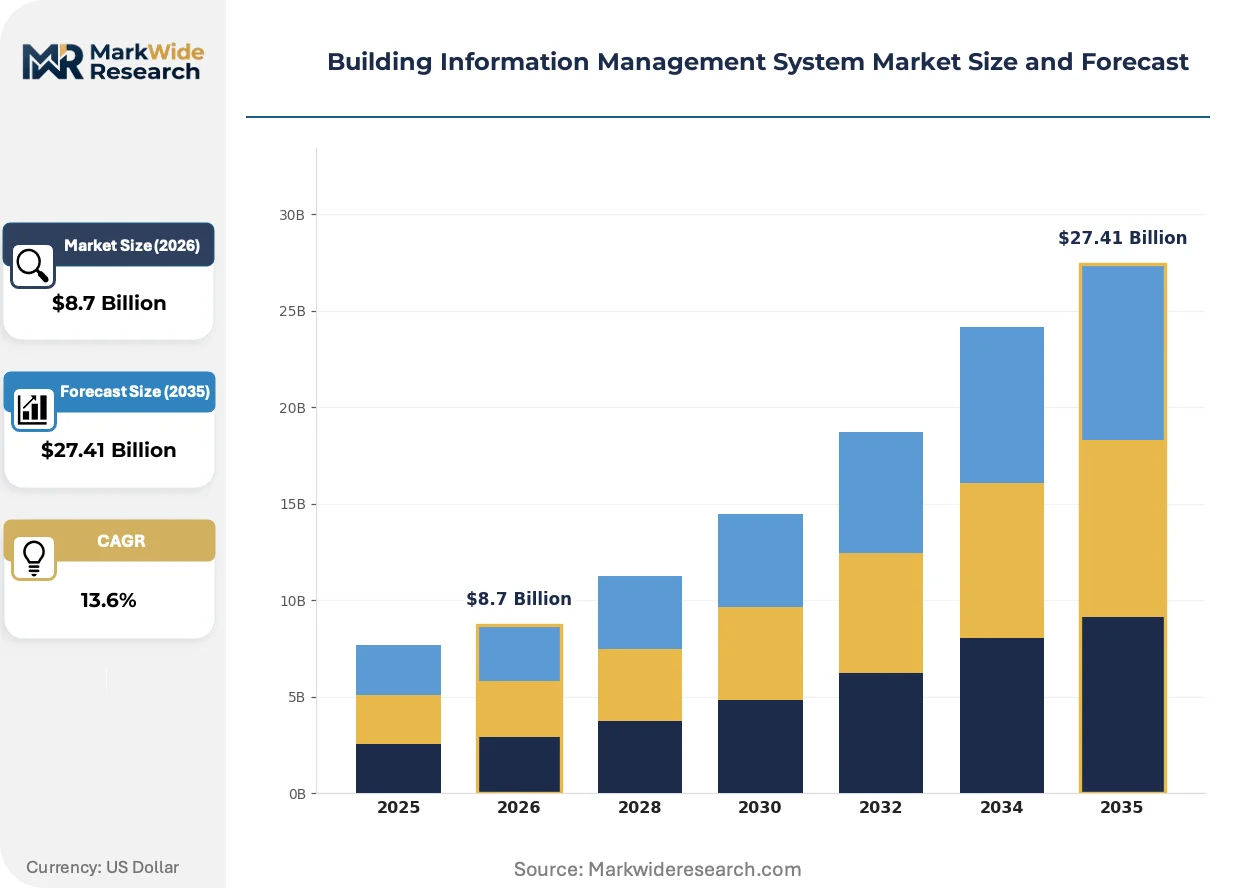
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling Software, Asset Management, Project Collaboration, Facility Scheduling, Regulatory Compliance Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Application: Construction Planning, Resource Management, Maintenance Scheduling, Energy Optimization, Space Utilization End User: Architects, Engineering Firms, Property Developers, Facility Operators, Construction Managers |
| Companies Covered | Autodesk Inc., Nemetschek Group, Bentley Systems Inc., Trimble Inc., Dassault Systèmes, Hexagon AB, Procore Technologies Inc., Asite Solutions Ltd., AVEVA Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Information Management System Market Trends and Innovations
Generative design algorithms and edge-computing architectures are converging to enable real-time building performance optimization. These capabilities are reshaping how owners evaluate platform vendors, prioritizing predictive analytics over static documentation.
Digital-twin middleware is modularizing around discrete functional components—energy simulation, occupancy analytics, predictive maintenance—rather than monolithic suites. Large hospital systems and university campuses in Sweden and Denmark are adopting best-of-breed stacks, integrating specialized modules through open APIs. This architecture is modularizing vendor competitive dynamics, compressing margins for generalist platforms while rewarding deep vertical specialists.
The EU AI Act's risk classification framework now governs automated decision-making in building control systems, particularly for fire safety and elevator management. Platform vendors must document algorithmic transparency and human oversight protocols to maintain CE marking eligibility. Industrial and healthcare facility operators face the steepest compliance burden, driving procurement toward vendors with pre-certified AI modules.
Facility owners are unbundling design-phase and operational-phase software procurement, ending the tradition of construction-contractor platform selection. Direct owner procurement of cloud-native asset management systems is displacing inherited BIM-to-FM workflows in UK social housing and Dutch municipal portfolios. This pattern is most pronounced where public sector framework agreements permit separate operational technology sourcing.
Building Information Management System Market Segmentation
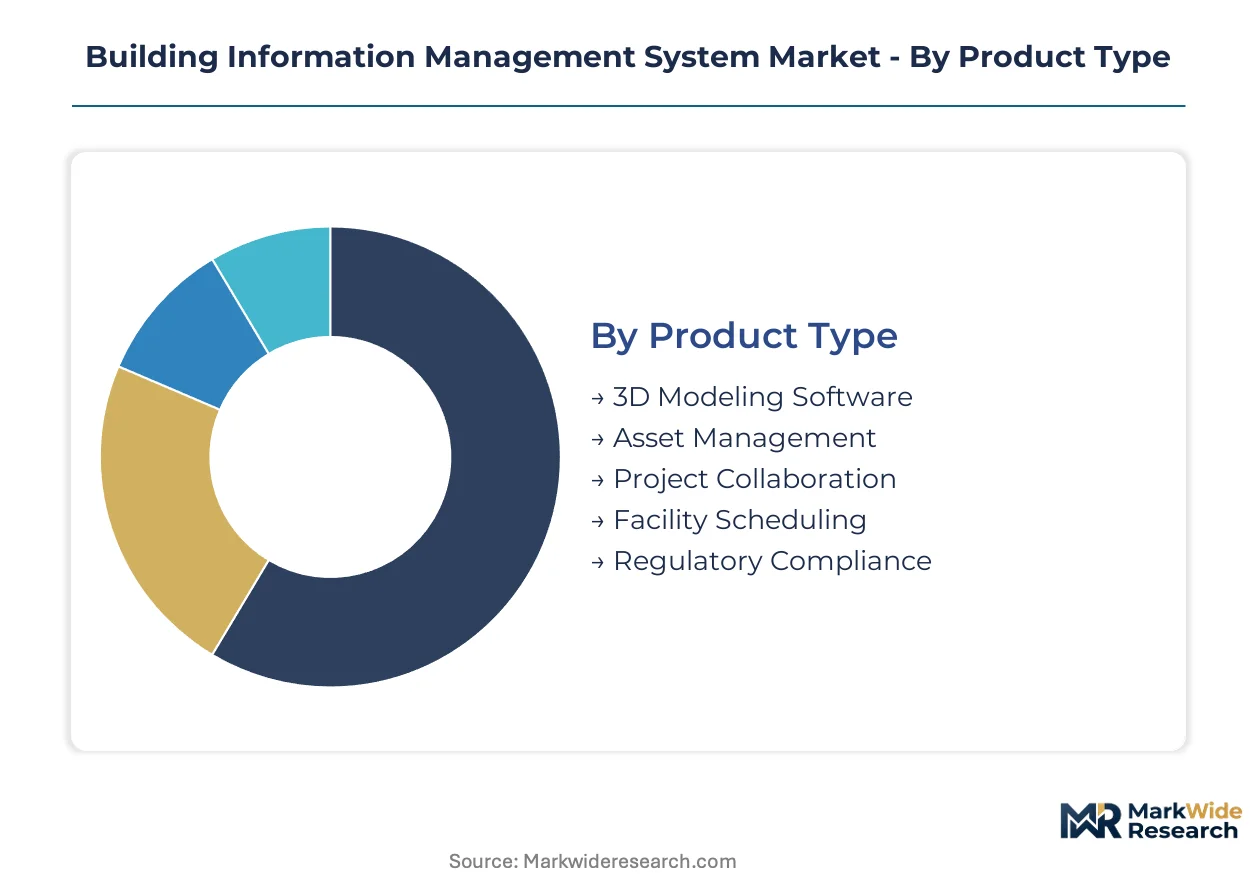
Building information management systems fragment across multiple technical and commercial axes that determine procurement patterns. Each segmentation dimension reveals distinct buyer priorities, from construction-phase visualization tools to operational-phase predictive analytics platforms.
Product Type:
Technical sophistication and lifecycle positioning separate modules that dominate capital expenditure from those capturing recurring operational revenue.
- 3D Modeling Software:Core geometric modeling engines utilizing Industry Foundation Classes for parametric design and clash detection. Demand concentrates in German infrastructure procurement where federal BIM mandates require model-based deliverables on public contracts above €5 million.
- Asset Management:Operational-phase platforms aggregating COBie-standard asset data for predictive maintenance and lifecycle cost optimization. UK social housing associations and Dutch municipal portfolios are accelerating direct procurement of these cloud-native systems, displacing inherited contractor-selected tools.
- Project Collaboration:Multi-stakeholder coordination environments enabling real-time model sharing and change management across distributed teams.
- Facility Scheduling:Integrated timeline engines linking construction sequencing with resource allocation and subcontractor coordination.
- Regulatory Compliance:Automated code-checking modules verifying designs against national building standards and emerging embodied-carbon disclosure requirements.
Asset management leads on scale; regulatory compliance leads on momentum.
Deployment:
Architecture choices reflect trade-offs between elastic compute scalability and data sovereignty constraints that vary by facility operator risk profile.
- Cloud-Based:SaaS platforms delivering centralized data repositories with automatic updates and API extensibility. Multi-site facility operators in Sweden and Denmark favor these architectures for real-time collaboration across hospital systems and university campuses.
- On-Premise:Self-hosted installations maintaining physical data control for operators with strict cybersecurity protocols or legacy integration requirements.
- Hybrid:Split architectures segregating sensitive design data on local servers while leveraging cloud analytics for non-critical workloads. French operators adopt these configurations to satisfy CNIL guidance on cloud data localization without sacrificing computational elasticity.
- Edge Computing:Distributed processing nodes enabling real-time building performance optimization through localized sensor data analysis.
Cloud-based deployment commands volume share; edge computing demonstrates steepest expansion trajectory.
Application:
Functional use cases map directly to stakeholder workflows, with operational-phase applications gaining procurement priority over traditional construction-planning tools.
- Construction Planning:Pre-build visualization and sequencing tools that reduce capital project waste through digital rehearsal of complex assemblies.
- Resource Management:Integrated tracking of labor, materials, and equipment across project timelines with automated shortage alerting.
- Maintenance Scheduling:Condition-based intervention planning utilizing IoT sensor streams to replace calendar-based servicing. Milan and Barcelona retrofit clusters drive adoption where century-old building stocks require non-invasive monitoring approaches.
- Energy Optimization:Continuous building performance tuning against EU Green Deal mandates and national building performance certificates in France and Germany.
- Space Utilization:Occupancy analytics platforms optimizing floor plate efficiency through real-time usage pattern recognition.
Energy optimization dominates current procurement; space utilization is climbing fastest as hybrid work patterns reshape facility requirements.
End User:
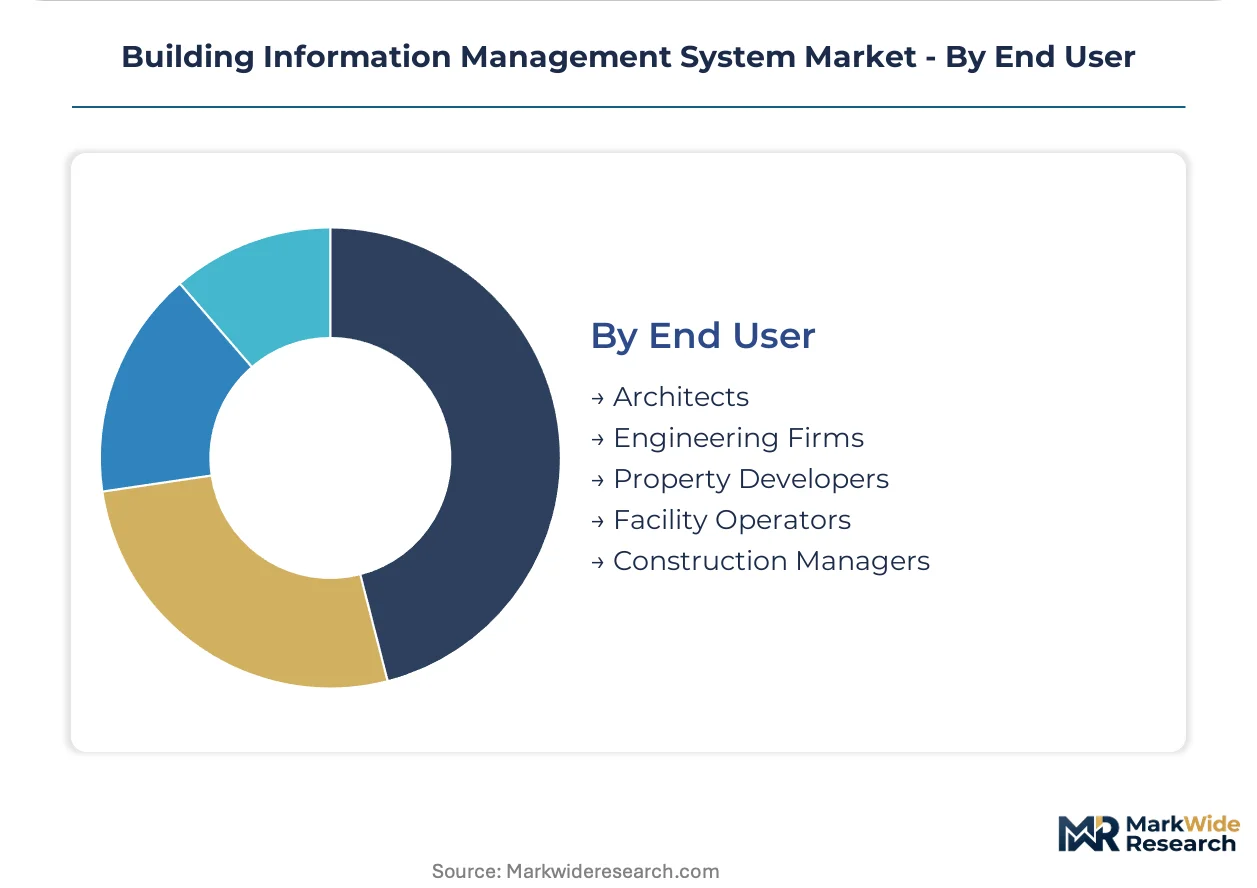
Professional role determines functional priorities, with facility operators emerging as independent buyers separate from traditional construction-phase stakeholders.
- Architects:Design-phase visualization and generative modeling tools prioritizing geometric freedom and rendering performance.
- Engineering Firms:Structural and MEP calculation engines requiring precision analysis and regulatory code integration.
- Property Developers:Investment decision support platforms linking design alternatives to pro forma financial projections.
- Facility Operators:Long-term asset stewards demanding predictive maintenance analytics and digital twin continuity across decades of operational life. This segment is expanding most quickly as owners unbundle operational technology procurement from construction contracts.
- Construction Managers:Field coordination and subcontractor management tools emphasizing schedule compliance and cost control.
Facility operators represent the fastest-growing buyer category; architects retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German BIM managers command premium compensation, concentrating specialized talent in Düsseldorf and Munich. Dutch engineering technologists anchor Northern European implementation capacity. Swedish facility operators drive cloud-native procurement sophistication.
Germany
Federal BIM mandates above €5 million and dense urban retrofit pipelines concentrate procurement volume. The national digital building mandate enforces COBie-standard deliverables on public infrastructure. Berlin and Hamburg municipal portfolios accelerate integrated BIM-to-FM workflow adoption.
United Kingdom
Social housing associations unbundle operational technology from construction contracts. UK BIM Framework mandates align with ISO 19650 for cross-border deliverables. London and Manchester facility operators displace inherited contractor-selected tools with direct cloud-native procurement.
France
CNIL guidance on cloud data localization conflicts with pure SaaS architectures. The EU Green Deal's embodied-carbon disclosure requirements embed compliance logic into procurement specifications. Paris and Lyon operators adopt hybrid deployments segregating sensitive design data from cloud analytics.
Sweden
Hospital systems and university campuses favor modular best-of-breed stacks over monolithic suites. National building performance certificates mandate energy-modeled asset data. Stockholm and Copenhagen clusters integrate specialized modules through open APIs for predictive maintenance.
United States
The General Services Administration embeds BIM deliverables into federal project contracts. Multi-site facility operators seek elastic compute for real-time collaboration across distributed portfolios. Federal procurement filters in Washington DC and California infrastructure projects exclude non-compliant vendors.
Building Information Management System Market Competitive Landscape
Capital-heavy platform developers compete with asset-light integration specialists for procurement influence. The vendor base spans three tiers: construction-cloud ecosystems anchoring large infrastructure contracts, federated portfolio strategies competing across verticals without full-stack dependency, and geospatial precision specialists dominating heavy civil procurement. Strategic moves concentrate on cloud-native restructuring and AI module certification.
Within the construction-cloud tier, Autodesk Inc. and Procore Technologies Inc. exemplify ecosystem anchoring strategies. Nemetschek Group occupies a federated position across architectural and engineering verticals. Bentley Systems Inc. represents geospatial precision specialization for industrial applications. Trimble Inc. and Dassault Systèmes sit within the hardware-software convergence archetype.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Nemetschek Group |
| Bentley Systems Inc. |
| Trimble Inc. |
| Dassault Systèmes |
| Hexagon AB |
| Procore Technologies Inc. |
| Asite Solutions Ltd. |
| AVEVA Group plc |
| Others |
Pricing and Supply Chain Analysis
Premium digital-twin platforms and commodity modeling tools diverge sharply in both pricing architecture and supply chain sourcing, with enterprise-grade IoT-integrated systems commanding subscription premiums through direct vendor relationships while standardized modules flow through regional distribution partnerships serving mid-market facility operators in Germany and the Netherlands.
Pricing Analysis
Bundled construction-cloud ecosystems and unbundled operational-phase modules split pricing architectures across the market. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth under ISO 19650 and EU Green Deal compliance tiers. Cost compression in commodity modeling tiers is intensifying because cloud-native entrants are restructuring around consumption-based SaaS. Mid-market facility operators in France and the UK exhibit highest price sensitivity, while federal infrastructure contractors in Germany demonstrate lowest sensitivity due to mandate-driven procurement.
Supply Chain Analysis
Regional distribution centers in Germany, the UK, and Sweden anchor hub-and-spoke patterns for software licensing and implementation services. Platform development draws from cloud infrastructure providers, specialized IoT sensor manufacturers, and geospatial data services. Single-source vulnerability concentrates in proprietary Industry Foundation Classes translation engines controlled by dominant design software vendors. Distribution runs through value-added resellers and direct enterprise sales teams, with hybrid deployments requiring localized implementation partners to satisfy data sovereignty requirements in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in operational-phase asset management modules as facility operators unbundle procurement from construction contractors, with cloud-native delivery models reducing customer acquisition costs and embedding vendors in long-term service relationships.
For Market Incumbents: Cement ecosystem lock-in by deepening API integrations with IoT sensor networks and predictive maintenance analytics, while acquiring specialized regulatory compliance modules to defend against modular best-of-breed competitors. Prioritize certification investment for AI code-checking functionality under the EU AI Act's risk classification framework. For New Entrants and Emerging Players: Facility management providers in Milan and Barcelona retrofit clusters represent the most penetrable buyer segment, given century-old building stocks demanding non-invasive digital surveying and as-built modeling services. Target direct procurement relationships with Dutch municipal portfolios and UK social housing associations, bypassing traditional construction-contractor gatekeepers through cloud-native asset management positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists offering deep regulatory compliance modules for embodied-carbon calculation and automated code-checking. Long-term viability favors vendors with pre-certified AI transparency protocols and established operational-phase customer relationships. Monitor procurement pattern shifts in German federal infrastructure contracts as the primary inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Restructures vendor economics around consumption-based recurring revenue versus perpetual licensing. |
| AI Module Certification | Secures CE marking eligibility under EU AI Act risk frameworks for automated building control systems. |
| Regulatory Compliance Integration | Embeds embodied-carbon calculation logic directly into procurement specifications for EU Green Deal adherence. |
| Vertical Specialist Acquisition | Compresses generalist platform margins while rewarding deep expertise in energy simulation or predictive maintenance. |
| Direct Owner Procurement Channels | Displaces inherited BIM-to-FM workflows in UK social housing and Dutch municipal portfolios. |
Research Methodology
Direct dialogue with BIM managers, facility operations directors, cloud procurement officers, and regulatory compliance leads grounded the qualitative foundation, cross-referenced with secondary validation from ISO 19650 implementation case studies, EU Green Deal technical documentation, federal procurement databases, and vendor SEC filings. Bottom-up and top-down triangulation reconciled segment-level demand patterns with aggregate market sizing.
Output projections across the analysis window reflect modeled segmentation across deployment architecture, professional end-user role, application lifecycle phase, and regional regulatory cluster. CAGRs derived from historical adoption velocity in mandated procurement environments, elasticity estimates for cloud migration, and IoT sensor density expansion curves in Nordic hospital systems and university campuses.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI Act enforcement timing, openBIM interoperability standardization, and cloud data localization guidance evolution. Outputs reflect documented assumptions around mandate compliance rates and hybrid architecture adoption thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
North America Building Automation System Market