
 Europe Smart Windows Market | 2026-2036
Europe Smart Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Windows Market Intelligence
The EU Green Deal's building renovation targets is realigning procurement priorities across European construction. Saint-Gobain leverages its integrated glass-coating capabilities to dominate electrochromic supply chains. AGC Glass Europe anchors production through regional float-glass facilities in Belgium and France. Chromogenics specializes in thermochromic films for Nordic climate applications.
Smart windows incorporate electroactive coatings—typically tungsten oxide or viologen-based layers deposited via sputtering—that modulate visible light transmission and solar heat gain in response to electrical stimuli or temperature shifts. Electrochromic systems lead commercial adoption due to proven durability cycles exceeding 50,000 switches, while suspended particle devices capture fastest growth in automotive sunroof retrofits. Liquid crystal technology occupies premium architectural segments where instant opacity switching commands price premiums.
REACH compliance and CE marking govern chemical safety and product conformity across EU member states, while the F-Gas Regulation phases out high-global-warming-potential blowing agents in insulating glass units. EMA and national building codes in Germany, France, and Sweden enforce escalating thermal transmittance limits that effectively mandate dynamic glazing in new construction. Stakeholders must monitor revision timelines for the Energy Performance of Buildings Directive to anticipate mandated smart-glass adoption thresholds.
Market Dynamics
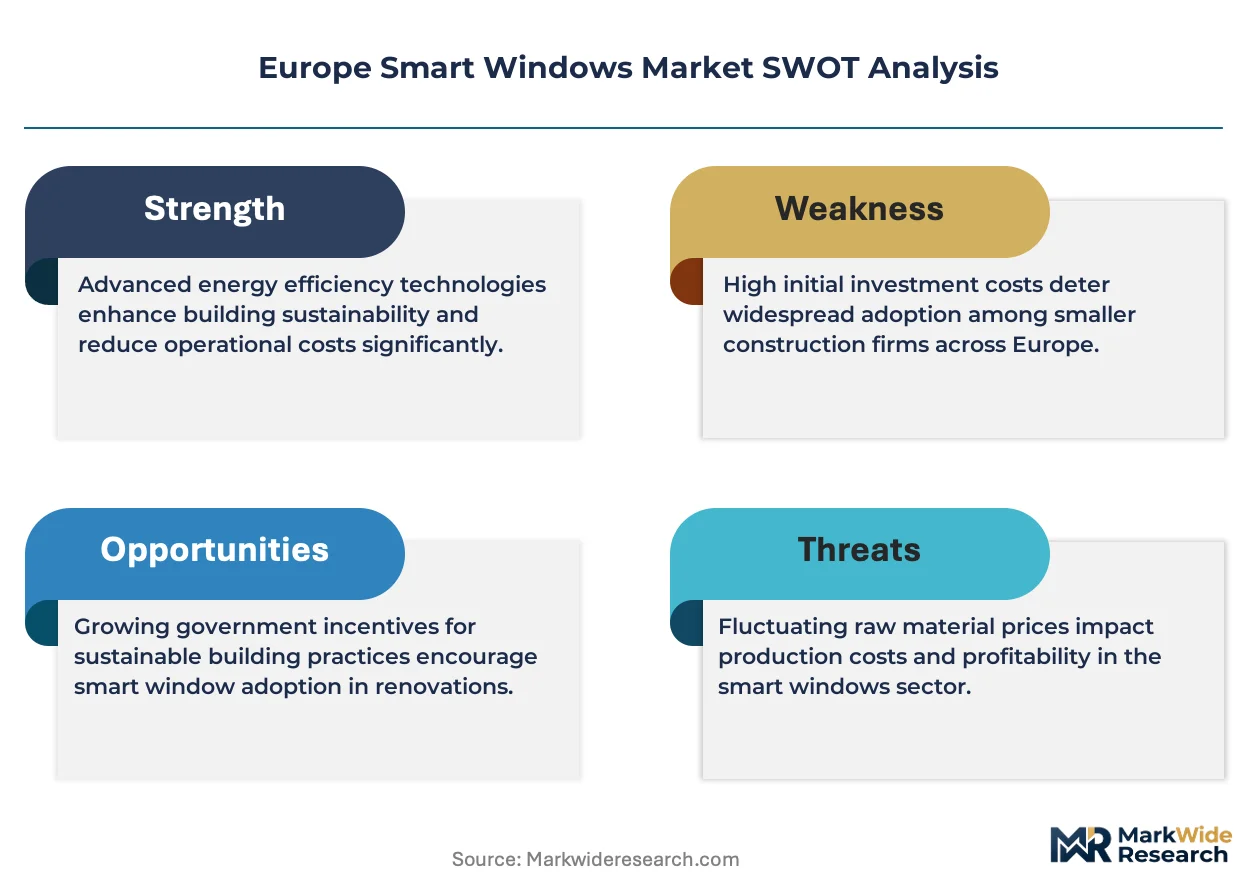
The EU Green Deal's escalating energy performance mandates are compressing payback periods for dynamic glazing investments across European commercial construction. Building renovation targets now effectively require electrochromic and thermochromic solutions in new builds and deep retrofits alike.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory energy performance upgrades across member states are eliminating static glazing options in new commercial construction. The directive tightens thermal transmittance limits every three years.
- Nordic near-zero energy building codes:Sweden, Norway, and Finland now mandate dynamic solar control in office buildings above specific floor areas. These codes accelerate specification of thermochromic films for variable daylight climates.
- F-Gas Regulation phase-out:Restrictions on high-global-warming-potential blowing agents in insulating glass units are pushing fabricators toward electrochromic alternatives that reduce HVAC loads without gas-filled cavities.
Market Restraints
- Sputtered tungsten oxide supply concentration:Deposition equipment and precursor materials for electrochromic layers concentrate among German and Japanese equipment vendors, creating input bottlenecks during capacity expansions.
- REACH compliance timelines:ECHA's evolving substance restrictions on viologen-based electrochromic chemistries extend product certification cycles by 18-24 months, delaying market entry for reformulated coatings.
- Static low-emissivity glass substitution:Mature hard-coat and soft-coat low-E products from regional float-glass facilities undercut smart windows on first cost in residential segments where dynamic control delivers marginal thermal benefit.
Strategic Opportunities
- Polish and Romanian commercial construction:EU cohesion funds are financing office and logistics buildouts in these markets where smart window penetration remains below Western European levels. Local glazing contractors lack electrochromic installation expertise, creating first-mover advantages.
- Automotive sunroof retrofits:Suspended particle device manufacturers are targeting aftermarket conversion of panoramic glass in premium German vehicle fleets. This channel bypasses OEM qualification timelines.
- Energy Performance of Buildings Directive revision:Anticipated 2025 amendments will likely mandate dynamic glazing in specific building categories. Stakeholders positioning integrated glass-coating capabilities now will capture specification lock-in.
Industry Challenges
- Electrochromic deposition technician scarcity:Sputtering process optimization for large-area architectural glass requires specialized training that regional vocational programs have not scaled to match installation demand in Germany and France.
- CE marking timeline compression:Notified body backlogs for construction product regulation compliance now extend 14-18 months, delaying revenue recognition for new electrochromic product variants.
- Legacy building management system integration:BACnet and Modbus protocol mismatches between smart window controllers and existing HVAC automation in 1990s-era commercial stock require costly middleware development per project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Windows Market |
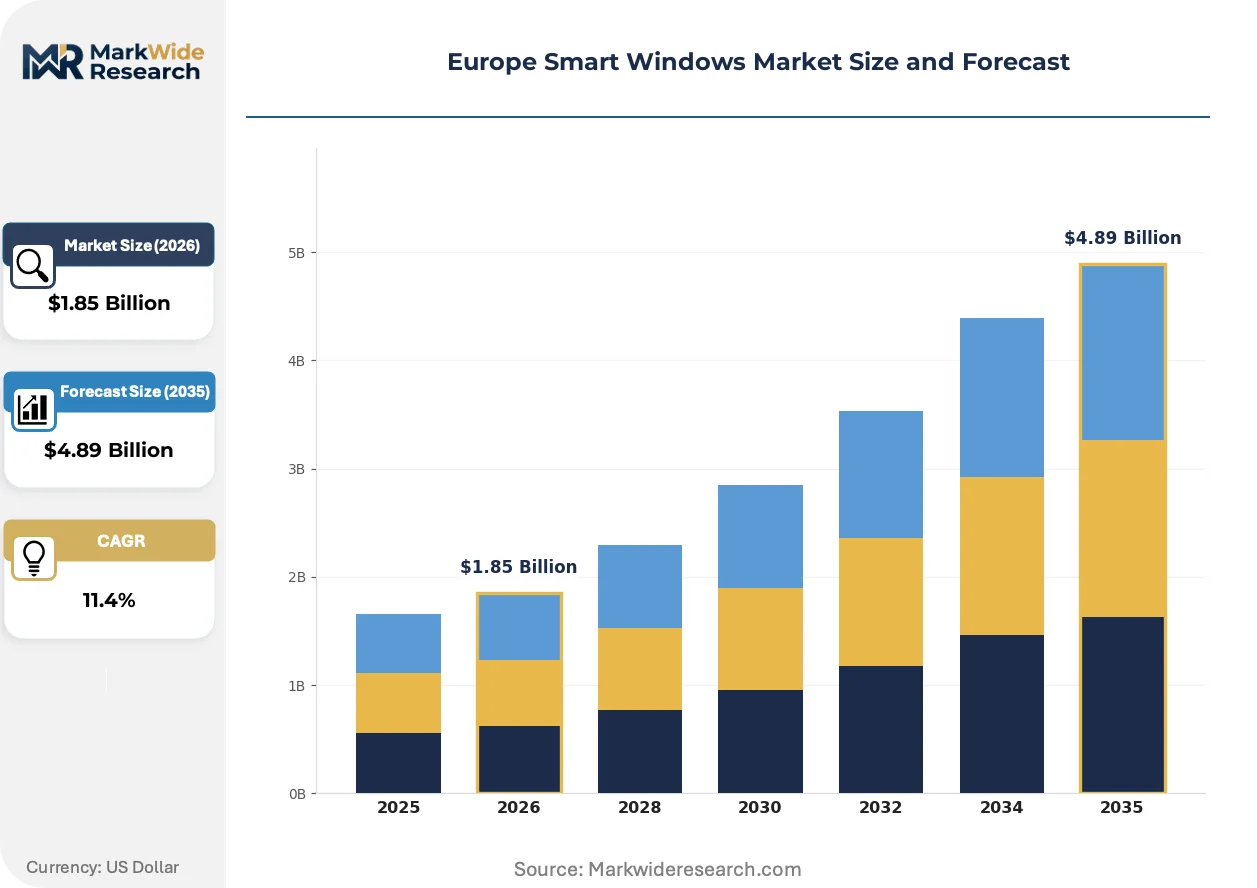
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic, Thermochromic, Photochromic, Suspended Particle Technology: Liquid Crystal, Nanotechnology, Polymer Dispersed Liquid Crystal, Smart Glass Application: Commercial Buildings, Residential Buildings, Automotive, Aerospace End User: Architects, Contractors, Homeowners, Facility Managers |
| Companies Covered | Saint-Gobain, AGC Glass Europe, View, Inc., Gentex Corporation, PPG Industries, EControl-Glas, Chromogenics, Smartglass International, SageGlass, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Windows Market Strategic Shifts & Innovations
Electrochromic technology is consolidating its position as the dominant dynamic glazing platform while regulatory pressure and procurement evolution reshape how smart windows reach European building projects.
Multi-layer sputtered tungsten oxide-nickel oxide stacks are consolidating electrochromic market share against suspended particle and liquid crystal alternatives. Large-format architectural glass processors in Belgium and France are adopting these chemistries for facade projects exceeding 10,000 square meters. The technology is consolidating supply chains around integrated glass-coating capabilities that captive deposition lines provide.
REACH chemical safety restrictions and the F-Gas Regulation are jointly eliminating conventional insulating glass configurations from compliant product portfolios. ECHA's substance of very high concern listings now target chromic acid precursors used in some electrochromic formulations. German facade engineers are responding by accelerating qualification of viologen-free coating stacks ahead of anticipated 2026 restriction timelines.
Building developers in France and Sweden are unbundling glazing procurement from general contractor packages, creating direct specification relationships with smart window fabricators. This disintermediation compresses decision cycles and shifts technical risk to specialized subcontractors. The pattern is most visible in Stockholm's ongoing commercial district redevelopment, where developer-led sustainability targets override traditional contractor material preferences.
Europe Smart Windows Market Segmentation
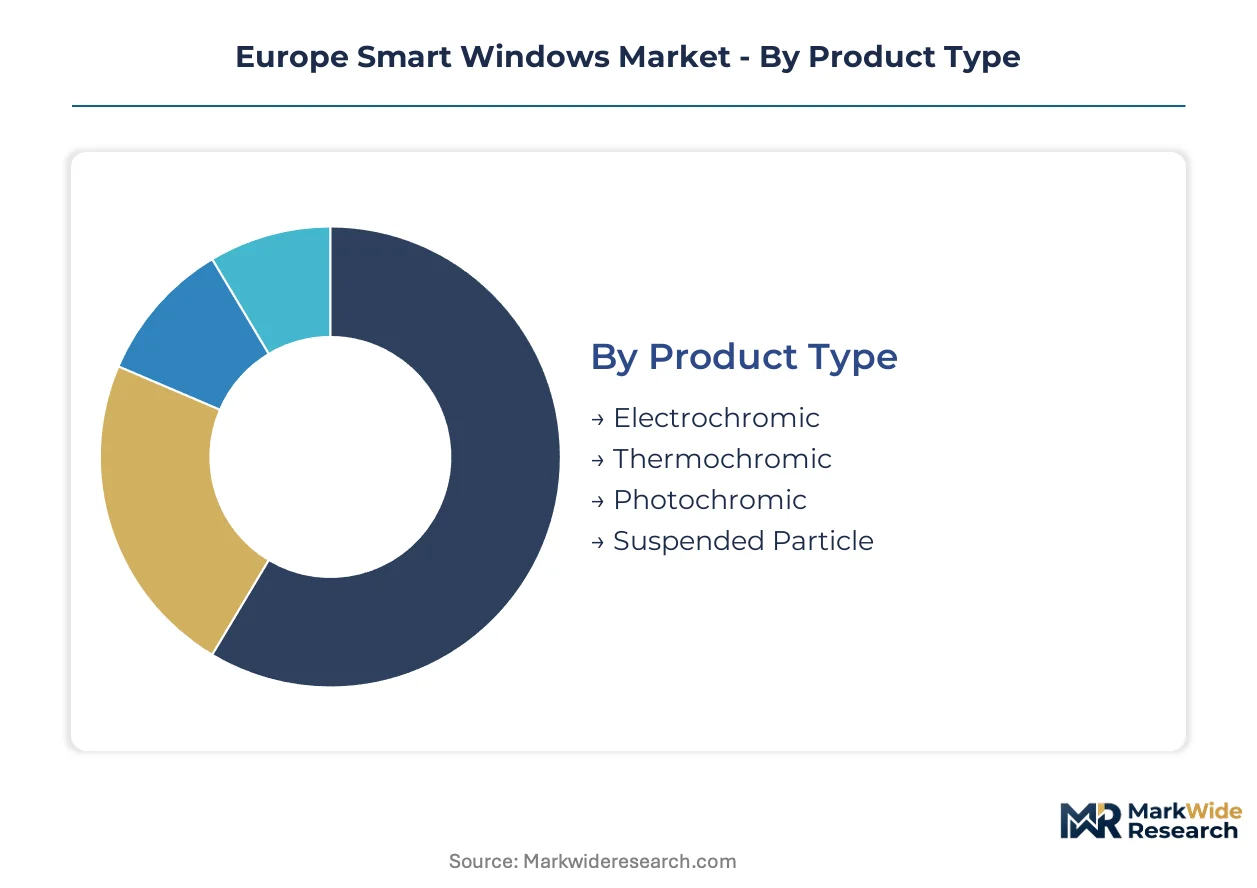
Technology selection in the Europe Smart Windows Market hinges on balancing installation complexity against regulatory compliance. Procurement patterns diverge sharply between new construction favoring integrated electrochromic systems and retrofit projects prioritizing film-based alternatives.
Product Type:
Standardization dominates electrochromic and thermochromic supply chains, while photochromic and suspended particle formats retain customization for niche applications.
- Electrochromic:Multi-layer tungsten oxide-nickel oxide stacks deposited via magnetron sputtering deliver 50,000+ switching cycles. German commercial facade projects specify these systems to meet EU Green Deal thermal transmittance limits without gas-filled cavities.
- Thermochromic:Vanadium dioxide thin films transition from infrared-transparent to blocking states above critical temperatures. Nordic office developments in Stockholm and Oslo deploy these for passive solar control where electrical infrastructure is limited.
- Photochromic:Silver halide-embedded polymers darken under UV exposure without external power.
- Suspended Particle:Light-absorbing nanoparticles in liquid suspensions enable instant opacity switching for automotive sunroof retrofits.
Leading the category by volume: Electrochromic. Growing fastest: Suspended Particle.
Technology:
Cost tiers separate mature liquid crystal platforms from emerging nanotechnology approaches still scaling manufacturing.
- Liquid Crystal:Polymer-dispersed configurations sandwich liquid crystals between conductive substrates for millisecond switching speeds. Premium architectural segments in Paris and London specify these for conference room privacy applications where instant response commands price premiums.
- Nanotechnology:Quantum dot and plasmonic coatings enable spectrally selective light modulation beyond visible wavelengths. Belgian research institutes pilot these for next-generation building-integrated photovoltaics.
- Polymer Dispersed Liquid Crystal:Droplet-matrix composites scatter light when de-energized, offering simplified manufacturing.
- Smart Glass:Umbrella term encompassing integrated sensor and control architectures.
Volume concentration: Liquid Crystal. Steepest expansion trajectory: Nanotechnology.
Application:
Customer type determines specification authority — developers control commercial projects while homeowners drive residential retrofit decisions.
- Commercial Buildings:Large-format facade installations exceeding 10,000 square meters dominate value capture. French and Swedish developers unbundle glazing procurement from general contractor packages, creating direct relationships with electrochromic fabricators.
- Residential Buildings:Single-family and multi-unit retrofits favor lower-cost thermochromic films. Polish and Romanian markets show rising specification as EU cohesion funds finance residential energy upgrades.
- Automotive:Aftermarket sunroof conversions bypass OEM qualification timelines.
- Aerospace:Cabin window retrofits demand lightweight, failure-resistant configurations.
Revenue leadership: Commercial Buildings. Gaining share fastest: Automotive.
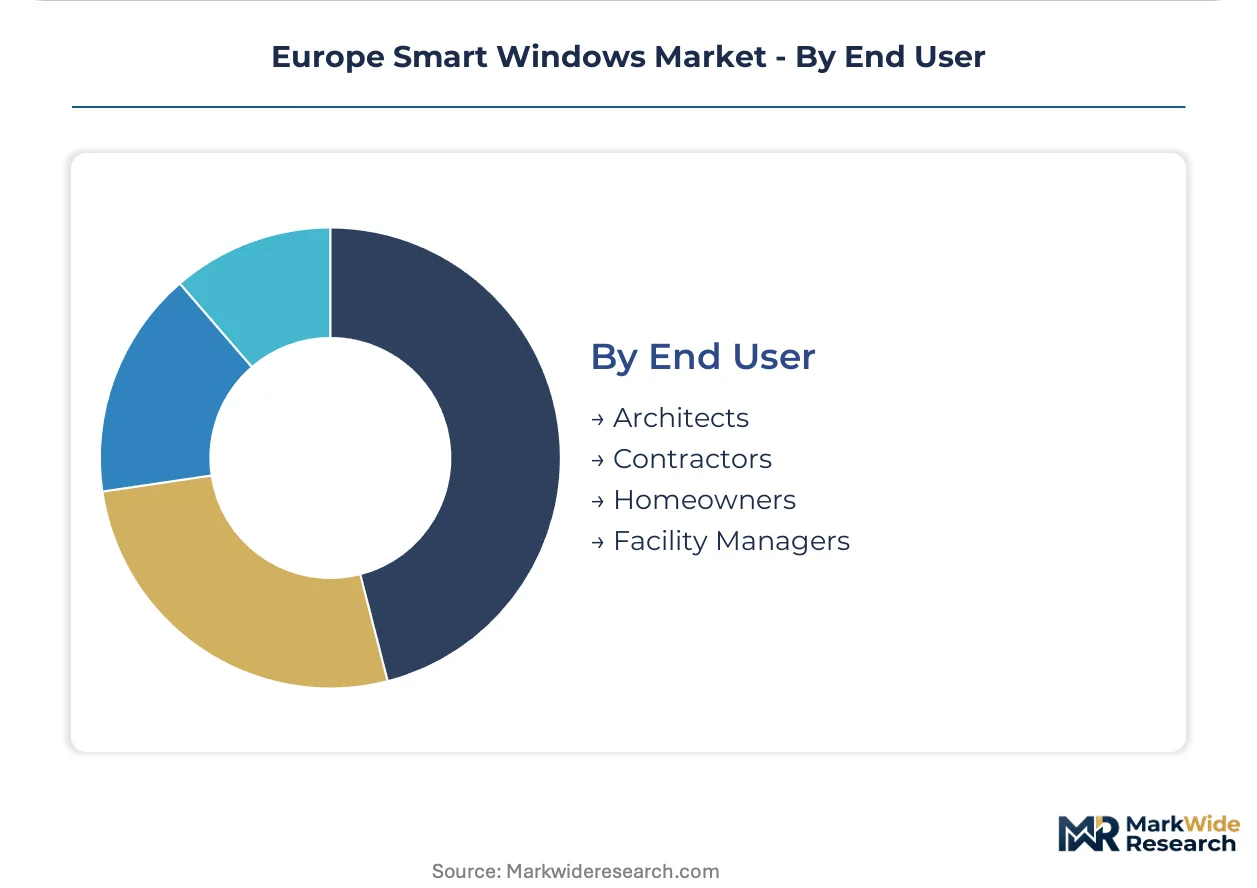
End User:
Supply concentration varies by decision-maker — architects specify performance while contractors optimize installation logistics.
- Architects:Design-phase specification control over thermal and daylighting performance. Nordic practitioners increasingly mandate dynamic glazing in response to near-zero energy building codes.
- Contractors:Execution risk and warranty exposure drive preference for proven electrochromic systems with established installation protocols.
- Homeowners:Price-sensitive demand concentrates in premium renovation segments.
- Facility Managers:Operational cost reduction through HVAC load management motivates retrofit specifications.
Specification authority: Architects. Fastest-growing engagement: Facility Managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium and France host the primary electrochromic coating capacity, while Nordic markets drive specification intensity through stringent building codes. German facade engineering clusters consume the majority of regional output. Distribution networks radiate from Benelux production nodes to serve renovation pipelines across Western and Eastern Europe.
Germany
Commercial facade retrofits in Berlin and Frankfurt account for substantial electrochromic system deployment. The national building code enforces thermal transmittance limits that effectively exclude static glazing from new office construction above specific floor areas. Bavarian glass processors are expanding magnetron sputtering lines to serve developer-led sustainability targets in Munich's commercial district.
France
Parisian commercial developers are unbundling glazing procurement from general contractor packages to accelerate specification cycles. The EU Green Deal's renovation targets are tightening enforcement through national energy performance standards. Lyon-based facade engineering clusters are qualifying viologen-free coating stacks ahead of anticipated ECHA restriction timelines.
Sweden
Stockholm's ongoing commercial district redevelopment is mandating dynamic solar control in response to near-zero energy building codes. EMA-aligned national regulations enforce escalating thermal performance limits that compress payback periods for thermochromic investments. Nordic climate applications are driving specification of vanadium dioxide thin films for passive solar control.
Poland
EU cohesion funds are financing office and logistics buildouts where smart window penetration remains below Western European benchmarks. REACH compliance requirements are extending product certification cycles for imported electrochromic systems. Warsaw-based glazing contractors lack installation expertise, creating first-mover advantages for specialized subcontractors.
Belgium
Regional float-glass facilities in Ghent anchor electrochromic supply chains through integrated coating capabilities. The F-Gas Regulation is phasing out high-global-warming-potential blowing agents in insulating glass units produced for export markets. Flemish research institutes are piloting quantum dot coatings for next-generation building-integrated photovoltaics.
Europe Smart Windows Market Key Industry Players
The competitive structure tilts toward integrated glass-coating specialists with captive deposition capabilities. Saint-Gobain and AGC Glass Europe anchor supply through regional production assets, while smaller specialists occupy niche technology segments. Three archetypes dominate: multinational building materials conglomerates with glass divisions, dedicated electrochromic technology developers, and regional float-glass processors adding coating capacity. Consolidation pressure is intensifying through strategic partnerships between coating equipment vendors and architectural fabricators, alongside capacity expansions targeting Nordic specification growth.
Among multinational building materials conglomerates, Saint-Gobain and AGC Glass Europe exemplify the integrated production archetype through Benelux-based float-glass and coating operations. Chromogenics represents the specialist tier focused on thermochromic film technologies for climate-specific applications. EControl-Glas and Smartglass International occupy positions within the regional fabricator segment, serving project-specific architectural requirements without captive raw material production. View, Inc. and SageGlass anchor the technology developer archetype, though their European market access depends on local installation partnerships.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Glass Europe |
| View, Inc. |
| Gentex Corporation |
| PPG Industries |
| EControl-Glas |
| Chromogenics |
| Smartglass International |
| SageGlass |
| Others |
Cost & Logistics Intelligence
Family-owned float-glass processors across Belgium and France anchor electrochromic supply chains through captive magnetron sputtering lines, translating upstream coating control into pricing discipline that resists commoditization pressure from static low-emissivity alternatives.
Pricing Analysis
Margin tightening in standard electrochromic facade systems reflects REACH compliance certification costs and extended CE marking timelines. Three-tier pricing structure across premium integrated-control, standard building-management-system-compatible, and economy retrofit film levels separates specification authority. Price differentiation rests on thermal performance certification tier and installation service bundling. Residential retrofits in Poland and Romania exhibit acute price sensitivity, while Stockholm commercial developers prioritize performance over first cost.
Supply Chain Analysis
Refurbishment flows for failed electrochromic controllers are emerging as secondary supply channels, with German facade engineering clusters recovering deposition equipment for redeployment. Raw material sourcing draws from German and Japanese equipment vendors for tungsten oxide precursors, Belgian float-glass facilities for substrate supply, and Nordic research institutes for vanadium dioxide thin films. Single-source vulnerability concentrates in sputtering equipment procurement, where two vendors dominate architectural-scale deposition tools. Distribution runs through Benelux production nodes to glazing contractors across Western and Eastern European renovation pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetron sputtering technician scarcity props pricing power for integrated coating specialists, constraining capacity expansion timelines across German and French commercial facade markets.
For Market Incumbents: Deepen backward integration into tungsten oxide precursor supply through captive chemical processing partnerships, insulating margin structures from ECHA substance restriction volatility. Expand deposition technician training programs with Bavarian vocational institutes to preempt installation bottleneck expansion. Prioritize viologen-free coating stack qualification ahead of anticipated 2026 restriction timelines. For New Entrants and Emerging Players: Thermochromic film technology for Nordic climate applications offers specification entry without competing against Saint-Gobain's electrochromic scale advantages. Target Polish and Romanian commercial construction where EU cohesion fund flows exceed local glazing contractor expertise, creating first-mover specification capture. Pursue direct developer relationships rather than general contractor channel penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional float-glass processors with underutilized coating capacity in Benelux production corridors, where F-Gas Regulation compliance investments have strained smaller fabricators. Five-to-ten year viability hinges on Energy Performance of Buildings Directive amendment positioning. Monitor ECHA substance of very high concern listing announcements for electrochromic chemistry inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive tungsten oxide supply insulates Saint-Gobain and AGC from ECHA restriction volatility. |
| Regional Capacity Expansion | Bavarian sputtering line additions target Munich developer-led sustainability specifications. |
| Viologen-Free Coating Qualification | Lyon facade engineering clusters accelerate REACH-compliant stack validation ahead of restriction timelines. |
| Installation Technician Training Scale-Up | German vocational partnerships address electrochromic deposition specialist scarcity constraining project delivery. |
| Developer Direct Procurement Relationships | Paris and Stockholm commercial projects unbundle glazing from contractor packages, shifting specification authority. |
Research Approach
Multi-period observation of electrochromic system deployment rates, REACH compliance certification timelines, and Nordic building code amendment trajectories anchored the trend analysis, supplemented by interviews with facade engineering directors, glazing procurement managers at French commercial developers, magnetron sputtering equipment vendors, and ECHA regulatory affairs specialists. Secondary validation drew from EU Green Deal implementation reports, national building code transposition documents, F-Gas Regulation enforcement notices, and construction product regulation notified body disclosure filings. Bottom-up project pipeline enumeration triangulated against top-down construction sector output estimates.
Segment-weighting across technology type, application category, and end-user decision authority structured the analytical framework across the analysis window. Modeled dimensions included electrochromic versus thermochromic versus suspended particle technology platforms, commercial building versus residential versus automotive application segments, and architect versus contractor versus facility manager specification control. CAGRs were derived from installed base growth rates applied to average system pricing trajectories, with inputs from HVAC load reduction quantification studies and dynamic glazing payback period analyses.
Several conditions sit outside the modeled scope, including potential EU AI Act implications for automated window control systems, unforeseen breakthroughs in quantum dot coating manufacturing scalability, and geopolitical disruption to Japanese sputtering equipment supply chains. Forecasts reflect assumptions regarding Energy Performance of Buildings Directive amendment timing and ECHA substance restriction implementation schedules. Practitioners should monitor ECHA candidate list announcements and Nordic national code revision publications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
North America Building Automation System Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
LAMEA Building Automation System Market