
 Sand Control Tools Market | 2026-2036
Sand Control Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Control Tools Market Analytics
Buyer concentration among offshore drillers is consolidating as supermajors internalize well completion planning and reduce vendor panels. Schlumberger Ltd. leverages integrated project management to anchor relationships with national oil companies in deepwater provinces. Baker Hughes Company competes through proprietary screen metallurgy and real-time downhole monitoring systems. Halliburton Company sustains geographic dominance in North American unconventional basins through localized manufacturing and service density.
Sand control tools are mechanical and chemical systems engineered to prevent formation sand migration into wellbores while maintaining hydrocarbon flow rates, typically constructed from corrosion-resistant alloys with mesh ratings between 40 and 400 microns depending on formation grain size distribution. These tools serve the essential function of preserving well productivity and preventing catastrophic downhole equipment erosion in unconsolidated sandstone reservoirs. Gravel packs occupy the largest installed base across mature offshore fields where reliability premiums justify higher upfront costs. Screens represent the fastest-growing product category as premium mesh and pre-packed designs displace conventional slotted liners in high-rate gas wells. Chemical stabilizers command concentrated margin pools in tight reservoirs where formation damage sensitivity limits mechanical intervention options.
API Specification 19SS governs screen manufacturing and testing protocols, while NORSOK D-010 shapes North Sea well integrity requirements that directly influence sand control tool qualification timelines. The EPA's UIC program and BSEE well control regulations in the United States impose additional barriers to entry for suppliers lacking documented subsea reliability records. Brazil's national petroleum regulator enforces ANP Resolution 46 requirements for sand management planning in pre-salt developments. Stakeholders must monitor regulatory divergence between prescriptive equipment standards and performance-based well integrity frameworks when allocating R&D and certification budgets across jurisdictions.
Market Dynamics
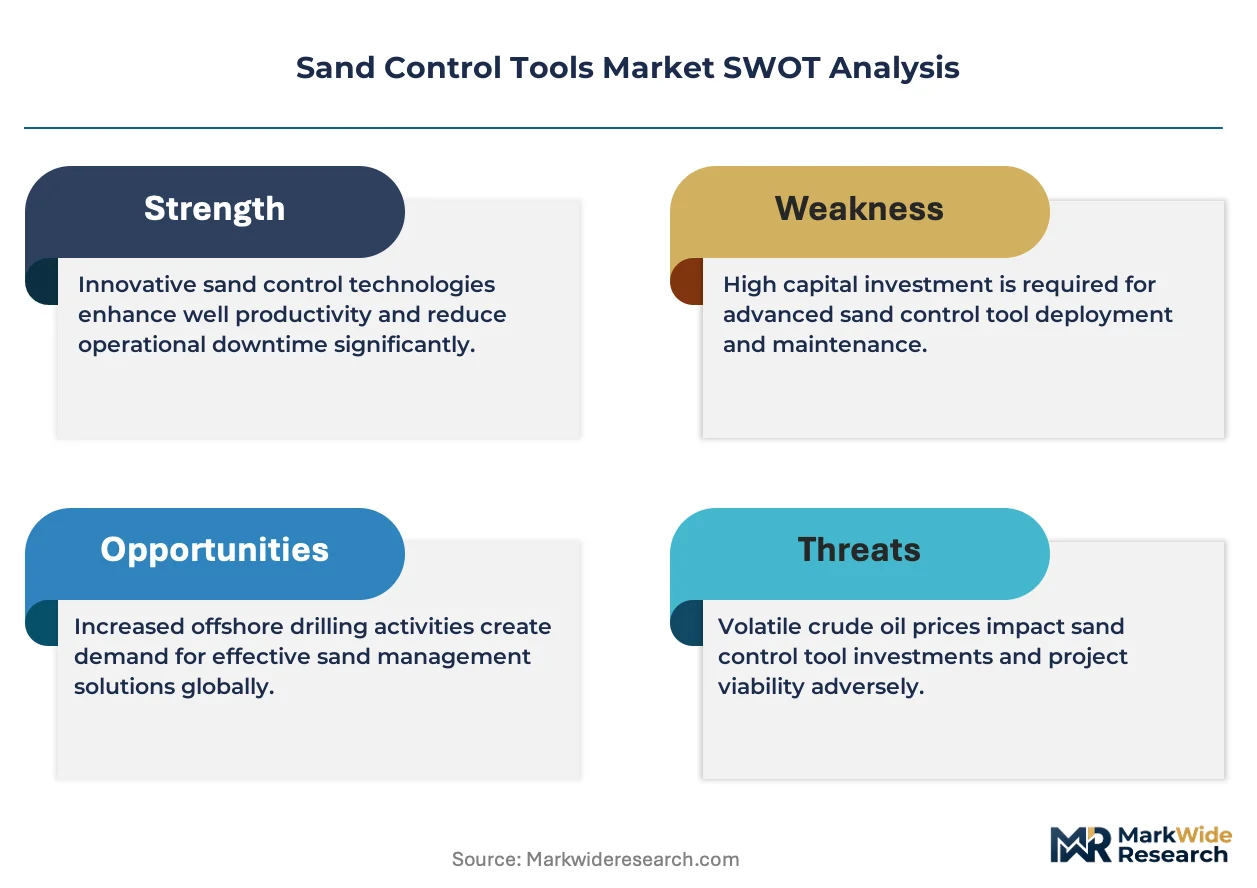
Deepwater drilling economics are forcing operators to consolidate sand control procurement around integrated service packages rather than discrete component sourcing, compressing vendor margins while raising technical qualification barriers for standalone suppliers.
Growth Catalysts
- Pre-salt development mandates:Brazil's ANP Resolution 46 requires comprehensive sand management planning for all pre-salt well completions, creating specification pull for premium screen systems and gravel pack assemblies.
- API Specification 19SS adoption:Standardized screen testing protocols reduce qualification friction for qualified suppliers entering new basins, accelerating replacement cycles for aging slotted liner installations.
- Unconventional gas well intensity:Horizontal laterals in the Permian and Marcellus shales require multi-stage sand control interventions per wellbore, multiplying tool consumption per drilling program.
Market Restraints
- Alloy input cost volatility:Nickel and chromium price swings directly impact corrosion-resistant screen manufacturing economics, squeezing margin predictability for fabricators without long-term supply agreements.
- Gulf of Mexico supplier concentration:Subsea reliability documentation requirements favor incumbent service companies with decade-long BSEE incident records, blocking new entrants regardless of technical merit.
- Mechanical screen limitations:Premium mesh designs face plugging risks in heavy oil reservoirs with high asphaltene content, restricting addressable market share in Canadian oil sands and Venezuelan heavy oil belts.
Strategic Opportunities
- West African deepwater frontier:Senegal and Mauritania offshore developments lack established sand control service infrastructure, creating first-mover positioning for integrated suppliers willing to localize inventory.
- Real-time downhole monitoring convergence:Fiber-optic pressure and temperature sensing bundled with sand screens enables predictive failure detection, justifying premium pricing against conventional passive systems.
- EPA UIC Class II permitting streamlining:Procedural efficiencies for enhanced oil recovery wells in Texas and Oklahoma reduce project cycle times, accelerating chemical stabilizer deployment in mature waterflood assets.
Industry Challenges
- Subsea installation skill scarcity:Gravel pack operations at 5,000+ foot water depths require specialized offshore crews with simultaneous drilling and completion experience, constraining deployment velocity.
- Multi-jurisdiction certification timelines:Suppliers must sequence API 19SS, NORSOK D-010, and ANP qualification testing sequentially rather than in parallel, extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Control Tools Market |
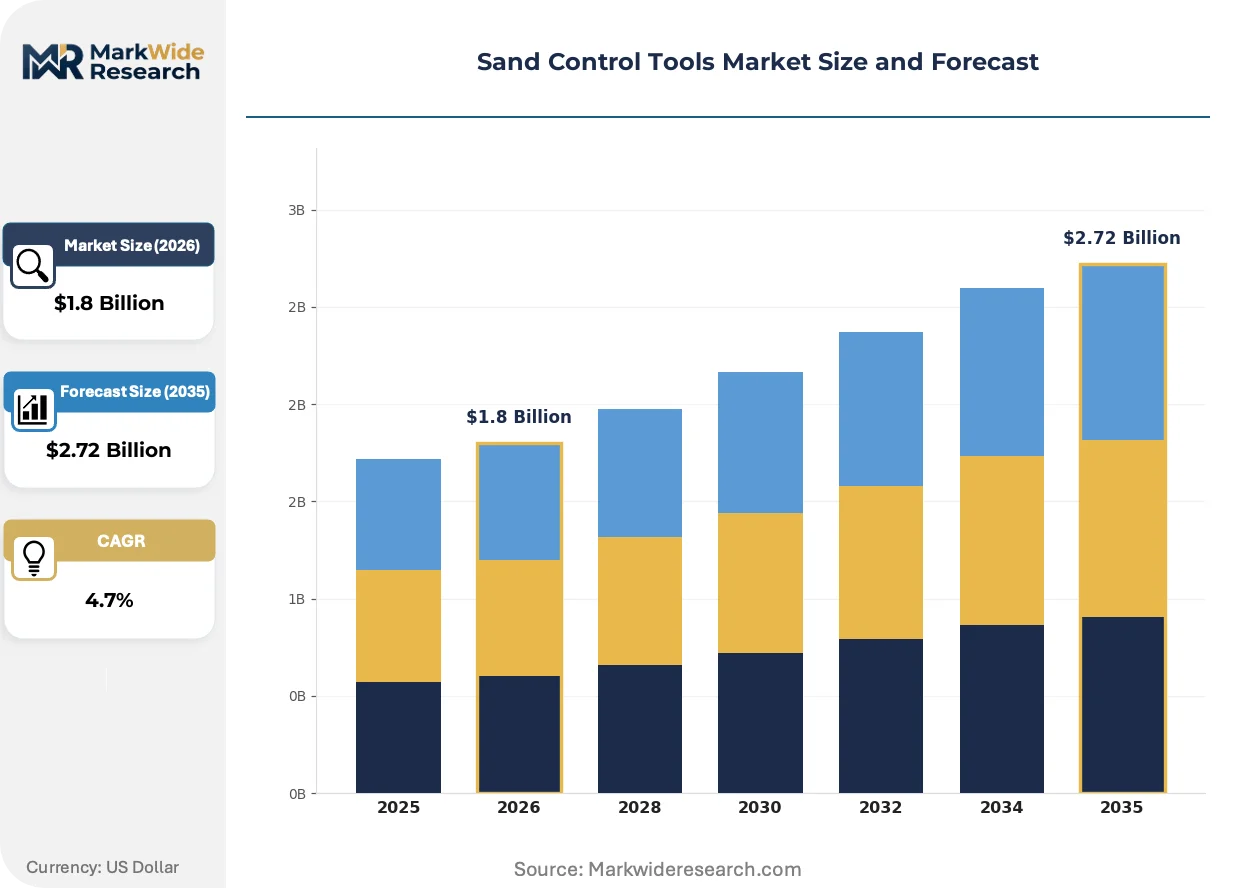
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravel Packs, Screens, Chemical Stabilizers, Resin Coated Sands End User: Oil & Gas Operators, Offshore Drillers, Service Contractors, Well Owners Application: Onshore Wells, Offshore Wells, Tight Reservoirs, Coal Bed Methane Installation Method: Surface Installation, Downhole Installation, Hydraulic Fracturing, Squeeze Cementing |
| Companies Covered | Baker Hughes Company, Schlumberger Ltd., Halliburton Company, Weatherford International Ltd., Superior Energy Services Inc., National Oilwell Varco, Oil States International Inc., Welltec International, Packers Plus Energy Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Control Tools Market Evolving Landscape
Digitalization of downhole diagnostics and metallurgical advances in erosion-resistant coatings are redefining performance benchmarks, while procurement centralization among supermajors is compressing the viable supplier base to integrated technology holders.
Pre-packed premium mesh screens with engineered gravel-to-formation grain size matching are converging with autonomous inflow control devices, enabling zonal flow management in heterogeneous reservoirs without intervention. Offshore operators in the Gulf of Mexico and North Sea are adopting these hybrid systems for high-rate gas wells where conventional standalone screens face erosion failures. The structural consequence is collapsing the distinction between sand exclusion and intelligent completion product categories, forcing specialists to partner or acquire complementary capabilities.
NORSOK D-010 well integrity standards are tightening material traceability and weld inspection requirements for subsea sand control equipment, extending qualification timelines but reducing field failure rates. Norwegian operators Statoil and Aker BP are mandating full manufacturing documentation packages for all critical pressure-containing components. Premium screen suppliers with existing D-010 certifications are capturing incremental share in Barents Sea developments where regulatory stringency exceeds Gulf of Mexico baselines.
Integrated project management contracts are displacing discrete tool rental arrangements as national oil companies in Brazil and Mexico consolidate procurement under single-source accountability frameworks. Service companies offering reservoir characterization, completion design, and post-installation monitoring as unified deliverables are securing multi-year framework agreements. This consolidation is most visible in Petrobras pre-salt campaigns where well complexity justifies bundled risk transfer over component-level competitive bidding.
Sand Control Tools Market Segmentation
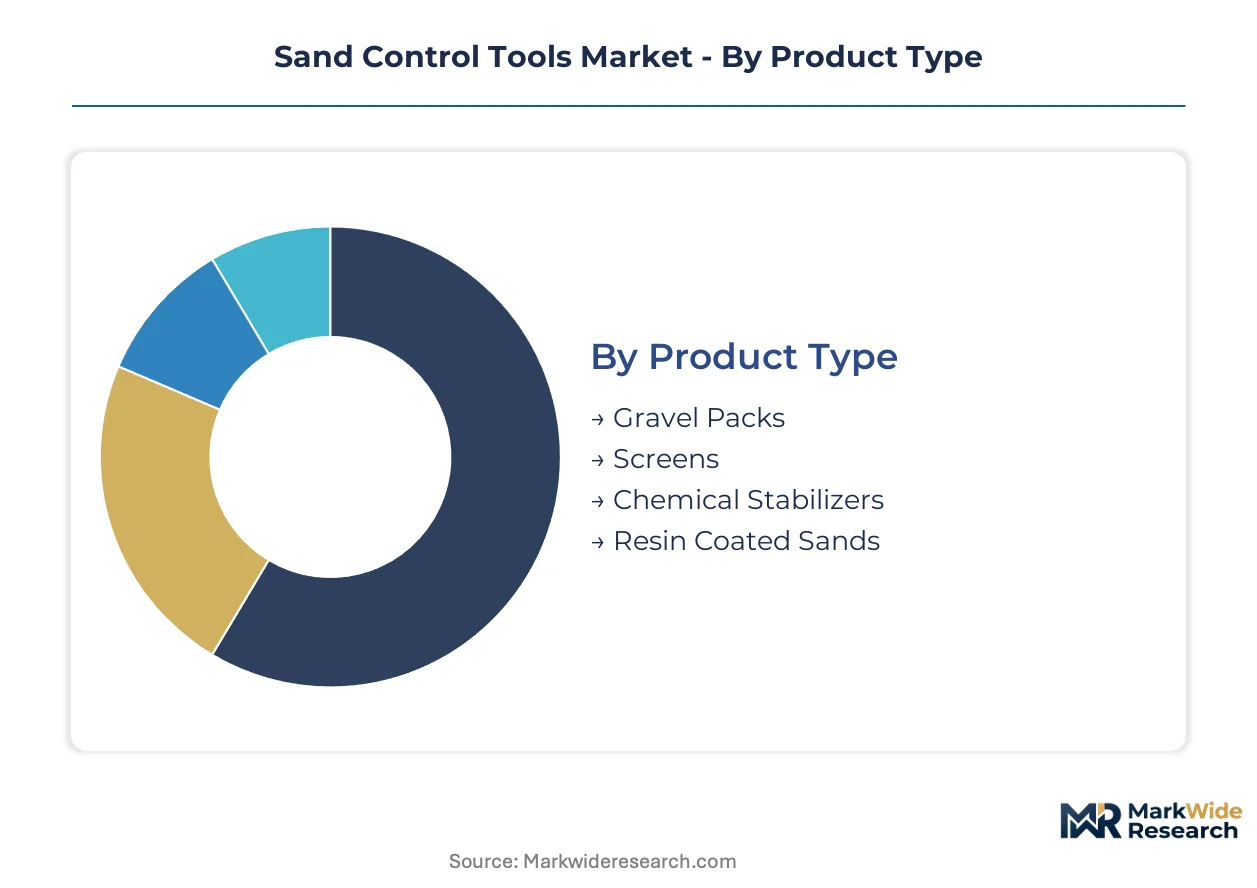
Sand control tool selection hinges on reservoir consolidation characteristics, completion architecture, and regulatory compliance requirements across jurisdictions. Procurement patterns diver sharply between integrated service packages and discrete component sourcing as operators balance reliability premiums against capital efficiency.
Product Type:
Standalone gravel pack systems demand extensive surface support infrastructure while premium mesh screens embed directly into intelligent completion assemblies.
- Gravel Packs:Engineered gravel-to-formation grain size matching creates permeable barriers around wellbores, typically deployed in mature Gulf of Mexico fields where BSEE documentation requirements favor proven reliability. Demand concentrates among supermajors operating deepwater assets off Brazil and Norway where well complexity justifies higher upfront installation costs.
- Screens:Corrosion-resistant alloys with 40-400 micron mesh ratings filter formation sand while preserving hydrocarbon flow rates, with pre-packed premium designs displacing conventional slotted liners in high-rate gas wells. Permian and Marcellus shale operators multiply screen consumption through multi-stage horizontal completions.
- Chemical Stabilizers:Polymer and resin formulations bond unconsolidated sand grains in situ without mechanical intervention, serving tight reservoirs where formation damage sensitivity limits screen deployment.
- Resin Coated Sands:Pre-cured resin shells encapsulate proppant particles for fracture conductivity control in unconventional stimulations, primarily consumed by Permian service contractors.
Gravel packs lead volumes today; screens are gaining share fastest.
End User:
Capital allocation authority determines procurement structure, with well owners internalizing completion design while service contractors retain execution risk.
- Oil & Gas Operators:Integrated majors like Petrobras and Equinor consolidate sand control under single-source accountability frameworks, bundling reservoir characterization, completion design, and post-installation monitoring. These entities prioritize subsea reliability documentation and multi-jurisdiction certification compliance over unit cost minimization.
- Offshore Drillers:Specialized contractors operating in 5,000+ foot water depths require simultaneous drilling and completion expertise, with crew scarcity constraining deployment velocity in West African frontier basins. BSEE incident records and NORSOK D-010 qualifications filter vendor eligibility regardless of technical merit.
- Service Contractors:Schlumberger, Baker Hughes, and Halliburton anchor relationships through localized manufacturing density and real-time downhole monitoring capabilities.
- Well Owners:Independent producers in Texas and Oklahoma leverage EPA UIC Class II permitting efficiencies to accelerate chemical stabilizer deployment in mature waterflood assets.
Oil & gas operators dominate procurement value; offshore drillers show steepest expansion trajectory as deepwater activity intensifies.
Application:
Reservoir pressure regimes and fluid characteristics dictate mechanical versus chemical intervention suitability.
- Onshore Wells:Horizontal laterals in unconventional basins require multiple sand control stages per wellbore, with Permian operators consuming screens and resin coated sands at intensity multiples versus vertical completions.
- Offshore Wells:Subsea installations face erosion risks at high flow rates, driving specification pull for premium mesh and gravel pack systems in Brazil's pre-salt and North Sea high-pressure gas developments.
- Tight Reservoirs:Low-permeability formations suffer irreversible damage from mechanical invasion, restricting addressable methods to chemical stabilizers and precision squeeze cementing.
- Coal Bed Methane:Shallow, low-pressure coal seams require minimal sand control intervention, representing a marginal consumption segment concentrated in Australian and Canadian basins.
Onshore wells anchor current demand; offshore applications expand most quickly as pre-salt and deepwater frontier developments mature.
Installation Method:
Execution complexity scales with water depth, reservoir temperature, and regulatory documentation burdens.
- Surface Installation:Gravel pack pumping and blending equipment positioned on offshore platforms or onshore pads, requiring API 19SS compliant screen handling protocols.
- Downhole Installation:Wireline and coiled tubing conveyed tools place screens and chemical systems at target depths, with fiber-optic sensing integration enabling predictive failure detection.
- Hydraulic Fracturing:High-pressure proppant injection in unconventional reservoirs consumes resin coated sands and diversion tools for zonal isolation.
- Squeeze Cementing:Pressure-pumped slurries seal perforation tunnels and annular channels, predominantly applied in mature North Sea waterflood conversions.
Downhole installation commands premium pricing; hydraulic fracturing shows the fastest volume climb tied to unconventional well intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands deeper gravel pack deployment than Norway, yet Brazilian pre-salt specifications are accelerating premium screen adoption faster than any other basin. Regulatory divergence between prescriptive equipment standards and performance-based well integrity frameworks shapes supplier qualification timelines across jurisdictions.
United States
Permian Basin operators multiply sand control consumption through multi-stage horizontal completions, while Gulf of Mexico drillers prioritize BSEE subsea reliability documentation. EPA UIC Class II permitting efficiencies in Texas and Oklahoma accelerate chemical stabilizer deployment in mature waterflood assets. Houston anchors integrated service company headquarters and localized manufacturing density for North American unconventional basins.
Brazil
Pre-salt well complexity justifies bundled risk transfer over component-level competitive bidding among Petrobras contractors. ANP Resolution 46 mandates comprehensive sand management planning for all pre-salt completions, creating specification pull for premium screen systems. Rio de Janeiro hosts national oil company procurement consolidation and deepwater service infrastructure for Campos and Santos basin developments.
Norway
Statoil and Aker BP mandate full manufacturing documentation packages for critical pressure-containing components in Barents Sea projects. NORSOK D-010 tightens material traceability and weld inspection requirements, extending qualification timelines but reducing field failure rates. Stavanger clusters subsea engineering competence and premium screen suppliers with existing D-010 certifications.
Saudi Arabia
Gas reservoir development in tight sandstone formations drives chemical stabilizer demand where mechanical invasion risks formation damage. The national petroleum regulator enforces well integrity standards that parallel API specifications for screen manufacturing and testing protocols. Dhahran concentrates Saudi Aramco technical headquarters and completion engineering procurement authority.
United Kingdom
North Sea decommissioning schedules intersect with late-life well intervention demand for squeeze cementing and remedial sand control. HSE offshore safety case requirements shape vendor qualification beyond baseline API standards. Aberdeen maintains Europe's largest concentration of subsea installation contractors and specialized offshore crews for simultaneous drilling and completion operations.
Sand Control Tools Market Competitive Landscape
United States producers anchor one tier of integrated service provision; European specialists hold differentiated positions in premium metallurgy and real-time monitoring systems. The vendor base separates into consolidated technology holders with full manufacturing documentation capabilities and regional fabricators serving discrete component demand. Three archetypes dominate: integrated project managers bundling reservoir characterization through post-installation monitoring, premium screen specialists with multi-jurisdiction certification portfolios, and chemical stabilizer formulators targeting tight reservoir applications. Competitive moves center on strategic partnerships for fiber-optic sensing convergence and localized inventory positioning in frontier basins lacking established service infrastructure.
Within the integrated service tier, Schlumberger Ltd., Baker Hughes Company, and Halliburton Company occupy positions as anchor technology holders. Schlumberger exemplifies the bundled accountability archetype through relationships with national oil companies in deepwater provinces. Baker Hughes represents premium metallurgy specialization with proprietary screen manufacturing capabilities. Halliburton anchors geographic dominance in North American unconventional basins through service density and completion design integration. These three entities collectively shape procurement centralization trends as supermajors reduce vendor panels and internalize well completion planning authority.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Schlumberger Ltd. |
| Halliburton Company |
| Weatherford International Ltd. |
| Superior Energy Services Inc. |
| National Oilwell Varco |
| Oil States International Inc. |
| Welltec International |
| Packers Plus Energy Services Inc. |
| Others |
Value Network & Pricing Analysis
Specialized offshore crews with simultaneous drilling and completion experience in the Gulf of Mexico command wage premiums that compress margin pools for integrated service providers, widening spreads between premium-tier bundled contracts and standard discrete component pricing. Labor-cost differentials between Stavanger's subsea engineering cluster and Houston's manufacturing base translate directly into three-tier pricing stratification across corrosion-resistant alloy screens.
Pricing Analysis
Capacity additions in China's specialty steel foundries are reshaping price floors for corrosion-resistant screen alloys, pressuring legacy suppliers in Germany and Japan. Project-based long-term contracts dominate procurement, with price differentiation hinging on API 19SS certification tier and NORSOK D-010 documentation completeness. Cost compression in standard mesh categories is intensifying as Brazilian pre-salt operators consolidate vendor panels. National oil companies prove least price-sensitive, while independent Permian producers aggressively benchmark unit costs across service contractors.
Supply Chain Analysis
Welder certification scarcity in Norway and Scotland constrains throughput for subsea pressure-containing components, extending lead times for Barents Sea developments. Manufacturing concentrates in the United States, Norway, and Brazil, with nickel and chromium feedstocks drawing from Australian and Indonesian mining operations. Single-source vulnerability around premium mesh weaving equipment in Germany and Japan threatens supply continuity. Distribution runs through integrated service company logistics networks rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through fiber-optic sensing bundling that commands premium pricing against passive systems, while alloy input hedging programs protect fabricator economics from nickel volatility.
For Market Incumbents: Extend D-010 certification coverage into Barents Sea suppliers before Statoil and Aker BP finalize framework agreements, and anchor gravel pack service density in West African frontier basins where crew scarcity blocks new entrants. Defensive consolidation around real-time downhole monitoring capabilities counters specialty fiber-optic entrants. Backward integration into corrosion-resistant alloy sourcing mitigates margin pressure from nickel price swings. For New Entrants and Emerging Players: Autonomous inflow control device convergence with pre-packed premium mesh screens offers a technology-first wedge into Petrobras pre-salt procurement where bundled accountability frameworks favor integrated suppliers. Target chemical stabilizer formulations for tight gas reservoirs in Saudi Arabia where mechanical invasion risks limit screen deployment. Pursue EPA UIC Class II permitting expertise as a go-to-market differentiator in Texas and Oklahoma waterflood assets. For Investors and Strategic Acquirers: National oil companies are the most active acquirer in this space, internalizing completion design capabilities through captive service company structures. Five-to-ten-year viability hinges on subsea reliability documentation depth rather than unit cost positioning. Premium screen specialists with parallel API 19SS and ANP qualification timelines represent the most defensible acquisition archetype. Watch BSEE incident record disclosure requirements as the signal for regulatory barrier escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Localized inventory positioning in Senegal and Mauritania captures first-mover rents before infrastructure matures. |
| Backward Integration | In-house corrosion-resistant alloy sourcing insulates margin pools from nickel and chromium price volatility. |
| Technology Licensing | Fiber-optic pressure sensing bundles with sand screens justify premium pricing against conventional passive systems. |
| Joint Venture | Partnerships with autonomous inflow control device specialists collapse the sand exclusion and intelligent completion category boundary. |
| Long-term Supply Agreement | Multi-year framework contracts with Petrobras bundle reservoir characterization through post-installation monitoring risk transfer. |
Research Methodology
Coverage spans the United States, Brazil, Norway, and Saudi Arabia, with primary inputs from each basin's procurement decision-makers. The study combines structured interviews with drilling engineers, completion superintendents, subsea project managers, and national oil company procurement leads with secondary validation through API specification documents, ANP regulatory filings, and BSEE incident databases. Bottom-up well count and completion intensity models triangulate against top-down service company revenue attribution across product categories.
Granularity extends to individual well architecture—horizontal lateral stage counts, water depth tiers, and reservoir consolidation indices—feeding segment-specific volume projections. The analytical framework models gravel pack, screen, and chemical stabilizer demand separately across onshore unconventional, offshore deepwater, and tight gas applications. CAGRs derive from well completion forecasts cross-referenced with sand control tool intensity coefficients by basin maturity. Alloy input cost indices and regulatory qualification timeline assumptions inform price trajectory modeling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pre-salt development pace and West African frontier drilling commitments. Projections reflect assumptions around BSEE documentation requirements remaining stable and NORSOK D-010 traceability standards not extending to raw material origin certification. Material deviation in Brazilian ANP enforcement stringency or nickel price volatility spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Trim Press Market
Tools
Global Scarifiers Market
Tools
Grinding Discs Market
Tools
Woodworking CNC Tools Market
Tools
Ratchet Wringer Market
Tools
Tool Setting Gauges Market
Tools
Cordless Bandsaw Sander Market
Tools
Leather Embossing Machine Market
Tools
Powder Compacting Pressers Market
Tools
Riveting Tools Market
Tools
Ripper Market
Tools
Metal Forming Tools Market
Tools
Grinding Machines Market
Tools
Wood-Sanding Machine Market
Tools
Telescopic Tool Boxes Market
Tools
Industrial Hand Tools Market