
 Dual Migraine Treatment Market | 2026-2036
Dual Migraine Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Migraine Treatment Market Analytics
Multi-source API procurement is pivoting toward captive manufacturing as patent cliffs approach for first-generation CGRP inhibitors. AbbVie leverages its immunology manufacturing infrastructure to secure biologic active ingredient supply chains. Eli Lilly and Company anchors its position through integrated antibody production campuses in the US Midwest. Biohaven Pharmaceuticals competes via specialized small-molecule formulation expertise in nasal delivery platforms.
Dual migraine treatment combines abortive and preventive pharmacological mechanisms into coordinated therapeutic regimens, typically pairing calcitonin gene-related peptide antagonists with triptans or antiemetics to address both acute symptom resolution and long-term episode reduction. Injectable solutions command premium positioning due to cold-chain requirements and subcutaneous administration training, while combination therapy represents the fastest-growing product configuration as payers favor bundled reimbursement. Telehealth services emerge as a high-margin distribution channel by reducing specialist visit overhead and enabling remote monitoring of treatment adherence.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for novel dual-mechanism candidates, though post-market cardiovascular safety monitoring requirements add compliance costs. The EU MDR imposes stricter clinical evidence standards on combination-device products such as autoinjector-plus-drug kits. Stakeholders must monitor evolving FDA guidance on dual-primary endpoint trial designs, as these determinations will shape which therapeutic configurations achieve label claims and formulary placement without explicit year-dependent forecasting.
Market Dynamics
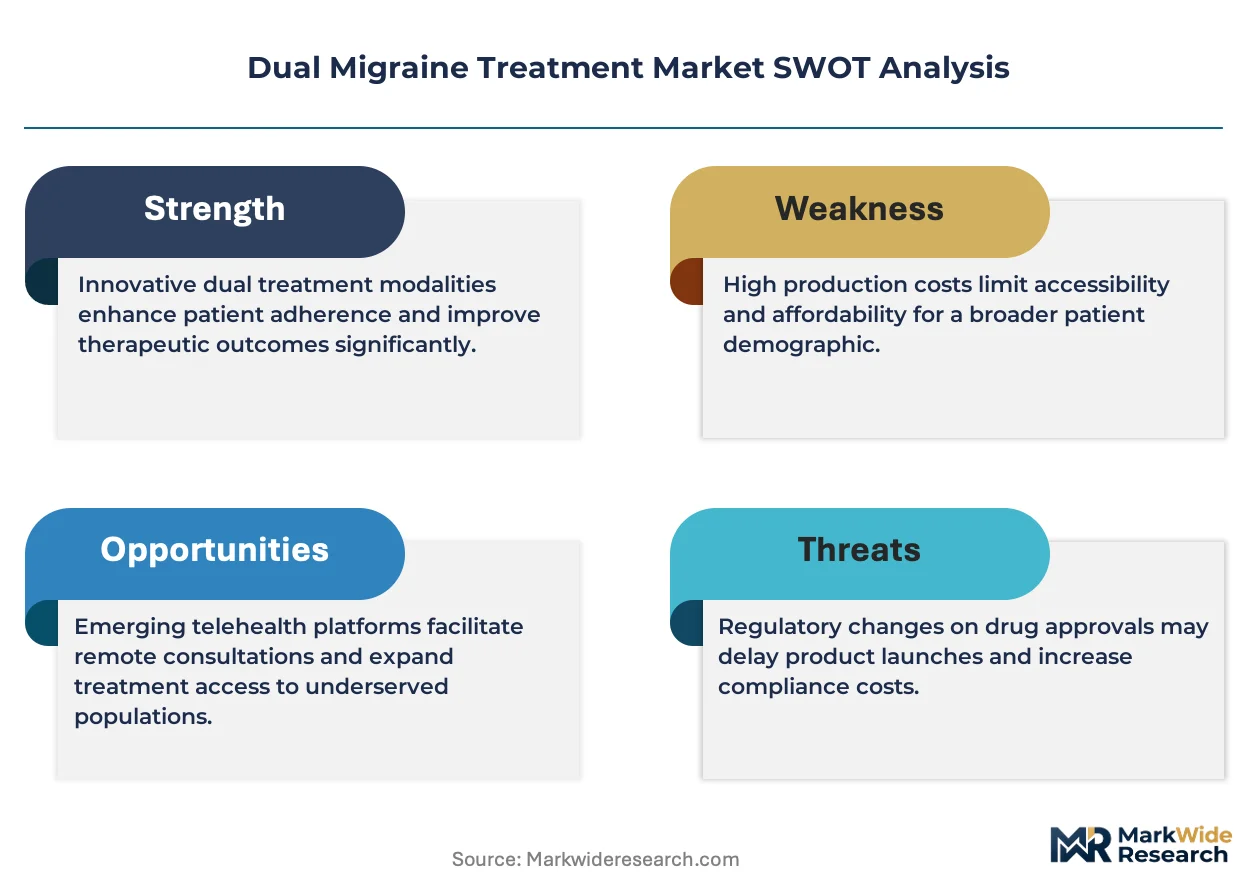
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for novel dual-mechanism candidates, forcing sponsors to accelerate cardiovascular safety database assembly prior to submission. The regulatory premium on speed-to-market reshapes capital allocation across clinical and manufacturing infrastructure.
Growth Catalysts
- Accelerated FDA Pathways:Breakthrough therapy designation for CGRP-targeting combinations compresses Phase II-to-approval intervals by 12-18 months. Sponsors redirect saved timeline into expanded indication pursuit.
- Telehealth Distribution:Remote monitoring platforms reduce specialist visit overhead and enable real-time adherence tracking. Neurology clinics in the United States adopt these channels fastest.
- Japan Reimbursement Alignment:MHLW preventive-abortive bundling incentives favor dual-therapy formulary placement over standalone agents. Payers in Tokyo and Osaka lead implementation.
Market Restraints
- Cold-Chain Input Concentration:Injectable CGRP antibodies require uninterrupted 2-8°C distribution. Limited qualified logistics providers in Germany and the United States create single-point vulnerability.
- EMA MDR Evidence Burden:Combination-device autoinjector kits face stricter clinical evidence standards than drug-only products. Smaller sponsors delay EU launch timelines.
- Triptan Substitution Pressure:Generic sumatriptan retains formulary preference for cost-sensitive payers. Dual-therapy premium pricing faces resistance in Medicaid programs.
Strategic Opportunities
- Underpenetrated Rural United States:Neurology deserts in the Mountain West and Deep South lack specialist access. Telehealth-enabled dual-therapy protocols capture patients otherwise managed by primary care.
- Nasal Delivery Convergence:Small-molecule CGRP antagonists combined with antiemetic powders bypass gastrointestinal absorption variability. Formulation specialists target episodic migraine patients who fear injections.
- IRA Price Negotiation Exclusion:Biologic small-molecule combinations fall outside Medicare price-setting timelines until 2028. Sponsors accelerate US launches ahead of eligibility thresholds.
Industry Challenges
- Cardiovascular Safety Monitoring:FDA mandates post-market surveillance for 5-HT1B/1D agonist combinations. Sponsors must build registry infrastructure capturing 10,000+ patient-years.
- Antibody Manufacturing Skill Scarcity:Mammalian cell culture expertise concentrates at legacy biologics campuses. New entrants compete for limited US Midwest and North Carolina talent pools.
- Legacy EHR Integration:Dual-therapy adherence tracking requires API connectivity with Epic and Cerner installations. Neurology clinics face 18-month implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Migraine Treatment Market |
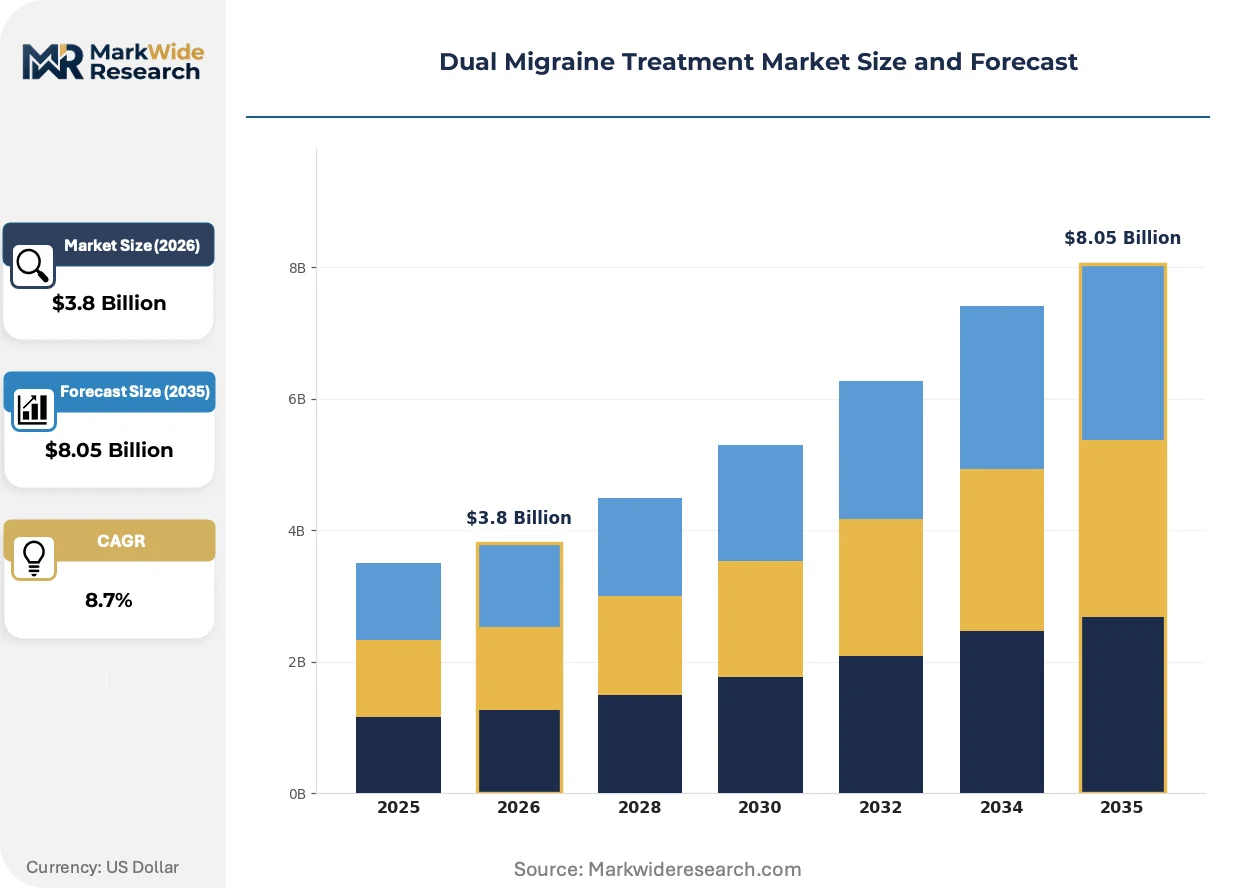
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Abortive Therapy, Preventive Therapy, Combination Therapy, Injectable Solutions End User: Hospital, Clinic, Homecare, Telehealth Services Delivery Mode: Oral, Injectable, Transdermal, Nasal Spray Therapy Area: Chronic Migraine, Episodic Migraine, Hemiplegic Migraine, Others |
| Companies Covered | AbbVie, Amgen, Eli Lilly and Company, Teva Pharmaceutical Industries, Pfizer, Biohaven Pharmaceuticals, Novartis, Lundbeck, Allergan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Migraine Treatment Market Evolving Landscape
Digital biomarker integration and formulation platform diversification are compressing traditional development paradigms. The competitive frontier shifts toward adherence-enabled delivery systems and regulatory-optimized trial designs.
Intranasal powder formulations of CGRP antagonists are converging with connected-device adherence monitors. Patients with needle aversion in Germany and Japan drive adoption of these non-injectable alternatives. The technology convergence enables real-world evidence generation that supports label expansion negotiations with EMA and PMDA.
EMA's updated MDR guidance on combination products imposes clinical evidence requirements exceeding prior drug-device precedents. Autoinjector-plus-drug kits now require human factors studies with 50+ patient participants. Sponsors targeting the European Union delay submission timelines to assemble dossiers, while those with existing MDD certifications rush transitional window filings.
Specialty pharmacy consolidation alters channel economics for injectable migraine therapies. CVS Specialty and Accredo now require outcomes data sharing as a condition of formulary inclusion. The United States market sees direct-to-patient shipment models displace traditional clinic-administered dosing for maintenance regimens.
Dual Migraine Treatment Market Segmentation
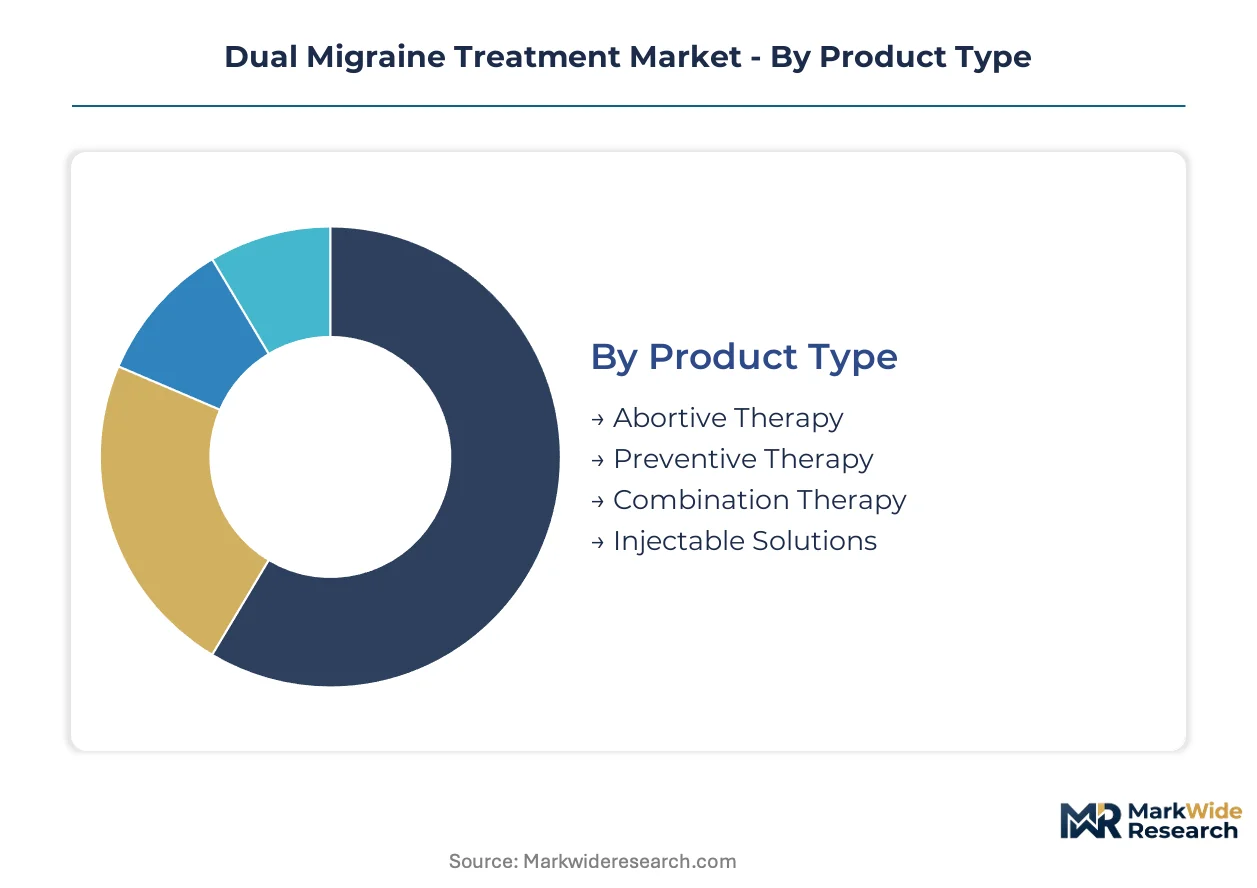
Therapeutic configuration and care setting determine reimbursement pathways and margin structures across the dual migraine treatment landscape. Segmentation reveals where cold-chain infrastructure investments concentrate versus where telehealth-enabled adherence tools capture patient volume.
Product Type:
Buyer differentiation centers on whether patients require immediate symptom interruption, long-term episode reduction, or coordinated protocols addressing both needs simultaneously.
- Combination Therapy:Coordinated regimens pair CGRP antagonists with triptans or antiemetics to address acute resolution and preventive reduction in unified protocols. Payers in the United States and Germany increasingly favor bundled reimbursement for these configurations over standalone agents.
- Injectable Solutions:Subcutaneous CGRP antibodies require cold-chain distribution at 2-8°C and specialized administration training. Premium positioning concentrates in hospital and clinic settings where reimbursement covers handling complexity.
- Abortive Therapy:Acute symptom relief agents including triptans and newer small-molecule antagonists.
- Preventive Therapy:Long-term episode reduction through monthly or quarterly biologic dosing regimens.
Volume sits with Injectable Solutions; growth tilts toward Combination Therapy.
End User:
Care setting selection reflects patient acuity, specialist availability, and reimbursement mechanism alignment across markets.
- Telehealth Services:Remote monitoring platforms reduce neurology specialist visit overhead while enabling real-time adherence tracking for dual-therapy protocols. Adoption concentrates fastest in the United States where rural access gaps and favorable reimbursement codes align.
- Clinic:Neurology and headache specialty clinics in Germany and Japan anchor dual-therapy protocol expansion, with MHLW bundling incentives accelerating preventive-abortive combination placement in Japanese metropolitan centers.
- Hospital:Acute care settings for severe migraine presentation and initial biologic administration.
- Homecare:Self-administered maintenance dosing with nursing support for complex regimens.
Volume concentrates in Clinic settings; expansion tilts toward Telehealth Services.
Delivery Mode:
Patient preference for administration route and pharmacokinetic requirements shape procurement concentration across therapeutic categories.
- Nasal Spray:Powder formulations of small-molecule CGRP antagonists bypass gastrointestinal absorption variability and address needle aversion. Demand clusters in Germany and Japan among episodic migraine patients seeking non-injectable alternatives with faster onset than oral agents.
- Injectable:Subcutaneous and intravenous routes for biologic agents requiring precise bioavailability.
- Oral:Small-molecule tablets and capsules for patient-administered acute and preventive therapy.
- Transdermal:Patch-based delivery systems for sustained antiemetic or analgesic release.
Procurement volume centers on Injectable; patient preference momentum gathers behind Nasal Spray.
Therapy Area:
Migraine subtype classification determines treatment intensity, combination protocol eligibility, and regulatory evidence requirements.
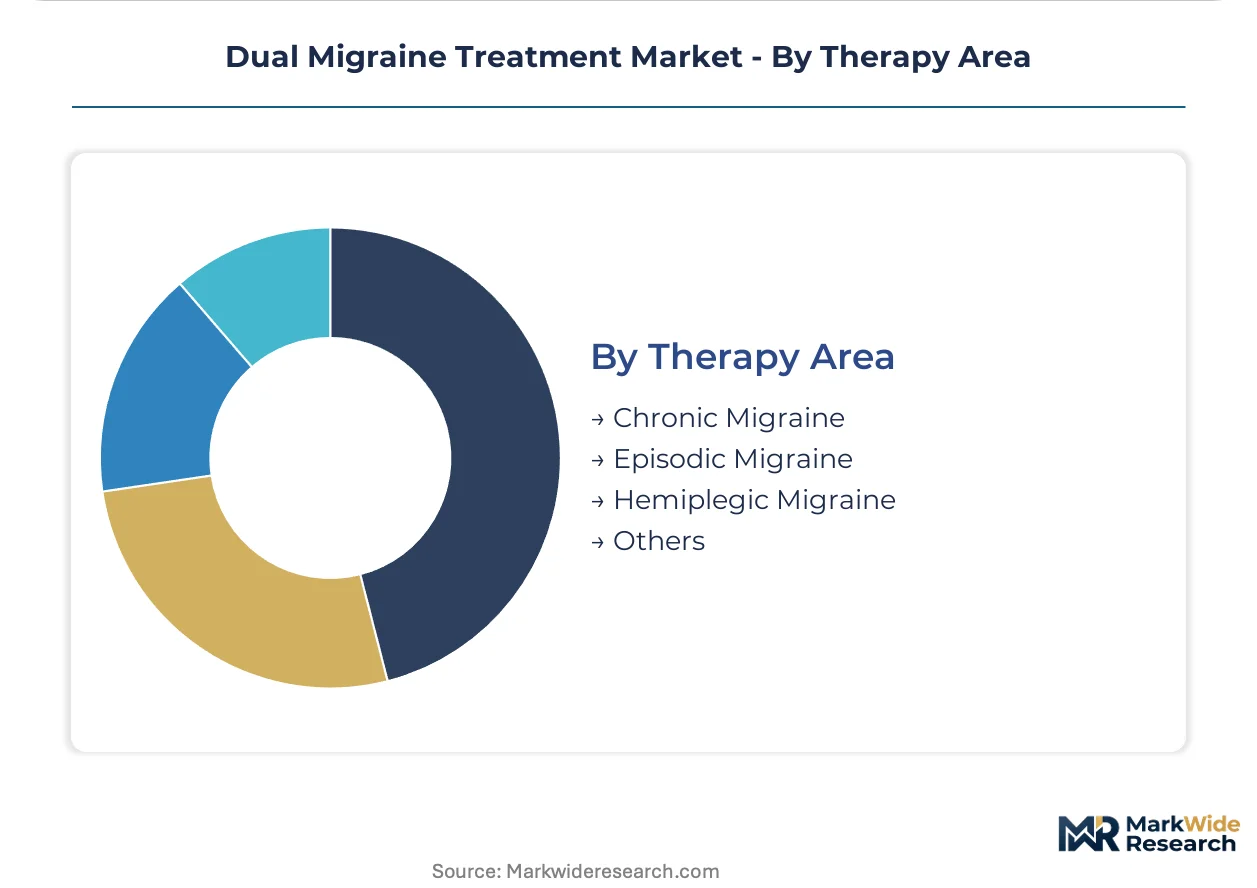
- Chronic Migraine:Defined as 15 or more headache days monthly, this population drives dual-therapy protocol adoption with highest treatment burden and reimbursement justification. Neurology clinics in the United States and Japan prioritize these patients for CGRP-targeting combination regimens.
- Episodic Migraine:Fewer than 15 monthly headache days with variable acute treatment needs.
- Hemiplegic Migraine:Rare subtype with motor aura requiring specialized neurological management.
- Others:Vestibular, abdominal, and other migraine variants with distinct symptomatic profiles.
Patient volume concentrates in Chronic Migraine; protocol innovation targets Episodic Migraine expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibody manufacturing campuses in the US Midwest and North Carolina anchor biologic active ingredient supply for dual migraine therapies, while cold-chain distribution hubs in Germany and Japan concentrate finished dose logistics.
United States
Neurology clinics in Boston and the San Francisco Bay Area pioneer dual-therapy protocols pairing CGRP antagonists with triptans. FDA breakthrough therapy designation compresses development timelines by 12-18 months for combination candidates. The IRA excludes biologic small-molecule combinations from Medicare price negotiation until 2028, accelerating launch timelines ahead of eligibility thresholds.
Germany
Headache specialty centers in Munich and Hamburg drive preventive-abortive bundling adoption among statutory health insurers. EMA MDR imposes stricter clinical evidence standards on combination-device autoinjector kits, delaying some submission timelines. Cold-chain logistics providers in Frankfurt and Cologne create distribution concentration for injectable CGRP antibodies requiring uninterrupted 2-8°C handling.
Japan
MHLW bundling incentives for preventive-abortive combinations favor dual-therapy formulary placement in Tokyo and Osaka metropolitan centers. PMDA accelerated review pathways align with EMA PRIME eligibility for novel dual-mechanism candidates. Domestic biologics manufacturing in Kansai region supports local supply security for chronic migraine patient populations.
United Kingdom
NHS England specialized commissioning frameworks prioritize CGRP-targeting combinations for chronic migraine patients failing prior preventive therapy. MHRA post-Brexit regulatory autonomy enables parallel EMA review compression for combination-device submissions. London and Manchester headache centers anchor real-world evidence generation supporting NICE technology appraisals.
Switzerland
Swissmedic's streamlined review procedures attract European headquarters for specialty migraine pharmaceutical developers. Basel and Zurich clusters concentrate formulation expertise for nasal delivery platforms bypassing gastrointestinal absorption variability. Reimbursement autonomy from EU frameworks permits premium pricing for dual-therapy regimens in private and mandatory health insurance segments.
Dual Migraine Treatment Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory navigation capabilities. The market structure consolidates around integrated biologics manufacturers with captive antibody production, mid-cap formulation specialists, and legacy neurology pharmaceutical divisions. Three archetypes dominate: large-cap immunology platforms with cold-chain infrastructure, small-molecule delivery technology specialists, and diversified pharmaceutical companies with neurology heritage. Competitive moves concentrate on backward integration into API supply and telehealth distribution partnerships.
Within the large-cap immunology tier, AbbVie and Eli Lilly and Company exemplify manufacturing-scale positioning through integrated antibody production campuses. Biohaven Pharmaceuticals occupies a specialist position in non-injectable formulation development. These three anchors represent divergent strategic vectors: immunology platform leverage, biologics manufacturing integration, and delivery technology differentiation.
| Leading Market Players |
|---|
| AbbVie |
| Amgen |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries |
| Pfizer |
| Biohaven Pharmaceuticals |
| Novartis |
| Lundbeck |
| Allergan |
| Others |
Value Network & Pricing Analysis
Cold-chain distribution technology upgrades for biologic CGRP antibodies simultaneously compress per-unit logistics costs and concentrate supply power among qualified 2-8°C carriers in Germany and the United States. This dual effect tightens margin capture at the distribution tier while amplifying price leverage for sponsors with captive manufacturing infrastructure.
Pricing Analysis
Service-bundling separates training-inclusive autoinjector kits from unbundled drug-only vials in reimbursement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks cold-chain certification depth and administration support inclusion. Price differentiation hinges on FDA breakthrough designation status and EMA MDR compliance tier. Cost compression in standard-tier injectables is intensifying because generic triptan substitution pressures Medicaid formulary placement. Medicaid programs exhibit highest price sensitivity; self-insured employer plans show lowest.
Supply Chain Analysis
Single-source vulnerability sits with qualified cold-chain logistics providers in Frankfurt and Cologne for EU distribution of temperature-sensitive biologics. Active pharmaceutical ingredient production concentrates in the US Midwest, North Carolina, and Kansai region of Japan. Mammalian cell culture media, single-use bioreactor bags, and purified CGRP antibody drug substance constitute critical input dependencies. Regulatory restriction risk looms through EMA MDR evidence burden delays for combination-device submissions. Distribution runs through specialty pharmacy consolidation at CVS Specialty and Accredo with outcomes-data requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturing-scale players as EMA MDR compliance costs and cardiovascular safety registry requirements force subscale sponsors toward partnership or exit. Regulatory burden asymmetry favors incumbents with existing infrastructure.
For Market Incumbents: Anticipate triptan generic erosion by accelerating nasal delivery platform diversification beyond injectable dependence. Deepen backward integration into antibody production campuses in the US Midwest to secure active ingredient supply against mammalian cell culture talent scarcity. Prioritize telehealth distribution partnerships to capture rural United States neurology desert volume before mid-cap competitors establish channel presence.
For New Entrants and Emerging Players: Begin with episodic migraine populations in Germany and Japan where needle aversion drives demand for non-injectable CGRP antagonist alternatives. Target nasal powder formulation white space with specialized pharmacokinetic expertise. Pursue go-to-market positioning through telehealth-enabled adherence monitoring to bypass specialist clinic access bottlenecks.
For Investors and Strategic Acquirers: Exit pathways concentrate in formulation-technology specialists with differentiated delivery platforms and regulatory-fast-track designations. Long-term viability favors sponsors with integrated manufacturing and demonstrated EMA MDR dossier assembly capability. Watch FDA guidance evolution on dual-primary endpoint trial designs as inflection signal for which therapeutic configurations achieve premium formulary placement.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough designation compresses Phase II-to-approval intervals by 12-18 months for combination candidates. |
| Manufacturing Scale-Up | Integrated antibody production campuses in the US Midwest secure biologic active ingredient supply chains against input concentration. |
| Pipeline Diversification | Nasal delivery platform development addresses needle-averse patient segments in Germany and Japan with faster onset profiles. |
| Strategic Partnership | Telehealth distribution alliances with CVS Specialty and Accredo satisfy outcomes-data-sharing formulary inclusion requirements. |
| Geographic Expansion | Rural United States neurology desert penetration via remote monitoring platforms captures primary-care-managed chronic migraine patients. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs across this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary database validation. Bottom-up patient-volume modeling and top-down therapeutic-class expenditure analysis enabled cross-verification.
Data-stream reconciliation across manufacturer-reported volume, payer claims databases, and distributor shipment records shaped the analytical framework. Segmentation dimensions spanned therapeutic configuration, delivery mode, care setting, and regional regulatory cluster across the analysis window. CAGRs derived from log-linear trend fitting to normalized expenditure trajectories with adjustment for IRA price negotiation exclusion effects and MHLW bundling incentive implementation.
Underlying measurement precision varies by segment; combination therapy and telehealth services carry tighter precision than emerging nasal delivery platforms. Forecasts reflect documented assumptions regarding regulatory pathway acceleration, cold-chain infrastructure expansion, and payer bundling adoption curves. Patent cliff timing, cardiovascular safety signal emergence, and biosimilar entry dynamics constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Oncology Adjuvants Market