
 Personalized Skin Care Products Market | 2026-2036
Personalized Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Skin Care Products Market Analytics
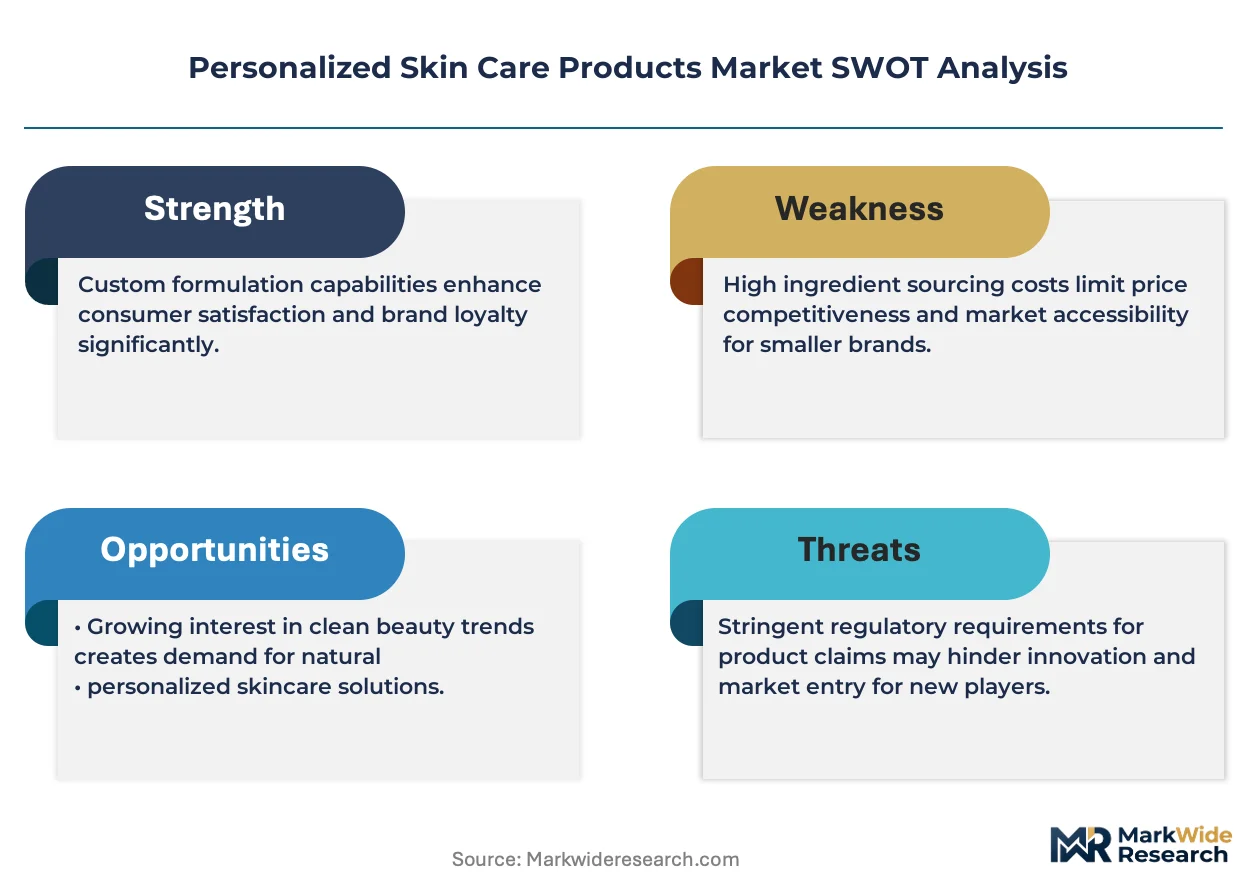
Fragmentation across digital-native consumer segments is repositioning how brands allocate R&D and marketing resources. L'Oréal leverages its ModiFace AI platform to sustain personalized recommendation engines across multiple markets. AmorePacific anchors its competitive stance through bio-fermentation technology leadership in customized essence formulations. Estée Lauder competes via its direct-to-consumer diagnostic tools that capture detailed skin microbiome profiles.
Personalized skin care products are cosmetic formulations engineered to individual skin profiles through biometric analysis, active ingredient calibration, and adaptive delivery systems, typically incorporating peptides, ceramides, or microbiome-targeting compounds synthesized via cold-process emulsification to preserve bioactivity. Their primary commercial purpose centers on delivering measurable dermatological outcomes superior to mass-market alternatives through precision matching of skin type, environmental exposure, and genetic predisposition. Serums command the deepest margin pools due to concentrated active loading and premium positioning, while online channels represent the fastest-growing distribution pathway as algorithmic skin quizzes convert browsing behavior into subscription revenue. Creams remain the volume anchor across mature demographics, whereas acne treatment applications show accelerating demand among younger consumers accessing tele-dermatology services.
The FDA's Modernization of Cosmetics Regulation Act (MoCRA) mandates adverse event reporting and facility registration, elevating compliance costs for smaller personalized formulators while creating barriers to market entry. The EU Cosmetics Regulation enforces strict ingredient safety assessments through the Scientific Committee on Consumer Safety, directly influencing which novel actives enter personalized product pipelines. China's NMPA requires animal-free testing alternatives and pre-market registration for imported cosmetics, reshaping how international brands localize customized offerings. Stakeholders must monitor evolving substantiation standards for AI-generated skin diagnoses as regulators scrutinize whether algorithmic recommendations constitute medical claims.
Market Dynamics
The personalized skin care products market is undergoing structural compression as algorithmic skin assessment tools displace traditional dermatologist consultations, forcing brands to recalibrate their customer acquisition costs and retention mechanics around data-driven subscription models rather than transactional retail.
Growth Catalysts
- AI-powered biometric analysis:Machine learning models trained on dermatological image databases enable real-time skin condition scoring, reducing formulation error rates and accelerating product-to-skin matching precision.
- MoCRA facility registration mandates:The FDA's Modernization of Cosmetics Regulation Act creates compliance infrastructure that legitimizes small-batch personalized formulators, expanding the addressable supplier base through standardized adverse event reporting protocols.
- Tele-dermatology integration:Remote diagnostic platforms in the United States and South Korea bridge the gap between clinical skin analysis and at-home product customization, converting medical-grade assessments into direct-to-consumer revenue streams.
Market Restraints
- Bioactive ingredient supply concentration:Peptide and ceramide precursor synthesis clusters in Chinese and South Korean biotech manufacturing hubs, exposing personalized formulators to input cost volatility and geopolitical supply disruptions.
- EU Scientific Committee on Consumer Safety review timelines:Novel active ingredient substantiation for personalized pipelines faces 18-24 month assessment windows, compressing product development cycles and elevating R&D burn rates.
- Microbiome testing standardization gaps:Inconsistent sampling protocols across diagnostic platforms create reproducibility failures, undermining consumer trust in algorithm-generated skin profiles and elevating return rates.
Strategic Opportunities
- Subscription-based tele-dermatology channels:Direct-to-consumer diagnostic tools bypass traditional retail markups, capturing recurring revenue through algorithmic skin quiz conversions and automated replenishment cycles.
- NMPA animal-free testing alternatives:China's National Medical Products Administration acceptance of non-animal safety substantiation methods opens pre-market registration pathways for international brands seeking localized customized offerings.
- Cold-process emulsification convergence with 3D printing:On-demand manufacturing technologies enable point-of-sale formulation, compressing inventory carrying costs and enabling hyper-localized active ingredient calibration.
Industry Challenges
- Computational dermatology talent scarcity:The intersection of machine learning and cosmetic chemistry requires hybrid skill sets that command premium compensation, constraining mid-tier brand R&D scaling.
- Legacy ERP integration friction:Established manufacturers face system architecture conflicts when embedding real-time skin data pipelines into batch-oriented production planning software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Skin Care Products Market |
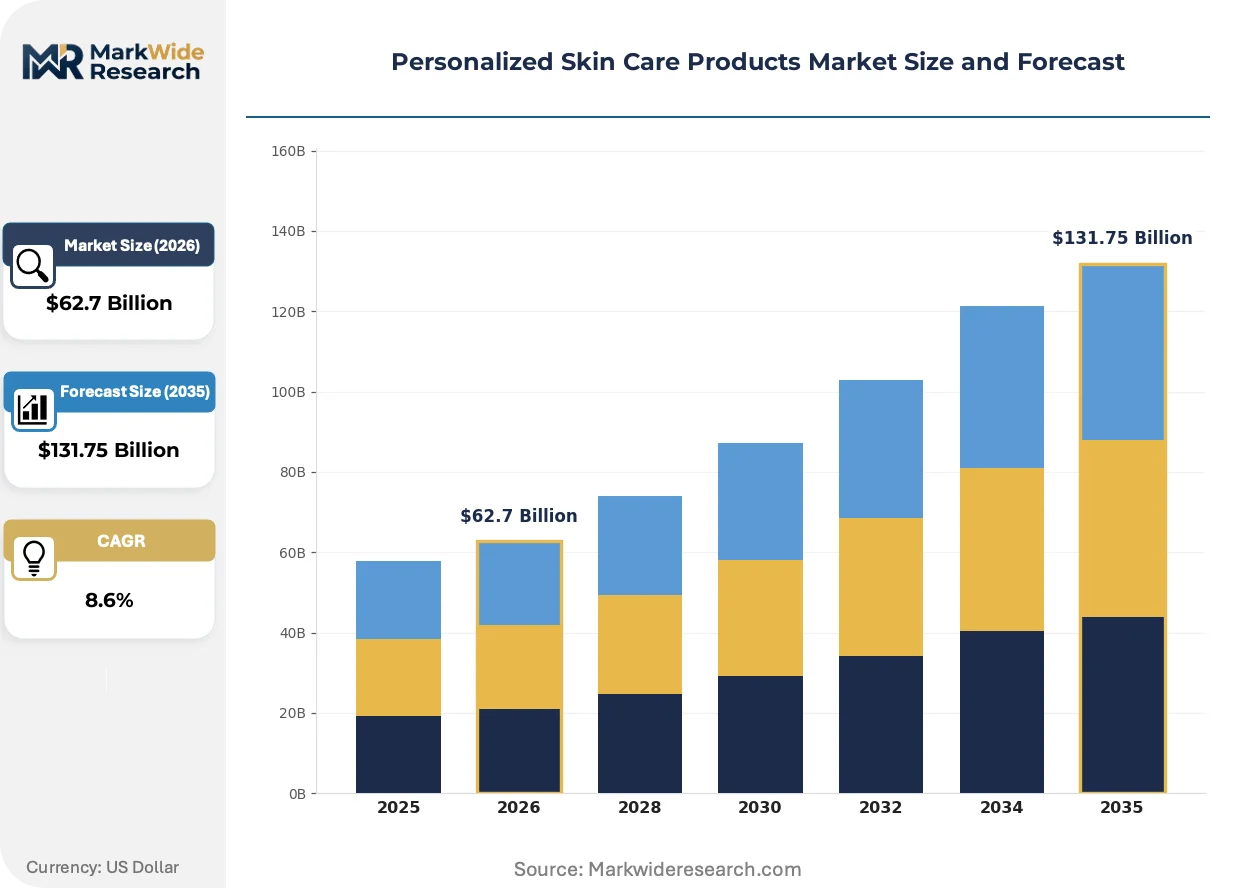
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $131.75 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Masks, Toners Skin Type: Oily, Dry, Combination, Sensitive Distribution Channel: Online, Specialty Stores, Pharmacies, Direct Sales Application: Anti-Aging, Hydration, Brightening, Acne Treatment |
| Companies Covered | Shiseido, Coty Inc., L'Oréal, AmorePacific, Unilever, Estée Lauder, Beiersdorf, Proven Skincare, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Skin Care Products Market Evolving Landscape
Biometric data capture is redefining competitive moats in personalized skin care, shifting value creation from ingredient marketing to diagnostic accuracy and algorithmic recommendation fidelity.
Microbiome-targeting peptide synthesis is expanding into acne treatment applications for Gen Z consumers accessing tele-dermatology services. Cold-process emulsification preserves bioactive integrity in customized serums, enabling higher active loading concentrations than heat-stabilized mass-market alternatives. The technology is expanding into at-home diagnostic devices that transmit skin barrier function data directly to formulation algorithms.
REACH substance restriction updates are forcing European personalized formulators to retire hydroquinone and certain paraben variants from customized whitening and anti-aging pipelines. The EU Cosmetics Regulation's expanded allergen labeling requirements elevate transparency costs but create differentiation opportunities for brands with clean ingredient substantiation. Small-batch manufacturers in Germany and France are responding by accelerating bio-fermentation technology investments to replace restricted synthetics.
Tele-dermatology subscription models are displacing department store counter consultations as the primary skin assessment channel for Millennial buyers in the United States. Algorithmic skin quizzes convert browsing behavior into recurring revenue through predictive replenishment cycles calibrated to individual product usage rates. This behavioral shift concentrates demand in digital-native brands with integrated diagnostic-formulation-fulfillment infrastructure rather than legacy retail-dependent competitors.
Personalized Skin Care Products Market Segmentation
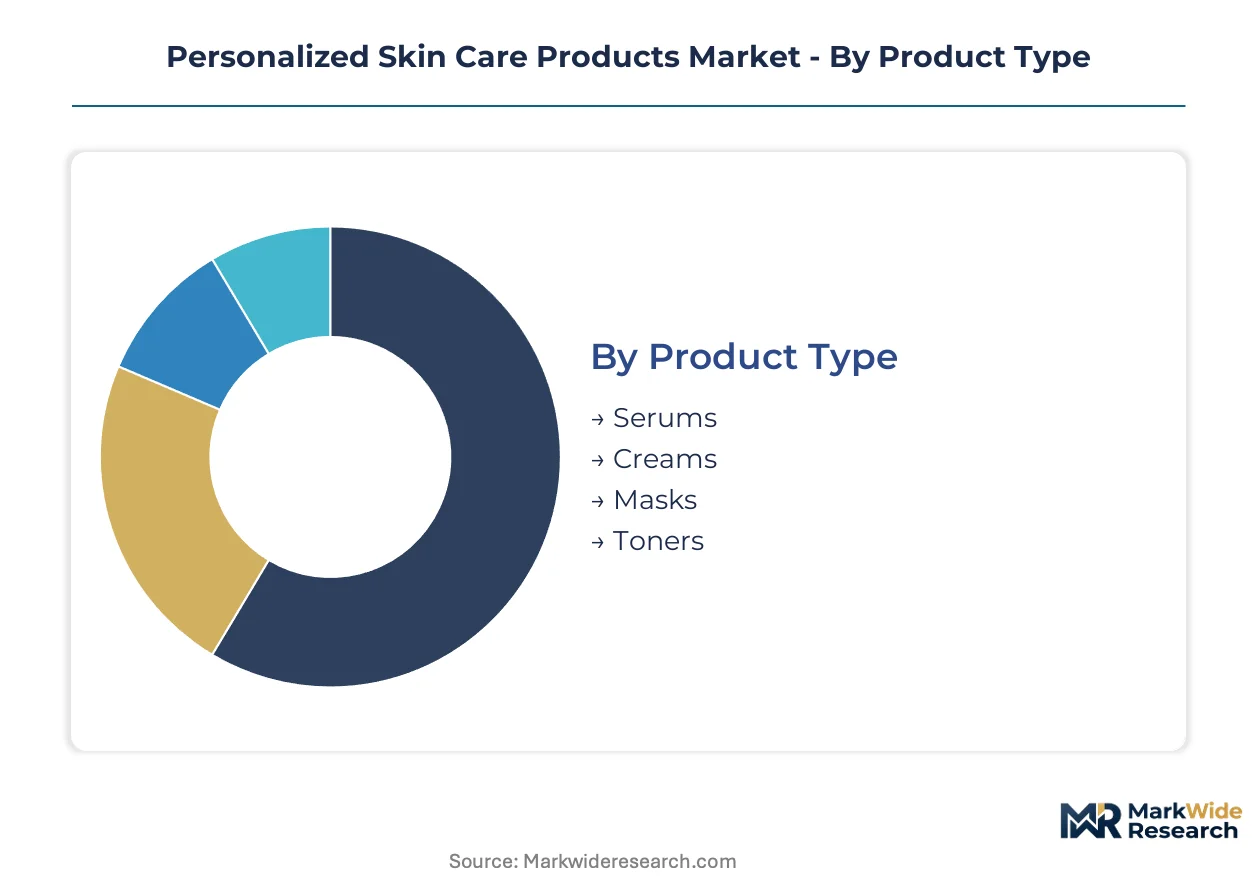
Personalized skin care segmentation determines regulatory pathways, manufacturing complexity, and margin architecture. Each dimension carries distinct certification burdens and supply chain requirements that shape competitive positioning.
Product Type:
MoCRA facility registration requirements scale with formulation complexity, with high-active serums triggering the most stringent FDA adverse event reporting protocols.
- Serums:Concentrated peptide and ceramide formulations manufactured via cold-process emulsification preserve bioactive integrity. Demand concentrates among Millennial subscribers to tele-dermatology platforms in the United States, where algorithmic skin quizzes drive automated replenishment cycles.
- Creams:Heat-stabilized emulsion bases support microbiome-targeting actives at lower concentrations than serums. Volume concentrates in mature demographics across Germany and France, where bio-fermentation technology investments replace restricted synthetics under REACH updates.
- Masks:Single-use delivery systems for intensive active loading, popular in South Korean subscription boxes.
- Toners:pH-balancing formulations with lower regulatory scrutiny, anchoring entry-level personalized routines.
Creams sit at the top of the volume ranking, with serums climbing the fastest.
Skin Type:
Diagnostic algorithm training data quality varies significantly across skin type categories, directly affecting formulation accuracy and return rates.
- Sensitive:Barrier-function-focused formulations with minimal allergen loads require EU Cosmetics Regulation expanded labeling compliance. Demand concentrates in urban Chinese markets, where NMPA animal-free testing alternatives accelerate pre-market registration for international brands.
- Oily:Sebum-regulating actives with microbiome-balancing peptides target Gen Z consumers accessing acne-focused tele-dermatology services in the United States and South Korea.
- Dry:Ceramide-heavy barrier repair formulations, standard in German small-batch manufacturing.
- Combination:Zone-specific active calibration, the most complex diagnostic challenge for AI platforms.
Oily skin formulations dominate current algorithmic quiz conversions, with sensitive skin applications expanding most quickly.
Distribution Channel:
Channel selection determines data capture depth and subscription mechanics, with online platforms enabling the richest biometric feedback loops.
- Online:Algorithmic skin quizzes convert browsing behavior into recurring revenue through predictive replenishment calibrated to individual usage rates. Demand concentrates in digital-native Millennial and Gen Z segments across the United States and China, where integrated diagnostic-formulation-fulfillment infrastructure displaces legacy retail.
- Specialty Stores:In-person biometric scanning combines with immediate fulfillment, anchoring South Korean and Japanese urban premium positioning.
- Pharmacies:Clinical credibility supports microbiome testing standardization, particularly in French and German markets.
- Direct Sales:Consultant-led skin assessment persists in mature demographic strongholds.
Online channels command the steepest expansion trajectory, with specialty stores retaining premium price realization.
Application:
Application focus determines active ingredient substantiation requirements, with acne treatment facing the most stringent clinical validation demands.
- Acne Treatment:Microbiome-targeting peptide synthesis requires EU Scientific Committee on Consumer Safety review timelines of 18-24 months for novel actives. Demand concentrates among Gen Z tele-dermatology subscribers in the United States and South Korea, where remote diagnostic platforms bridge clinical analysis and at-home customization.
- Anti-Aging:Retinoid and peptide combinations face REACH substance restrictions on hydroquinone variants in European pipelines.
- Hydration:Hyaluronic acid and ceramide blends, the entry point for personalized subscription adoption.
- Brightening:Niacinamide and vitamin C formulations, restricted by China's NMPA pre-market registration for imported actives.
Hydration applications anchor subscription volume, with acne treatment gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates tele-dermatology subscription volume while China dominates bioactive ingredient manufacturing infrastructure, creating divergent competitive dynamics across the two largest demand centers.
United States
Millennial and Gen Z consumers drive algorithmic skin quiz adoption through integrated diagnostic-formulation-fulfillment platforms. FDA's MoCRA mandates facility registration and adverse event reporting, elevating compliance costs for small-batch personalized formulators. New York and California anchor tele-dermatology service clusters where remote diagnostic platforms convert medical-grade assessments into direct-to-consumer revenue streams.
China
Urban consumers in Shanghai and Beijing access international customized offerings through cross-border digital commerce channels. NMPA requires animal-free testing alternatives and pre-market registration for imported cosmetics, reshaping localization strategies for foreign brands. The Yangtze River Delta concentrates peptide and ceramide precursor synthesis capacity, exposing personalized formulators to input cost volatility.
South Korea
Gen Z demand concentrates in acne-focused tele-dermatology applications with microbiome-targeting peptide formulations. MFDS regulates novel active ingredient safety assessments, influencing which customized actives enter domestic pipelines. Seoul anchors bio-fermentation technology leadership in customized essence manufacturing.
Germany
Mature demographics sustain cream volume through small-batch manufacturers investing in bio-fermentation technology. REACH substance restrictions force retirement of hydroquinone and certain paraben variants from customized whitening pipelines. Bavaria and Baden-Württemberg concentrate clean ingredient substantiation capabilities.
France
Pharmacy distribution channels support microbiome testing standardization for clinical credibility in personalized routines. EU Cosmetics Regulation expanded allergen labeling requirements elevate transparency costs for formulators. Paris anchors premium positioning for specialty store biometric scanning with immediate fulfillment.
Personalized Skin Care Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across algorithmic skin assessment and customized formulation infrastructure. The market exhibits tiered consolidation with global beauty conglomerates controlling diagnostic platform IP while mid-tier brands capture subscription revenue through specialized tele-dermatology channels. Three archetypes dominate: vertically integrated conglomerates with AI platform assets, digital-native specialists with direct-to-consumer diagnostic tools, and biotech-forward manufacturers with fermentation-based active synthesis. Competitive moves concentrate on strategic partnerships between diagnostic platforms and formulation labs, plus geographic licensing of algorithmic recommendation engines.
Within the conglomerate tier, L'Oréal and Estée Lauder occupy positions spanning multiple continents through proprietary AI diagnostic assets and direct-to-consumer infrastructure. AmorePacific exemplifies the biotech-forward archetype with concentrated manufacturing in East Asian fermentation clusters. Shiseido anchors a hybrid position bridging Japanese precision manufacturing with expanding tele-dermatology subscription models.
| Leading Market Players |
|---|
| Shiseido |
| Coty Inc. |
| L'Oréal |
| AmorePacific |
| Unilever |
| Estée Lauder |
| Beiersdorf |
| Proven Skincare |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
A sharp bifurcation between algorithmic diagnostic platforms and commodity formulation services manifests in divergent margin structures and supplier qualification requirements across the personalized skin care value chain. Premium pricing accrues to integrated diagnostic-formulation platforms that capture recurring subscription revenue, while small-batch manufacturers compete on input cost efficiency and regulatory compliance speed.
Pricing Analysis
Capacity additions in Chinese biotech manufacturing hubs are reshaping price floors for peptide and ceramide precursors, compressing margins for mid-tier formulators dependent on spot-market sourcing. Pricing stratifies across premium, standard, and economy tiers based on active ingredient concentration and algorithmic recommendation fidelity. Pricing pressure stems from EU Scientific Committee on Consumer Safety review timelines that extend R&D burn rates for novel actives. Gen Z tele-dermatology subscribers demonstrate lowest price sensitivity due to medical-grade positioning, while mature cream buyers in Germany exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from FDA MoCRA-registered facilities mandate multi-supplier qualification for adverse event reporting compliance, elevating procurement complexity. Geographic supply concentration centers on China, South Korea, and the United States for peptide synthesis, bio-fermentation capacity, and algorithmic platform development. Raw material dependencies include cold-process emulsification equipment, microbiome testing consumables, and AI training data pipelines. Single-source vulnerability concentrates in Yangtze River Delta biotech clusters exposed to geopolitical disruption. Distribution runs through direct-to-consumer subscription channels with predictive replenishment algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personalized skin care market functions as a regulatory compounder where FDA MoCRA facility registration mandates and EU Cosmetics Regulation substantiation requirements continuously elevate compliance barriers that favor scaled incumbents with captive compliance infrastructure.
For Market Incumbents: Anchor diagnostic platform IP through proprietary algorithmic recommendation engines that convert skin microbiome data into formulation instructions. Deepen backward integration into bio-fermentation capacity in South Korean manufacturing clusters to secure peptide supply against Chinese input cost volatility. Defend against digital-native entrants by controlling tele-dermatology subscription channels that capture recurring revenue. For New Entrants and Emerging Players: Enter via NMPA animal-free testing compliance services for international brands seeking China market access, the most penetrable regulatory white-space. Target acne treatment applications for Gen Z consumers in South Korea where microbiome-targeting peptide demand outpaces qualified supplier capacity. Launch through specialty store biometric scanning partnerships in Japanese urban centers to bypass incumbent-controlled online channels. For Investors and Strategic Acquirers: Consolidation pressure builds where computational dermatology talent scarcity constrains mid-tier brand R&D scaling. Long-term viability favors vertically integrated platforms spanning diagnostic AI, formulation manufacturing, and direct-to-consumer fulfillment. Acquisition targets include biotech-forward manufacturers with fermentation-based active synthesis capabilities in East Asian clusters. Monitor EU Scientific Committee on Consumer Safety review timeline compression as inflection signal for novel active pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Process Emulsification Scale-Up | Preserves bioactive integrity in serums for Millennial tele-dermatology subscribers. |
| AI Diagnostic Platform Licensing | Enables geographic expansion of algorithmic skin quiz conversion engines. |
| MoCRA Facility Registration Investment | Legitimizes small-batch formulators through standardized adverse event protocols. |
| Tele-Dermatology Channel Integration | Bridges clinical skin analysis with at-home customization revenue streams. |
| Bio-Fermentation Technology Acquisition | Secures peptide synthesis capacity against REACH substance restriction impacts. |
Research Methodology
Multiple input streams — primary interviews with formulation chemists, regulatory affairs specialists, and tele-dermatology platform operators; secondary validation through FDA MoCRA facility registration databases, EU Cosmetics Regulation submission records, and NMPA pre-market registration filings; plus trade data from Chinese customs and South Korean MFDS disclosures — were reconciled through bottom-up and top-down triangulation. Conversations with diagnostic platform engineers and subscription commerce executives informed algorithmic recommendation engine economics. Cross-referencing of adverse event reporting patterns against active ingredient sourcing records validated supply concentration assumptions.
Historical subscription revenue trajectories were cross-referenced against panel input from tele-dermatology service providers to calibrate algorithmic quiz conversion assumptions across the analysis window. Segmentation dimensions modeled include product type concentration, skin type diagnostic complexity, distribution channel data capture depth, and application-specific substantiation requirements. CAGRs were derived from reconciling biometric data capture adoption curves with bioactive ingredient manufacturing capacity expansion. Cold-process emulsification technology penetration and microbiome testing protocol standardization served as industry-specific forecast inputs.
Inputs from FDA adverse event reporting systems and EU Scientific Committee on Consumer Safety review databases were available through the study window; gaps in real-time algorithmic diagnostic accuracy validation introduce uncertainty bands around subscription retention assumptions. Forecasts reflect documented regulatory milestone timelines and biotech manufacturing capacity expansion announcements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Cosmetic Skin Care Market
Skincare
Peel Off Face Mask Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Vitamin C Serum Market
Skincare
Preoperative Skin Preparation Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Retinoids Market
Skincare
Natural Skin Care Products Market
Skincare
Skincare Serums Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Skin Bioactive Market
Skincare
Sensitive Skin Care Products Market
Skincare
Pseudo Collagen Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
DNA-Based Skin Care Products Market