
 Global Active Wound Care Market | 2026-2036
Global Active Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Active Wound Care Market Foresight
Specialized tissue-engineering expertise is collapsing across wound care manufacturing hubs, constraining production scale-up for advanced biologic dressings. Smith & Nephew leverages its vertically integrated cell-therapy infrastructure to sustain leadership in skin-substitute supply chains. Mölnlycke Health Care AB anchors Nordic production capacity for silicone-based interactive dressings. Organogenesis Inc. specializes in living-cell matrices that dominate hospital outpatient protocols for diabetic foot ulcers.
Active wound care encompasses biologically interactive dressings and engineered skin substitutes designed to modulate the wound microenvironment through controlled moisture balance, protease regulation, and growth-factor delivery. These products typically incorporate collagen matrices, amniotic-derived extracellular vesicles, or antimicrobial silver complexes manufactured under ISO 13485 quality systems for chronic and acute wound management. Collagen-based interactive dressings command the deepest margin pools due to raw-material sourcing constraints and specialized processing requirements. Foam segments lead volume throughput across hospital procurement channels, while alginate formulations compete in exuding wound applications where ionic exchange properties accelerate hemostasis.
FDA's regenerative medicine advanced therapy designation compresses clinical-trial timelines for biologic wound products, while EMA's MDR framework tightens conformity-assessment burdens for European market access. Japan's PMDA accelerates conditional approvals for combination-device biologics under its Sakigake designation pathway. Stakeholders must monitor evolving reimbursement coding for cellular and tissue-based products across Medicare, NHS England, and Germany's G-BA to align portfolio investments with payor-validated clinical endpoints.
Market Dynamics
Specialized tissue-engineering expertise is collapsing across wound care manufacturing hubs, constraining production scale-up for advanced biologic dressings and forcing buyers into multi-year supply agreements with vertically integrated producers.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy Designation:The FDA's RMAT pathway compresses clinical-trial timelines for biologic wound products, accelerating commercialization of living-cell matrices and engineered skin substitutes.
- Hospital Outpatient Protocol Expansion:Ambulatory surgical centers in the United States are adopting advanced wound biologics for diabetic foot ulcer management, driven by Medicare reimbursement coding updates.
- Aging Demographics with Chronic Wounds:Japan's super-aged population generates sustained hospital demand for interactive dressings that modulate protease activity in non-healing wounds.
Market Restraints
- Collagen Raw-Material Sourcing Constraints:Bovine and porcine collagen supply concentrates in specific geographic processing clusters, exposing manufacturers to input cost volatility and batch-to-batch variability.
- EMA MDR Conformity-Assessment Burdens:The European Union's Medical Device Regulation tightens clinical-evidence requirements for tissue-based products, extending European market-access timelines.
- Silver Complex Substitution Pressure:Antimicrobial foam dressings face displacement from iodine-based alternatives in exuding wound applications where ionic exchange properties prove comparable.
Strategic Opportunities
- Underpenetrated German Outpatient Sector:Germany's G-BA reimbursement framework increasingly validates advanced wound biologics, opening private-practice channels previously dominated by conventional dressings.
- Combination-Device Convergence:Integration of electroactive polymers with amniotic-derived extracellular vesicles creates next-generation interactive dressings for bioelectric wound healing.
- Japan Sakigake Conditional Approval Pathway:PMDA's accelerated review mechanism for innovative medical devices reduces time-to-market for novel biologic-device combinations.
Industry Challenges
- ISO 13485 Quality-System Talent Scarcity:Living-cell matrix production requires specialized quality-assurance personnel trained in cell-therapy manufacturing standards, creating recruitment bottlenecks.
- Cell-Viability Certification Timelines:Shelf-life validation for engineered skin substitutes demands extended stability testing under controlled-temperature logistics, compressing working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Active Wound Care Market |
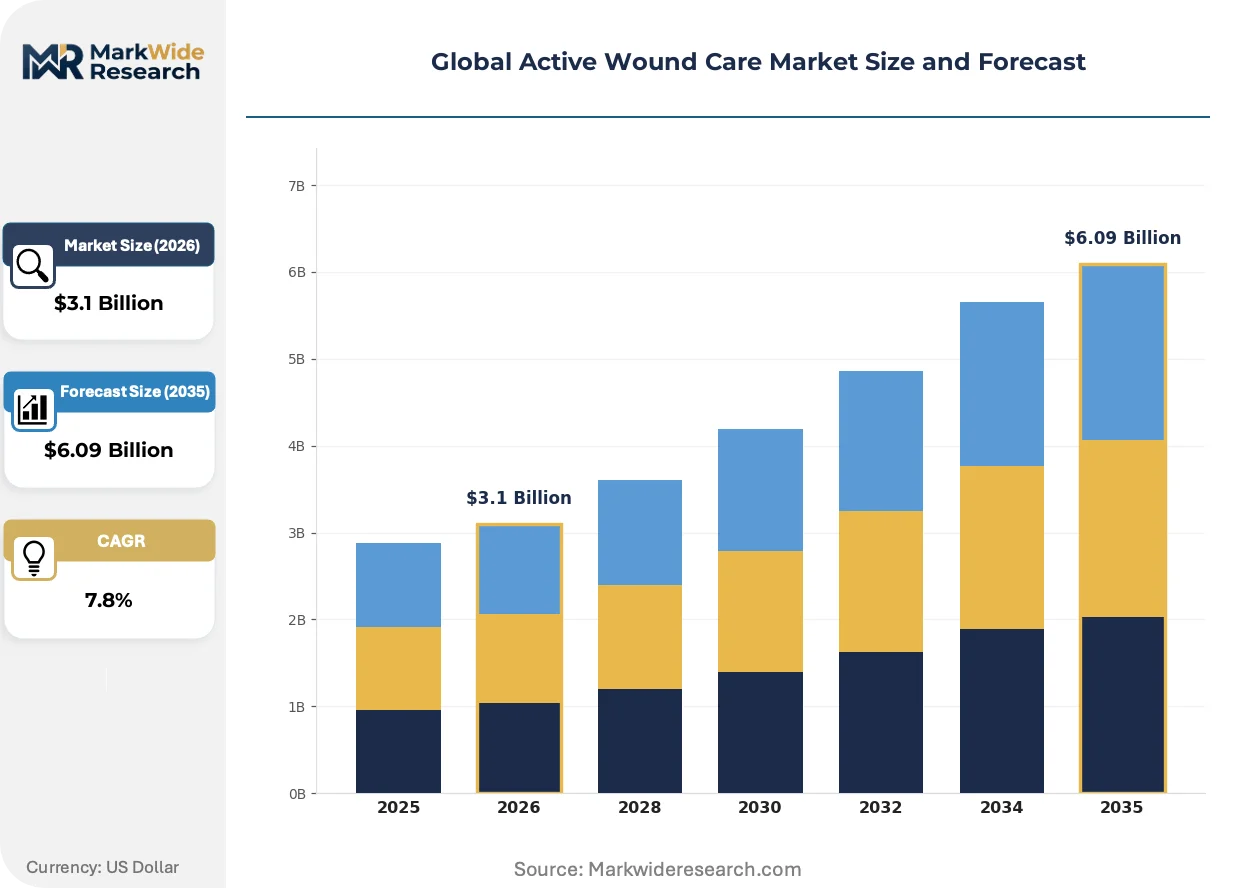
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid, Alginate, Foam, Film, Silicone, Collagen Wound Type: Pressure Ulcers, Diabetic Ulcers, Surgical Wounds, Burns, Venous Ulcers, Traumatic Wounds End User: Hospitals, Clinics, Ambulatory Care Centers, Home Healthcare, Rehabilitation Centers, Specialty Care Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Medical Supply Stores, Direct Sales, Third-Party Distributors |
| Companies Covered | Smith & Nephew, ConvaTec Inc., Mölnlycke Health Care AB, MiMedx, Integra LifeSciences, Organogenesis Inc., 3M, Coloplast Corp, Tissue Regenix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Active Wound Care Market Shifts & Advancements
Biologically interactive dressing technologies are fragmenting into two distinct performance tiers, with premium living-cell matrices separating from advanced synthetic platforms in both clinical positioning and procurement channels.
Amniotic-derived extracellular vesicle technology is bifurcating the advanced wound biologics landscape. These nanoscale signaling particles regulate inflammation and angiogenesis in chronic wounds. Hospital outpatient departments in the United States are adopting them at accelerated pace for diabetic foot ulcer protocols. The technology is bifurcating margin pools, with vesicle-based products commanding price premiums over conventional growth-factor dressings while synthetic alternatives compete on volume throughput.
REACH regulation in the European Union is tightening substance restrictions on antimicrobial silver complexes used in interactive dressings. Industrial consequence includes reformulation costs and supply-chain requalification for manufacturers serving European hospitals. Wound care producers with European market exposure are responding by accelerating iodine-based and polyhexamethylene biguanide alternatives through their R&D pipelines.
Hospital procurement departments are consolidating vendor panels for advanced wound biologics, shifting from multi-source purchasing to single-source agreements with vertically integrated suppliers. This concentration disrupts traditional distribution channels where regional medical-device distributors previously held relationships with wound care nurses. The behavioral shift is most visible in United States integrated delivery networks, where standardization committees now mandate specific skin-substitute brands across entire hospital systems.
Global Active Wound Care Market Segmentation
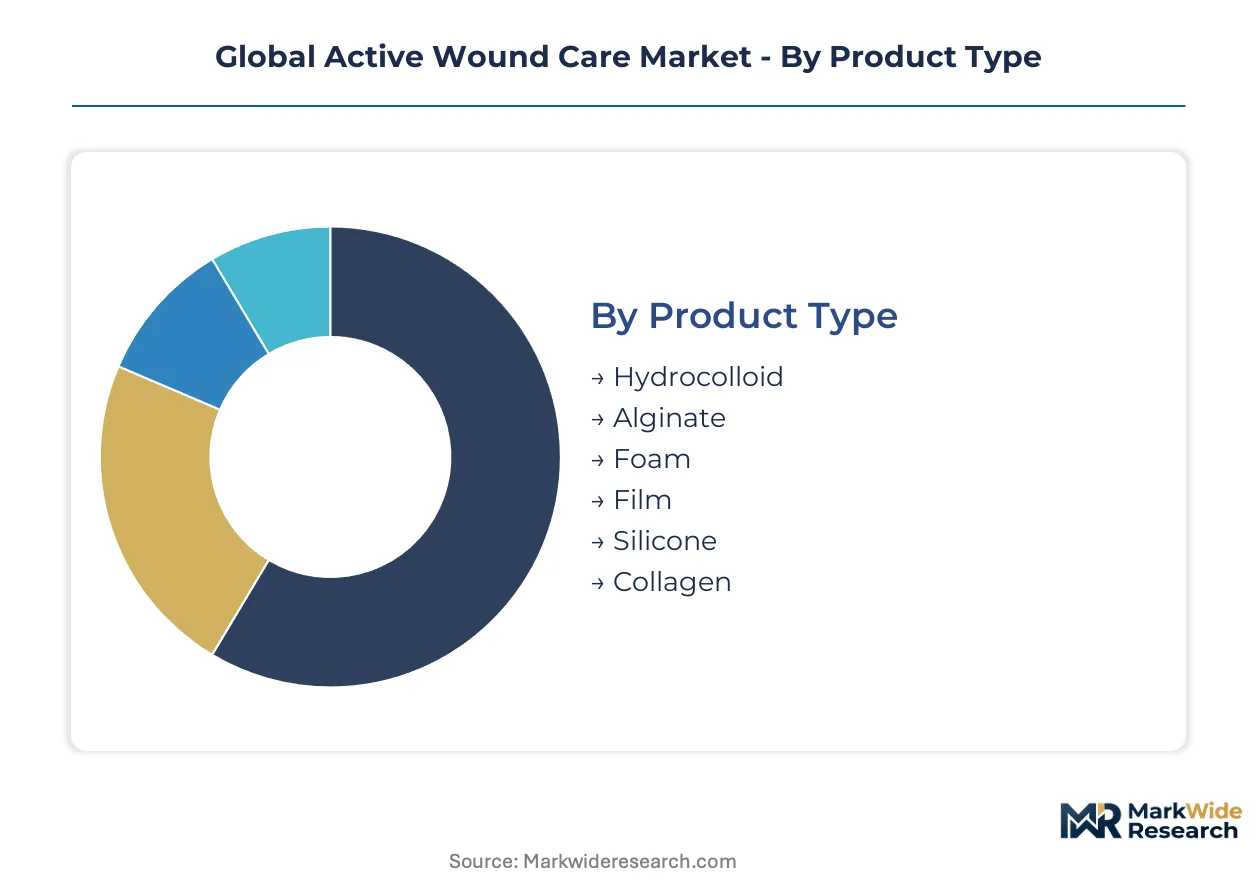
Active wound care segmentation reveals divergent margin structures across material technologies and care settings. Product-type differentiation separates premium biologic matrices from high-volume synthetic platforms. End-user concentration in hospital outpatient departments reshapes procurement patterns for advanced dressings.
Product Type:
Collagen and silicone formulations command the deepest margin pools due to specialized raw-material sourcing and manufacturing complexity.
- Collagen:Bovine and porcine-derived matrices modulate protease activity and deliver growth-factor signaling in chronic wound beds. Hospital outpatient protocols in the United States prioritize collagen for diabetic foot ulcer management where Medicare reimbursement validates clinical endpoints.
- Silicone:Soft-adhesion polymer layers enable atraumatic removal from fragile periwound skin while maintaining moisture balance. German hospital procurement channels favor silicone for pressure ulcer prevention in aging care facilities.
- Alginate:Ionic-exchange seaweed fibers accelerate hemostasis in exuding wound applications.
- Foam:Polyurethane absorbent cores dominate volume throughput across acute care settings.
- Hydrocolloid:Gel-forming particles seal partial-thickness wounds in ambulatory environments.
- Film:Semi-permeable membranes protect superficial wounds with minimal exudate.
Collagen holds installed capacity. Silicone is rotating up the share rankings.
Wound Type:
Volume concentration clusters around chronic ulcer categories where reimbursement frameworks favor advanced biologics over conventional dressings.
- Diabetic Ulcers:Lower-extremity lesions in diabetic patients drive demand for living-cell matrices and amniotic-derived extracellular vesicles. Japan's super-aged population generates sustained hospital demand for interactive dressings targeting neuropathic wound healing.
- Pressure Ulcers:Immobility-related tissue damage in long-term care facilities requires moisture-balancing dressings with antimicrobial protection. EMA's MDR framework tightens clinical-evidence requirements for pressure ulcer biologics entering European markets.
- Surgical Wounds:Post-operative incision management favors antimicrobial foam and film combinations.
- Venous Ulcers:Chronic venous insufficiency lesions in lower extremities absorb compression-therapy adjunct dressings.
- Burns:Thermal and chemical injuries demand silver-complex antimicrobial coverage in specialized burn centers.
- Traumatic Wounds:Acute mechanical injuries in emergency departments prioritize rapid hemostasis and infection control.
Diabetic ulcers anchor revenue concentration. Pressure ulcers are climbing the fastest as long-term care expands.
End User:
Procurement authority is consolidating toward integrated delivery networks that standardize advanced biologic formularies across multiple sites.
- Hospitals:Inpatient and outpatient departments command the largest procurement volumes for engineered skin substitutes and living-cell matrices. FDA's RMAT designation accelerates hospital adoption of regenerative biologics through compressed trial timelines.
- Ambulatory Care Centers:Freestanding surgical facilities in the United States are adopting advanced wound biologics for same-day diabetic foot ulcer procedures under updated Medicare coding.
- Clinics:Physician office laboratories in Germany's G-BA reimbursement framework increasingly validate advanced wound biologics.
- Home Healthcare:Skilled nursing visits deploy simplified interactive dressings for chronic wound monitoring.
- Specialty Care Centers:Wound care clinics concentrate expertise in debridement and biologic application.
- Rehabilitation Centers:Post-acute facilities manage pressure ulcer prevention in mobility-limited patients.
Hospitals hold installed capacity. Ambulatory care centers are gaining share fastest.
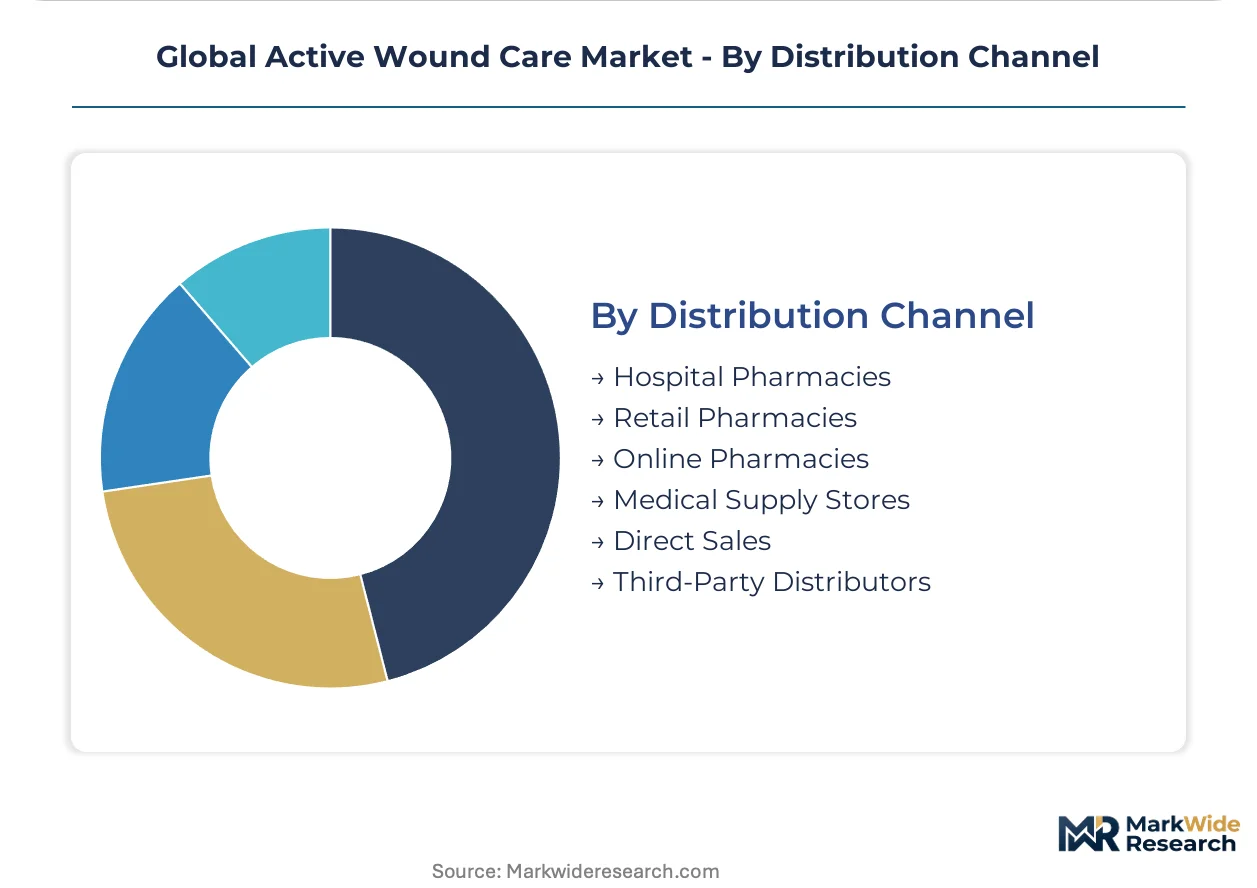
Distribution Channel:
Channel economics favor direct relationships with vertically integrated manufacturers as hospital vendor panels consolidate.
- Hospital Pharmacies:Captive dispensing operations within integrated delivery networks control formulary access for advanced biologics. United States health systems increasingly mandate specific skin-substitute brands across entire hospital networks.
- Direct Sales:Manufacturer field forces bypass traditional distributors to secure multi-year supply agreements with wound care manufacturing hubs facing tissue-engineering expertise shortages.
- Third-Party Distributors:Regional medical-device distributors retain relevance in specialty care center and clinic channels.
- Retail Pharmacies:Community drugstores serve home healthcare and minor wound care segments.
- Online Pharmacies:Digital platforms expand access to standard interactive dressings for consumer-directed purchasing.
- Medical Supply Stores:Durable medical equipment dealers support long-term care and rehabilitation facility stocking.
Hospital pharmacies hold installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's RMAT pathway anchors United States demand for regenerative wound biologics, while EMA's MDR framework and Japan's PMDA Sakigake mechanism shape competitive positioning across their respective jurisdictions. Hospital procurement consolidation and reimbursement coding updates drive divergence in regional adoption curves.
United States
Medicare reimbursement coding for cellular and tissue-based products accelerates hospital outpatient adoption of living-cell matrices. FDA's regenerative medicine advanced therapy designation compresses clinical-trial timelines for biologic wound products. Boston and Research Triangle Park clusters concentrate tissue-engineering expertise for engineered skin substitute manufacturing.
Germany
Germany's G-BA reimbursement framework validates advanced wound biologics for private-practice channels previously dominated by conventional dressings. EMA's MDR conformity-assessment requirements tighten clinical-evidence standards for tissue-based products entering European markets. North Rhine-Westphalia anchors Nordic production capacity for silicone-based interactive dressings through vertically integrated manufacturing hubs.
Japan
Japan's super-aged population generates sustained hospital demand for interactive dressings modulating protease activity in non-healing wounds. PMDA's Sakigake designation pathway accelerates conditional approvals for combination-device biologics. Kanto region medical centers concentrate expertise in diabetic foot ulcer protocols using amniotic-derived extracellular vesicles.
United Kingdom
NHS England reimbursement coding evolution shapes portfolio investments for advanced wound biologics targeting chronic ulcer management. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR standards while enabling faster national approval pathways. London and Southeast England clusters host specialized wound care clinics driving adoption of collagen-based interactive dressings.
India
CDSCO regulatory pathways for medical devices and biologics attract contract manufacturing investments from global wound care producers. India's pharmaceutical manufacturing infrastructure supports cost-competitive production of antimicrobial foam and alginate dressings. Maharashtra and Gujarat industrial corridors concentrate sterile dressing manufacturing capacity serving domestic hospital procurement and export markets.
Global Active Wound Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the active wound care market. Vertically integrated cell-therapy specialists command premium positioning in living-cell matrices, while diversified medical-device conglomerates leverage scale economies in synthetic interactive dressings. Three archetypes dominate: regenerative biologic specialists, polymer chemistry platform players, and wound care focused pure-plays. Competitive moves concentrate on backward integration into collagen raw-material sourcing and multi-year supply agreements with hospital integrated delivery networks.
Among vertically integrated regenerative specialists, Smith & Nephew, Organogenesis Inc., and MiMedx exemplify archetypes capturing value through captive cell-therapy infrastructure. These entities occupy positions where tissue-engineering expertise scarcity creates defensive moats against synthetic-platform competitors. Diversified conglomerates including 3M and Coloplast Corp sit within scale-driven tiers where polymer chemistry capabilities translate across multiple medical-device categories. The competitive terrain rewards players controlling both biologic manufacturing quality systems and direct hospital procurement relationships.
| Leading Market Players |
|---|
| Smith & Nephew |
| ConvaTec Inc. |
| Mölnlycke Health Care AB |
| MiMedx |
| Integra LifeSciences |
| Organogenesis Inc. |
| 3M |
| Coloplast Corp |
| Tissue Regenix |
| Others |
Supply & Pricing Matrix
Cell-therapy manufacturing scale economies in United States and German production hubs concentrate supply among vertically integrated producers, establishing price floors for living-cell matrices while synthetic dressing platforms compete on volume throughput.
Pricing Analysis
United States hospital procurement channels command price premiums over German outpatient and Indian contract manufacturing markets. Three-tier pricing structure across premium, standard, and economy levels separates living-cell matrices from advanced synthetics from commodity foam dressings. Price differentiation hinges on ISO 13485 certification tier and captive cell-therapy infrastructure ownership. Cost compression in synthetic segments is intensifying because iodine-based alternatives displace silver complexes in exuding wound applications. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with multi-year supply agreements show lowest.
Supply Chain Analysis
Bovine collagen processing clusters in Midwest United States and North Rhine-Westphalia create geographic chokepoints for premium matrix production. Manufacturing draws from porcine dermal tissue, amniotic membrane sourcing networks, and electroactive polymer feedstocks. Single-source vulnerability concentrates in living-cell matrix producers with ISO 13485 quality-system talent scarcity. Distribution runs through hospital pharmacy captive dispensing and direct manufacturer field forces, bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent biologic dressing manufacturers face substitution defense against synthetic-platform competitors and iodine-based antimicrobial alternatives eroding silver-complex market share.
For Market Incumbents: Fortify backward integration into bovine and porcine collagen raw-material sourcing to secure batch-to-batch consistency against input cost volatility. Expand ISO 13485-certified cell-therapy capacity in United States manufacturing clusters to defend against synthetic-platform price competition. Lock multi-year supply agreements with integrated delivery networks before procurement consolidation completes. For New Entrants and Emerging Players: Differentiate on amniotic-derived extracellular vesicle technology for diabetic foot ulcer protocols where Medicare reimbursement validates clinical endpoints. Target Germany's G-BA-validated private-practice outpatient channels previously dominated by conventional dressings. Pursue PMDA Sakigake conditional approval pathway for combination-device biologics in Japan's super-aged hospital market. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated regenerative specialists with captive cell-therapy infrastructure over diversified polymer chemistry conglomerates. Five-to-ten year viability hinges on reimbursement coding alignment with payor-validated clinical endpoints. Monitor FDA RMAT designation grants as inflection indicator for biologic product commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collagen Sourcing | Captive raw-material supply secures margin pools against bovine processing cluster concentration. |
| ISO 13485 Quality System Certification | Cell-therapy manufacturing standards create recruitment moats and regulatory compliance barriers. |
| Hospital System Partnership Agreements | Direct procurement relationships with integrated delivery networks displace traditional distributor channels. |
| FDA RMAT Designation Pursuit | Compressed clinical-trial timelines accelerate living-cell matrix commercialization for chronic wounds. |
| PMDA Sakigake Pathway Application | Conditional approval mechanism reduces time-to-market for combination-device biologics in Japan. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across wound care manufacturing, hospital procurement, and regulatory affairs domains. Primary interviews captured perspectives from biomedical engineers in hospital purchasing committees, GPO contracts managers, cell-therapy manufacturing quality leads, and wound care clinic clinicians. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement coding updates, and hospital procurement database trends. Bottom-up product-type volume estimates triangulated against top-down regional demand projections.
Across the analysis window, forecasts modeled product type segmentation by collagen, silicone, alginate, foam, hydrocolloid, and film platforms; wound type by diabetic ulcer, pressure ulcer, surgical wound, venous ulcer, burn, and traumatic injury categories; end user by hospital, ambulatory care center, clinic, home healthcare, specialty care center, and rehabilitation center channels; and distribution channel by hospital pharmacy, direct sales, third-party distributor, retail pharmacy, online pharmacy, and medical supply store pathways. CAGRs derived from historical volume trajectories, reimbursement policy elasticity estimates, and demographic chronic wound prevalence modeling. Forecast inputs incorporated ISO 13485 quality-system talent availability and cell-viability certification timeline constraints.
Forecasts assume regulatory continuity in FDA RMAT, EMA MDR, and PMDA Sakigake frameworks; material policy shifts would require re-modeling commercialization timeline assumptions. Practitioners should keep alternative scenarios live as reimbursement coding evolution and antimicrobial substance restriction trajectories unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Pressure Ulcer Treatment Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Wound Evacuators Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Wound Management Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Philippines Wound Care Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Global Digital Wound Measurement Devices Market