
 Australia Wound Care Management Devices Market | 2026-2036
Australia Wound Care Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Wound Care Management Devices Market Outlook
Australian wound dressing manufacturing is decoupling from European supply chains as domestic converters expand hydrocolloid and foam production capacity. Smith & Nephew PLC leverages its Sydney distribution hub to sustain rapid hospital fulfillment across southeastern states. Mölnlycke Health Care AB anchors its antimicrobial portfolio through direct contracts with major public health networks. Coloplast AS specializes in stoma and advanced wound interfaces, competing on clinician training programs rather than price alone.
Wound care management devices encompass dressings, bandages, sutures, and antiseptics engineered to maintain moist healing environments, manage exudate, and prevent infection across acute, chronic, surgical, and burn indications. Hydrocolloid formulations typically comprise carboxymethyl cellulose, gelatin, and pectin in a polyurethane matrix, forming a cohesive gel upon contact with wound fluid to facilitate autolytic debridement. Dressings lead product type revenue due to recurrent hospital consumption and home care transition protocols, while chronic wound applications expand fastest as diabetes-related foot ulcer incidence rises. Hospitals dominate end user spend through centralized procurement, though home care segments gain traction via remote monitoring integration.
TGA's medical device framework mandates clinical evidence standards for Class IIa and IIb wound products, directly shaping manufacturer registration timelines and post-market surveillance obligations. The Therapeutic Goods Act interfaces with ISO 13485 quality management requirements to determine market access pathways for imported and domestically produced devices. Stakeholders must monitor TGA's anticipated reclassification of antimicrobial-impregnated dressings, which would trigger additional clinical trial obligations and reshape competitive positioning for suppliers lacking local regulatory expertise.
Market Dynamics
Hospital procurement centralization across New South Wales and Victoria is compressing vendor margins while elevating compliance requirements under TGA's reclassified device framework. This structural shift favors domestic converters with established regulatory pathways over import-dependent distributors.
Growth Catalysts
- Diabetes-related foot ulcer incidence:Rising chronic wound caseloads in metropolitan tertiary centers are expanding recurring demand for advanced hydrocolloid and foam dressing protocols.
- TGA's updated medical device framework:Accelerated local compliance timelines are filtering out low-evidence suppliers, consolidating market access for clinically validated domestic manufacturers.
- Remote monitoring integration:Home care transition protocols incorporating digital wound assessment tools are extending device utilization beyond hospital discharge.
Market Restraints
- Carboxymethyl cellulose supply concentration:Raw material sourcing remains concentrated among European chemical processors, exposing Australian converters to currency and shipping cost volatility.
- Class IIb clinical evidence requirements:TGA's escalating evidentiary standards for antimicrobial-impregnated dressings are extending registration timelines by 18-24 months for novel entrants.
- Autolytic debridement substitutes:Enzymatic debridement agents and negative pressure wound therapy systems are capturing complex case volumes from traditional dressing categories.
Strategic Opportunities
- Queensland and Western Australia expansion:Underpenetrated public health networks outside southeastern states present first-mover advantages for compliant suppliers with distribution infrastructure.
- Antimicrobial-impregnated dressing reclassification:TGA's anticipated regulatory shift will create tiered market access where early clinical trial investment differentiates premium positioning.
- Silicone adhesive convergence with foam substrates:Technology integration enabling atraumatic removal is opening pediatric and geriatric sensitive-skin segments previously served by basic gauze.
Industry Challenges
- ISO 13485 quality management certification:Small domestic converters face 12-18 month compliance timelines and auditor scarcity, delaying TGA registration and hospital tender eligibility.
- Legacy ERP integration with hospital procurement portals:Electronic ordering system fragmentation across state health networks requires redundant technical adaptation for multi-jurisdictional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Wound Care Management Devices Market |
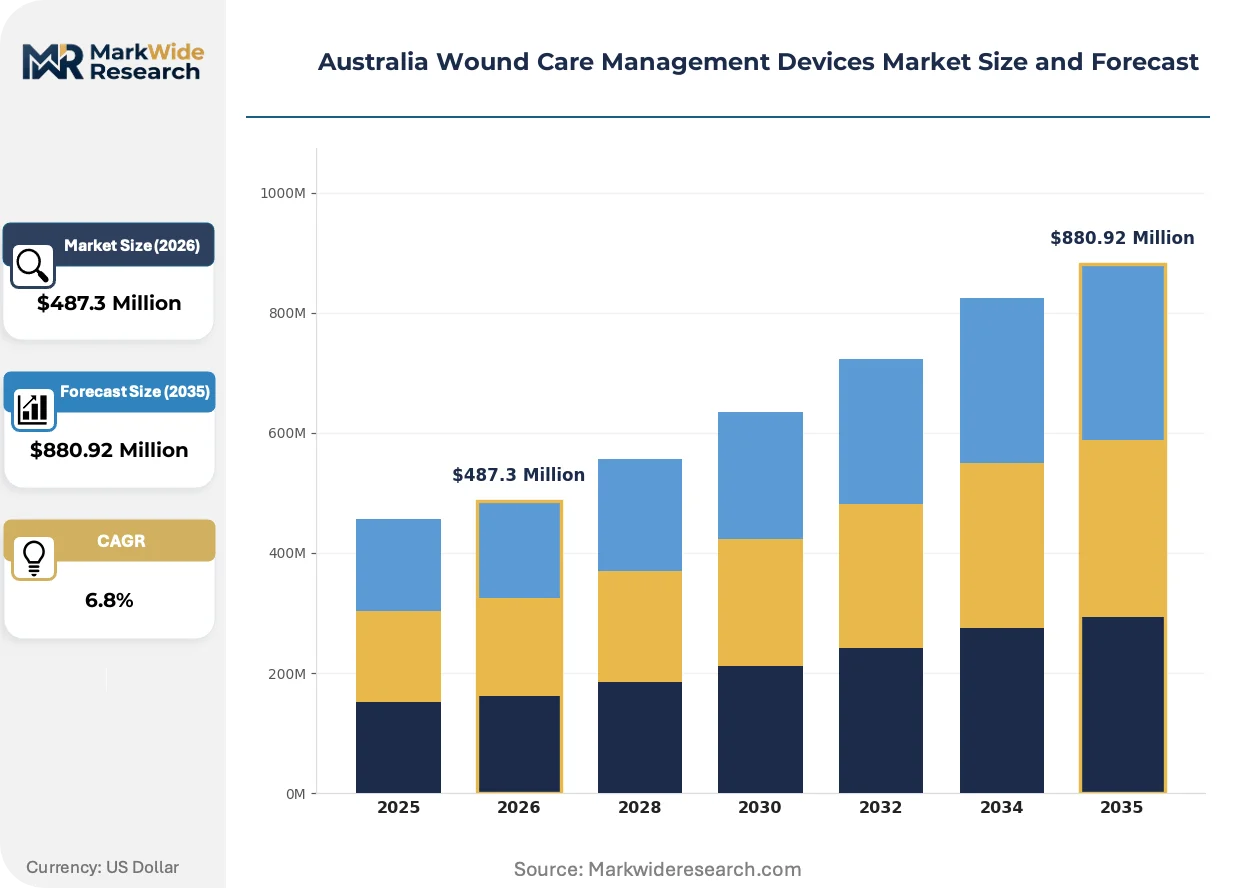
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Bandages, Sutures, Antiseptics End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Application: Acute Wounds, Chronic Wounds, Surgical Wounds, Burns Material: Absorbent Fibers, Hydrocolloids, Collagen, Foam |
| Companies Covered | Johnson & Johnson, ConvaTec Inc., 3M Health Care Ltd, Hollister Incorporated, Medline Industries Inc., Smith & Nephew PLC, Coloplast AS, Mölnlycke Health Care AB, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Wound Care Management Devices Market Strategic Shifts
Digital wound assessment tools and smart dressing substrates are converging with centralized procurement platforms, reshaping how clinical evidence translates to contract eligibility across Australian public health networks.
Sensor-embedded dressings incorporating moisture and temperature detection are modularizing chronic wound monitoring by enabling remote exudate tracking without clinic visits. Metropolitan home care providers in Sydney and Melbourne are piloting these systems for diabetes-related foot ulcer patients. This technology is compressing the traditional nurse visitation cycle while generating real-world evidence datasets that strengthen TGA registration submissions.
TGA's anticipated reclassification of antimicrobial-impregnated dressings under stricter clinical evidence standards is elevating barrier-to-entry for import-reliant distributors. Domestic manufacturers with established Australian clinical trial infrastructure are accelerating pipeline investments to preempt compliance deadlines. The regulatory shift most acutely affects silver-ion and PHMB-impregnated foam suppliers lacking local post-market surveillance capabilities.
State-level procurement consolidation is consolidating purchasing authority within New South Wales HealthShare and Victorian Health Purchasing Victoria, reducing vendor touchpoints from regional hospital clusters to centralized tender boards. Distributors are responding by embedding clinical specialists within procurement negotiation teams rather than relying on traditional sales representative models. This behavioral shift is most pronounced in surgical wound management categories where volume commitments drive multi-year sole-supplier arrangements.
Australia Wound Care Management Devices Market Segmentation
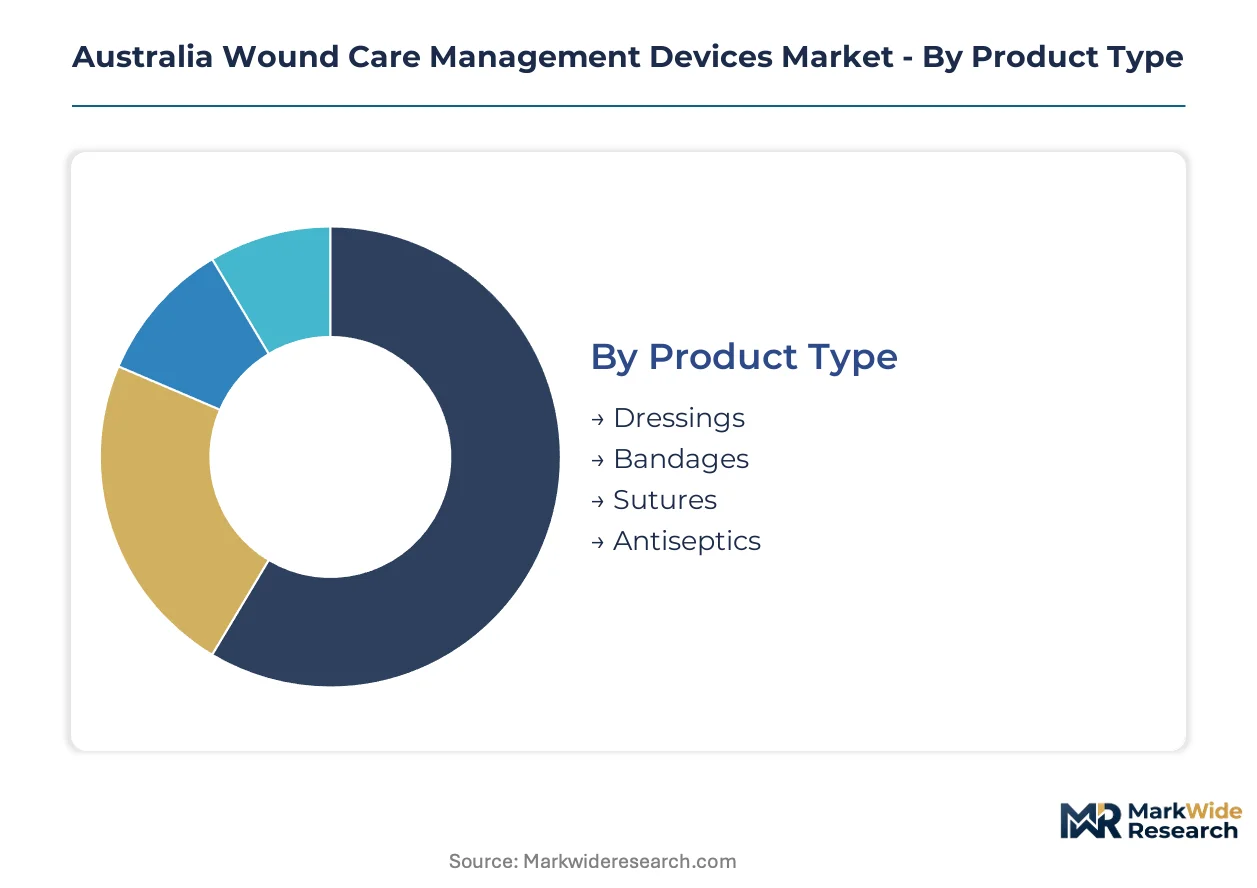
Segmentation in the Australian wound care market reveals how procurement centralization and TGA compliance requirements reshape competitive access across product categories. Hospital tender boards now weight clinical evidence tiers alongside unit economics, compressing margins for undifferentiated suppliers.
Product Type:
Replacement cycles vary sharply across this category, with advanced dressings commanding 6-12 month upgrade intervals versus commodity bandages on 24-36 month cycles.
- Dressings:Hydrocolloid and foam formulations dominate hospital procurement volumes through New South Wales HealthShare and Victorian Health Purchasing Victoria tenders. TGA's updated medical device framework filters out low-evidence suppliers, consolidating access for clinically validated domestic converters with ISO 13485 certification.
- Bandages:Elastic and compression wraps serve high-volume surgical discharge protocols across metropolitan tertiary centers. Demand concentrates in basic gauze and crepe substrates where price competition intensifies under centralized state purchasing.
- Sutures:Absorbable and non-absorbable surgical closure products anchor operating theater supply contracts.
- Antiseptics:Topical antimicrobial solutions support pre-operative skin preparation and wound irrigation protocols.
Volume placements concentrate in Dressings; the faster expansion belongs to advanced hydrocolloid and foam substrates as chronic wound protocols extend into home care settings.
End User:
Customer procurement sophistication creates three distinct cost tiers, with state health networks at premium compliance levels and home care operators at price-sensitive entry points.
- Hospitals:Centralized purchasing through HealthShare NSW and HVP drives multi-year sole-supplier arrangements for surgical wound categories. Clinical specialists now embed directly within procurement negotiation teams, displacing traditional sales representative access models.
- Clinics:Outpatient wound care centers in Sydney and Melbourne purchase through group purchasing organizations with lighter TGA documentation requirements.
- Home Care:Remote monitoring integration extends device utilization beyond hospital discharge, with digital wound assessment tools compressing traditional nurse visitation cycles.
- Long-term Care Facilities:Aged care providers in Queensland and Western Australia present underpenetrated demand for pressure ulcer prevention protocols.
Procurement value pools deepest at Hospitals; Home Care segments are climbing the fastest as transition protocols incorporate sensor-embedded dressings.
Application:
Clinical outcome requirements stratify sharply, with surgical wounds demanding sterile supply chain guarantees and chronic wounds requiring sustained exudate management over extended treatment windows.
- Surgical Wounds:Operating theater consumption drives recurring demand for antimicrobial-impregnated dressings and advanced closure systems. TGA's anticipated reclassification of silver-ion and PHMB-impregnated foams is extending registration timelines for import-reliant distributors lacking local post-market surveillance.
- Chronic Wounds:Diabetes-related foot ulcer incidence in metropolitan tertiary centers expands demand for autolytic debridement protocols. Sensor-embedded dressings with moisture and temperature detection enable remote monitoring without clinic visits.
- Acute Wounds:Trauma and emergency department consumption favors rapid-application bandages and basic dressings.
- Burns:Specialized burn centers require hydrocolloid and collagen-based products for moist healing environments.
Contract stability favors Surgical Wounds; Chronic Wounds are gaining share fastest as diabetes prevalence reshapes caseload composition across Australian public health networks.
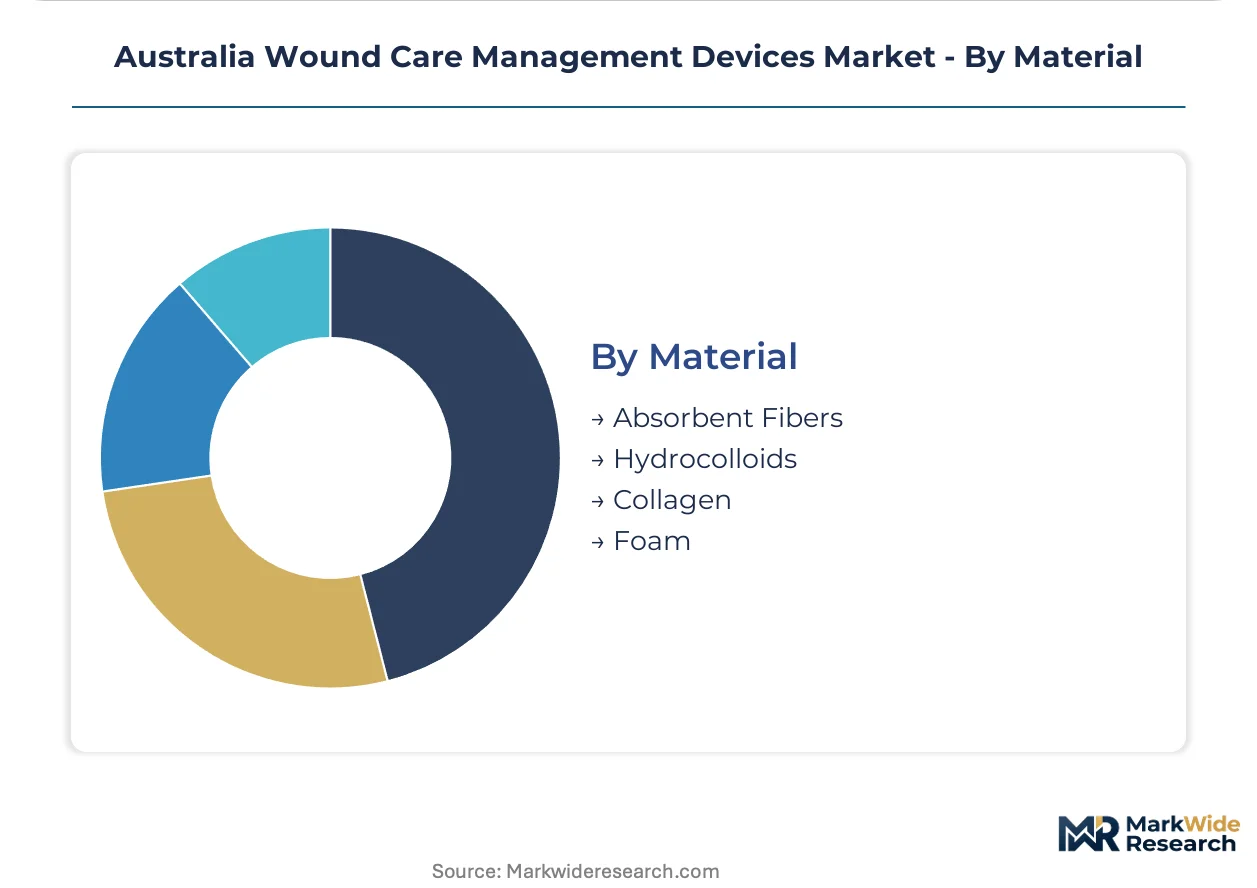
Material:
Supply concentration determines margin structure, with European carboxymethyl cellulose processors exposing domestic converters to currency volatility while foam substrate production localizes.
- Foam:Polyurethane foam substrates with silicone adhesive convergence enable atraumatic removal, opening pediatric and geriatric sensitive-skin segments previously served by basic gauze. Domestic converters are expanding production capacity to reduce import dependency.
- Hydrocolloids:Carboxymethyl cellulose, gelatin, and pectin formulations in polyurethane matrices form cohesive gels upon wound fluid contact. Raw material sourcing concentration among European chemical processors creates supply risk for Australian manufacturing.
- Absorbent Fibers:Cotton and synthetic gauze substrates serve high-volume commodity applications with thin margins.
- Collagen:Animal-derived and recombinant collagen products support burn and complex wound healing protocols.
Manufacturing investment flows toward Foam; Hydrocolloids maintain steepest expansion trajectory as chronic wound protocols proliferate across state health networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carboxymethyl cellulose supply routes from European chemical processors anchor southeastern manufacturing clusters, while polyurethane foam substrate production localizes around Melbourne and Sydney converter facilities.
New South Wales
HealthShare NSW centralized procurement drives multi-year sole-supplier arrangements for surgical wound categories across metropolitan tertiary centers. TGA's updated medical device framework filters tender eligibility through ISO 13485 certification requirements. Sydney distribution hubs sustain rapid hospital fulfillment through embedded clinical specialist negotiation teams.
Victoria
Victorian Health Purchasing Victoria tender boards compress vendor touchpoints from regional hospital clusters to centralized purchasing authorities. The state's Therapeutic Goods Act interface shapes post-market surveillance obligations for antimicrobial-impregnated dressing suppliers. Melbourne-based domestic converters expand hydrocolloid production capacity to reduce European import dependency.
Queensland
Underpenetrated public health networks in Brisbane and Gold Coast present first-mover advantages for compliant suppliers with distribution infrastructure. The state's lighter procurement centralization allows outpatient wound care centers lighter TGA documentation pathways. Aged care providers in regional Queensland drive pressure ulcer prevention protocol demand.
Western Australia
Perth metropolitan hospitals concentrate surgical wound management consumption with limited local converter presence. The state's geographic isolation elevates inventory holding costs for import-reliant distributors. Remote monitoring integration pilots for diabetes-related foot ulcer patients extend device utilization into home care settings.
South Australia
Adelaide tertiary centers anchor chronic wound caseload management with rising diabetes-related foot ulcer incidence. The state's procurement scale limits standalone tender board authority, channeling purchases through interjurisdictional agreements. Local clinical trial infrastructure remains underdeveloped relative to southeastern states.
Australia Wound Care Management Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue silicone-foam convergence and sensor-embedded substrates. The vendor base stratifies across three tiers: multinational health care conglomerates with full portfolio breadth, regional specialists dominating single categories, and domestic converters leveraging regulatory proximity. Dominant competitive moves include backward integration into foam substrate manufacturing and clinical specialist embedding within state procurement negotiation teams.
Among multinational health care conglomerates, Johnson & Johnson and 3M Health Care Ltd exemplify scale-driven archetypes with diversified medical device portfolios spanning wound management adjacent categories. Smith & Nephew PLC occupies a position within the surgical wound specialist tier, leveraging Sydney distribution infrastructure for southeastern state fulfillment. Mölnlycke Health Care AB and Coloplast AS represent European-origin specialists competing through clinician training program differentiation rather than pure price positioning. Domestic converter presence remains limited, with Medline Industries Inc. exemplifying the mid-scale distributor archetype navigating TGA compliance timelines.
| Leading Market Players |
|---|
| Johnson & Johnson |
| ConvaTec Inc. |
| 3M Health Care Ltd |
| Hollister Incorporated |
| Medline Industries Inc. |
| Smith & Nephew PLC |
| Coloplast AS |
| Mölnlycke Health Care AB |
| Medtronic PLC |
| Others |
Value Chain & Pricing Dynamics
Biomedical engineering talent concentration in Melbourne and Sydney drives labor-cost differentials that widen pricing-tier spreads between ISO 13485-certified premium suppliers and basic commodity converters. TGA compliance timelines and auditor scarcity amplify these spreads as smaller domestic manufacturers absorb extended certification delays.
Pricing Analysis
Warranty and clinician training bundling separates premium positioning from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation hinging on TGA registration tier and embedded clinical specialist support. Cost compression in standard tiers intensifies because HealthShare NSW and Victorian Health Purchasing Victoria tender boards demand volume commitments. Home care operators exhibit highest price sensitivity; metropolitan tertiary centers with sole-supplier arrangements show lowest.
Supply Chain Analysis
ISO 13485 certification and TGA registration act as gating mechanisms that filter supplier participation. Raw material sourcing draws from Germany, Sweden, and Belgium for carboxymethyl cellulose and specialized polyurethane precursors. Foam substrate production, hydrocolloid gel formulations, and silicone adhesive layers constitute critical input dependencies. Single-source vulnerability runs through European chemical processors for carboxymethyl cellulose. Distribution runs through Sydney and Melbourne hubs serving southeastern state health networks with direct hospital fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia wound care market sits in a technology-transition phase as sensor-embedded dressings with remote monitoring capabilities displace traditional passive substrates in chronic wound protocols.
For Market Incumbents: Anchor market position through backward integration into foam substrate manufacturing and captive supply of polyurethane precursors. Negative pressure wound therapy systems and enzymatic debridement agents threaten traditional dressing volumes in complex cases. ISO 13485 certification investment and embedded clinical specialist teams within state procurement negotiations provide defensive leverage against import-reliant distributors facing TGA reclassification delays. For New Entrants and Emerging Players: The mid-tier price-point gap between Smith & Nephew PLC premium positioning and basic commodity bandages opens white-space in Queensland and Western Australia public health networks. Underpenetrated aged care pressure ulcer prevention protocols in regional Queensland present accessible entry volume. Direct contracting with outpatient wound care centers bypasses centralized tender board complexity while building clinical evidence for eventual hospital system expansion. For Investors and Strategic Acquirers: Re-rating potential sits with domestic converters possessing established TGA registration pathways and Australian clinical trial infrastructure given antimicrobial-impregnated dressing reclassification catalysts. Long-term viability favors suppliers with vertically integrated foam production and remote monitoring technology integration. Watch TGA's final reclassification timeline as inflection indicator for competitive access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Registration Acceleration | Early clinical trial investment preempts antimicrobial-impregnated dressing reclassification deadlines. |
| Hospital System Partnership | Multi-year sole-supplier arrangements with HealthShare NSW lock in surgical wound category volumes. |
| Sensor-Embedded Dressing Development | Moisture and temperature detection modules enable remote monitoring for diabetes-related foot ulcer patients. |
| Backward Integration into Foam Substrates | Domestic polyurethane production reduces European import dependency and currency exposure. |
| Clinician Training Program Expansion | Differentiation through embedded clinical specialists displaces traditional sales representative access models. |
Study Parameters
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation sources include TGA registration databases, HealthShare NSW tender documentation, Victorian Health Purchasing Victoria contracts, and ISO 13485 certification records. Bottom-up and top-down triangulation reconciles device-level consumption data with state health network expenditure reports.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user, application, and material substrate with TGA regulatory tier as an overlay. CAGRs derive from trend extrapolation of hospital procurement volumes, chronic wound incidence trajectories, and home care transition protocol adoption. Forecast inputs incorporate diabetes prevalence projections and antimicrobial dressing reclassification probability assessments.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time tender outcome data and confidential contract pricing introduce uncertainty bands. Forecasts reflect documented assumptions regarding TGA timeline adherence and chronic wound protocol standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Care Sealants Market
Wound Care
Vascular Dressings Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Foam Dressing Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Wound Retractor Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Autologous Wound Patches Market
Wound Care
Wound Skin Care Market
Wound Care
Wound Closure Strips Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Collagen Dressings Market