
 Dental 3D Printing Scanner Market | 2026-2036
Dental 3D Printing Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Dental 3D Printing Scanner Market Insights
Software-defined subscription tiers for cloud-based scan processing and AI-powered margin detection are expanding what manufacturers monetize beyond hardware units. 3Shape A/S leverages its open-platform Trios ecosystem to sustain recurring revenue from dental labs worldwide. Dentsply Sirona Inc. anchors its competitive stance through vertical control over chairside-to-lab workflows. Align Technology Inc. dominates clear-aligner therapy by integrating proprietary scanning with treatment planning software.
Dental 3D printing scanners are precision optical devices that capture intraoral or model-based geometry through structured light or laser triangulation, typically achieving accuracy below 20 microns for clinical crown-and-bridge fabrication. These systems digitize anatomical structures to drive CAD/CAM milling, photopolymer printing, and thermoforming processes across restorative and orthodontic applications. Intraoral scanners command the largest installed base due to chairside adoption, while lab scanners retain margin concentration in high-throughput production environments. Structured light scanning leads technology deployment for its speed-to-accuracy ratio, though laser scanning extends into implantology where sub-10-micron tolerance matters.
FDA 510(k) clearance and EU MDR conformity assessment shape product development timelines and market access for scanner manufacturers serving the United States and European Union. ISO 12836 standardization for digitizing accuracy provides the technical baseline that national regulators reference for type-testing requirements. Dental laboratories and clinic networks must monitor how AI-enhanced scan validation tools alter liability frameworks and reimbursement documentation standards.
Market Dynamics
Digital workflow mandates from German dental lab consolidators are compressing scanner replacement cycles and forcing mid-tier manufacturers toward AI-enhanced margin detection software to retain procurement relevance.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket notification pathways for optical scanning systems are reducing time-to-market for structured light platforms targeting chairside adoption in US dental clinics.
- EU MDR conformity assessment:Tightened performance validation standards under the Medical Device Regulation are filtering sub-20-micron accuracy claims and elevating certified system demand across European dental laboratories.
- Photopolymer printing integration:Direct compatibility between intraoral scan outputs and resin-based additive manufacturing is pulling hardware procurement into integrated CAD/CAM-to-print workflows.
Market Restraints
- CMOS sensor supply concentration:Dependence on East Asian semiconductor foundries for high-resolution imaging arrays creates input volatility and extended lead times for scanner assembly.
- Laser triangulation cost floor:Sub-10-micron tolerance systems require precision galvanometer assemblies that resist economies of scale, capping price accessibility for independent dental practices.
- ISO 12836 testing burden:Third-party digitizing accuracy certification adds six-to-nine month validation timelines before commercial release in regulated markets.
Strategic Opportunities
- Cloud-native scan processing:Subscription-tier software architectures enable recurring revenue capture from dental labs previously lost to perpetual-license hardware bundling.
- Implantology sub-segment expansion:Surgical guide fabrication workflows demand sub-10-micron accuracy that laser scanning systems can command at premium pricing.
- AI Act compliance tooling:Automated margin detection algorithms validated under emerging EU artificial intelligence frameworks create differentiation for European-market scanner deployments.
Industry Challenges
- CAD/CAM technician scarcity:Dental laboratories face recruitment friction for operators capable of bridging optical scan data into milling and printing machine control.
- Legacy PVS impression integration:Hybrid workflows requiring physical model digitization create data format incompatibilities that slow full digital adoption in established practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental 3D Printing Scanner Market |
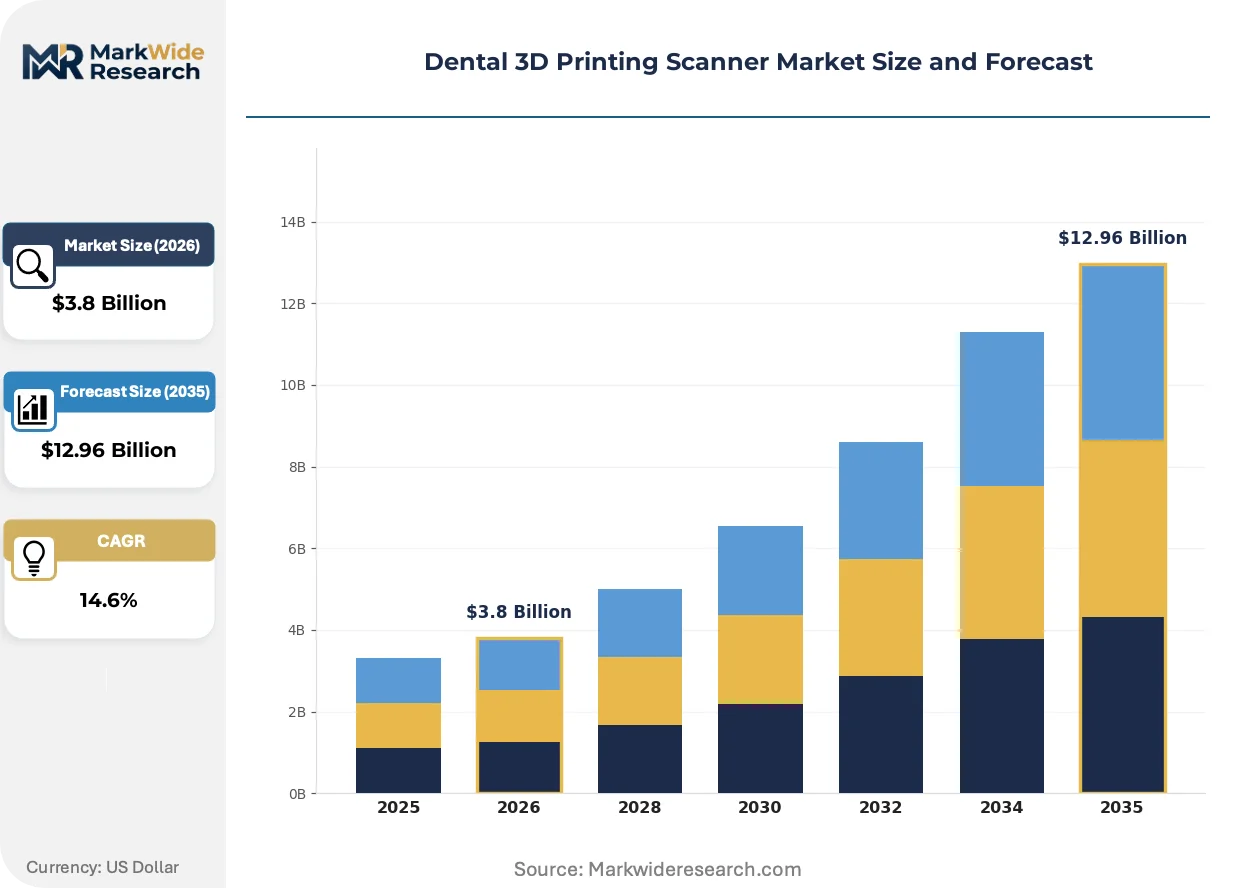
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, Desktop Scanners, Mobile Scanners, Lab Scanners Technology: Laser Scanning, Structured Light Scanning, Optical Scanning, 3D Photogrammetry End User: Dental Clinics, Dental Laboratories, Orthodontic Practices, Research Institutions Application: Crowns & Bridges, Implants, Orthodontics, Prosthodontics |
| Companies Covered | 3Shape A/S, Dentsply Sirona Inc., Align Technology Inc., Envista Holdings Corporation, Planmeca Oy, Institut Straumann AG, Carestream Dental LLC, Medit Corp., Shining 3D Tech Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental 3D Printing Scanner Market Trends and Innovations
Scanner manufacturers are weaponizing software ecosystems to capture lifetime value from hardware placements, shifting competitive advantage from optical engineering to platform lock-in and recurring revenue architecture.
Structured light scanning is overtaking laser triangulation in chairside restorative applications due to superior speed-to-accuracy ratios for full-arch capture. General dentistry practices in Germany and the United States are standardizing on sub-20-micron structured light platforms for crown-and-bridge fabrication. This technology compression is collapsing the addressable market for premium laser systems outside implantology and orthodontic bracket positioning.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for optical digitizing devices classified as Class IIa medical devices. Scanner manufacturers must now submit clinical performance data and post-market surveillance protocols that exceed previous MEDDEV guidance. German notified bodies are experiencing backlog concentrations that delay CE marking by four to six months, advantaging larger firms with dedicated regulatory affairs capacity.
Dental lab procurement is consolidating toward preferred vendor agreements with platform-locked subscription tiers. Independent laboratories in Bavaria and North Rhine-Westphalia are abandoning multi-vendor hardware portfolios for single-ecosystem standardization that reduces training overhead and software licensing fragmentation. This behavior shift compresses competitive entry for standalone scanner manufacturers lacking cloud processing and AI tool integration.
Dental 3D Printing Scanner Market Segmentation
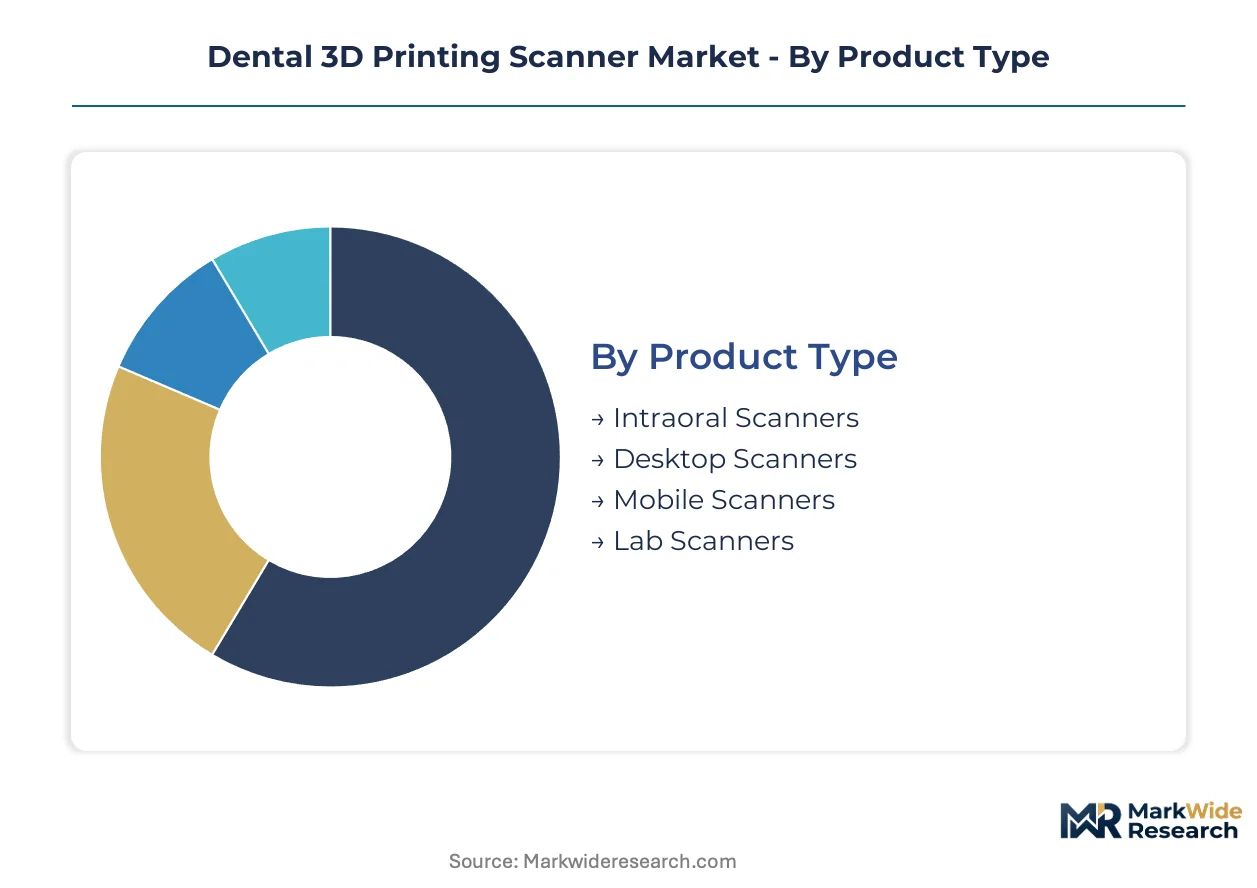
Segmentation in dental 3D printing scanners reveals how hardware specifications, workflow integration, and regulatory classification reshape procurement decisions across chairside and laboratory environments. Understanding these divides exposes where manufacturers capture premium pricing versus where commoditization pressures concentrate.
Product Type:
Volume concentration sits with intraoral systems, while premium margins attach to lab-grade platforms engineered for throughput and sub-10-micron tolerances.
- Intraoral Scanners:Handheld optical devices capture direct patient anatomy through structured light or confocal microscopy, eliminating physical impressions. German dental clinic networks and US group practices are standardizing on these for same-day crown workflows, compressing replacement cycles to 4-5 years as software ecosystems mature.
- Lab Scanners:Fixed-position systems process physical models and dies with galvanometer-steered laser triangulation achieving implantology-grade precision. Bavarian dental lab consolidators mandate these for surgical guide fabrication, where ISO 12836-certified accuracy determines procurement eligibility.
- Desktop Scanners:Compact units serve small laboratories bridging digital and physical workflows, typically handling 10-15 models daily with structured light arrays.
- Mobile Scanners:Portable cart-based systems enable multi-chair deployment in clinic networks, prioritizing interoperability with existing CAD/CAM investments.
Today's leader: Intraoral Scanners. Tomorrow's challenger: Lab Scanners.
Technology:
Cost tier separation runs from premium laser systems through mid-market structured light to emerging photogrammetry alternatives.
- Structured Light Scanning:Pattern projection onto anatomical surfaces enables full-arch capture in under 30 seconds with 15-20 micron accuracy. General dentistry practices in North Rhine-Westphalia favor this speed-to-precision ratio for high-volume crown-and-bridge production, displacing slower laser alternatives in restorative applications.
- Laser Scanning:Triangulation-based systems using precision galvanometers achieve sub-10-micron tolerances essential for implant abutment and bracket positioning. The cost floor from optical component sourcing limits penetration outside specialized prosthodontic and orthodontic laboratories.
- Optical Scanning:Broad category encompassing confocal microscopy and active wavefront sampling, deployed where surface reflectivity challenges structured light performance.
- 3D Photogrammetry:Multi-camera correlation methods extract geometry from texture patterns, gaining traction in research institutions for facial scanning integration with intraoral data.
Structured Light Scanning commands installed base dominance. Laser Scanning retains margin concentration in surgical workflows.
End User:
Customer type determines software bundling requirements and service contract structures more than hardware specifications alone.
- Dental Clinics:Chairside adoption demands seamless CAD/CAM integration and cloud-based scan storage compliant with HIPAA and GDPR. US dental service organizations negotiate enterprise licenses spanning hundreds of locations, shifting procurement toward platform-locked ecosystems.
- Dental Laboratories:High-throughput production environments prioritize batch processing capabilities and open STL export formats. German lab networks under digital workflow mandates are consolidating vendor relationships to reduce training overhead.
- Orthodontic Practices:Clear-aligner therapy workflows require specific scan formats compatible with thermoforming simulation software.
- Research Institutions:Academic users drive validation studies for emerging accuracy standards and AI-enhanced margin detection algorithms.
Dental Laboratories anchor hardware volume. Dental Clinics represent the steepest expansion trajectory for recurring software revenue.
Application:
Margin structure varies by clinical tolerance requirements and reimbursement documentation complexity.
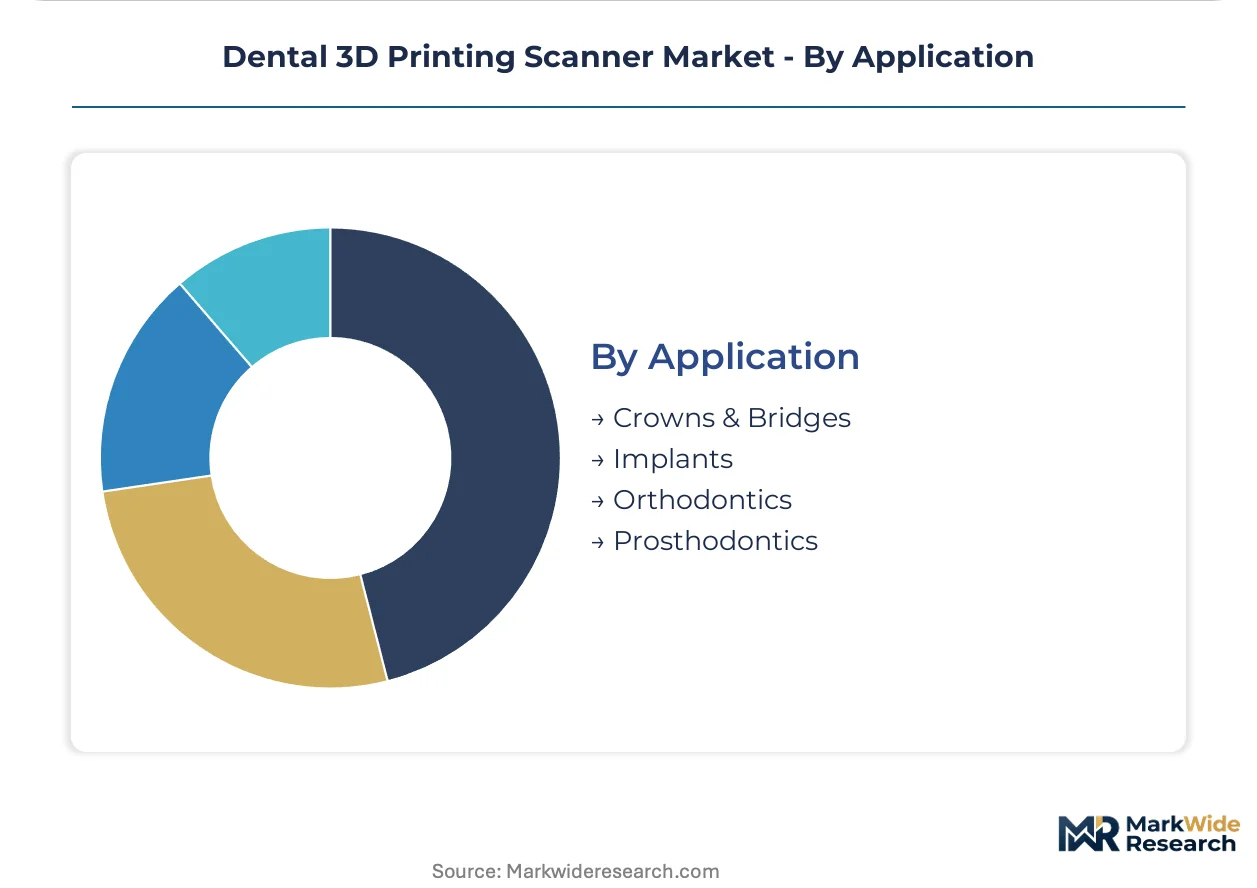
- Crowns & Bridges:Restorative applications tolerate 20-micron accuracy for single-unit fabrication, enabling structured light platform standardization. German statutory insurance reimbursement frameworks now require digital workflow documentation, accelerating scanner placement in general practices.
- Implants:Surgical guide fabrication demands sub-10-micron tolerances and ISO 12836-certified digitizing accuracy. Premium pricing persists here as laser systems resist commoditization.
- Orthodontics:Clear-aligner therapy integration prioritizes scan-to-treatment-planning software pipelines over absolute geometric precision.
- Prosthodontics:Full-arch rehabilitation combines intraoral and model-based scanning, creating hybrid procurement requirements.
Crowns & Bridges deliver installed base scale. Implants defend premium positioning through tolerance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany compresses scanner replacement cycles through digital workflow mandates, while the United States accelerates chairside adoption via streamlined FDA pathways and dental service organization consolidation.
United States
Chairside CAD/CAM standardization and dental service organization expansion drive hardware procurement across multi-location networks. FDA 510(k) premarket notification pathways for optical scanning systems compress regulatory timelines for structured light platforms. The Greater Boston cluster anchors precision optics development, with Massachusetts-based manufacturers advancing confocal microscopy integration for reflective surface capture.
Germany
Dental lab consolidation in Bavaria and North Rhine-Westphalia compresses replacement cycles and forces subscription-tier software bundling. EU MDR Article 10 conformity assessment requirements for Class IIa medical devices extend validation timelines, advantaging firms with dedicated regulatory capacity. The Stuttgart precision engineering corridor concentrates galvanometer assembly for sub-10-micron laser systems serving implantology workflows.
China
Domestic photopolymer printer manufacturing pulls scanner procurement into integrated CAD/CAM-to-print ecosystems for export-oriented dental laboratories. NMPA medical device registration requirements for optical digitizing equipment tighten clinical performance documentation standards. The Yangtze River Delta manufacturing belt, centered on Shanghai and Suzhou, hosts CMOS sensor packaging facilities critical to imaging array supply.
Japan
Aging demographic pressure on prosthodontic service delivery accelerates digital workflow investment in clinic networks. PMDA premarket approval processes for medical devices with AI-enhanced margin detection algorithms extend software validation requirements. The Nagoya medical device manufacturing corridor concentrates optical component sourcing for structured light projection systems.
Switzerland
Precision manufacturing heritage supports premium positioning for implantology-grade scanning systems demanding ISO 12836-certified accuracy. Swissmedic medical device conformity assessment procedures for active optical devices mandate post-market surveillance protocols exceeding baseline EU requirements. The Basel-Zurich corridor anchors high-value dental technology R&D, with manufacturers commanding premium pricing for surgical guide fabrication workflows.
Dental 3D Printing Scanner Market Competitive Landscape
Top-tier vendors anchor platform-locked ecosystems with recurring software revenue, while mid-tier specialists compete on hardware specifications and open-format interoperability. Market structure concentrates around three strategic archetypes: vertically integrated dental technology conglomerates controlling chairside-to-lab workflows; pure-play scanner manufacturers monetizing through cloud-native subscription tiers; and regional fabricators competing on cost-optimized structured light platforms. Dominant competitive moves include strategic partnerships for CAD/CAM software integration and geographic expansion through distributor networks in emerging dental laboratory markets.
Within the premium ecosystem tier, 3Shape A/S and Dentsply Sirona Inc. occupy positions defined by platform breadth and vertical workflow control, while Align Technology Inc. exemplifies the therapy-integrated archetype linking proprietary scanning to clear-aligner treatment planning. Shining 3D Tech Co. Ltd. represents the Asia-based manufacturing specialist competing on hardware cost structures and photopolymer printer compatibility.
| Leading Market Players |
|---|
| 3Shape A/S |
| Dentsply Sirona Inc. |
| Align Technology Inc. |
| Envista Holdings Corporation |
| Planmeca Oy |
| Institut Straumann AG |
| Carestream Dental LLC |
| Medit Corp. |
| Shining 3D Tech Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Structured light scanning platform commoditization is collapsing hardware margins while concentrating value capture in cloud-native software ecosystems, simultaneously reshaping procurement economics and supplier power dynamics across dental laboratory networks.
Pricing Analysis
Capacity additions in Chinese structured light module manufacturing are reshaping price floors for mid-tier intraoral systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 12836 certification grade and AI margin detection bundling. Cost compression in standard-tier hardware is intensifying because photopolymer printer OEMs bundle scanners at near-zero marginal cost. Independent dental practices exhibit highest price sensitivity, while German dental lab consolidators prioritize ecosystem lock-in over unit economics.
Supply Chain Analysis
High-resolution CMOS sensor supply rests on Taiwanese and South Korean semiconductor foundries, with Japanese precision optics houses anchoring galvanometer assembly for laser triangulation systems. Critical dependencies include structured light projection modules, precision motion control assemblies, and medical-grade aluminum housings. Single-source vulnerability concentrates in EUV lithography-dependent imaging arrays. Distribution runs through authorized dental equipment distributors with certified service technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on software subscription attach rates displacing perpetual licensing, with AI-enhanced margin detection tools commanding premium tier positioning.
For Market Incumbents: Anticipate displacement from Asia-based hardware specialists by deepening backward integration into CMOS sensor packaging and securing exclusive cloud processing partnerships with German dental lab networks. Prioritize EU MDR regulatory capacity buildout to exploit notified body backlogs disadvantaging mid-tier competitors. For New Entrants and Emerging Players: Capture white-space in orthodontic practice segments underserved by clear-aligner-integrated scanning ecosystems, particularly in Japanese clinic networks facing prosthodontic service delivery pressures. Deploy photopolymer printer compatibility as primary go-to-market wedge against platform-locked incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone hardware manufacturers lacking recurring revenue architecture and AI tool validation. Long-term viability favors platform-locked ecosystems with demonstrated dentist workflow retention. Watch FDA 510(k) clearance velocity for structured light platforms as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Subscription Tier Launch | Transforms hardware vendors into recurring revenue platforms capturing lifetime value from dental lab customers. |
| AI Margin Detection Algorithm Validation | EU AI Act compliance creates differentiation barrier for European-market scanner deployments against non-compliant imports. |
| Photopolymer Printer Ecosystem Integration | Direct scan-to-print workflows pull hardware procurement decisions into integrated CAD/CAM system choices. |
| EU MDR Dedicated Regulatory Capacity Buildout | Notified body backlogs advantaging larger firms with clinical performance data submission expertise. |
| Galvanometer Assembly Backward Integration | In-house production of precision optical components defends sub-10-micron tolerance premium positioning. |
Research Methodology
Multiple input streams — primary interviews with dental laboratory directors, CAD/CAM technicians, and GPO procurement managers; FDA 510(k) clearance databases and EU MDR notified body registries; and dental equipment distributor transaction records — were reconciled through bottom-up hardware shipment triangulation against top-down dental clinic digital workflow adoption surveys.
Data-stream reconciliation across product type, technology modality, end-user segment, and application tolerance requirements shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycle compression and software attach rate expansion modeling, with German dental lab consolidation patterns and US dental service organization procurement standardization serving as key demand-side inputs.
EU MDR implementation delays, CMOS sensor supply disruptions, and AI regulatory framework finalization are the dominant revision risks to modeled outcomes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Global Dental Milling Machine Market