
 Auto-Transfusion Systems Market | 2026-2036
Auto-Transfusion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Auto-Transfusion Systems Market Intelligence
Software-defined perfusion monitoring and predictive maintenance subscription tiers is hardening the commercial model around auto-transfusion hardware. Haemonetics Corporation leverages its installed base of cell salvage platforms to lock in recurring service revenue across North American hospital networks. Fresenius SE & Co. KGaA anchors its position through backward integration into blood processing consumables, while LivaNova PLC competes on cardiac surgery workflow integration.
Auto-transfusion systems are electromechanical devices that recover, filter, wash, and reinfuse a patient's shed blood during or after surgical procedures, typically achieving hematocrit levels between 50-60% in the processed output. These systems reduce allogeneic transfusion exposure and conserve blood bank inventory in high-bleeding procedures. Cell salvage devices command the deepest installed base and replacement cycle revenue, while automated systems with closed-loop processing represent the fastest-growing technology tier as hospitals prioritize staff efficiency and contamination risk reduction. Orthopedic surgery applications are expanding fastest in ambulatory surgical centers, though cardiac surgery retains the highest per-procedure consumable spend.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for device manufacturers. ISO 13485 quality management certification and IEC 60601 electrical safety standards form baseline predicates for commercial distribution across regulated markets. Stakeholders must monitor evolving CMS reimbursement coding for autologous blood recovery and track how health technology assessment bodies in Germany and Japan evaluate cost-effectiveness against standard transfusion protocols.
Market Dynamics
The shift from capital equipment sales to recurring consumable and service revenue streams is restructuring competitive economics in auto-transfusion systems, as manufacturers prioritize installed base lock-in over upfront device margins.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements are accelerating hospital replacement cycles for legacy devices, creating upgrade demand across German and French tertiary centers.
- Ambulatory surgical center expansion:Orthopedic procedure migration to outpatient settings is extending addressable procedure volume for compact cell salvage units in the United States.
- Enhanced Recovery After Surgery protocols:ERAS adoption in Japanese university hospitals is embedding auto-transfusion into standardized cardiac and major orthopedic pathways.
Market Restraints
- Single-use consumable cost concentration:Proprietary tubing sets and collection reservoirs account for 60-70% of lifetime ownership costs, constraining budget-constrained purchasers.
- Specialized perfusionist workforce scarcity:Limited training pipeline for certified clinical perfusionists restricts device utilization rates in smaller surgical programs.
- Leukodepletion filter supply vulnerability:Filter membrane production concentrates among three European specialty material suppliers, exposing downstream assemblers to input volatility.
Strategic Opportunities
- India's tertiary hospital infrastructure buildout:Greenfield cardiac surgery centers under the Ayushman Bharat scheme present first-mover positioning for automated systems.
- Trauma and emergency medicine adoption:Military and civilian trauma networks represent untapped deployment scenarios for portable intraoperative cell salvage.
- Subscription-based predictive maintenance:Remote monitoring software tiers enable recurring revenue capture from mid-tier hospital networks previously served by basic service contracts.
Industry Challenges
- FDA 510(k) predicate device pathway complexity:Substantial equivalence determinations for novel processing algorithms extend clearance timelines and inflate regulatory consulting expenditures.
- Legacy EMR integration friction:Proprietary data formats from incumbent cell salvage platforms resist seamless connectivity with hospital information systems, complicating quality audit workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto-Transfusion Systems Market |
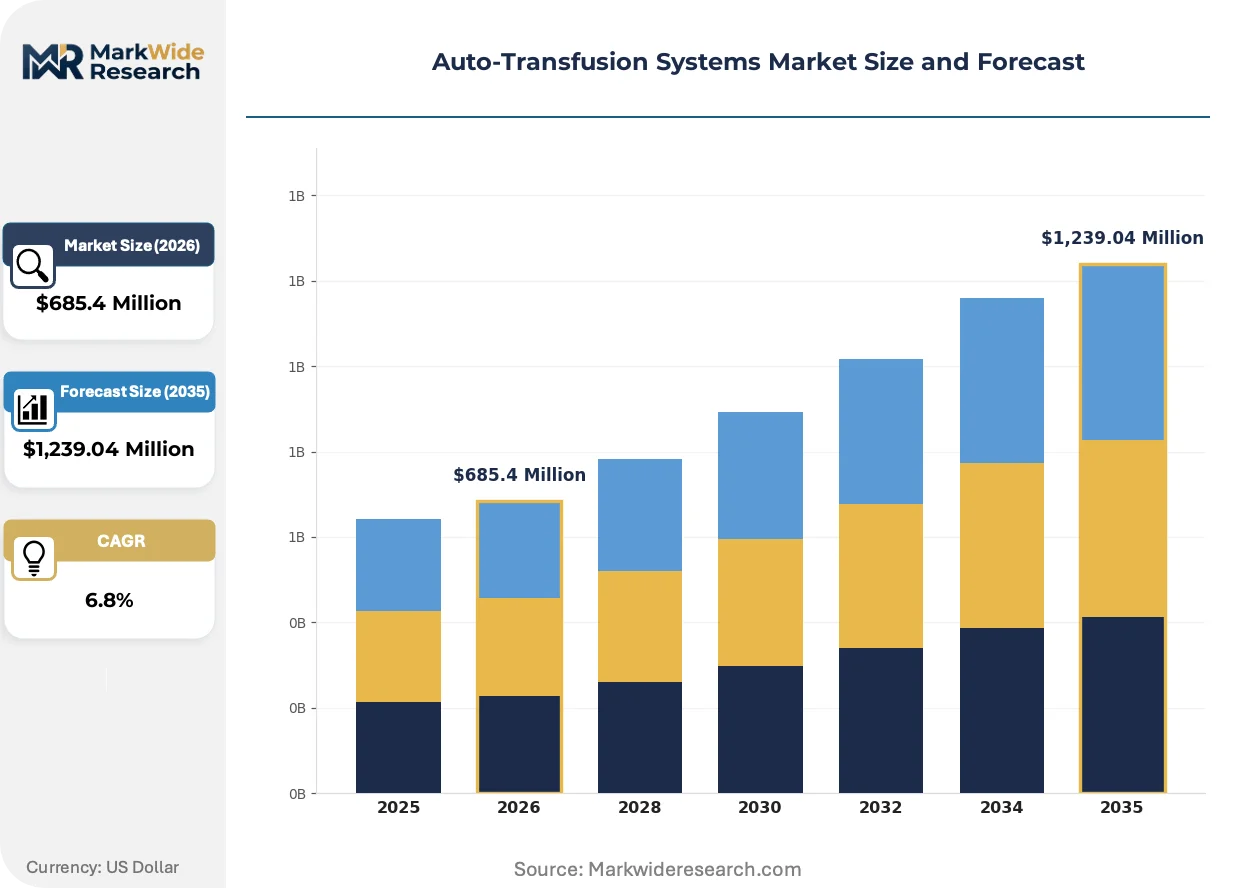
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Salvage Devices, Blood Processing Units, Accessories, Filters End User: Hospitals, Surgical Centers, Blood Banks, Clinics Technology: Closed System, Open System, Automated Systems, Portable Devices Application: Orthopedic Surgery, Cardiac Surgery, Trauma Surgery, Transfusion Medicine |
| Companies Covered | Haemonetics Corporation, LivaNova PLC, Fresenius SE & Co. KGaA, Medtronic, BD, Teleflex Incorporated, Zimmer Biomet, B. Braun SE, SARSTEDT AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto-Transfusion Systems Market Strategic Shifts & Innovations
Software-defined functionality and closed-loop automation are displacing manual operator intervention as the primary value axis, while regulatory data requirements and procurement centralization reshape how manufacturers capture margin.
Artificial intelligence-based hematocrit prediction algorithms are integrating real-time optical sensors with machine learning models to optimize wash protocols without perfusionist adjustment. Tertiary cardiac centers in Germany and Japan are piloting these systems to reduce processing variability. This convergence is integrating predictive analytics into device control architectures, compressing the performance gap between experienced and novice clinical operators.
The EU MDR's expanded clinical evidence requirements are forcing manufacturers to maintain post-market surveillance registries that track device-specific outcomes across implantation sites. This regulatory burden is elevating compliance costs disproportionately for smaller device assemblers lacking dedicated regulatory affairs infrastructure. Cardiac surgery device portfolios face the steepest documentation demands, driving consolidation among notified body relationships.
Hospital procurement departments are consolidating supplier relationships through multi-year enterprise agreements that bundle auto-transfusion hardware with consumable commitments and service tiers. This purchasing pattern is displacing transactional device acquisitions in United States health systems exceeding 500 beds. Academic medical centers in Boston and Cleveland have pioneered these structures, extending payment terms in exchange for volume guarantees and technology refresh commitments.
Auto-Transfusion Systems Market Segmentation
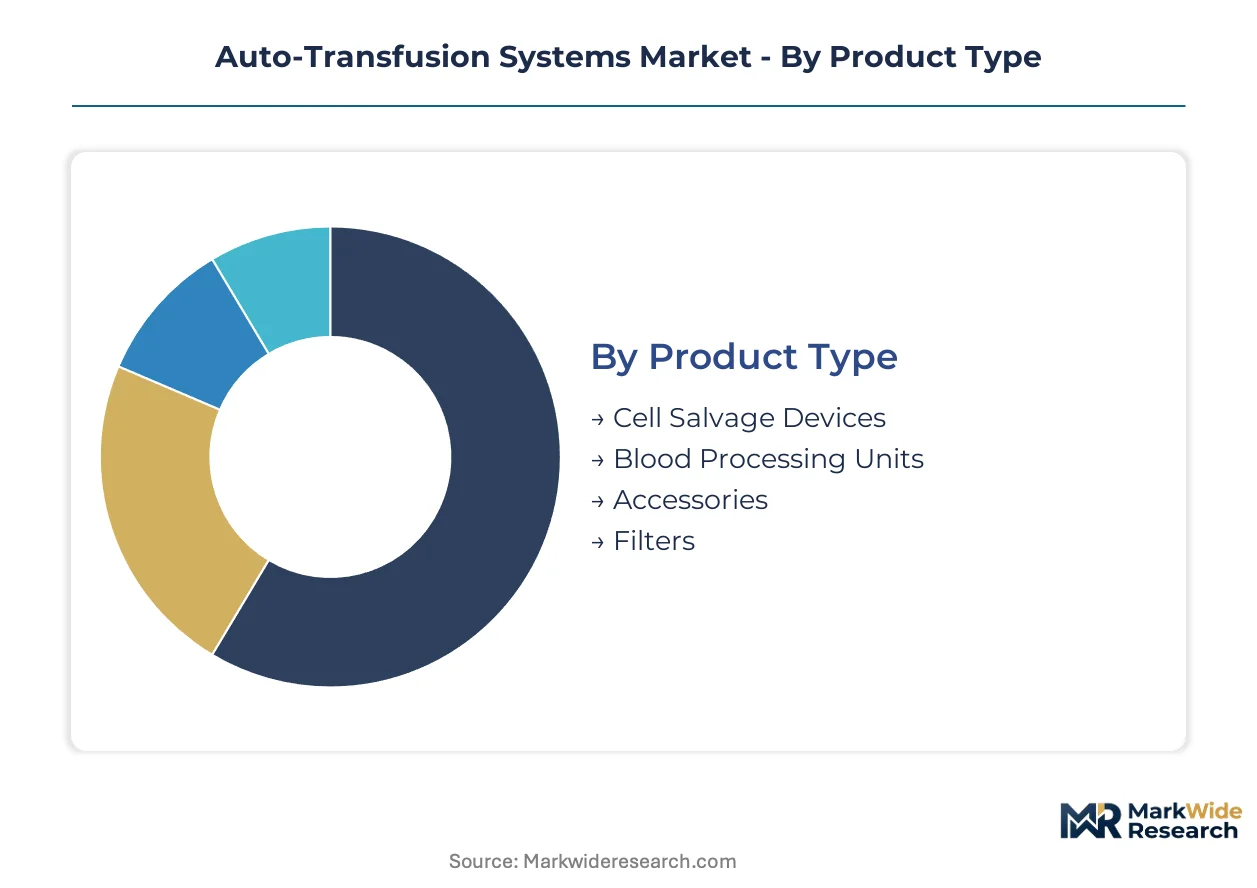
Segmentation in auto-transfusion systems reveals distinct procurement patterns across technology tiers and care settings. Product architecture, automation level, and surgical application each create separate competitive arenas with unique margin profiles and regulatory requirements.
Product Type:
Technology specifications determine capital intensity and consumable attach rates across the installed base.
- Cell Salvage Devices:Electromechanical platforms recover shed blood through centrifugal washing and filtration, achieving hematocrit outputs between 50-60%. Demand concentrates in United States tertiary cardiac centers where replacement cycles accelerate under FDA's updated blood device guidance.
- Blood Processing Units:Modular components handle anticoagulation, washing, and reinfusion functions as discrete subsystems. German university hospitals favor these configurations for customized perfusion workflows in complex aortic procedures.
- Accessories:Collection reservoirs, suction wands, and tubing sets constitute proprietary consumable ecosystems.
- Filters:Leukodepletion and microaggregate filtration membranes represent critical single-use components with concentrated European supply.
Mature deployment sits with Cell Salvage Devices. Newer deployment is concentrated in modular Blood Processing Units.
End User:
Procurement authority and procedure volume reshape pricing leverage across customer categories.
- Hospitals:Tertiary academic medical centers in Boston and Cleveland command enterprise-tier pricing through multi-year bundled agreements spanning hardware, consumables, and predictive maintenance subscriptions.
- Surgical Centers:Ambulatory orthopedic facilities in the United States drive compact system demand as procedure migration accelerates under CMS reimbursement shifts.
- Blood Banks:Centralized processing facilities maintain quality-controlled autologous blood inventories for scheduled surgical programs.
- Clinics:Limited-acuity settings deploy basic cell salvage for minor orthopedic and obstetric applications.
Revenue concentration favors Hospitals. Volume expansion is climbing the fastest in Surgical Centers.
Technology:
Automation architecture separates premium positioning from commodity alternatives.
- Closed System:Sealed processing loops eliminate environmental contamination risk through sterile fluid pathways. Japanese university hospitals embed these platforms into ERAS protocols for cardiac and major orthopedic pathways.
- Open System:Semi-automated configurations require manual transfer steps between collection and reinfusion.
- Automated Systems:Closed-loop processing with AI-driven hematocrit prediction reduces perfusionist intervention. German tertiary centers pilot these systems to compress variability between novice and experienced operators.
- Portable Devices:Battery-powered units enable trauma field deployment and military medical evacuation scenarios.
Installed base dominance rests with Closed System platforms. Steepest expansion trajectory belongs to Automated Systems.
Application:
Procedure bleeding risk and blood bank dependency determine per-case consumable intensity.
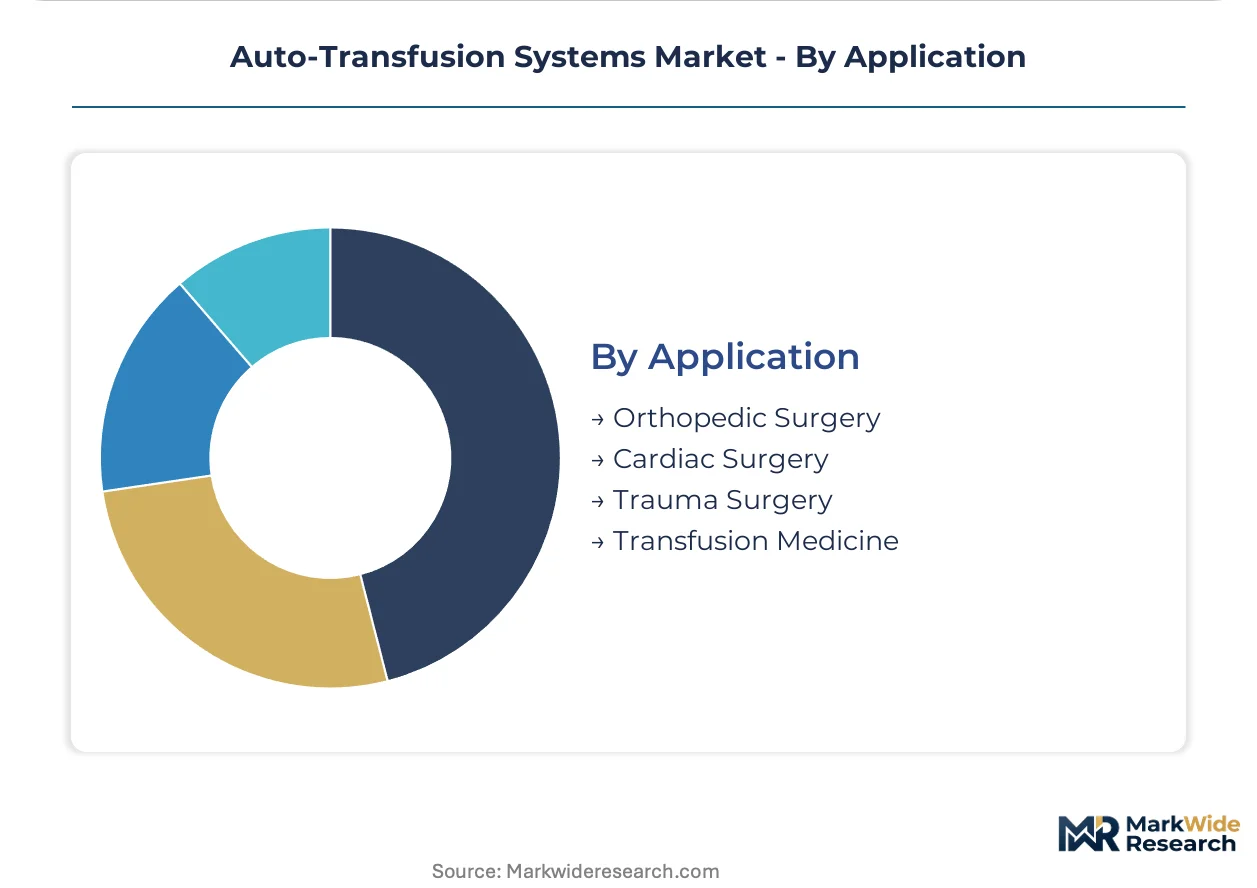
- Orthopedic Surgery:Joint replacement and spinal fusion procedures generate predictable shed blood volumes suitable for routine cell salvage. United States ambulatory surgical centers represent the fastest volume growth as same-day discharge protocols expand.
- Cardiac Surgery:Cardiopulmonary bypass and aortic procedures command the highest per-procedure consumable spend due to large-volume processing requirements and specialized leukodepletion protocols.
- Trauma Surgery:Emergency hemorrhage control creates demand for rapid-deployment portable systems in civilian and military settings.
- Transfusion Medicine:Preoperative autologous donation programs and directed donation processing utilize processing capabilities outside intraoperative contexts.
Revenue yield peaks in Cardiac Surgery. Addressable volume is gaining share fastest in Orthopedic Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while consumption spreads across tertiary cardiac centers in Japan and expanding surgical networks in India. This divergence creates distinct procurement patterns across developed and emerging markets.
United States
CMS reimbursement shifts accelerate orthopedic procedure migration to ambulatory surgical centers, driving compact cell salvage demand. The FDA's updated blood device guidance tightens 510(k) clearance pathways for novel processing algorithms. Boston and Cleveland academic medical centers pioneer multi-year enterprise agreements bundling hardware with consumable commitments.
Germany
University hospitals favor modular blood processing configurations for customized perfusion workflows in complex aortic procedures. The EU MDR's stricter clinical evidence requirements accelerate replacement cycles for legacy devices across tertiary centers. The Baden-Württemberg and Bavaria clusters concentrate notified body relationships and regulatory affairs infrastructure.
Japan
Enhanced Recovery After Surgery protocol adoption embeds auto-transfusion into standardized cardiac and major orthopedic pathways. METI coordinates health technology assessment evaluations of cost-effectiveness against standard transfusion protocols. Tokyo and Osaka university hospitals pilot AI-driven hematocrit prediction systems to reduce processing variability.
India
Greenfield cardiac surgery centers under the Ayushman Bharat scheme present first-mover positioning for automated systems. The Central Drugs Standard Control Organization governs medical device registration timelines for imported equipment. Maharashtra and Karnataka tertiary hospital buildouts concentrate demand for closed-loop processing platforms.
United Kingdom
NHS procurement centralization favors enterprise-tier suppliers capable of nationwide service coverage and training infrastructure. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance alignment with EU MDR technical documentation standards. London and Manchester cardiac surgery networks negotiate volume guarantees in exchange for extended payment terms.
Auto-Transfusion Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the auto-transfusion systems landscape. The vendor base consolidates around three to five integrated platform suppliers commanding installed base lock-in through proprietary consumable ecosystems. Strategic archetypes separate full-stack perfusion technology providers from modular component specialists and regional distribution-focused assemblers. Dominant competitive moves include backward integration into blood processing consumables and subscription-based predictive maintenance service tiers.
Within the full-stack tier, Haemonetics Corporation and LivaNova PLC exemplify platform-centric positioning anchored by cardiac surgery workflow integration. Fresenius SE & Co. KGaA occupies a distinct archetype through upstream control over blood processing consumables. These three entities represent contrasting paths to recurring revenue capture across North American and European hospital networks.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| LivaNova PLC |
| Fresenius SE & Co. KGaA |
| Medtronic |
| BD |
| Teleflex Incorporated |
| Zimmer Biomet |
| B. Braun SE |
| SARSTEDT AG & Co. KG |
| Others |
Cost & Logistics Intelligence
Hospital procurement consolidation into multi-year enterprise agreements across United States health systems exceeding 500 beds forces manufacturers to bundle hardware with consumable commitments and service tiers, compressing upfront device margins while extending payment terms and locking in recurring revenue streams.
Pricing Analysis
Margin tightening in automated systems reflects the shift from capital equipment sales toward subscription-based predictive maintenance and consumable attach rates. Three-tier pricing structure across premium closed-loop platforms, standard cell salvage devices, and economy modular configurations differentiates by automation level and FDA clearance tier. Cost-down pressure on consumable bundles accelerates because proprietary tubing sets and collection reservoirs account for 60-70% of lifetime ownership costs. Ambulatory surgical centers exhibit highest price sensitivity; tertiary cardiac centers show lowest due to per-procedure reimbursement adequacy.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise-tier demand from academic medical centers, while regional distributors serve mid-tier hospital networks and surgical centers. Manufacturing concentrates in Germany and the United States for electromechanical platforms, with leukodepletion filter membrane production anchored in European specialty material suppliers. Component dependencies include centrifugal processing bowls, anticoagulant tubing sets, and optical sensor arrays. Single-source vulnerability in European filter membrane supply exposes downstream assemblers to input volatility. Distribution runs through authorized service partners for installation, training, and preventive maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leukodepletion filter supply concentration among three European specialty material suppliers props pricing power for integrated platform manufacturers, constraining margin expansion for device assemblers lacking captive consumable production.
For Market Incumbents: Lock in installed base retention through backward integration into blood processing consumables and predictive maintenance subscription tiers that reduce customer switching costs. Counter emerging modular component specialists by embedding proprietary data formats that resist seamless EMR connectivity. Prioritize notified body relationship consolidation in Germany to navigate EU MDR documentation burdens that disproportionately burden smaller competitors. For New Entrants and Emerging Players: Regional distributors in India's Maharashtra and Karnataka cardiac surgery clusters offer partnership pathways to bypass direct sales infrastructure requirements. Target greenfield tertiary centers under Ayushman Bharat scheme deployment for automated closed-loop platforms where incumbent presence remains limited. Differentiate through trauma field portability and military medical evacuation scenarios that established players have underdeveloped. For Investors and Strategic Acquirers: The window for entry favors mid-cap device assemblers with ISO 13485 certification infrastructure and established European notified body relationships. Long-term viability hinges on recurring revenue capture from consumable ecosystems rather than transactional hardware sales. Monitor FDA 510(k) clearance timeline extensions for novel processing algorithms as inflection indicator for regulatory consulting expenditure inflation and competitive moat widening.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Pathway | Accelerates notified body consolidation among German cardiac surgery device portfolios. |
| Predictive Maintenance Subscription Tier | Captures recurring revenue from mid-tier hospital networks previously served by basic contracts. |
| Hospital System Partnership | Boston and Cleveland academic medical centers pioneer multi-year enterprise bundling agreements. |
| Software Companion Development | AI-driven hematocrit prediction algorithms reduce processing variability between novice and experienced perfusionists. |
| Reimbursement Strategy | CMS coding alignment for autologous blood recovery determines ambulatory surgical center adoption economics. |
Research Approach
Independent corroboration across perfusionist interviews, hospital purchasing committee discussions, and biomedical engineering consultations underwrites the qualitative findings. Primary fieldwork captured perspectives from clinical perfusionists, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries. Bottom-up procedure volume modeling triangulated against top-down equipment installed base estimates.
Comparable-period anchoring to historical replacement cycle data and consumable attach rate trends structured the projection framework across the analysis window. Segmentation dimensions modeled include product architecture tier, automation level, surgical application, and end-user facility type. CAGRs derived from weighted average of equipment replacement velocity and consumable consumption intensity. Forecast inputs incorporated EU MDR compliance cost pass-through assumptions and CMS reimbursement coding evolution trajectories.
Caveats apply where FDA 510(k) predicate device pathway complexity or leukodepletion filter supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding hospital capital expenditure recovery and perfusionist workforce training pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Global Medical Composite Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Struts Implants Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Cyberknife Market