
 Struts Implants Market | 2026-2036
Struts Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Struts Implants Market Analytics
Patient-specific implant design is tilting struts manufacturing toward additive production workflows and digital surgical planning. Medtronic leverages integrated navigation-to-implant ecosystems to lock in hospital system contracts. Globus Medical sustains R&D intensity in expandable cage-strut hybrids. Stryker anchors its position through broad trauma-to-spine portfolio breadth.
Struts implants are structural scaffolds inserted during orthopedic, cardiovascular, or trauma procedures to maintain anatomical alignment under physiological load, typically fabricated from titanium alloys, PEEK polymers, or resorbable composites with porosity engineered between 60-80% to permit osseointegration. Non-absorbable metal struts dominate current surgical volume due to proven fatigue resistance and radiolucency compatibility, while biodegradable polymer variants represent the fastest-growing material segment as surgeons seek to eliminate secondary removal procedures. Hospitals command the largest end-user share through centralized procurement and bundled payment structures, though outpatient facilities are gaining traction for less complex strut-augmented interventions.
FDA 510(k) premarket notification and EU MDR technical documentation requirements enforce biocompatibility validation and fatigue testing standards that extend development timelines for new entrants. ISO 5834 and ASTM F2077 provide material-specific benchmarks that manufacturers must satisfy for market access across multiple jurisdictions. Stakeholders should monitor how evolving reimbursement codes for same-day spine procedures reshape site-of-service economics and struts implant selection criteria.
Market Dynamics
Patient-specific additive manufacturing is compressing traditional production timelines while FDA 510(k) clearance pathways and EU MDR technical documentation requirements extend commercialization cycles for new entrants. This structural tension between customization velocity and regulatory rigor defines current competitive positioning.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification for predicate-based struts implants accelerates hospital procurement cycles in the United States. Titanium alloy devices with established fatigue resistance profiles clear faster than novel materials.
- Germany's Hospital Procurement Centralization:Bundled payment structures under Diagnosis-Related Group reforms concentrate purchasing power, favoring suppliers with comprehensive trauma-to-spine portfolios.
- PEEK Polymer Osseointegration:Radiolucent polymer struts with engineered 60-80% porosity enable post-operative imaging clarity that metal implants cannot match, driving adoption in spinal fusion procedures.
Market Restraints
- Titanium Sponge Supply Concentration:Russian and Ukrainian feedstock disruptions have destabilized titanium alloy pricing, squeezing margins for manufacturers dependent on vacuum arc remelting processes.
- EU MDR Technical Documentation Burden:Enhanced clinical evidence requirements for Class III implantable devices extend CE marking timelines by 18-24 months, freezing product pipelines for mid-tier manufacturers.
- Bioresorbable Polymer Degradation Uncertainty:Variable in-vivo resorption rates for polylactic acid struts create liability exposure and slow surgeon adoption despite elimination of secondary removal procedures.
Strategic Opportunities
- Japan's Super-Aged Society:METI reimbursement incentives for minimally invasive spine procedures expand the surgical candidate pool beyond traditional age cutoffs, creating demand for expandable cage-strut hybrids.
- Same-Day Surgery Site Migration:Outpatient facilities in Texas and Florida are gaining traction for less complex strut-augmented interventions, bypassing hospital bundled payment constraints.
- Digital Surgical Planning Integration:Convergence of pre-operative CT segmentation with additive manufacturing workflows enables anatomically matched implants that command premium positioning.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Limited workforce proficiency in electron beam melting and selective laser sintering constrains production scaling for patient-specific geometries.
- ISO 5834 Fatigue Testing Bottlenecks:Certified testing laboratory capacity shortages delay biocompatibility validation, compressing launch windows against competitor patent cliffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Struts Implants Market |
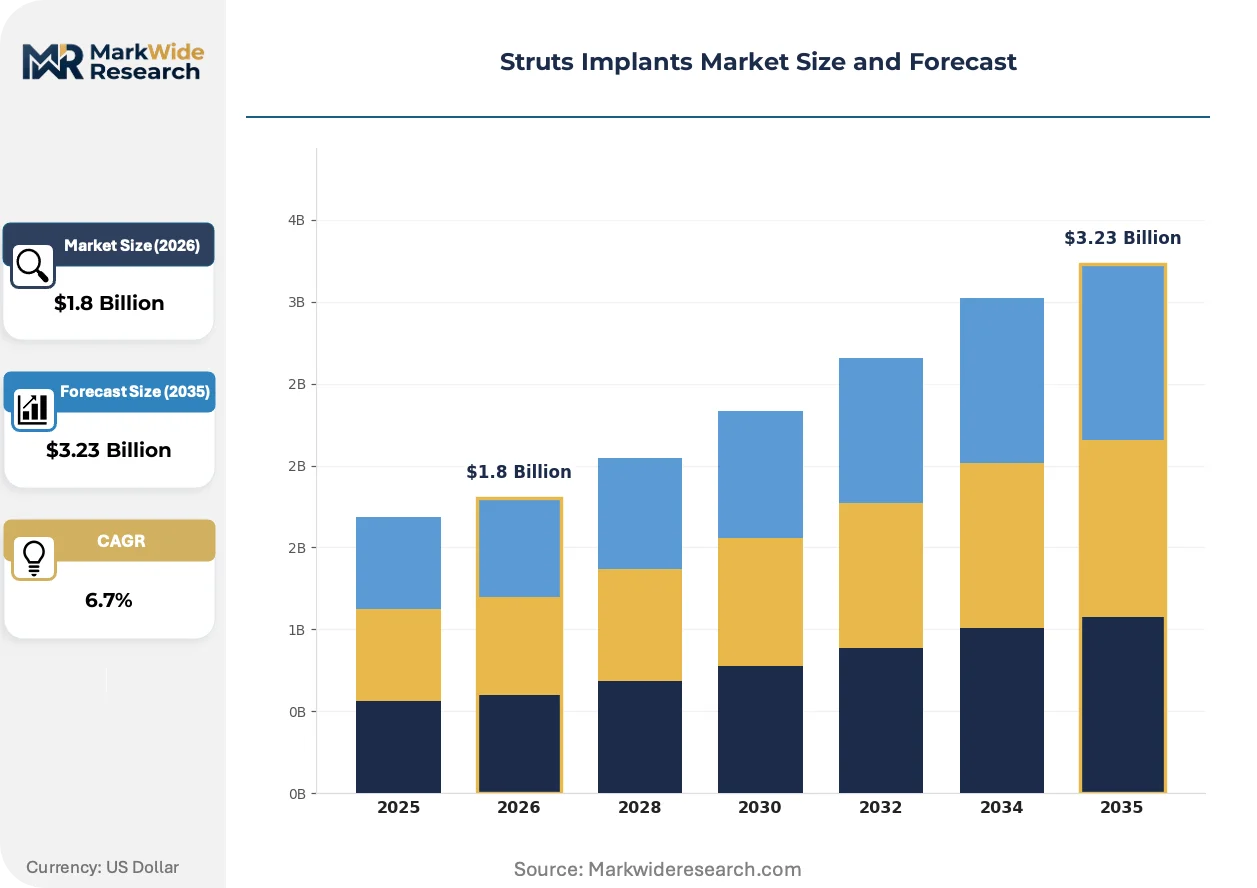
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Struts, Non-Absorbable Struts, Biodegradable Struts, Custom Struts Material: Polymer, Metal, Composite, Ceramics End User: Hospitals, Clinics, Outpatient Facilities, Rehabilitation Centers Application: Orthopedic Surgery, Cardiovascular Procedures, Trauma Surgery, Dental Surgery |
| Companies Covered | Medtronic, Globus Medical, Alphatec Spine, Johnson & Johnson, Stryker, Zimmer Biomet, NuVasive, B. Braun, Orthofix Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Struts Implants Market Evolving Landscape
Digital thread integration from imaging to implantation is collapsing traditional manufacturing lead times while regulatory harmonization efforts across FDA and EU MDR frameworks create compliance complexity. Material science advances and site-of-service economics are simultaneously reshaping product specifications and distribution priorities.
Titanium lattice structures with gyroid architecture are hybridizing load-bearing performance with osseointegration channels previously requiring separate processing steps. Academic medical centers in Boston and Heidelberg are piloting these geometries for complex deformity corrections. The technology is hybridizing conventional subtractive machining with additive workflows, compressing toolpath programming from weeks to days.
EU MDR Article 10 technical documentation mandates now require periodic safety update reports for implantable devices, forcing manufacturers to maintain post-market surveillance infrastructure that exceeds prior Medical Device Directive obligations. German notified bodies have consolidated under this framework, reducing certification channel capacity. High-volume struts producers are responding by pre-submitting clinical data packages to streamline conformity assessment.
Hospital value analysis committees now mandate radiolucency compatibility and fatigue testing documentation before contract inclusion, displacing traditional surgeon preference-based selection. Integrated delivery networks in California and New York are consolidating vendor lists to three approved suppliers per implant category. This concentration is most visible in academic medical centers where procurement standardization reduces variation in surgical supply chains.
Struts Implants Market Segmentation
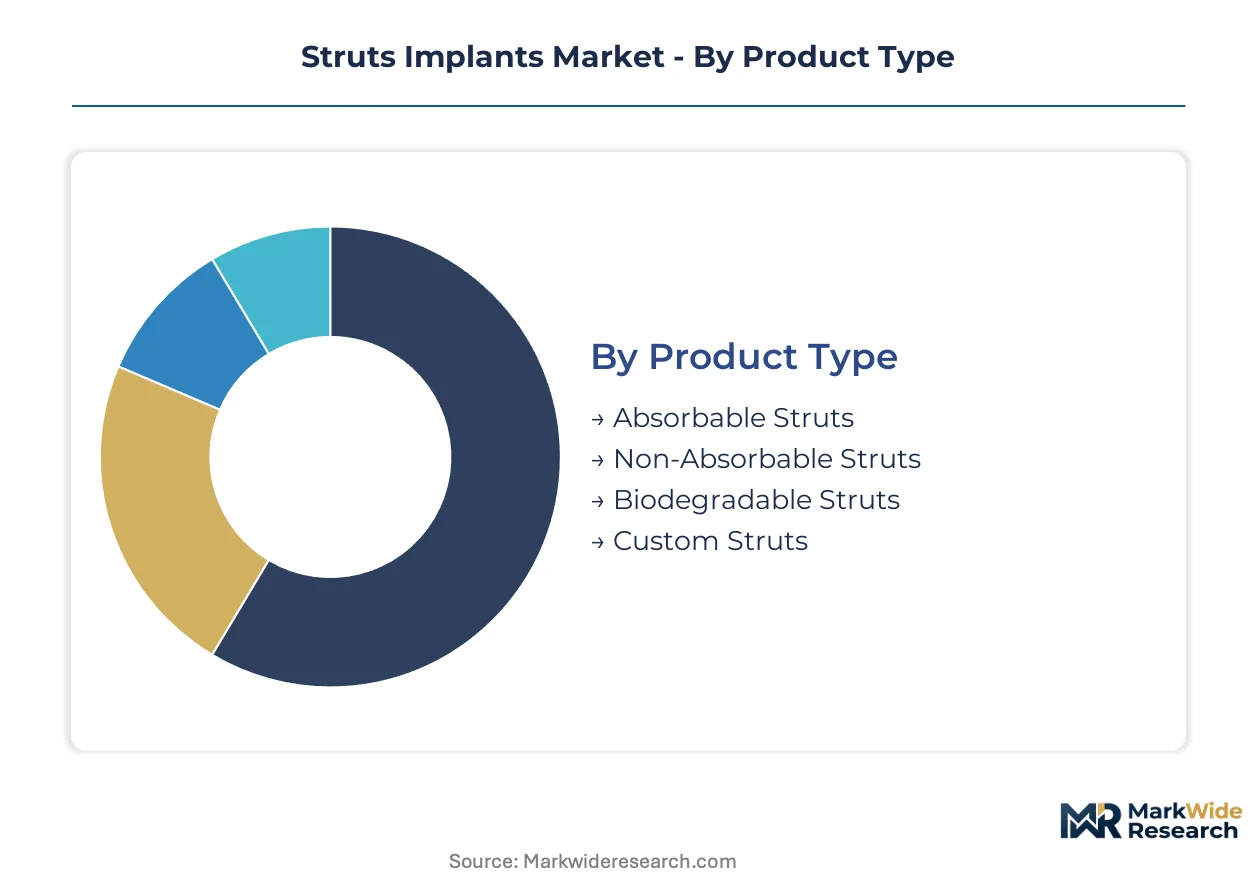
Struts implant segmentation reveals how material science innovation and site-of-service economics reshape procurement patterns. Manufacturers align product portfolios across absorbability spectra, structural compositions, and procedural settings to capture diverging reimbursement incentives.
Product Type:
Mature non-absorbable platforms anchor hospital purchasing contracts while emerging biodegradable formats attract outpatient migration strategies.
- Absorbable Struts:Polylactic acid and polyglycolic acid constructs degrade through hydrolysis over 12-24 months, eliminating secondary removal procedures. Demand concentrates in pediatric orthopedic applications at academic medical centers in Germany and Japan where growth plate preservation drives adoption. Variable resorption rates create liability exposure that slows surgeon uptake despite procedural efficiency gains.
- Non-Absorbable Struts:Titanium alloy and PEEK polymer scaffolds provide permanent structural support with established fatigue resistance profiles. These devices dominate spinal fusion volumes at US hospitals where bundled payment structures favor proven durability over material innovation. FDA 510(k) predicate pathways accelerate procurement cycles for titanium variants with decade-long clinical track records.
- Biodegradable Struts:Magnesium alloy formulations offer strength-to-weight ratios approaching titanium with controlled corrosion kinetics. Early adoption clusters in cardiovascular stent-graft applications at European research hospitals.
- Custom Struts:Patient-specific geometries fabricated through electron beam melting match complex deformity anatomies. Additive production workflows compress design-to-implant timelines from weeks to days at Boston and Heidelberg surgical planning centers.
Non-absorbable struts retain volume leadership; biodegradable struts hold the steepest expansion curve.
Material:
Cost tier stratification separates premium radiolucent polymers from commodity metal feedstocks, with composite hybrids commanding mid-tier positioning.
- Polymer:PEEK and carbon-fiber-reinforced PEEK deliver radiolucency that enables post-operative CT and MRI clarity impossible with metal alternatives. These materials capture premium pricing in spinal fusion procedures where imaging follow-up protocols mandate artifact-free visualization.
- Metal:Titanium alloys processed through vacuum arc remelting provide fatigue resistance exceeding 10 million cycles under physiological loading. Russian and Ukrainian titanium sponge supply disruptions have destabilized pricing for manufacturers dependent on traditional feedstock channels.
- Composite:Polymer-ceramic and metal-polymer hybrids combine load-bearing performance with tunable modulus matching. Early clinical traction appears in trauma plating systems where stress shielding reduction improves bone remodeling outcomes.
- Ceramics:Alumina and zirconia formulations offer extreme hardness for dental implant strut applications. Brittle fracture risk constrains expansion beyond maxillofacial reconstruction niches.
Metal alloys dominate procurement volumes; polymer variants gain share fastest in radiolucency-sensitive applications.
End User:
Customer type determines contract structure complexity, with centralized hospital purchasing contrasting fragmented outpatient facility procurement.
- Hospitals:Integrated delivery networks consolidate vendor lists to three approved suppliers per implant category, demanding comprehensive trauma-to-spine portfolios. Value analysis committees mandate fatigue testing documentation and radiolucency compatibility before contract inclusion.
- Clinics:Specialized orthopedic and cardiovascular clinics prioritize surgeon preference and rapid device availability over procurement standardization. These settings favor established non-absorbable platforms with predictable reimbursement coding.
- Outpatient Facilities:Ambulatory surgery centers in Texas and Florida bypass hospital bundled payment constraints for less complex strut-augmented interventions. Same-day spine procedure reimbursement expansion drives capital equipment investment in these settings.
- Rehabilitation Centers:Post-acute facilities focus on external fixation and temporary bracing systems rather than permanent implant provision. Demand concentrates in trauma recovery protocols requiring staged surgical intervention.
Hospitals command contract value leadership; outpatient facilities trace the steepest volume growth trajectory.
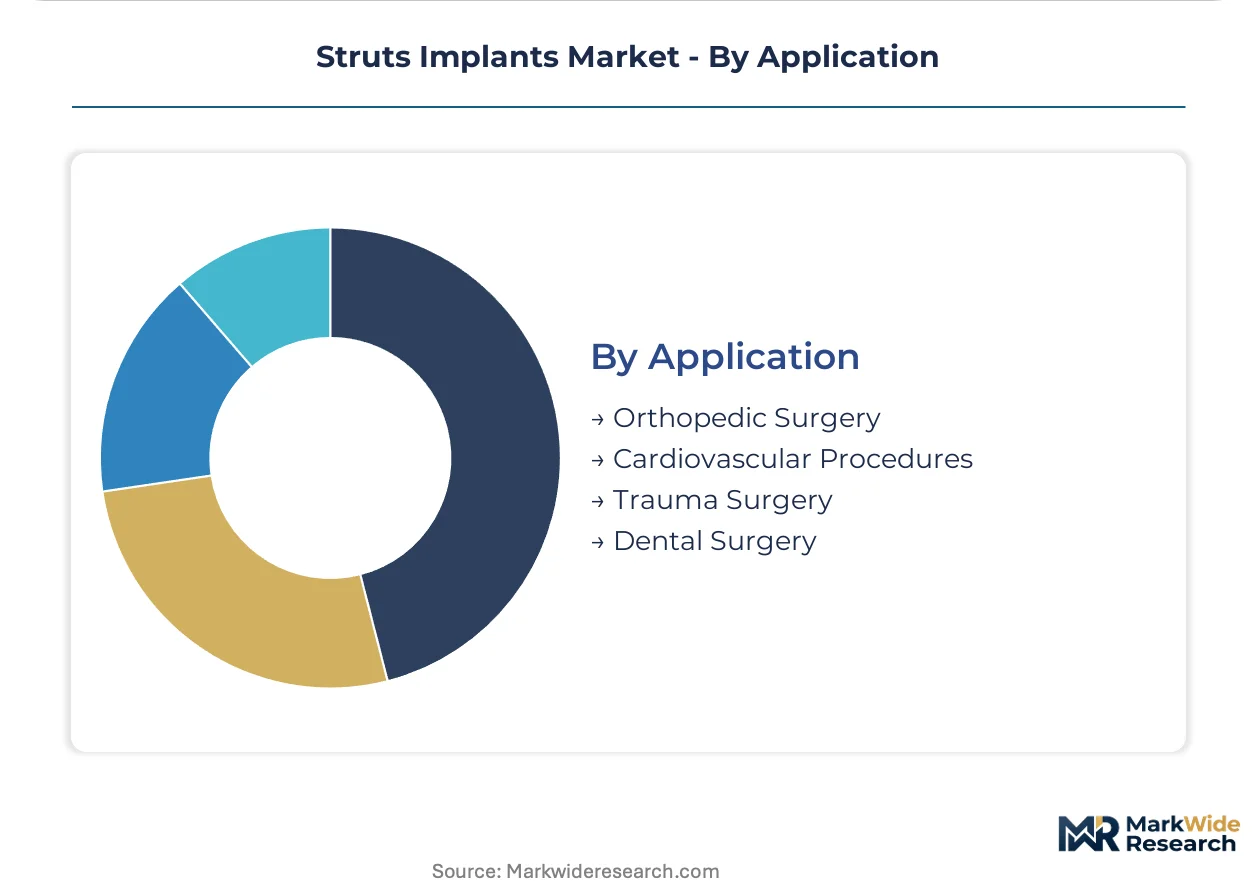
Application:
Application segmentation aligns with procedural reimbursement codes and regulatory pathway complexity across surgical specialties.
- Orthopedic Surgery:Spinal fusion and deformity correction procedures consume the largest strut implant volumes, with expandable cage-strut hybrids gaining traction in minimally invasive approaches. METI reimbursement incentives in Japan expand surgical candidacy beyond traditional age cutoffs.
- Cardiovascular Procedures:Stent-graft and transcatheter valve applications require biocompatible strut architectures with fatigue resistance under cyclic vascular loading. Magnesium biodegradable formats attract early adoption in pediatric congenital repair.
- Trauma Surgery:Fracture fixation and pelvic reconstruction demand rapid implant availability with standardized sizing. Military medical centers prioritize titanium lattice structures for blast injury management.
- Dental Surgery:Alveolar ridge preservation and implant site development utilize smaller-format struts with osseointegration-optimized surfaces. Ceramic formulations compete in aesthetic zone applications where metal show-through concerns arise.
Orthopedic surgery retains procedural volume leadership; cardiovascular applications demonstrate the most rapid technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement centralization and aging demographics concentrate demand in three national markets. Regulatory pathway efficiency and reimbursement structures determine commercialization velocity across these territories.
United States
FDA 510(k) premarket notification pathways accelerate clearance timelines for predicate-based titanium alloy devices. Bundled payment structures under CMS programs concentrate purchasing power within integrated delivery networks. Academic medical centers in Boston and New York Metro pilot patient-specific additive manufacturing workflows for complex deformity corrections.
Germany
Diagnosis-Related Group reforms under the national hospital payment system favor suppliers with comprehensive trauma-to-spine portfolios. EU MDR technical documentation requirements extend CE marking timelines, freezing pipelines for mid-tier manufacturers. The Heidelberg surgical planning cluster advances digital thread integration from CT segmentation to electron beam melting production.
Japan
METI reimbursement incentives for minimally invasive spine procedures expand surgical candidacy beyond traditional age cutoffs in this super-aged society. PMDA regulatory harmonization efforts with FDA frameworks streamline approval pathways for established device categories. The Kanto region around Tokyo hosts the highest concentration of expandable cage-strut hybrid adoption.
United Kingdom
NHS England value analysis committees mandate fatigue testing documentation and radiolucency compatibility before contract inclusion. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while preserving UK-specific conformity assessment routes. London and Southeast England surgical hubs concentrate demand for PEEK polymer struts in spinal fusion procedures.
Switzerland
Swissmedic certification requirements enforce ISO 5834 biocompatibility benchmarks that exceed baseline EU thresholds. Premium pricing tolerance in this market attracts manufacturers positioning patient-specific custom struts. The Basel and Zurich medical technology clusters support prototyping workflows for titanium lattice structures with gyroid architecture.
Struts Implants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The market structure consolidates around integrated navigation-to-implant ecosystems and broad trauma-to-spine portfolio breadth. Two strategic archetypes dominate: diversified medtech conglomerates leveraging hospital system contracts, and spine-focused specialists sustaining R&D intensity in expandable cage-strut hybrids. M&A activity and digital surgical planning integration represent the dominant competitive moves.
Among diversified medtech conglomerates, Medtronic and Stryker occupy positions anchoring hospital procurement through integrated delivery network contracts. Globus Medical exemplifies the spine-specialist archetype with concentrated R&D positioning. These three entities represent the competitive spectrum from ecosystem breadth to segment depth.
| Leading Market Players |
|---|
| Medtronic |
| Globus Medical |
| Alphatec Spine |
| Johnson & Johnson |
| Stryker |
| Zimmer Biomet |
| NuVasive |
| B. Braun |
| Orthofix Holdings |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors connecting Shanghai to Long Beach transmit titanium sponge cost volatility directly into implant pricing tiers, compressing margins for manufacturers locked into long-term hospital contracts while enabling premium positioning for suppliers with captive feedstock sources.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange titanium pricing dominate procurement between struts manufacturers and integrated delivery networks. Pricing stratifies across premium radiolucent PEEK tiers, standard titanium alloy platforms, and economy-grade stainless steel alternatives. Cost compression in standard titanium segments is intensifying because Russian and Ukrainian sponge supply disruptions force secondary sourcing at elevated spot rates. Academic medical centers demonstrate the lowest price sensitivity due to bundled payment insulation, while ambulatory surgery centers in Texas and Florida exhibit acute cost consciousness.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for struts implant manufacturers. Production gravity centers on the United States, Germany, and Japan for finished devices, while titanium sponge feedstock draws from Kazakhstan, Japan, and Saudi Arabia. Vacuum arc remelting capacity and electron beam melting equipment constitute critical component dependencies. Single-source vulnerability in certified testing laboratory capacity for ISO 5834 fatigue validation constrains new product launches. Distribution runs through group purchasing organizations and integrated delivery network central warehouses to hospital value analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital surgical planning subscriptions and post-market surveillance services are expanding at double the rate of hardware revenue, transforming struts implant commercialization from transactional device sales into recurring-revenue platform relationships.
For Market Incumbents: Build ecosystem lock-in through navigation-to-implant software integration that embeds proprietary struts geometries into surgical workflow. Consolidate position by acquiring electron beam melting capacity in the United States to insulate against titanium supply volatility. Counter the threat of mid-tier additive manufacturing specialists by pre-submission of clinical data packages to German notified bodies under EU MDR Article 10 requirements. For New Entrants and Emerging Players: Outpatient spine facilities in Florida and Texas represent the most penetrable entry point for bypassing hospital bundled payment constraints. Pediatric orthopedic applications in German academic medical centers offer white-space demand for absorbable polylactic acid struts with growth plate preservation claims. Capture initial share through rapid-turn custom strut production enabled by CT-to-implant digital thread workflows. For Investors and Strategic Acquirers: Additive manufacturing service bureaus with FDA-registered quality systems and electron beam melting capacity represent the highest-conviction acquisition archetype. Frame long-term viability around the 5-10 year window for biodegradable magnesium alloy regulatory validation and reimbursement establishment. Monitor PMDA-METI harmonization announcements as the inflection signal for Japanese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts lock in three-year procurement commitments with exclusive vendor status. |
| CE Marking Pathway | EU MDR technical documentation pre-submission to German notified bodies accelerates conformity assessment timelines. |
| Software Companion Development | Digital surgical planning integration embeds proprietary implant geometries into pre-operative CT segmentation workflows. |
| Backward Integration into Titanium | Captive vacuum arc remelting capacity insulates margin compression from Kazakhstan-Japan sponge supply volatility. |
| Reimbursement Strategy | CPT code expansion for same-day spine procedures in CMS programs enables ambulatory surgery center market entry. |
Research Methodology
Cross-validation between surgeon interviews and hospital procurement database analysis anchors the qualitative findings in operational reality. Primary fieldwork engaged spine surgeons, biomedical engineers, GPO contracts managers, and value analysis committee chairs across Boston, New York Metro, and Heidelberg clusters. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, and CMS Medicare reimbursement coding updates. Bottom-up demand modeling triangulated against top-down titanium alloy consumption estimates from trade flow data.
Calibration against historical procedure volume elasticities and material substitution patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include absorbability profile, material composition, end-user facility type, and procedural application. CAGRs were derived from regression analysis of implant unit economics against demographic surgical candidacy expansion. Forecast inputs incorporated METI reimbursement incentive trajectories and DRG bundled payment evolution in German hospital systems.
Stress conditions across titanium sponge supply disruption severity, EU MDR certification timeline extension, and same-day spine procedure reimbursement expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PMDA-FDA harmonization progress and biodegradable polymer degradation rate standardization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endocavity Transducer Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Middle Ear Implants Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
United States Minimally Invasive Surgery Device Market