
 South Africa Ultrasound Devices Market | 2026-2036
South Africa Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Ultrasound Devices Market Analytics
Radiographer and sonographer training pipelines is bifurcating the market into equipment-rich urban centers and underserved rural districts. Siemens Healthineers AG leverages its installed base of cart-based systems to sustain service contracts across South Africa's academic hospital complexes. GE Healthcare anchors its position through localized technical support networks that reduce equipment downtime for high-volume obstetric units.
Ultrasound devices generate real-time anatomical images through piezoelectric transducer arrays operating at frequencies between two and eighteen megahertz, with beamforming algorithms processing reflected acoustic echoes for diagnostic visualization. Cart-based systems dominate capital procurement budgets due to their advanced Doppler and 4D imaging capabilities, while portable and handheld units are capturing expanded placement in emergency departments and remote clinic outreach programs. Application demand concentrates in obstetrics and cardiology, where non-invasive screening protocols create recurring volume for equipment operators.
SAHPRA governs medical device registration and post-market surveillance, enforcing compliance with IEC 60601 safety standards and ISO 13485 quality management systems that manufacturers must satisfy for market authorization. The South African Bureau of Standards (SBS) adopts harmonized electromagnetic compatibility testing protocols that add certification layers for imported ultrasound platforms. Stakeholders must monitor NHI procurement framework evolution and radiology tariff restructuring to align capital deployment with reimbursement trajectories.
Market Dynamics
The National Health Insurance procurement framework is concentrating purchasing authority within South Africa's provincial health departments, forcing ultrasound vendors to restructure distribution channels around centralized tender processes rather than direct hospital sales relationships.
Growth Catalysts
- SAHPRA Registration Streamlining:The regulator's risk-based classification pathway accelerates market authorization for Class II diagnostic ultrasound systems, reducing time-to-market for manufacturers targeting maternal health applications.
- Obstetric Screening Protocols:Expanded antenatal care mandates in Gauteng and KwaZulu-Natal provincial health plans create recurring equipment demand across public maternity wards.
- Cardiac Imaging Backlogs:Diagnostic chains in Johannesburg and Cape Town metropolitan corridors are deploying additional Doppler-capable systems to address echocardiography appointment queues exceeding twelve weeks.
Market Restraints
- Import Tariff Structure:Harmonized System code 9018.12.90 attracts duties between zero and fifteen percent depending on country of origin, compressing margin structures for European and Asian manufacturers without preferential trade agreements.
- Transducer Supply Concentration:Piezoelectric crystal arrays and matching layer materials concentrate among three East Asian component suppliers, exposing South African assemblers to shipping cost volatility and extended lead times.
- Rural Infrastructure Deficits:Unreliable grid power in Limpopo and Eastern Cape districts limits deployment of high-wattage cart-based systems, restricting market penetration to solar-compatible portable units with reduced imaging depth.
Strategic Opportunities
- Point-of-Care Emergency Adoption:Trauma units in Durban and Pretoria academic hospitals are integrating handheld ultrasound for FAST protocols, creating placement opportunities outside traditional radiology departments.
- NHI Reimbursement Alignment:The phased rollout of uniform tariff codes for diagnostic imaging creates predictable revenue streams for equipment operators who achieve preferred supplier status under provincial contracting frameworks.
- Rural Telemedicine Integration:Combination of portable ultrasound with cellular-connected image transmission enables diagnostic support from urban sonographers to clinic nurses in Mpumalanga and Northern Cape districts.
Industry Challenges
- Sonographer Training Bottlenecks:Council for Medical Schemes accreditation requirements limit the annual pipeline of certified operators, constraining equipment utilization rates even where capital procurement budgets exist.
- Legacy System Interoperability:PACS integration with existing hospital information systems requires customized middleware development, extending deployment timelines and inflating total cost of ownership for replacement purchases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Ultrasound Devices Market |
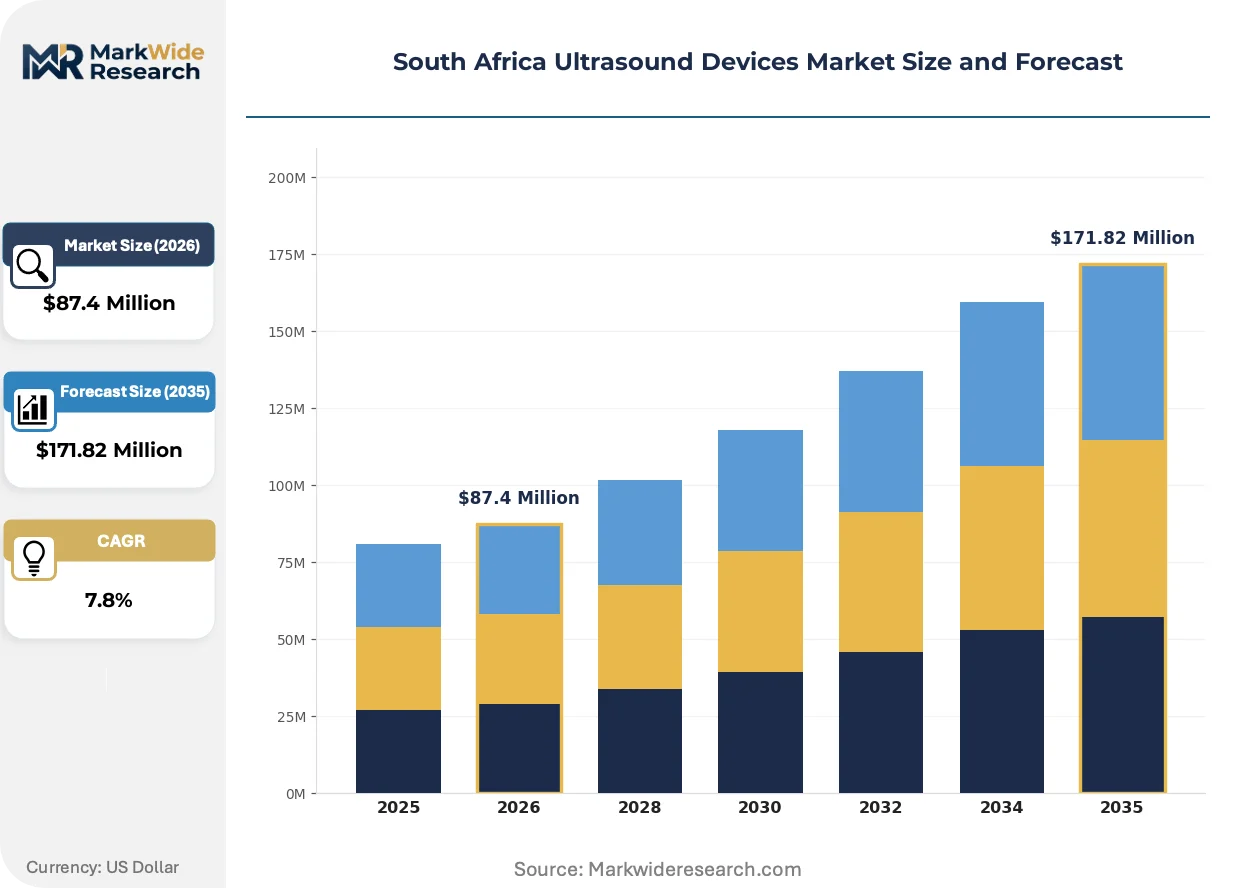
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $171.82 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Handheld, Cart-based, Console Technology: 2D, 3D, Doppler, 4D Application: Cardiology, Obstetrics, Urology, Emergency End User: Hospitals, Diagnostic Clinics, Research Institutions, Specialty Centers |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Koninklijke Philips N.V., Samsung Medison Co. Ltd, Mindray Medical International Ltd, Hitachi Ltd, Esaote SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Ultrasound Devices Market Evolving Landscape
Artificial intelligence inference engines are embedding directly into ultrasound hardware, automating anatomical measurements and standardizing image acquisition protocols across operators with varying skill levels.
Beamforming architecture is decomposing from hardware-dependent FPGA arrays into software-defined processing pipelines running on GPU clusters. Tertiary hospital networks in Johannesburg are piloting these platforms to reduce per-unit electronics cost while enabling post-purchase feature activation through firmware licenses. This modular approach is compressing capital expenditure cycles and allowing radiology departments to defer advanced Doppler functionality until clinical volume justifies the upgrade.
SAHPRA's alignment with International Medical Device Regulators Forum harmonization initiatives is converging South African technical documentation requirements with Australian TGA and Health Canada pathways. Manufacturers holding existing approvals from these reference regulators now qualify for accelerated review timelines. Diagnostic equipment distributors are restructuring regulatory affairs teams around this mutual recognition framework to compress product launch schedules.
Service contract unbundling is fragmenting the traditional bundled purchase model where equipment, installation, and maintenance were single-tender items. Private diagnostic chains in Cape Town and Durban are separating hardware acquisition from technical support procurement, awarding multi-year service agreements to independent biomedical engineering firms rather than original equipment manufacturers. This disintermediation is most pronounced in high-volume obstetric units where downtime tolerance approaches zero and local response time outweighs brand loyalty.
South Africa Ultrasound Devices Market Segmentation
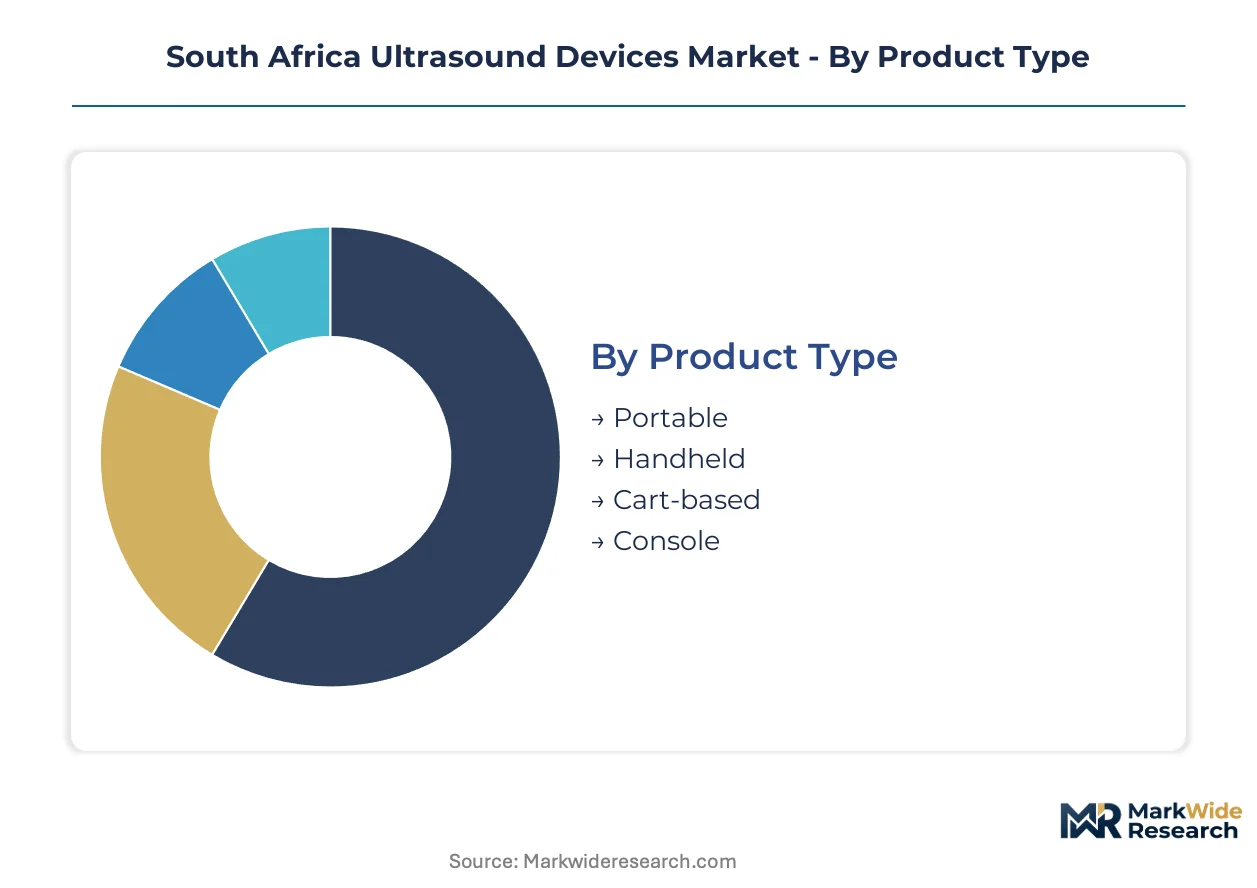
Ultrasound device segmentation in South Africa reflects divergent procurement pathways between public health infrastructure and private diagnostic networks. Channel dynamics determine which product configurations gain traction across academic hospital complexes versus independent clinic chains.
Product Type:
Portable units flow through emergency department procurement channels. Cart-based systems dominate centralized provincial tender processes.
- Cart-based:High-wattage systems with advanced beamforming arrays anchor capital budgets at Charlotte Maxeke and Groote Schuur academic hospitals. Gauteng provincial health departments prioritize these configurations for high-volume obstetric wards despite grid reliability constraints in peri-urban installations.
- Portable:Battery-operated platforms with reduced imaging depth capture placement in Eastern Cape district hospitals where solar-compatible power profiles override raw performance specifications. KwaZulu-Natal outreach programs deploy these units for mobile antenatal screening.
- Handheld:Smartphone-connected probes enable FAST protocols at Pretoria trauma centers.
- Console:Premium configurations serve Johannesburg private diagnostic chains with dedicated echocardiography suites.
Cart-based systems dominate installed base. Portable configurations are where expansion concentrates.
Technology:
Cost tiers separate basic screening applications from premium diagnostic workflows. Reimbursement alignment under NHI frameworks favors standardized acquisition protocols.
- Doppler:Velocity measurement algorithms process frequency-shifted echoes for cardiac output quantification. Cape Town diagnostic chains deploy these systems to address echocardiography backlogs exceeding twelve weeks.
- 4D:Real-time volumetric rendering enables fetal anomaly detection at Tygerberg Hospital maternal-fetal medicine units. Western Cape provincial budgets prioritize this capability for tertiary referral centers.
- 2D:Conventional grayscale imaging satisfies basic antenatal screening protocols.
- 3D:Static volumetric reconstruction supports urological intervention planning.
Doppler capability anchors premium pricing tiers. 4D functionality is climbing the fastest among technology upgrades.
Application:
Volume concentration varies by metropolitan corridor and provincial health priority. Maternal health mandates reshape equipment allocation across public maternity networks.
- Obstetrics:Transabdominal and transvaginal probe configurations address antenatal screening volumes at Chris Hani Baragwanath maternity complex. Gauteng health department procurement specifications mandate minimum frame rates for fetal cardiac assessment.
- Cardiology:Transthoracic and transesophageal echo protocols require specialized probe arrays. Durban private cardiology practices invest in stress-echo capabilities to capture NHI-aligned tariff codes.
- Emergency:FAST examination protocols drive handheld adoption at Pietermaritzburg trauma units.
- Urology:Transrectal imaging supports prostate intervention guidance at urology specialty centers.
Obstetrics commands the largest equipment allocation. Cardiology is gaining share fastest among application expansions.
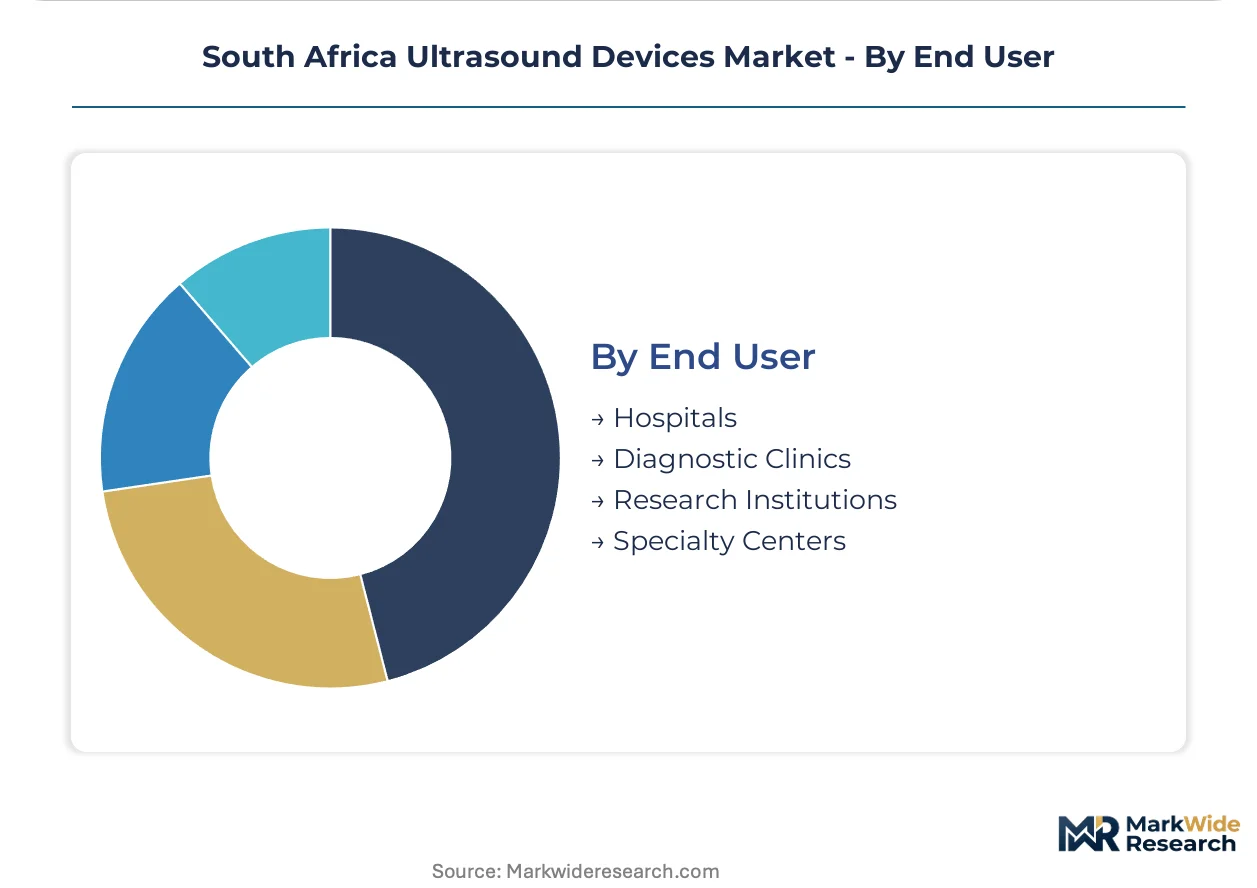
End User:
Customer type determines service contract structures and technical support expectations. Procurement authority concentration under NHI frameworks reshapes vendor-hospital relationships.
- Hospitals:Academic complexes with in-house biomedical engineering departments unbundle service agreements from hardware acquisition. Steve Biko Academic Hospital maintains captive technical capacity for probe repair and preventive maintenance.
- Diagnostic Clinics:Independent chains in Johannesburg and Cape Town metropolitan corridors prioritize response-time guarantees over manufacturer brand loyalty. These operators separate equipment purchase from multi-year service procurement.
- Specialty Centers:Cardiac and maternal-fetal medicine facilities concentrate high-end system deployment.
- Research Institutions:University medical schools pilot AI-embedded beamforming platforms for clinical validation studies.
Hospitals retain the deepest installed base. Diagnostic clinics are where vendor disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial health departments across South Africa deploy ultrasound capacity unevenly, with Gauteng and Western Cape concentrating cart-based systems for tertiary care while Limpopo and Eastern Cape rely on portable units for grid-constrained outreach.
Gauteng
Johannesburg academic hospitals anchor the deepest installed base of Doppler-capable systems. Charlotte Maxeke and Chris Hani Baragwanath maternity complexes drive obstetric equipment procurement under provincial health department tenders. SAHPRA registration pathways for Class II diagnostic systems accelerate vendor market authorization for maternal health applications.
Western Cape
Cape Town metropolitan diagnostic chains address echocardiography backlogs exceeding twelve weeks through additional system deployment. Tygerberg Hospital maternal-fetal medicine units prioritize 4D volumetric rendering capabilities for fetal anomaly detection. The provincial health budget concentrates advanced imaging at tertiary referral centers.
KwaZulu-Natal
Durban private cardiology practices invest in stress-echo capabilities to capture National Health Insurance-aligned tariff codes. Mobile antenatal screening programs deploy portable units across rural districts. Pietermaritzburg trauma units integrate handheld ultrasound for FAST examination protocols.
Eastern Cape
District hospitals prioritize solar-compatible portable platforms where grid reliability constraints override raw performance specifications. Steve Biko Academic Hospital maintains captive biomedical engineering capacity for probe repair and preventive maintenance. Rural clinic outreach depends on battery-operated systems with reduced imaging depth.
Limpopo
Unreliable grid power limits deployment of high-wattage cart-based systems to major urban centers. Mpumalanga-adjacent districts pilot cellular-connected image transmission enabling diagnostic support from urban sonographers to clinic nurses. Northern Cape outreach programs mirror this telemedicine integration model.
South Africa Ultrasound Devices Market Competitive Landscape
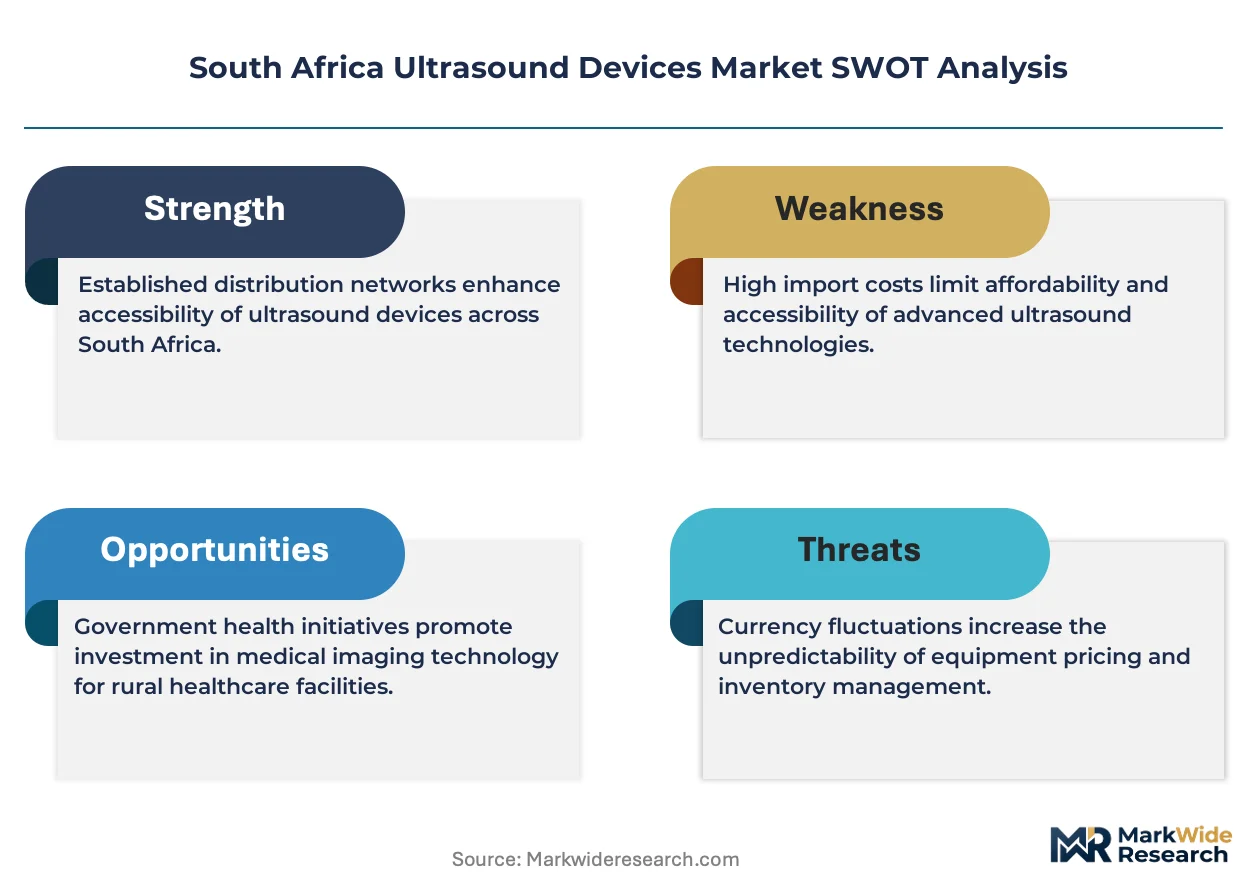
A small set of integrated leaders sits above a broader specialist tier in South Africa's ultrasound devices market. Siemens Healthineers AG and GE Healthcare anchor the premium cart-based segment through established service networks and academic hospital relationships. Mid-tier specialists concentrate on portable configurations for rural outreach and emergency department placement. Competitive positioning hinges on SAHPRA registration speed, localized technical support density, and unbundled service contract flexibility.
Among diversified health technology conglomerates, Siemens Healthineers AG and GE Healthcare exemplify the integrated leader archetype through sustained service contract penetration across academic hospital complexes. Canon Medical Systems Corporation occupies a position within the imaging specialist tier. Koninklijke Philips N.V. and Samsung Medison Co. Ltd represent additional anchors for equipment procurement in private diagnostic chains. Mindray Medical International Ltd exemplifies the emerging competitor archetype targeting portable system placement in resource-constrained districts.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Koninklijke Philips N.V. |
| Samsung Medison Co. Ltd |
| Mindray Medical International Ltd |
| Hitachi Ltd |
| Esaote SpA |
| Others |
Value Network & Pricing Analysis
Ninety-day transducer lead times from East Asian crystal array suppliers compress margin structures for South African distributors while amplifying pricing power among manufacturers holding strategic component inventories. This inventory asymmetry concentrates negotiating leverage with vendors who pre-position piezoelectric matching layer materials, forcing smaller assemblers toward spot-market procurement that inflates landed equipment costs.
Pricing Analysis
Long-term service contracts dominate procurement relationships between provincial health departments and cart-based system vendors, with three-tier pricing structure across premium, standard, and economy levels differentiating by Doppler capability and probe array density. Price differentiation hinges on SAHPRA registration tier and after-sales technical support density, with premium configurations commanding substantial markups for 4D volumetric rendering. Cost compression in portable segments intensifies as Mindray and domestic distributors compete for Eastern Cape district hospital tenders. Public maternity wards exhibit highest price sensitivity due to centralized NHI procurement budgets, while private Johannesburg diagnostic chains prioritize response-time guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of piezoelectric ceramics and acoustic lens materials characterizes vendor behavior given eighteen-month certification cycles for SAHPRA device registration. Component sourcing concentrates in China, South Korea, and Japan for transducer crystal arrays, matching layer polymers, and beamforming ASICs. Single-source vulnerability pervades the three East Asian suppliers controlling piezoelectric crystal production, exposing South African assemblers to shipping cost volatility and customs clearance delays at Durban port. Distribution runs through authorized medical equipment distributors with SAHPRA import licenses, who maintain regional spare probe inventories to satisfy provincial tender response-time requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as NHI procurement centralization splinters vendor relationships and creates entry points for specialized service providers. The unbundling of hardware acquisition from technical support contracts generates niche opportunities for independent biomedical engineering firms and portable system specialists.
For Market Incumbents: Shield installed base positions at Charlotte Maxeke and Groote Schuur academic hospitals through captive probe repair capabilities and preventive maintenance contracts that lock out independent service competitors. Deepen backward integration into transducer refurbishment to offset margin pressure from provincial tender price caps. Accelerate SAHPRA registration for AI-embedded beamforming platforms to maintain technology differentiation against emerging competitors.
For New Entrants and Emerging Players: SAHPRA's mutual recognition pathway with TGA and Health Canada compresses regulatory timelines for manufacturers holding existing reference approvals. Target Eastern Cape and Limpopo district hospitals where solar-compatible portable specifications override brand loyalty and service response times matter more than advanced imaging depth. Pursue direct relationships with KwaZulu-Natal mobile antenatal screening programs as a beachhead for handheld system placement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming medical imaging divisions lacking SAHPRA registration infrastructure or localized service networks. Long-term viability depends on NHI reimbursement alignment and provincial preferred supplier status rather than equipment innovation cycles alone. Watch NHI tariff code finalization as the inflection signal determining which diagnostic chains achieve predictable revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Fast-Track | Mutual recognition with TGA and Health Canada accelerates market authorization for maternal health applications. |
| Service Contract Unbundling | Independent biomedical engineering firms capture multi-year agreements from Cape Town diagnostic chains. |
| Portable System Localization | Solar-compatible battery profiles unlock Eastern Cape and Limpopo district hospital procurement channels. |
| AI-Embedded Beamforming Pilot | Johannesburg tertiary networks validate software-defined processing for deferred feature activation revenue. |
| Telemedicine Integration Partnership | Cellular-connected image transmission enables Mpumalanga diagnostic support from urban sonographer networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAHPRA device registration databases, provincial health department tender records, and hospital procurement disclosures. Primary interviews engaged radiology department heads, biomedical engineering managers at academic hospital complexes, GPO contracts administrators, and SAHPRA regulatory affairs specialists. Secondary validation drew from IEC 60601 safety standard documentation, National Health Insurance white papers, and customs import records under harmonized system code 9018.12.90. Bottom-up equipment placement counts triangulate against top-down provincial health budget allocations.
Segmentation dimensions modeled span product type, technology tier, clinical application, and end-user category across the analysis window. Obstetric and cardiology application splits incorporate provincial maternal health mandate timelines and echocardiography backlog data. CAGRs derive from equipment replacement cycles, NHI procurement volume assumptions, and rural electrification infrastructure trajectories. Forecast inputs include sonographer training pipeline capacity, transducer component lead time trends, and SAHPRA registration queue processing rates.
Underlying assumptions cover NHI phased rollout continuity, grid reliability stabilization in Limpopo and Eastern Cape districts, and sustained mutual recognition framework alignment with reference regulators, with deviation risk concentrated in provincial budget reallocation and import tariff restructuring. Revision becomes warranted when NHI procurement framework specifications cross thresholds that invalidate current vendor qualification criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Europe Biopsy Devices Market