
 Global Hematocrit Test Devices Market | 2026-2036
Global Hematocrit Test Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hematocrit Test Devices Market Foresight
The gap between premium automated hematology analyzers and commodity manual centrifuges is expanding as laboratories face divergent capital constraints and throughput requirements. Danaher leverages its life sciences platform to sustain integrated workflow solutions across hospital networks. Sysmex Corporation anchors its position through specialized optical detection systems that dominate high-volume reference labs. Abbott Laboratories competes by extending its point-of-care footprint into resource-limited settings where portability commands premium positioning.
Hematocrit test devices measure the volume percentage of red blood cells in blood samples, typically operating through centrifugal separation at standardized speeds or through impedance-based cell counting with precision thresholds below two percent variation. These instruments serve critical functions in transfusion medicine, chronic anemia management, and polycythemia screening across clinical and research environments. Automated hematology analyzers capture the dominant margin pool as health systems prioritize throughput and interfaced laboratory information systems. Point-of-care testing devices represent the fastest-growing product category, driven by decentralized diagnostic models and emergency department triage protocols. Microhematocrit centrifuges retain entrenched positions in blood banks and mobile clinics where cost minimization overrides automation demands.
FDA classification under 21 CFR Part 862 governs hematocrit device performance standards and premarket notification requirements, while the EU Medical Device Regulation mandates clinical evidence thresholds for automated systems entering European markets. Japan's PMDA enforces QMS certification that shapes export eligibility for non-domestic manufacturers. Stakeholders must monitor evolving harmonization between ISO 15189 laboratory accreditation and national proficiency testing programs as regulatory fragmentation threatens cross-border instrument deployment strategies.
Market Dynamics
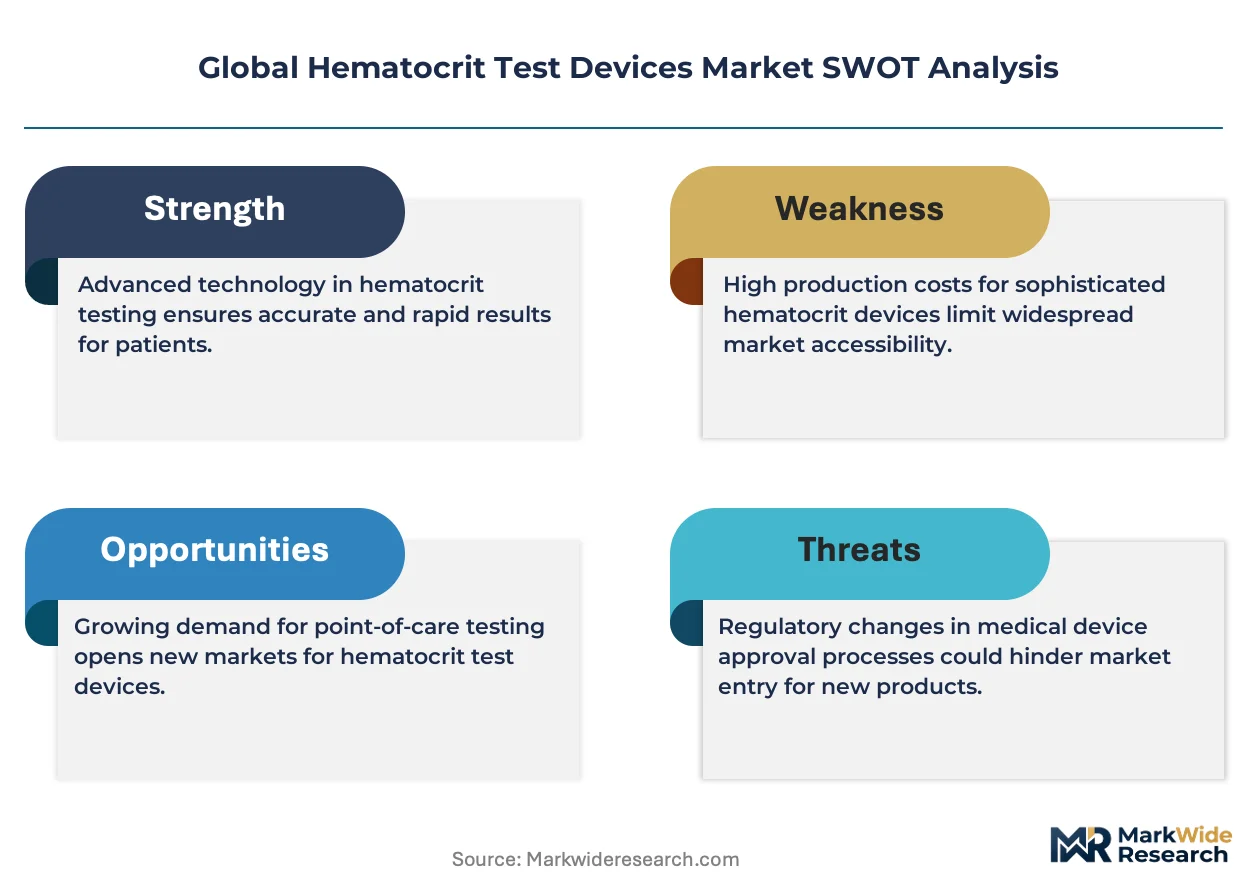
The FDA's evolving clinical laboratory improvement amendments are compressing device classification timelines while simultaneously fragmenting approval pathways between automated and point-of-care systems.
Growth Catalysts
- CLIA Waivers:The FDA's streamlined waiver pathways for moderate-complexity tests accelerate point-of-care deployment in emergency departments and satellite clinics across the United States.
- Optical Detection Advances:Multi-wavelength spectrophotometry reduces sample volume requirements below fifty microliters, enabling capillary blood sampling in pediatric and geriatric populations.
- Japan:METI's reimbursement expansion for home-based chronic disease monitoring drives demand for portable hematocrit meters in Tokyo's aging metropolitan corridors.
Market Restraints
- Optical Component Concentration:Precision photodiode and laser diode supply concentrates among German and Japanese component specialists, creating single-source vulnerability for mid-tier device assemblers.
- EU MDR Compliance Burden:The European Union's Medical Device Regulation mandates clinical evidence thresholds that extend automated system approval timelines by eighteen to thirty-six months.
- Capillary Action Limitations:Manual microhematocrit methods exhibit operator-dependent variability exceeding three percent, constraining their utility in precision transfusion medicine protocols.
Strategic Opportunities
- Brazil:ANVISA's accelerated registration pathway for Class II diagnostics creates first-mover positioning in blood bank modernization programs across São Paulo and Rio de Janeiro states.
- AI-Enabled Interpretation:Machine learning algorithms for hemolysis detection and interference flagging converge with impedance-based counting to reduce manual validation workloads.
- Retail Pharmacy Channels:CVS Health and Walgreens pilot diagnostic kiosks in California and Texas markets, extending hematocrit screening beyond traditional laboratory settings.
Industry Challenges
- Laboratory Information System Integration:HL7 FHIR interface certification demands specialized informatics talent that concentrates among Boston and San Francisco health technology clusters.
- Proficiency Testing Harmonization:ISO 15189 accreditation requirements diverge between CAP, UKAS, and JAB programs, forcing manufacturers to maintain multiple quality management system variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hematocrit Test Devices Market |
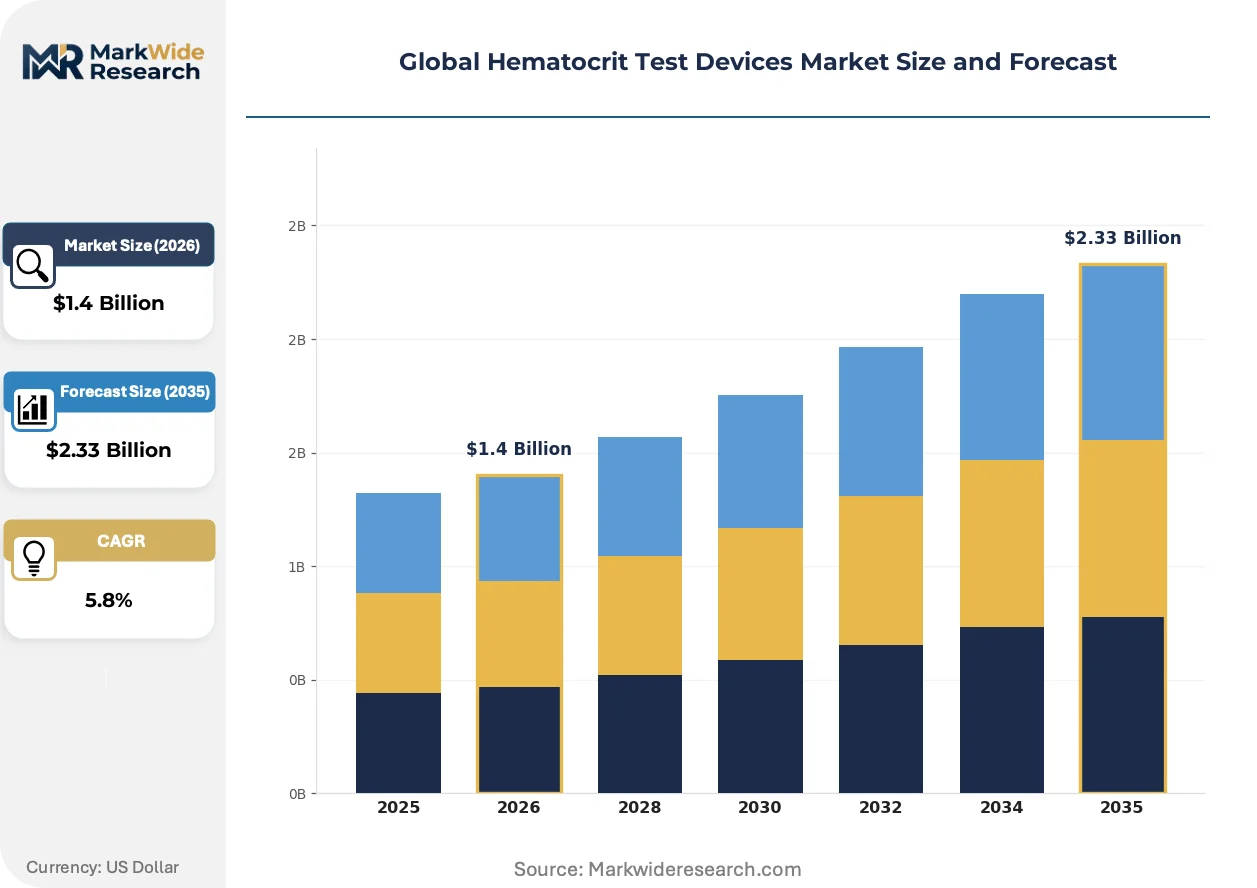
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microhematocrit Centrifuge, Automated Hematology Analyzer, Point-of-Care Testing Device, Manual Centrifuge Application: Blood Donation Screening, Anemia Diagnosis, Thalassemia Monitoring, Polycythemia Detection, Sickle Cell Disease Evaluation End User: Diagnostic Laboratories, Blood Banks, Research Institutes, Mobile Clinics, Academic Institutions Technology: Microcentrifuge, Spectrophotometry, Conductivity Analysis, Optical Detection, Impedance Measurement |
| Companies Covered | Danaher, Sysmex Corporation, Abbott Laboratories, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Nova Biomedical, EKF Diagnostics, Nihon Kohden Corporation, HORIBA Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hematocrit Test Devices Market Shifts & Advancements
Digital microfluidics and smartphone-connected readers are collapsing the cost-performance gap between laboratory-grade analyzers and portable screening tools.
Impedance-based cell counting with automated pipetting is converging with cloud-based quality control monitoring. Reference laboratories in Germany and Japan deploy these integrated systems to reduce manual sample handling by sixty percent while maintaining traceability for accreditation audits. The convergence is compressing service contract margins for standalone maintenance providers.
The EU Medical Device Regulation's post-market surveillance requirements mandate annual clinical follow-up for Class IIa automated systems. Manufacturers must establish notified body relationships and systematic literature review protocols that extend product lifecycle management costs. High-volume hematology departments in France and Italy delay procurement decisions pending clarity on MDR implementation consistency.
Hospital procurement committees now unbundle instrument acquisition from reagent supply agreements, reversing decade-long bundled pricing conventions. Independent service organizations capture maintenance contracts previously held by original equipment manufacturers. This behavioral shift concentrates in United States academic medical centers and German hospital networks where purchasing cooperatives wield consolidated negotiating leverage.
Global Hematocrit Test Devices Market Segmentation
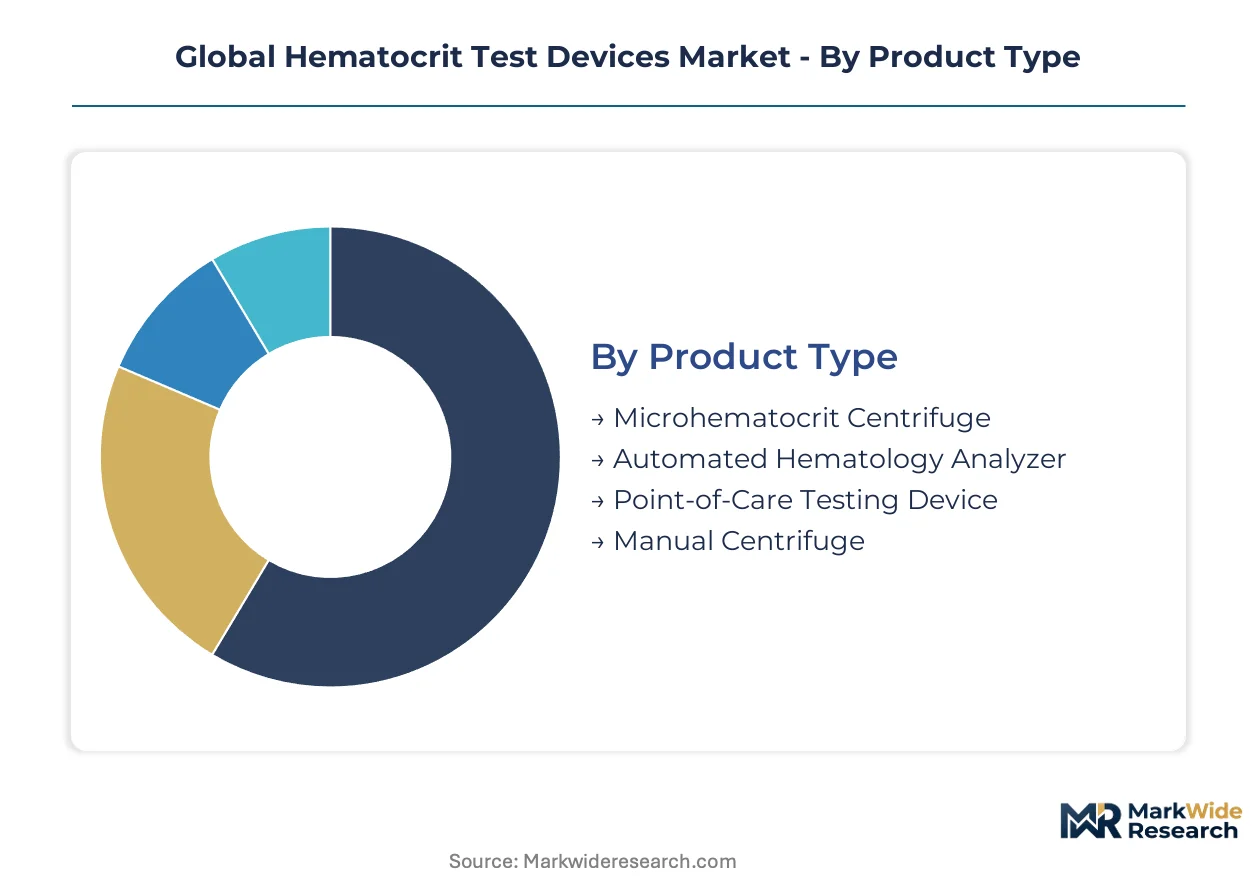
Hematocrit test devices fragment across four critical dimensions that determine procurement priorities, regulatory pathways, and service contract structures. Product type and technology choices lock in capital expenditure profiles and consumable economics for five-to-seven-year depreciation cycles. Application and end-user segmentation reveals where point-of-care disruption threatens traditional laboratory revenue pools.
Product Type:
Capital constraints and throughput requirements split buyers into automation-seekers versus cost-minimizers.
- Automated Hematology Analyzer:These systems integrate impedance-based counting with automated pipetting and cloud-connected quality control, processing hundreds of samples hourly. Demand concentrates in German and Japanese reference laboratories where ISO 15189 accreditation mandates traceable automation. Health systems prioritize these units to reduce manual validation workloads by sixty percent.
- Point-of-Care Testing Device:Portable meters employing capillary sampling and digital microfluidics enable hematocrit screening outside laboratory walls. Emergency departments in United States academic medical centers deploy these for triage protocols, while Tokyo's aging corridors drive home-based chronic disease monitoring under METI reimbursement expansion.
- Microhematocrit Centrifuge:Manual centrifugal separation at standardized speeds remains entrenched in blood banks where cost minimization overrides automation demands.
- Manual Centrifuge:Basic centrifugation units serve mobile clinics and resource-limited settings with minimal capital requirements.
Automated hematology analyzers lead volumes today; point-of-care testing devices are gaining share fastest.
Application:
Clinical urgency and reimbursement codes shape device selection across screening versus diagnostic contexts.
- Blood Donation Screening:High-throughput protocols in São Paulo and Rio de Janeiro blood banks favor rapid centrifugal methods under ANVISA modernization programs, though optical detection systems penetrate premium collection centers.
- Anemia Diagnosis:Chronic anemia management drives recurring testing volumes in pediatric and geriatric populations where fifty-microliter sample requirements enable capillary blood collection. Multi-wavelength spectrophotometry reduces invasiveness for these demographics.
- Thalassemia Monitoring:Specialized hemoglobinopathy centers require precision thresholds below two percent variation for transfusion timing decisions.
- Polycythemia Detection:JAK2 mutation screening protocols in hematology departments demand interfaced laboratory information systems for longitudinal tracking.
- Sickle Cell Disease Evaluation:Sickle cell programs in United States academic medical centers integrate hematocrit with hemoglobin electrophoresis workflows.
Blood donation screening commands the largest installed base; anemia diagnosis shows the steepest expansion trajectory.
End User:
Procurement authority and reimbursement structure determine whether buyers prioritize throughput, portability, or capital efficiency.
- Diagnostic Laboratories:Hospital-based and independent laboratories in France and Italy delay automated system procurement pending EU MDR implementation clarity, while German networks consolidate purchasing through cooperatives.
- Blood Banks:Transfusion medicine protocols in mobile collection units and fixed centers require traceable results with minimal operator variability, constraining manual microhematocrit utility.
- Research Institutes:Precision thresholds and interfaced data systems dominate requirements for clinical trial endpoints and biomarker validation studies.
- Mobile Clinics:California and Texas pilot programs extend screening through retail pharmacy kiosks where portability commands premium positioning.
- Academic Institutions:Training programs and research protocols in Boston and San Francisco health technology clusters demand HL7 FHIR interface certification.
Diagnostic laboratories dominate current procurement; mobile clinics are expanding most quickly.
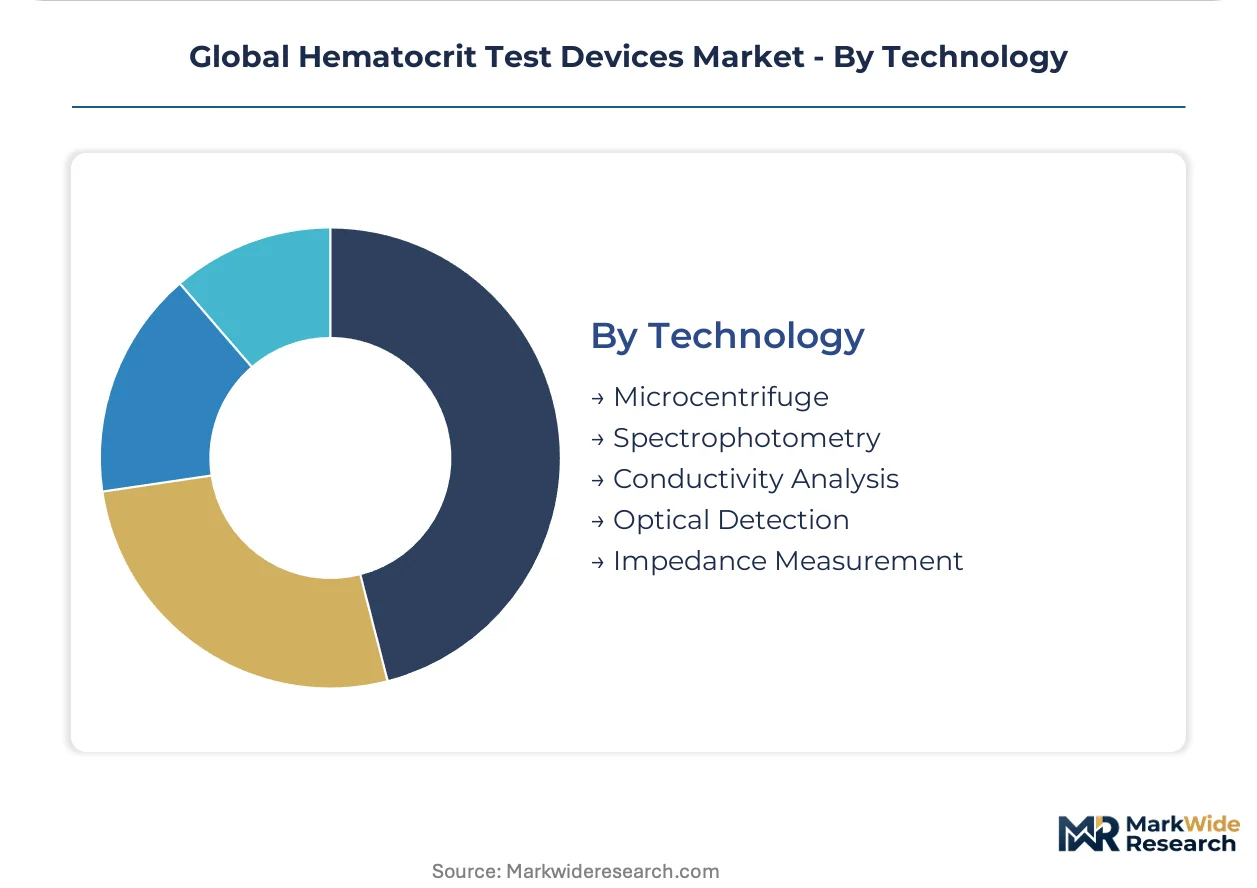
Technology:
Detection methodology determines precision, sample volume, and supply chain vulnerability to optical component concentration.
- Optical Detection:Specialized photodiode and laser diode systems from German and Japanese component specialists enable multi-wavelength spectrophotometry with sub-fifty-microliter sampling. Sysmex Corporation anchors market position through these technologies in high-volume reference labs.
- Impedance Measurement:Coulter principle-based counting with automated pipetting converges with cloud-based quality control monitoring. Danaher leverages life sciences platforms to sustain integrated workflow solutions across United States hospital networks.
- Microcentrifuge:Standardized centrifugal separation at twelve thousand RPM for five minutes remains the cost baseline for blood bank screening.
- Spectrophotometry:Single-wavelength absorbance methods serve resource-limited settings where component sourcing constraints limit optical detection deployment.
- Conductivity Analysis:Electrical property measurement offers reagent-free alternatives for specific clinical environments.
Optical detection systems capture dominant margins; impedance measurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands reference laboratory automation while Japan drives portable meter adoption through aging demographics, yet both markets face divergent regulatory pressures that reshape procurement timelines.
United States
Emergency department triage protocols and CLIA waiver expansion accelerate point-of-care deployment across academic medical centers. The FDA's evolving clinical laboratory improvement amendments compress device classification timelines for moderate-complexity tests. Boston and San Francisco health technology clusters concentrate HL7 FHIR interface certification talent that shapes integration requirements.
Germany
ISO 15189 accreditation mandates drive traceable automation in high-volume reference laboratories. The EU Medical Device Regulation extends automated system approval timelines by eighteen to thirty-six months. Hospital purchasing cooperatives in North Rhine-Westphalia consolidate negotiating leverage to unbundle instrument acquisition from reagent supply agreements.
Japan
METI reimbursement expansion for home-based chronic disease monitoring fuels portable hematocrit meter demand in Tokyo's aging metropolitan corridors. The PMDA enforces QMS certification that shapes export eligibility for non-domestic manufacturers. Osaka's Kansai region anchors specialized optical detection system manufacturing for regional supply.
Brazil
Blood bank modernization programs across São Paulo and Rio de Janeiro states create procurement windows for rapid screening methods. ANVISA's accelerated registration pathway for Class II diagnostics enables first-mover positioning. São Paulo's healthcare infrastructure expansion concentrates demand for cost-efficient centrifugal separation systems.
France
Hematology departments delay automated procurement decisions pending clarity on MDR implementation consistency. The EU MDR's post-market surveillance requirements mandate annual clinical follow-up for Class IIa systems. Paris-based hospital networks evaluate unbundled service contracts as independent maintenance providers capture market share.
Global Hematocrit Test Devices Market Competitive Landscape
Top-tier vendors anchor the premium automated analyzer segment, while mid-tier assemblers compete on point-of-care portability and capital efficiency. The market structures around three strategic archetypes: integrated life sciences platforms leveraging workflow solutions, specialized optical detection specialists dominating reference laboratories, and point-of-care extenders targeting resource-limited settings. Competitive moves concentrate on M&A for informatics capabilities and geographic expansion through regulatory first-mover positioning.
Among diversified health technology conglomerates, Danaher, Sysmex Corporation, and Abbott Laboratories occupy distinct positioning vectors that exemplify the market's tiered competitive structure. Danaher represents the integrated platform archetype through life sciences workflow solutions. Sysmex Corporation anchors specialized optical detection positioning in high-volume laboratory environments. Abbott Laboratories exemplifies point-of-care extension strategies into decentralized diagnostic settings.
| Leading Market Players |
|---|
| Danaher |
| Sysmex Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Nova Biomedical |
| EKF Diagnostics |
| Nihon Kohden Corporation |
| HORIBA Ltd |
| Others |
Supply & Pricing Matrix
Photodiode and laser diode spot prices from German and Japanese specialty component suppliers cascade through three distinct pricing tiers for hematocrit test devices, with premium optical detection systems commanding substantial markups over impedance-based alternatives and manual centrifuge baselines. Procurement committees in United States academic medical centers and German hospital networks exploit unbundled reagent contracts to compress capital equipment margins while elevating consumable pricing power.
Pricing Analysis
Capacity additions in Chinese and South Korean electronic component manufacturing are reshaping price floors for mid-tier impedance-based analyzers, forcing incumbent vendors toward three-tier pricing structure across premium, standard, and economy levels differentiated by optical detection precision and cloud connectivity certification. Price differentiation hinges on ISO 15189 accreditation compliance and HL7 FHIR interface capability, with German reference laboratories showing lowest sensitivity and mobile clinics in Brazil exhibiting highest price elasticity. Margins are tightening in the standard tier due to component commoditization, while premium optical systems retain pricing power through single-source photodiode supply from Osaka's Kansai manufacturing cluster.
Supply Chain Analysis
Precision photodiode and laser diode supply rests on Japanese and German specialty component producers, with secondary sourcing from Taiwanese semiconductor foundries for signal processing chips and Chinese manufacturers for plastic consumables and centrifuge housings. Raw material dependencies include optical-grade silicon substrates, rare-earth doped laser crystals, and medical-grade polymers for capillary tubes. Single-source vulnerability concentrates in high-precision photodetector arrays from two Osaka-based suppliers. Distribution runs through original equipment manufacturer direct sales forces for automated analyzers, independent distributors for point-of-care devices, and group purchasing organizations for United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through cloud-connected quality control software attach rates and premium-tier shifts toward sub-fifty-microliter optical detection systems in pediatric and geriatric applications.
For Market Incumbents: Anchor defensive positioning through backward integration into photodiode supply chains and captive cloud infrastructure development, countering emerging digital-native entrants with software-defined workflow solutions. Prioritize ISO 15189 accreditation maintenance as European Union MDR implementation creates compliance moats, while expanding service contract capture as independent maintenance organizations erode traditional aftermarket revenue pools. For New Entrants and Emerging Players: Direct-to-clinic digital distribution channels enable rapid penetration of Brazil's ANVISA-accelerated Class II registration pathway, particularly for cost-optimized point-of-care devices targeting São Paulo blood bank modernization. White-space concentration sits in retail pharmacy diagnostic kiosks piloted by CVS Health and Walgreens in California and Texas markets, where portability premiums override brand loyalty and cloud-native architectures bypass legacy LIS integration burdens. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized optical detection component suppliers possessing PMDA QMS certification and established notified body relationships for EU MDR compliance. Long-term viability through the projection horizon favors acquisition targets with hybrid hardware-software revenue models and installed base expansion in METI-reimbursed home monitoring corridors. Watch FDA CLIA waiver expansion velocity as the critical inflection signal for point-of-care market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence thresholds compress approval timelines for automated systems entering French and Italian hospital networks. |
| Hospital System Partnership | Integrated workflow solutions with Danaher's life sciences platform secure multi-year reagent supply agreements across German cooperatives. |
| Software Companion Development | Cloud-based quality control monitoring with HL7 FHIR certification reduces manual validation workloads by sixty percent in reference laboratories. |
| Reimbursement Strategy | METI home-based chronic disease monitoring expansion in Tokyo's aging corridors drives portable meter demand with premium positioning. |
| Regulatory First-Mover Positioning | ANVISA accelerated Class II registration in São Paulo and Rio de Janeiro blood banks captures modernization procurement windows. |
Research Methodology
Multiple input streams — structured interviews with hematology department directors and biomedical engineers, hospital purchasing committee deliberation records, and GPO contract databases — were reconciled against FDA 510(k) filings, PMDA QMS certification registries, and EU MDR notified body documentation. Primary fieldwork engaged clinical laboratory managers, point-of-care device operators in emergency departments, blood bank quality officers, and diagnostic distributor channel heads across United States, German, Japanese, and Brazilian markets. Secondary validation drew from customs trade data for optical component flows, SEC 10-K instrument revenue disclosures, and ISO 15189 accreditation audit records. Bottom-up demand modeling triangulated against top-down macro healthcare expenditure projections.
Data-stream reconciliation across product type, technology detection methodology, application urgency tier, and end-user procurement authority generated volume and value outputs over the projection horizon. Segmentation dimensions modeled include automation level, detection physics, clinical versus screening application, and laboratory versus decentralized setting. CAGRs derived from instrument replacement cycles, reagent consumable attach rates, and reimbursement code expansion trajectories. Forecast inputs incorporated CLIA waiver approval velocity, EU MDR implementation consistency, and METI chronic disease monitoring policy evolution.
The model assumes a particular technology adoption path; alternative pathways for digital microfluidics and smartphone-connected readers would alter the outlook if capillary sampling precision achieves laboratory-grade thresholds. Forecasts reflect assumptions regarding regulatory harmonization between ISO 15189 and national proficiency testing programs, photodiode supply concentration persistence, and cloud infrastructure penetration in resource-limited settings. A small set of named triggers — FDA classification timeline compression, EU MDR post-market surveillance enforcement intensity, and Japanese home monitoring reimbursement expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Global Laboratory Grinders Market