
 France Anesthesia Devices Market | 2026-2036
France Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Anesthesia Devices Market Foresight
CE marking under the EU Medical Device Regulation is unwinding competitive access for smaller anesthesia equipment suppliers in France. Draegerwerk AG leverages its integrated gas delivery platforms to sustain dominance in high-acuity settings. GE Healthcare anchors its position through deep installed bases across AP-HP hospital networks. Koninklijke Philips NV differentiates via digital monitoring ecosystems that bridge anesthesia machines with critical care informatics.
Anesthesia devices comprise electromechanical systems that regulate gas mixtures, ventilate patients, and monitor physiological parameters during surgical sedation and pain management, typically integrating vaporizers, breathing circuits, and multi-parameter displays in a single workstation. These systems serve the essential function of maintaining controlled unconsciousness while safeguarding respiratory and cardiovascular stability across operating rooms, emergency suites, and intensive care units. Monitoring equipment commands premium positioning as French hospitals prioritize integrated hemodynamic and respiratory tracking during prolonged procedures. Low-flow anesthesia technology expands fastest as facilities seek reduced volatile agent consumption and lower environmental emissions. Airway management devices occupy stable replacement demand tied to single-use protocols and infection control mandates.
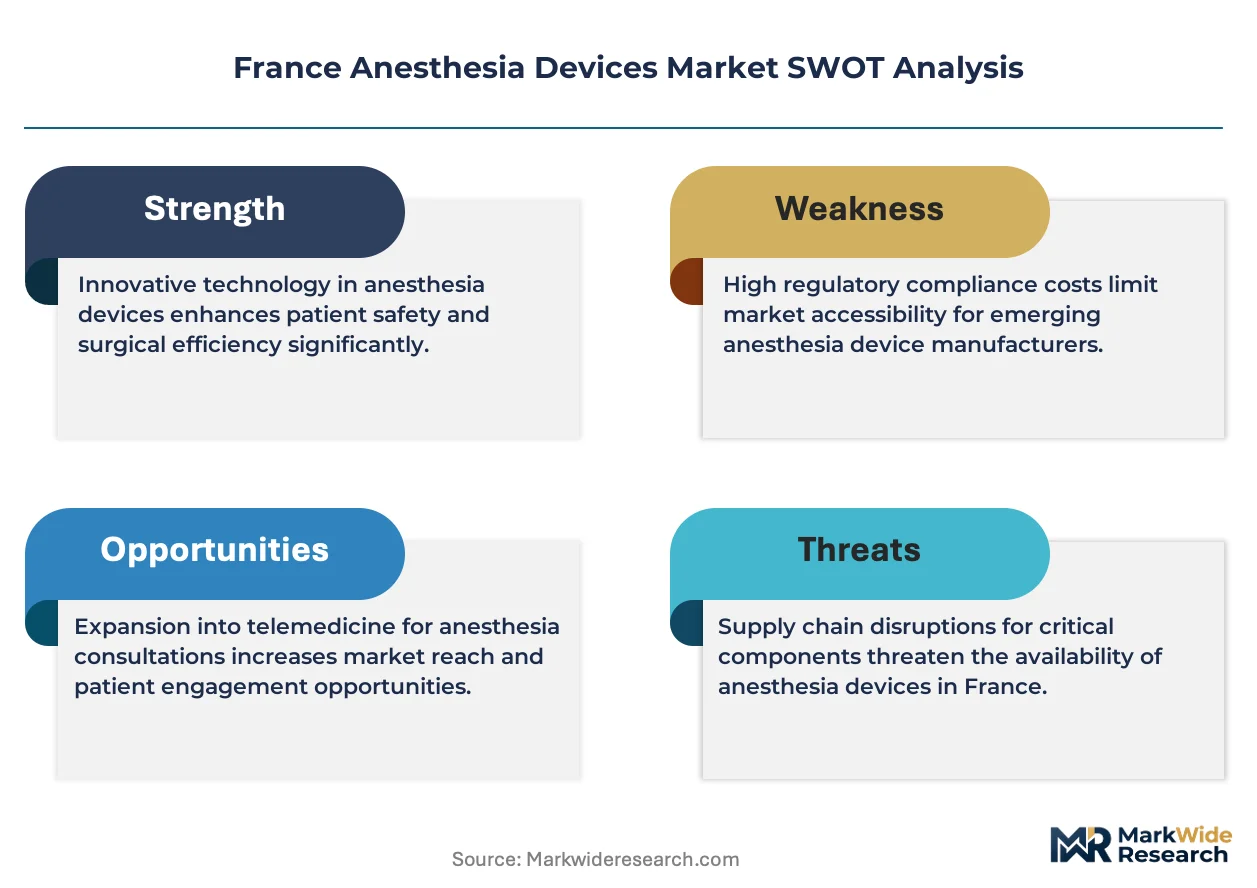
ANSM enforces post-market surveillance and vigilance reporting that shapes product liability exposure and accelerates obsolescence timelines for legacy devices. The EU MDR's stricter clinical evidence requirements and EUDAMED registration obligations raise barriers for new entrants while favoring established manufacturers with dedicated regulatory affairs teams. Stakeholders must track reimbursement negotiations between HAS and hospital federations, as tariff adjustments for innovative anesthesia modalities will determine adoption velocity across public and private surgical networks.
Market Dynamics
ANSM's intensified post-market surveillance mandates are compressing replacement cycles for legacy anesthesia workstations across French hospital networks, forcing capital allocation toward compliant integrated systems.
Growth Catalysts
- Surgical capacity expansion:University hospital centers in Île-de-France and Auvergne-Rhône-Alpes are commissioning additional operating suites, directly stimulating anesthesia workstation procurement.
- EU MDR compliance deadlines:The Medical Device Regulation's EUDAMED registration and clinical evidence requirements are accelerating obsolescence of pre-2017 installed bases.
- Low-flow anesthesia adoption:Volatile agent reduction protocols are driving replacement demand for modern vaporizer and breathing circuit technologies.
Market Restraints
- Capital intensity barriers:Integrated anesthesia workstations require substantial upfront investment, constraining procurement flexibility for smaller private surgical clinics.
- Regulatory compliance costs:ANSM vigilance reporting and EU MDR technical documentation obligations inflate total cost of ownership for equipment holders.
- Supply concentration risk:Critical components including precision gas flow sensors and vaporizer modules concentrate among limited specialized suppliers.
Strategic Opportunities
- Digital monitoring convergence:Integration of anesthesia machines with critical care informatics platforms creates differentiation pathways for vendors serving AP-HP networks.
- Single-use airway device transition:Infection control mandates are elevating demand for disposable laryngoscope blades and supraglottic airways in ambulatory surgical centers.
- Regional hospital modernization:HAS reimbursement negotiations for innovative anesthesia modalities present adoption catalysts across medium-sized public hospitals in Occitanie and Provence-Alpes-Côte d'Azur.
Industry Challenges
- Biomedical engineering talent scarcity:Qualified technicians for anesthesia workstation calibration and preventive maintenance are concentrated in Paris and Lyon metropolitan areas.
- Legacy system integration complexity:New EU MDR-compliant devices must interface with existing hospital information systems, extending deployment timelines.
- Extended certification timelines:ANSM's review queue for substantial equivalence determinations delays market entry for iterative product improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Anesthesia Devices Market |
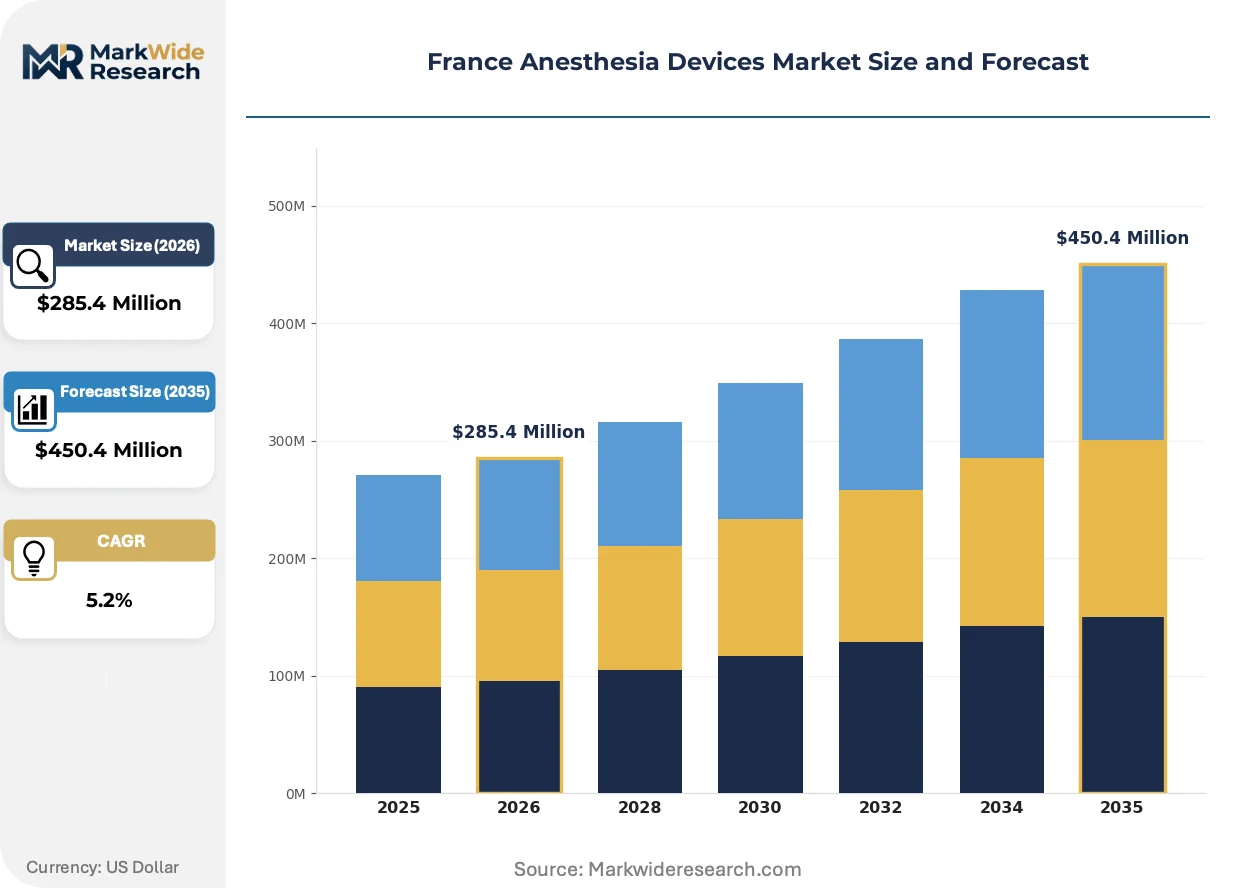
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Anesthesia Machines, Monitoring Equipment, Airway Management Devices, Infusion Pumps Technology: Gas Delivery, Automated Control, Digital Monitoring, Portable Devices, Low-Flow Systems Application: Surgical Procedures, Pain Management, Obstetrics, Emergency Medicine, Critical Care End User: Hospitals, Ambulatory Surgical Centers, Research Institutes, Specialty Clinics, Rehabilitation Centers |
| Companies Covered | B. Braun Melsungen AG, Draegerwerk AG, Heyer Medical AG, Kalstein France, Fisher & Paykel Healthcare, GE Healthcare, Getinge AB, Koninklijke Philips NV, Mindray, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Anesthesia Devices Market Shifts & Advancements
Digital integration and environmental compliance are restructuring competitive advantage in French anesthesia equipment, with vendors racing to embed connectivity and reduce volatile agent emissions simultaneously.
Portable ultrasound-guided vascular access devices are miniaturizing anesthesia workflow in preoperative and emergency settings. Regional anesthesia teams at university hospitals are deploying handheld systems for real-time nerve visualization. This form factor compression is miniaturizing capital equipment requirements and enabling point-of-care deployment outside traditional operating theaters.
ANSM's updated vigilance reporting requirements are mandating automated adverse event capture from connected anesthesia workstations. Manufacturers must now embed software architectures capable of real-time data transmission to national pharmacovigilance databases. High-acuity settings face the steepest compliance burden, driving preference toward vendors with established regulatory affairs infrastructure.
Service unbundling is fragmenting traditional anesthesia equipment purchasing in private surgical networks. Buyers are separating hardware acquisition from maintenance contracts and software subscriptions, pressuring vendor margin structures. This decomposition is most pronounced in Île-de-France, where independent service organizations compete for multi-vendor maintenance agreements.
France Anesthesia Devices Market Segmentation
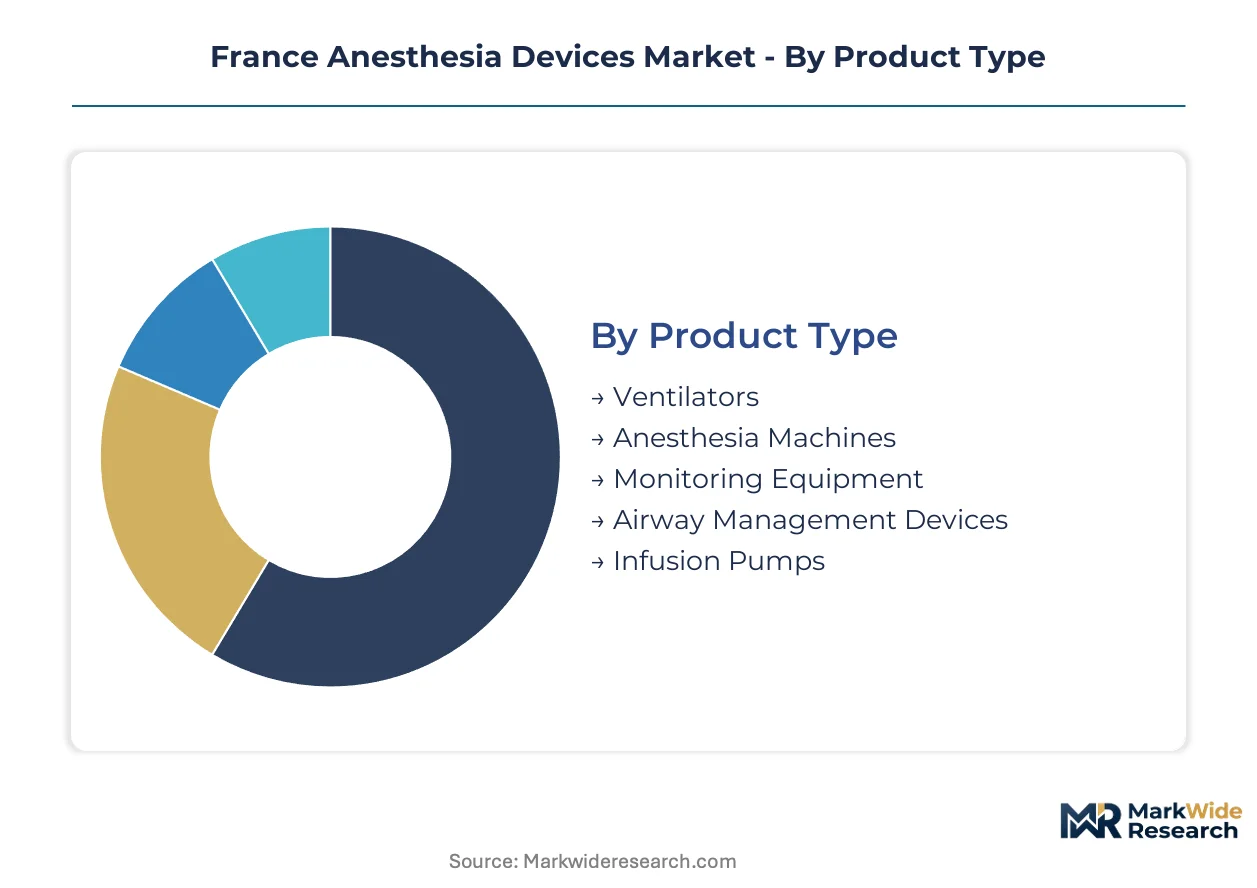
Anesthesia device procurement across France fragments along technological capability, clinical setting, and patient acuity. Channel mix varies sharply between capital-intensive workstation sales to university hospitals and disposable airway device flows to ambulatory networks.
Product Type:
Ventilators and anesthesia machines move through direct manufacturer-hospital contracts with multi-year service attachments. Monitoring equipment and airway devices distribute through medical supply distributors serving fragmented clinic networks.
- Anesthesia Machines:Integrated workstations combining gas delivery, ventilation, and vaporizer functions in a single cabinet. CHU de Bordeaux and Hospices Civils de Lyon are expanding fleets to meet EU MDR compliance deadlines, with procurement concentrated in high-acuity surgical suites requiring seamless HIS integration.
- Monitoring Equipment:Multi-parameter displays tracking hemodynamic, respiratory, and neurological status during sedation. AP-HP networks in Paris prioritize devices with native connectivity to critical care informatics platforms, driving preference for vendors with established digital ecosystems.
- Ventilators:Electromechanical systems providing controlled mechanical ventilation during general anesthesia.
- Airway Management Devices:Laryngoscopes, endotracheal tubes, and supraglottic airways following single-use protocols.
- Infusion Pumps:Syringe and volumetric pumps for intravenous anesthetic and analgesic delivery.
Anesthesia machines dominate installed base. Monitoring equipment is where expansion concentrates.
Technology:
Cost tiers separate premium integrated platforms from modular upgrades and portable point-of-care systems. University hospitals absorb full-capability workstations while regional facilities prioritize targeted technology modules.
- Digital Monitoring:Networked sensor arrays with real-time data transmission to EHR and pharmacovigilance systems. ANSM's automated adverse event capture mandates are forcing software architecture upgrades across Île-de-France university hospitals, favoring vendors with dedicated regulatory affairs infrastructure.
- Low-Flow Systems:Closed-circuit anesthesia delivery minimizing volatile agent consumption and environmental emissions. Auvergne-Rhône-Alpes facilities are retrofitting existing machines with low-flow vaporizer modules to meet sustainability targets while reducing per-procedure agent costs.
- Gas Delivery:Precision flow control systems for nitrous oxide, oxygen, and medical air blending.
- Automated Control:Closed-loop anesthesia systems adjusting drug delivery based on physiological feedback.
- Portable Devices:Handheld ultrasound and miniaturized monitoring for prehospital and emergency deployment.
Digital monitoring commands premium pricing. Low-flow systems are climbing the fastest.
Application:
Volume concentrates in scheduled surgical procedures with predictable equipment utilization, while margin concentrates in emergency and critical care settings requiring rapid deployment capability.
- Surgical Procedures:General anesthesia delivery across orthopedic, cardiac, and abdominal interventions. Operating suite expansion at CHU de Montpellier and Centre Hospitalier Universitaire de Nice is driving workstation procurement with 15-plus year depreciation schedules.
- Critical Care:Sedation and ventilation management for mechanically ventilated patients outside operating theaters. Réanimation units at Parisian university hospitals are demanding anesthesia platforms with seamless ICU-to-OR transfer capability, blurring equipment category boundaries.
- Pain Management:Regional anesthesia and patient-controlled analgesia in postoperative and chronic settings.
- Emergency Medicine:Rapid-sequence intubation and procedural sedation in trauma and resuscitation bays.
- Obstetrics:Labor analgesia and cesarean section anesthesia in maternity units.
Surgical procedures anchor equipment utilization. Critical care is gaining share fastest.
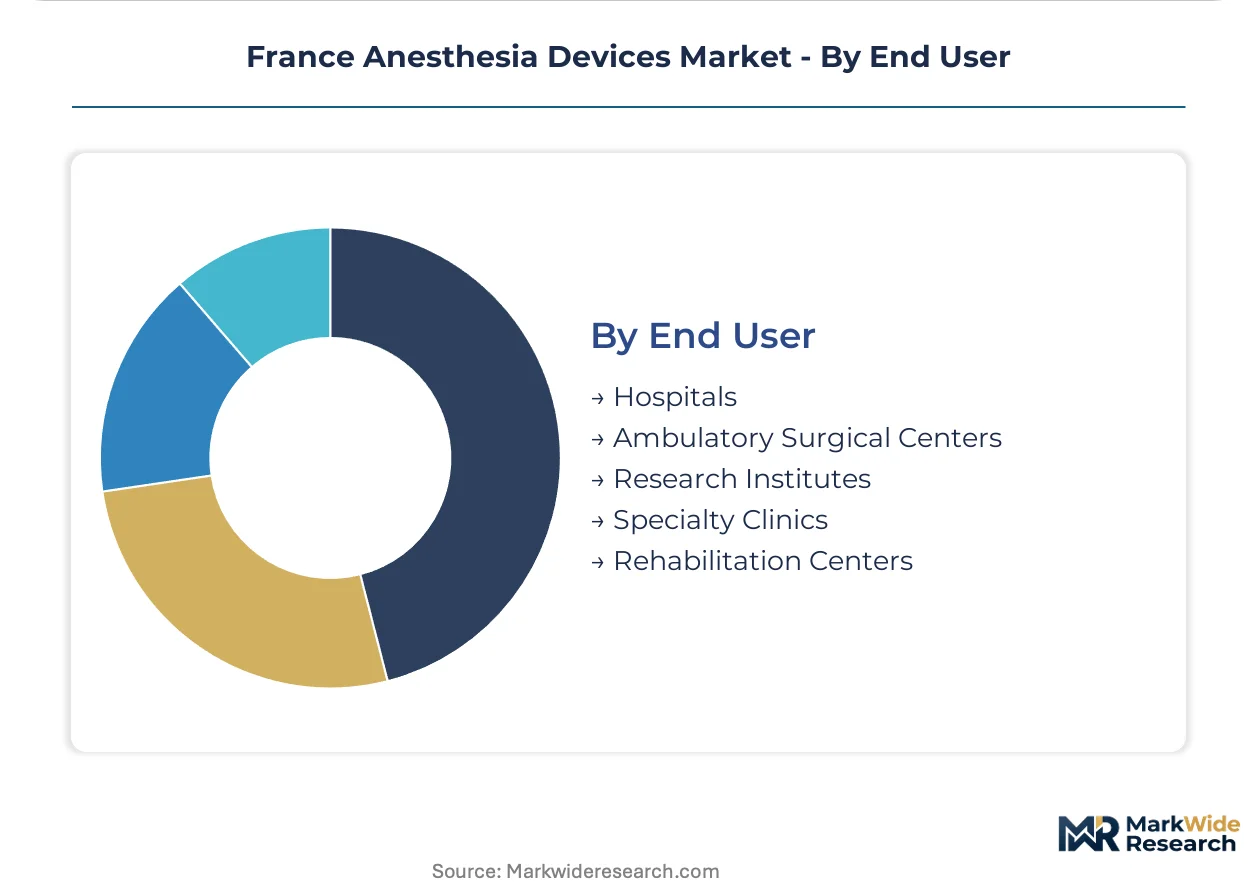
End User:
Customer type determines procurement modality: hospitals negotiate enterprise frameworks, ambulatory centers purchase through group purchasing organizations, and research institutes acquire through dedicated innovation budgets.
- Hospitals:Public and private acute care facilities with centralized biomedical engineering departments. The 39 CHUs across France account for disproportionate anesthesia machine procurement volume, with AP-HP's 39-hospital network exercising significant vendor negotiation leverage through consolidated purchasing.
- Ambulatory Surgical Centers:Standalone facilities performing same-day procedures without overnight admission. Clinique de la Roseraie in Strasbourg and similar centers in Provence-Alpes-Côte d'Azur are driving demand for compact anesthesia workstations with rapid turnaround capabilities and lower capital footprints.
- Specialty Clinics:Ophthalmology, dentistry, and gastroenterology practices requiring sedation capabilities.
- Research Institutes:Academic and pharmaceutical research facilities conducting anesthesia pharmacology studies.
- Rehabilitation Centers:Long-term care facilities managing chronic pain and spasticity.
Hospitals dominate installed base. Ambulatory surgical centers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM's updated medical device vigilance requirements are redistributing procurement priority across French hospital networks, compressing replacement cycles in high-acuity regions while elevating compliance spending in peripheral markets.
Île-de-France
AP-HP's 39-hospital network commands disproportionate anesthesia workstation procurement volume through consolidated purchasing frameworks. ANSM's EUDAMED registration deadlines are accelerating obsolescence of pre-2017 installed bases across Parisian university hospitals. CHU de Bicêtre and Hôpital Européen Georges-Pompidou are commissioning additional operating suites with integrated gas delivery platforms.
Auvergne-Rhône-Alpes
Hospices Civils de Lyon are expanding surgical capacity with EU MDR-compliant integrated systems. Low-flow anesthesia retrofit programs at Centre Hospitalier Lyon Sud are reducing volatile agent consumption to meet regional sustainability targets. Clermont-Ferrand's university hospital cluster is driving demand for digital monitoring ecosystems with native HIS connectivity.
Provence-Alpes-Côte d'Azur
Centre Hospitalier Universitaire de Nice is modernizing anesthesia fleets ahead of ANSM vigilance reporting mandates. Ambulatory surgical centers in Marseille are adopting compact workstations with rapid turnaround capabilities. HAS reimbursement negotiations for innovative anesthesia modalities are determining adoption velocity across public surgical networks in the region.
Occitanie
CHU de Montpellier's operating suite expansion is stimulating procurement of anesthesia machines with 15-plus year depreciation schedules. Regional hospitals in Toulouse are prioritizing targeted technology modules over full-capability workstations. Biomedical engineering talent scarcity is concentrating preventive maintenance contracts in the Montpellier metropolitan area.
Hauts-de-France
University hospital centers in Lille are replacing legacy systems to meet ANSM's automated adverse event capture requirements. Smaller public hospitals in the region face capital intensity barriers for integrated workstation procurement. Independent service organizations are competing for multi-vendor maintenance agreements across the Lille metropolitan surgical network.
France Anesthesia Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with dedicated regulatory affairs infrastructure. Market structure concentrates around vendors capable of delivering integrated gas delivery platforms with seamless hospital information system connectivity. Two strategic archetypes dominate: established European manufacturers with deep installed bases across AP-HP networks, and Asian conglomerates competing on modular upgrade pathways. Competitive moves center on portfolio diversification into digital monitoring ecosystems and strategic partnerships for EUDAMED compliance support.
Among Germany-based diversified medical technology groups, Draegerwerk AG and B. Braun Melsungen AG exemplify the established European archetype with extensive regulatory affairs capabilities. Draegerwerk AG occupies a position anchored in high-acuity settings through integrated gas delivery platforms. B. Braun Melsungen AG represents the full-line anesthesia supplier model with broad portfolio coverage. GE Healthcare, a US-based conglomerate, sits within the digital convergence tier, leveraging critical care informatics integration to differentiate across hospital networks. These three companies collectively represent the regulatory-heavy competitive dynamic shaping French procurement.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Draegerwerk AG |
| Heyer Medical AG |
| Kalstein France |
| Fisher & Paykel Healthcare |
| GE Healthcare |
| Getinge AB |
| Koninklijke Philips NV |
| Mindray |
| Others |
Supply & Pricing Matrix
EU MDR certification gates both supply qualification and price differentiation in France's anesthesia device market, forcing vendors to absorb compliance costs while hospitals stratify procurement across capability tiers. ANSM vigilance reporting mandates compress replacement cycles and elevate total cost of ownership calculations across Île-de-France and Auvergne-Rhône-Alpes procurement committees.
Pricing Analysis
Cost-plus contracts with medical device inflation indexation dominate anesthesia workstation procurement across French CHU networks. Three-tier pricing structure across premium, standard, and economy levels separates integrated digital monitoring platforms from modular upgrades and portable point-of-care systems. Pricing pressure stems from service unbundling in Île-de-France private surgical networks, where independent service organizations compete for multi-vendor maintenance agreements. Ambulatory surgical centers exhibit highest price sensitivity due to capital intensity barriers, while AP-HP's consolidated purchasing exercises significant negotiation leverage.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for precision gas flow sensors and vaporizer modules. Component supply concentrates in Germany, Switzerland, and the United States for critical electromechanical subsystems. Raw material dependencies span medical-grade aluminum alloys, precision-machined brass fittings, and specialized polymer compounds for breathing circuits. Single-source vulnerability persists for EU MDR-compliant software architectures capable of real-time pharmacovigilance data transmission. Distribution runs through direct manufacturer-hospital contracts with multi-year service attachments for capital equipment, supplemented by medical supply distributors for disposable airway devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's anesthesia device market rewards service-attach strategies as software subscriptions and preventive maintenance contracts expand faster than hardware replacement cycles. Recurring revenue layers now command disproportionate margin contribution across vendor portfolios.
For Market Incumbents: Fortify regulatory affairs infrastructure to defend AP-HP network positions against Asian conglomerates competing on modular upgrade pathways. Deepen backward integration into precision gas flow sensor production to mitigate single-source supply risk. Accelerate EU MDR technical documentation capabilities to compress ANSM review timelines for iterative product improvements. For New Entrants and Emerging Players: Differentiate on portable ultrasound-guided vascular access miniaturization for preoperative and emergency deployment outside traditional operating theaters. Target ambulatory surgical centers in Provence-Alpes-Côte d'Azur with compact anesthesia workstations featuring rapid turnaround capabilities and lower capital footprints. Pursue group purchasing organization channel partnerships to bypass direct hospital procurement barriers. For Investors and Strategic Acquirers: EU MDR compliance deadlines reshape the acquisition landscape toward targets with established EUDAMED registration and clinical evidence portfolios. Five-to-ten-year viability hinges on digital monitoring convergence capabilities bridging anesthesia machines with critical care informatics platforms. Monitor HAS reimbursement negotiations for innovative anesthesia modalities as the signal determining adoption velocity across medium-sized public hospitals.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EUDAMED registration accelerates market access for EU MDR-compliant integrated workstations across French CHU networks. |
| Hospital System Partnership | AP-HP consolidated purchasing frameworks favor vendors with native HIS connectivity and multi-site service capabilities. |
| Software Companion Development | ANSM automated adverse event capture mandates require real-time pharmacovigilance data transmission architectures. |
| Reimbursement Strategy | HAS tariff adjustments for low-flow anesthesia modalities determine adoption velocity in Occitanie and Provence-Alpes-Côte d'Azur. |
| Backward Integration | In-house production of precision gas flow sensors mitigates supply concentration risk from limited specialized suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the anesthesia device value chain, including hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at established manufacturers. Secondary validation drew from ANSM vigilance databases, EU MDR EUDAMED registration records, hospital procurement disclosures, and CHU capital expenditure reports. Bottom-up equipment unit economics triangulated against top-down market sizing across product type, technology tier, and end-user segments.
Across the analysis window, forecasts employed a segmented growth framework modeling anesthesia machines, monitoring equipment, ventilators, airway management devices, and infusion pumps by digital monitoring, low-flow systems, gas delivery, automated control, and portable device technologies. CAGRs derived from surgical capacity expansion trajectories, EU MDR compliance-driven replacement cycles, and low-flow anesthesia adoption curves specific to French sustainability targets and volatile agent cost structures.
Decision-makers should treat outputs as directional under assumptions of stable ANSM vigilance enforcement and continued EU MDR implementation timelines; material deviation would warrant model refresh. Forecasts reflect base-case surgical volume growth and public hospital capital allocation priorities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Latin America General Surgical Devices Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Medical Face Shield Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market