
 Global Medical Composite Market | 2026-2036
Global Medical Composite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Composite Market Foresight
Hospital procurement groups is unwinding traditional supplier relationships as ambulatory surgical centers gain purchasing influence in composite-intensive device categories. Toray Industries anchors its position through captive carbon fiber supply chains that extend from precursor chemistry to finished medical-grade prepreg. SGL Carbon specializes in high-modulus pitch-based fibers for radiolucent surgical tables and imaging equipment where metal interference creates clinical limitations. Dentsply Sirona competes in dental composites through integrated material-scanner-milling workflows that lock clinicians into proprietary resin systems.
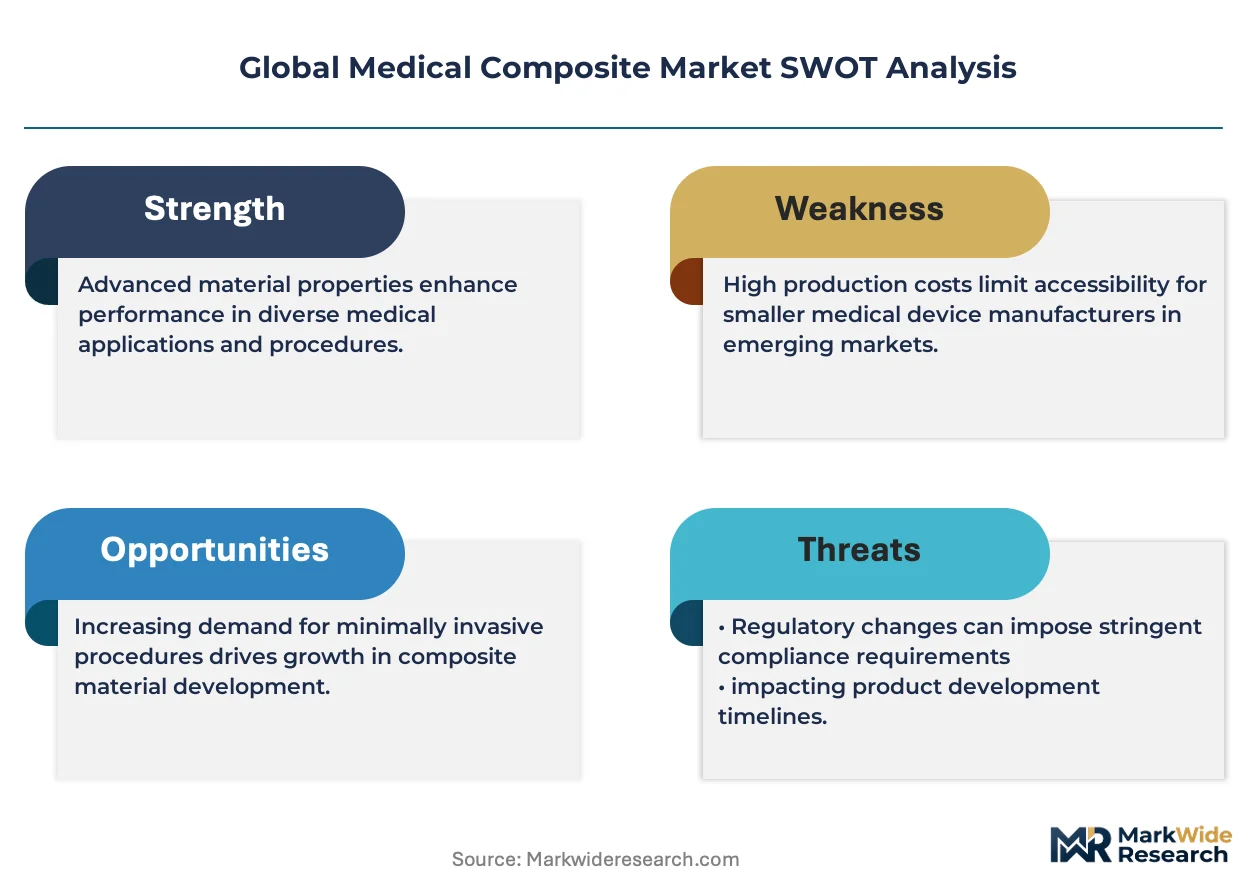
Medical composites integrate fiber reinforcements with biocompatible resin matrices to achieve strength-to-weight ratios exceeding titanium alloys while permitting magnetic resonance imaging compatibility; carbon fiber grades rated at 230 GPa tensile modulus dominate structural orthopedic applications where radiolucency enables post-operative imaging without artifact. Glass fiber formulations lead in cost-sensitive dental and prosthetic segments where modulus requirements remain moderate and aesthetic layering demands translucency control. Hybrid composites represent the fastest-growing product category as manufacturers blend carbon and glass plies to optimize stiffness gradients in custom orthopedic braces and external fixation devices.
FDA 21 CFR Part 820 quality system regulations and EU MDR Annex I general safety requirements shape material selection protocols, with notified bodies demanding extensive cytotoxicity and sensitization data for fiber-resin combinations in permanent implant contact. ISO 10993 biocompatibility testing series governs preclinical validation pathways, while REACH substance restrictions limit certain amine hardeners in European-manufactured components. Stakeholders must monitor evolving FDA guidance on additive-manufactured composite structures and anticipate whether regulator convergence on fiber-release testing protocols will create new barriers for market entry or consolidate supplier bases around vertically integrated compounders with in-house toxicology capabilities.
Market Dynamics
Orthopedic device manufacturers are unwinding legacy metal preferences as carbon fiber reinforced polymers gain traction in load-bearing implants, reshaping supplier qualification protocols and procurement criteria across the value chain.
Growth Catalysts
- FDA biocompatibility guidance acceleration:Updated FDA guidance on long-term implantable devices has compressed material validation timelines, pushing manufacturers toward pre-qualified composite formulations.
- Radiolucency imperative in imaging:Magnetic resonance imaging compatibility requirements in spinal and trauma applications are pulling carbon fiber grades rated at 230 GPa tensile modulus into structural orthopedic segments.
- German precision machining cluster:Stuttgart and Tuttlingen medical technology corridors concentrate composite machining capabilities that align with orthopedic OEM supply chains.
Market Restraints
- Carbon fiber precursor volatility:Polyacrylonitrile supply concentration among Asian petrochemical producers creates input cost instability for medical-grade prepreg manufacturers.
- EU MDR post-market surveillance burden:Expanded clinical follow-up requirements for permanent implant contact devices extend commercialization timelines and inflate regulatory compliance costs.
- Titanium alloy substitution resilience:Established metallurgical supply chains and surgeon familiarity with metal implants sustain competitive pressure in load-bearing hip and knee applications.
Strategic Opportunities
- Hybrid composite white space:Blended carbon-glass ply configurations for custom orthopedic braces and external fixation devices represent an underexploited product architecture.
- Ambulatory surgical center channel expansion:Outpatient procedure volume concentration is creating procurement influence shifts favoring composite-intensive disposable and semi-disposable device categories.
- ISO 10993 testing standardization:Emerging convergence on fiber-release testing protocols may consolidate supplier bases around compounders with in-house toxicology capabilities.
Industry Challenges
- Biocompatibility data generation bottleneck:Extensive cytotoxicity and sensitization studies for novel fiber-resin combinations create multi-year preclinical validation timelines.
- Additive manufacturing qualification uncertainty:Evolving FDA guidance on 3D-printed composite structures leaves manufacturers without clear regulatory pathways for next-generation implant geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Composite Market |
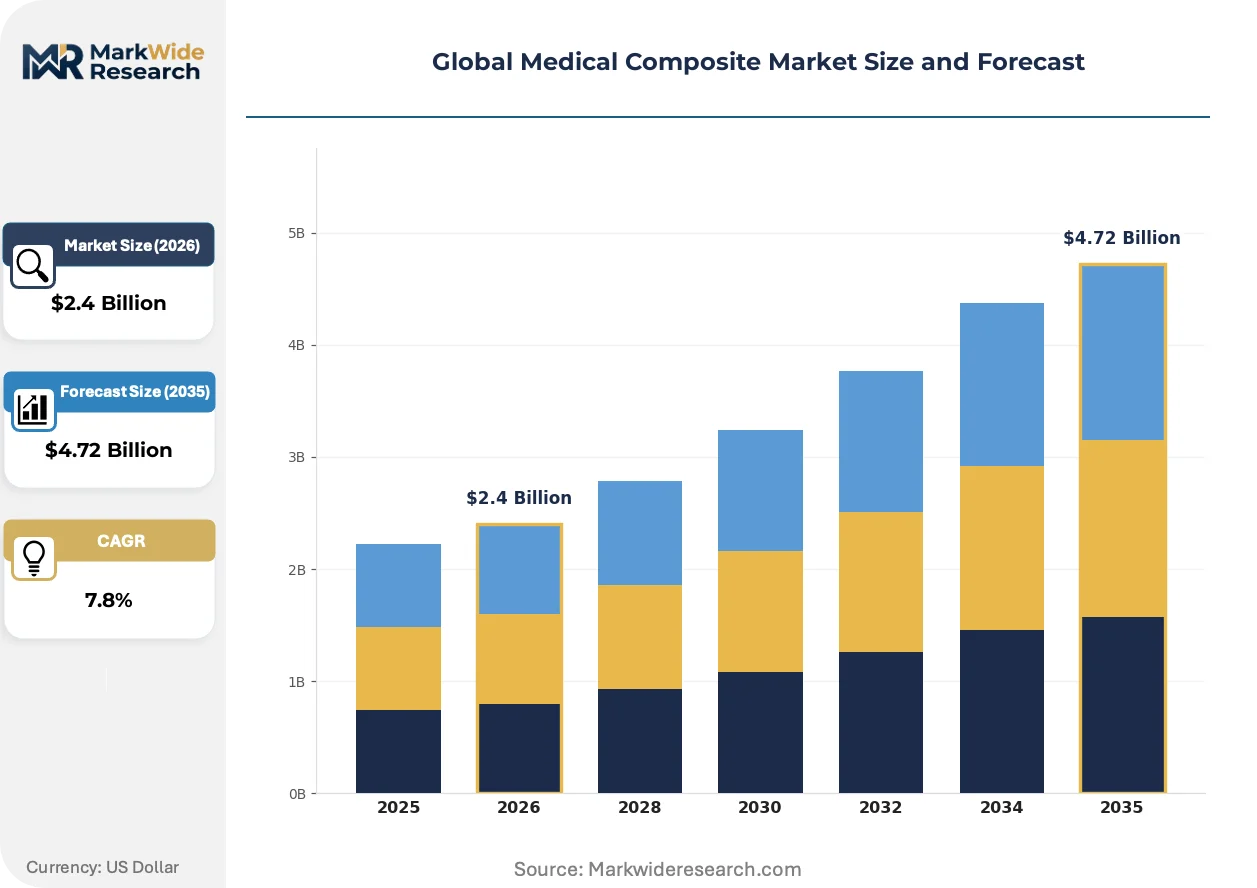
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Composites Application: Orthopedic Devices, Dental Implants, Prosthetics, Surgical Instruments, Diagnostic Equipment End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Rehabilitation Clinics Delivery Mode: Injection Molding, Hand Lay-Up, Resin Transfer Molding, Compression Molding |
| Companies Covered | 3M Company, Toray Industries Inc., Dentsply Sirona, Royal DSM, SGL Carbon SE, Kulzer GmbH, Zeus Industrial Products Inc., IDC Composite International Inc., Composiflex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Composite Market Shifts & Advancements
Material science advances and regulatory convergence are compressing development cycles while reshaping competitive positioning around radiolucency performance and manufacturing scalability.
Continuous fiber-reinforced thermoplastic composites are supplanting thermoset prepregs in trauma fixation plates and external fixation systems. European orthopedic OEMs are accelerating adoption timelines as radiolucency specifications harden in purchasing contracts. This technology is supplanting legacy autoclave-cured epoxy systems by enabling in-situ consolidation and post-forming adjustments that reduce surgical customization lead times.
EU MDR Annex I general safety requirements are tightening material traceability mandates for long-term implantable devices. Notified bodies now demand batch-level fiber provenance documentation and resin hardener toxicity profiles that exceed prior CE marking thresholds. German and Swiss manufacturers with integrated precursor-to-prepreg operations are capturing disproportionate notified body approval velocity.
Hospital procurement groups are fragmenting traditional supplier relationships as ambulatory surgical centers accumulate purchasing influence in composite-intensive categories. Distributor consolidation in the United States and Western Europe is compressing vendor margins while favoring compounders with direct-to-provider logistics capabilities. This shift is most visible in spinal implant and arthroscopic device segments where procedure migration to outpatient settings accelerates volume concentration.
Global Medical Composite Market Segmentation
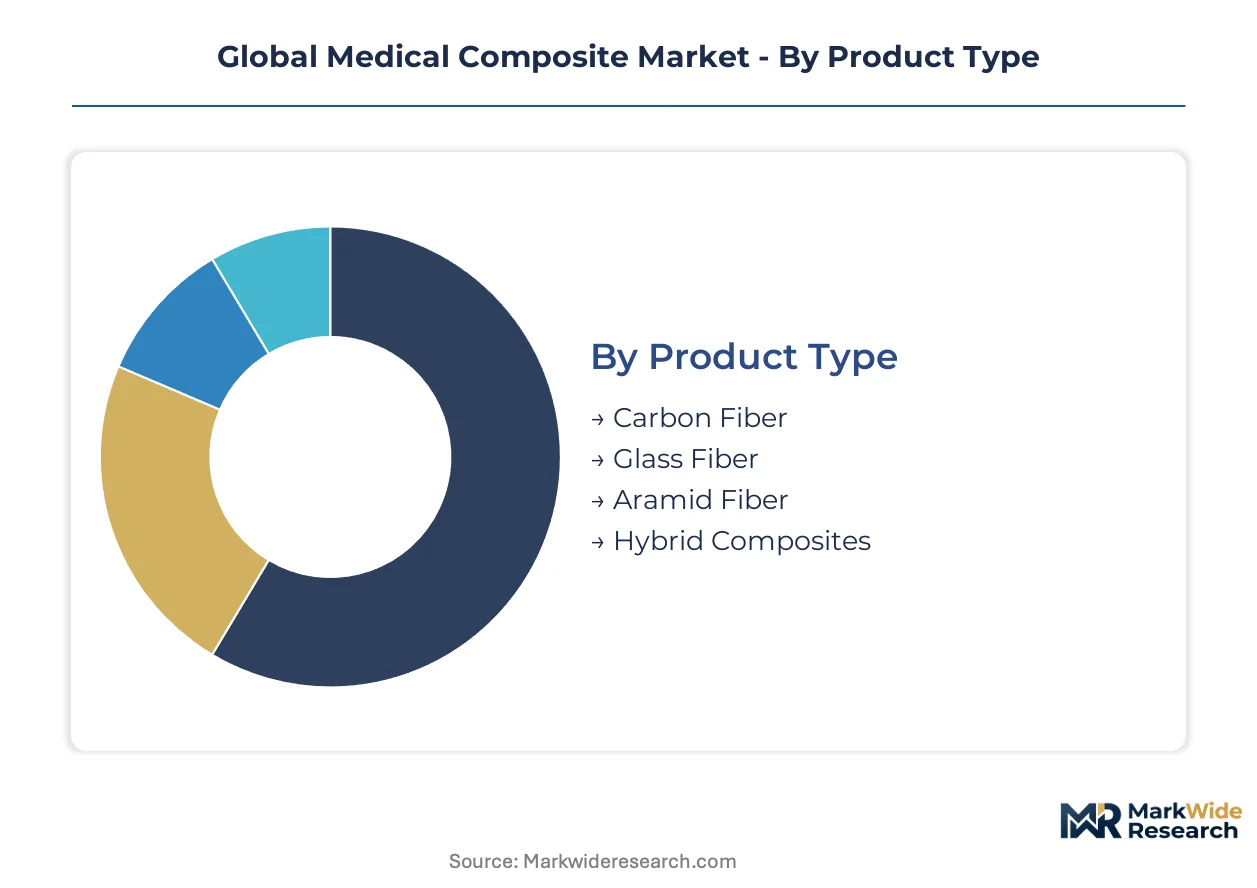
Segmentation in medical composites reveals how fiber selection, manufacturing method, and clinical setting interact to determine pricing power. Each dimension carries distinct margin structures shaped by regulatory validation burdens and production scalability.
Product Type:
Margin pools concentrate in fiber grades where biocompatibility certification creates supply scarcity and pricing leverage for qualified manufacturers.
- Carbon Fiber:Medical-grade carbon fiber rated at 230 GPa tensile modulus dominates structural orthopedic implants where radiolucency enables artifact-free post-operative MRI. Demand concentrates in spinal fixation and trauma plates from German precision machining clusters around Stuttgart and Tuttlingen, where orthopedic OEM supply chains align with composite fabrication capabilities.
- Glass Fiber:E-glass and S-glass formulations lead cost-sensitive dental and prosthetic segments where modulus requirements remain moderate and aesthetic layering demands translucency control. Italian and Chinese manufacturers capture volume in dental crown substructures and temporary prosthetic frameworks where price sensitivity exceeds performance thresholds.
- Aramid Fiber:Para-aramid grades serve ballistic protection in military-medical hybrid trauma systems and specialized orthopedic bracing where vibration damping properties outweigh radiolucency requirements.
- Hybrid Composites:Blended carbon-glass ply configurations optimize stiffness gradients in custom orthopedic braces and external fixation devices, expanding most quickly as manufacturers balance cost and performance in patient-specific geometries.
Carbon fiber holds installed capacity. Hybrid composites are rotating up the share rankings.
Application:
Application segments diverge sharply by regulatory pathway length, with permanent implant contact commanding premium pricing over external or temporary device categories.
- Orthopedic Devices:Load-bearing implants including spinal rods, trauma plates, and external fixation systems utilize continuous fiber-reinforced thermoplastic composites supplanting legacy autoclave-cured epoxy systems. FDA 21 CFR Part 820 quality system regulations and EU MDR Annex I requirements compress development cycles while favoring pre-qualified material formulations.
- Dental Implants:Fiber-reinforced composite posts and abutments compete with zirconia and titanium in esthetic zone restorations, with glass fiber formulations dominating where translucency matching natural dentition drives material selection.
- Prosthetics:Carbon fiber sockets and pylons in lower-limb prostheses balance strength-to-weight ratios against cost constraints in reimbursement-constrained markets.
- Surgical Instruments:Radiolucent retractors and positioning systems for MRI-guided procedures utilize carbon fiber grades where metal interference creates clinical limitations.
- Diagnostic Equipment:Patient tables and coil housings in magnetic resonance imaging systems leverage pitch-based carbon fiber for electromagnetic transparency.
Orthopedic devices concentrate manufacturing investment. Dental implants are climbing the fastest as chairside digital workflows expand addressable procedures.
End User:
End user segmentation tracks purchasing authority migration from centralized hospital procurement toward outpatient settings with distinct volume and customization requirements.
- Hospitals:Academic medical centers and tertiary hospitals maintain capital equipment budgets for reusable composite surgical instruments and diagnostic tables, though procurement consolidation pressures vendor margins.
- Ambulatory Surgical Centers:Outpatient procedure volume concentration creates procurement influence shifts favoring composite-intensive disposable and semi-disposable device categories in spinal implant and arthroscopic segments.
- Diagnostic Laboratories:Imaging centers demand radiolucent patient positioning systems compatible with high-field MRI scanners, with specifications tightening in purchasing contracts.
- Rehabilitation Clinics:Custom orthotic and prosthetic fabrication drives demand for moldable thermoplastic composites enabling in-situ patient fitting adjustments.
Hospitals retain bulk purchasing leverage. Ambulatory surgical centers are gaining share fastest as procedure migration accelerates.
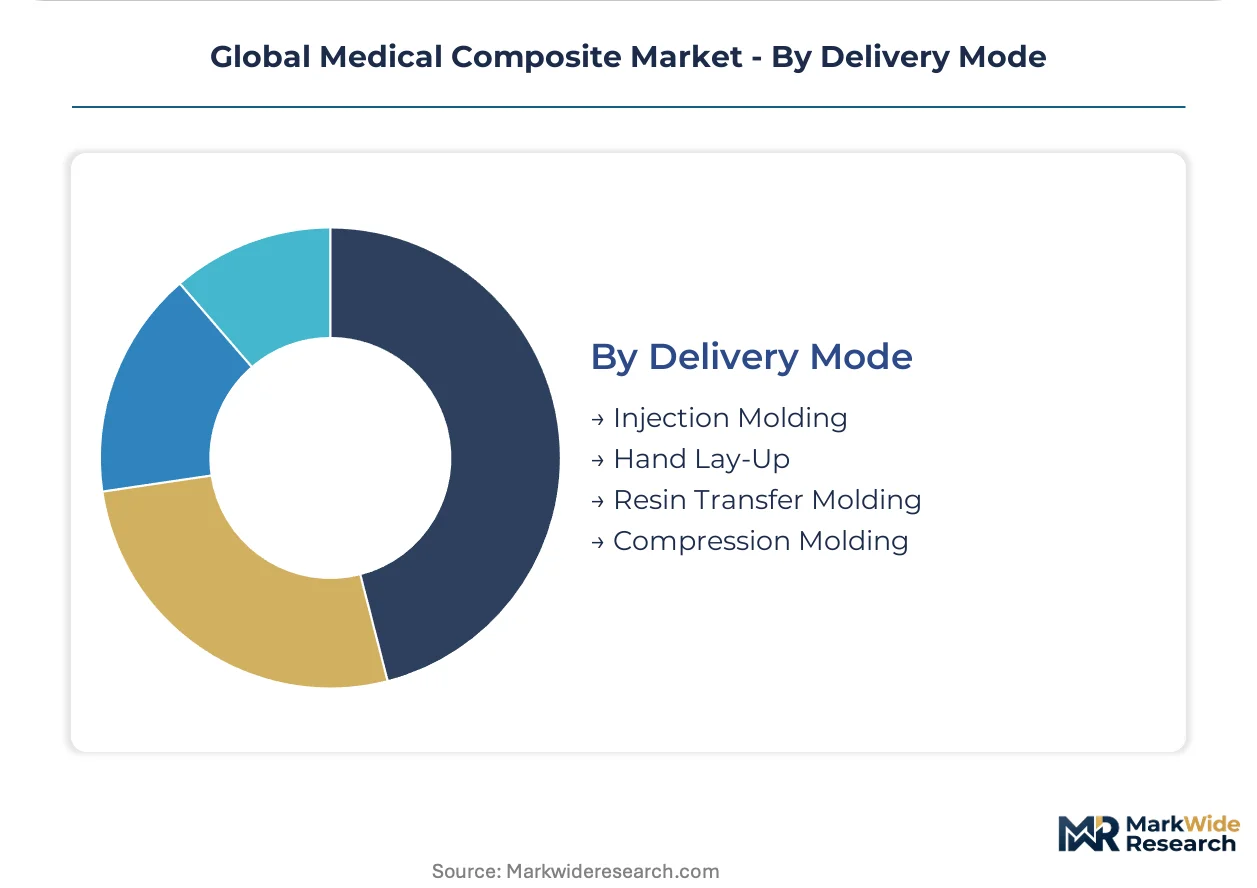
Delivery Mode:
Manufacturing method selection determines capital intensity, batch size flexibility, and regulatory reproducibility documentation burdens.
- Injection Molding:High-volume production of standardized dental and prosthetic components utilizes short-fiber reinforced thermoplastics where dimensional consistency and surface finish meet ISO 10993 biocompatibility requirements.
- Hand Lay-Up:Custom orthopedic braces and patient-specific prosthetic sockets rely on manual fiber placement for complex geometries where automation remains uneconomical at low volumes.
- Resin Transfer Molding:Medium-series production of surgical instrument housings and diagnostic equipment components balances fiber volume fraction control with mold cost amortization.
- Compression Molding:Prepreg-based consolidation for structural orthopedic implants achieves void-free laminates with documented batch traceability for EU MDR post-market surveillance requirements.
Compression molding holds qualified capacity for implant-grade output. Injection molding is rotating up as dental volume scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic OEM procurement offices concentrate in German precision machining corridors, while ambulatory surgical center chains in the United States and diagnostic imaging networks in Japan drive composite-intensive device demand.
United States
Ambulatory surgical centers now account for the majority of spinal implant and arthroscopic procedure volumes, pulling composite-intensive disposable device categories into outpatient procurement channels. FDA 21 CFR Part 820 quality system regulations compress supplier qualification timelines for carbon fiber-reinforced trauma fixation systems. Minneapolis and Warsaw, Indiana host concentrated orthopedic device manufacturing clusters where composite machining capabilities align with OEM supply chain requirements.
Germany
Stuttgart and Tuttlingen medical technology corridors concentrate precision composite fabrication capabilities that serve European orthopedic OEM supply chains. EU MDR Annex I general safety requirements and expanded post-market surveillance obligations extend commercialization timelines for permanent implant contact devices. Bavarian and Baden-Württemberg manufacturers with integrated precursor-to-prepreg operations capture disproportionate notified body approval velocity for carbon fiber structural implants.
Japan
Magnetic resonance imaging equipment manufacturers demand pitch-based carbon fiber for patient tables and coil housings where electromagnetic transparency enables high-field scanner compatibility. PMDA biocompatibility guidelines and METI industrial standards shape material validation protocols for long-term implantable devices. Nagoya and Osaka industrial zones concentrate composite fabrication capabilities serving domestic diagnostic equipment OEMs and export markets.
Switzerland
Swissmedic regulatory frameworks and ISO 10993 testing infrastructure attract medical composite compounders seeking European market access. Precision machining capabilities around Zurich and Basel align with orthopedic and dental device OEM supply chains. Domestic manufacturers leverage integrated toxicology and biocompatibility testing capabilities to accelerate fiber-resin combination validation timelines.
China
NMPA medical device registration requirements and GB standards for implantable materials are tightening documentation burdens for carbon fiber-reinforced orthopedic components. Domestic demand concentrates in diagnostic imaging equipment and cost-sensitive prosthetic segments where glass fiber formulations compete on price. Yangtze River Delta manufacturing clusters are developing medical-grade prepreg capabilities to serve both domestic hospitals and export markets.
Global Medical Composite Market Competitive Landscape
Player mix skews toward integrated fiber producers and specialized medical device material compounders with captive biocompatibility testing capabilities. Market structure concentrates around three strategic archetypes: upstream fiber manufacturers with medical-grade prepreg downstream operations; mid-tier compounders serving dental and prosthetic segments with standardized formulations; and niche specialists in patient-specific orthopedic bracing and external fixation systems. Dominant competitive moves include backward integration into precursor chemistry to secure carbon fiber supply chains, and strategic partnerships with orthopedic OEMs to co-develop implant-grade material formulations.
Within the integrated fiber-producer tier, Toray Industries Inc. and SGL Carbon SE exemplify archetypes with upstream control over precursor operations extending toward medical-grade finished materials. Dentsply Sirona occupies a position representing dental composite specialists with integrated material-scanner-milling workflows. These three companies anchor distinct competitive vectors: carbon fiber supply chain security, high-modulus pitch-based fiber specialization for radiolucent applications, and chairside digital workflow integration respectively.
| Leading Market Players |
|---|
| 3M Company |
| Toray Industries Inc. |
| Dentsply Sirona |
| Royal DSM |
| SGL Carbon SE |
| Kulzer GmbH |
| Zeus Industrial Products Inc. |
| IDC Composite International Inc. |
| Composiflex Inc. |
| Others |
Supply & Pricing Matrix
Carbon fiber precursor scale economies in Asian petrochemical corridors establish minimum efficient scale thresholds that compress margin structures for European and North American medical-grade prepreg manufacturers unable to match throughput volumes. This concentration dynamic elevates price floors for implant-grade carbon fiber while pushing compounders toward hybrid formulations that blend glass fiber cost advantages with selective carbon fiber performance zones.
Pricing Analysis
Cost-plus contracts with polyacrylonitrile indexation dominate raw material procurement between fiber producers and medical compounders, transferring commodity volatility directly into finished prepreg pricing. Three-tier pricing structure across premium implant-grade, standard device-grade, and economy dental-grade levels separates FDA-validated formulations from CE-marked and non-certified alternatives. Pricing pressure stems from distributor consolidation in United States and Western European procurement channels. Ambulatory surgical centers exhibit highest price sensitivity due to reimbursement constraints, while academic medical centers prioritize radiolucency performance over unit cost.
Supply Chain Analysis
Inventory buffers for medical-grade carbon fiber extend to six-month coverage given batch-level biocompatibility certification requirements and EU MDR traceability mandates. Supply concentrates in Japan, Germany, and the United States for high-modulus pitch-based fibers serving diagnostic equipment applications, while polyacrylonitrile precursor production draws from South Korean and Chinese petrochemical complexes. Single-source vulnerability characterizes medical-grade resin hardener supply given REACH substance restrictions on amine chemistry alternatives. Distribution runs through orthopedic OEM direct procurement offices in Stuttgart and Tuttlingen clusters, supplemented by GPO contracts for hospital system volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical composites sit in early-cycle expansion as carbon fiber reinforced polymers displace titanium alloys in load-bearing orthopedic segments, with radiolucency requirements accelerating penetration in spinal fixation and trauma applications.
For Market Incumbents: Secure captive carbon fiber supply through backward integration into precursor operations or long-term offtake agreements with Toray Industries and SGL Carbon, defending against Asian petrochemical producers' vertical integration moves. Prioritize ISO 10993 testing infrastructure investments to accelerate fiber-resin combination validation timelines as EU MDR post-market surveillance requirements harden. For New Entrants and Emerging Players: Anchor in hybrid composite white space for custom orthopedic braces and external fixation devices, where blended carbon-glass configurations face limited qualified competition and lower regulatory barriers than permanent implant contact categories. Target ambulatory surgical center procurement channels with disposable device formats, leveraging direct-to-provider logistics partnerships to bypass consolidated distributor tiers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with integrated toxicology capabilities and notified body relationships, positioning them for sustained OEM contract renewals. Long-term viability over a multi-year window favors acquisition targets with Bavarian or Baden-Württemberg manufacturing footprints and established EU MDR technical documentation. Watch FDA guidance convergence on additive-manufactured composite structures as inflection signal for next-generation implant geometry qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Toray Industries and SGL Carbon anchor supply security through captive polyacrylonitrile operations extending to medical-grade prepreg. |
| ISO 10993 Testing Infrastructure Expansion | Swiss and German compounders accelerate fiber-resin validation timelines through in-house toxicology capabilities and notified body relationships. |
| Hybrid Composite Product Development | Blended carbon-glass ply configurations capture custom orthopedic brace demand with optimized stiffness gradients and reduced certification burden. |
| Ambulatory Surgical Center Channel Direct Access | Dentsply Sirona and dental specialists bypass distributor consolidation through chairside digital workflow integration locking clinicians into proprietary resin systems. |
| EU MDR Technical Documentation Investment | German manufacturers with batch-level fiber provenance systems capture disproportionate approval velocity for permanent implant contact devices. |
Research Methodology
The analysis maps carbon fiber structural implants, glass fiber dental composites, hybrid orthopedic braces, and radiolucent diagnostic equipment segments, each validated through orthopedic device procurement directors, biomedical engineers, notified body auditors, and GPO contracts managers. Primary interviews with Stuttgart and Tuttlingen cluster manufacturers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and ISO 10993 testing records. Bottom-up volume builds across fiber grades and application categories triangulate against top-down OEM procurement spend estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled by fiber type, application regulatory pathway, end-user purchasing authority, and manufacturing method capital intensity. CAGRs derived from procedure volume migration patterns, material substitution elasticities, and reimbursement code evolution. Industry-specific forecast inputs include EU MDR post-market surveillance cost inflation and carbon fiber precursor capacity expansion timelines.
Material uncertainties — regulatory guidance revisions on additive-manufactured composites, polyacrylonitrile supply disruptions, and REACH substance restriction expansions — sit outside the modeled envelope. Forecasts reflect assumptions regarding fiber-resin biocompatibility validation standardization and ambulatory surgical center procurement influence trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Diabetes Devices Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Flow Diverters Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market