
 Middle East and Africa Aligner Sheet Market | 2026-2036
Middle East and Africa Aligner Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aligner Sheet Market Foresight
Buyer concentration among orthodontic clinics is realigning as dental hospital chains across Saudi Arabia and the UAE consolidate procurement decisions. Align Technology, Inc. leverages its direct-to-practitioner digital workflow to sustain premium positioning in Gulf markets. Dentsply Sirona Inc. anchors its regional presence through distributor partnerships that extend into North African territories. Straumann Holding AG competes by specializing in high-transparency thermoplastic formulations tailored to Middle Eastern patient preferences.
The Middle East and Africa Aligner Sheet refers to thin, formable polymer membranes engineered from multilayer thermoplastic or polyurethane compositions, typically manufactured through vacuum forming or precision injection molding to achieve controlled elastic modulus and optical clarity for sequential tooth repositioning. Thermoplastic sheets dominate current volume due to established cost structures and broad compatibility with intraoral scanning workflows, while polyurethane variants capture expanding margin pools among premium orthodontic providers seeking enhanced stain resistance and patient comfort. CAD/CAM technology integration is displacing conventional impression-based fabrication across mid-tier and premium segments, though vacuum forming retains substantial share in price-sensitive North African markets where equipment capital constraints persist.
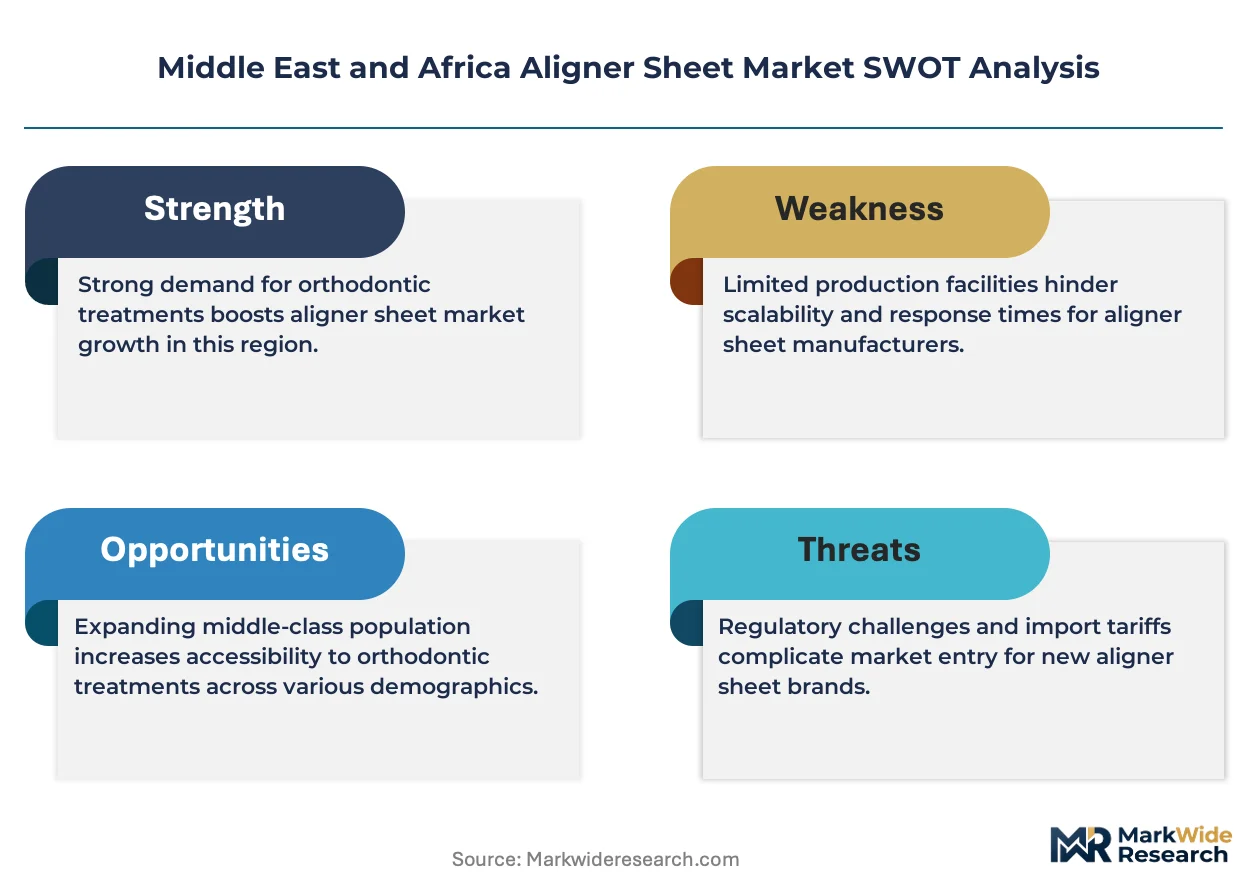
SFDA in Saudi Arabia and MOHAP in the UAE enforce biocompatibility and polymer traceability standards that elevate compliance costs for sheet suppliers while creating barriers against unvalidated imports. South Africa's national health regulator applies ISO 13485-aligned quality system requirements that shape procurement specifications for public-sector dental tenders. Stakeholders must monitor evolving polymer substance restrictions under Gulf harmonization initiatives and assess localized manufacturing partnerships to mitigate cross-border certification delays.
Market Dynamics
Biocompatibility certification requirements from SFDA and MOHAP are restructuring supplier qualification protocols across Saudi Arabia and the UAE, forcing sheet manufacturers to absorb elevated compliance costs or exit premium distribution channels entirely.
Growth Catalysts
- Healthcare privatization mandates:Saudi Vision 2030 directives channel sovereign investment into specialized dental services, expanding the addressable base for premium aligner materials.
- CAD/CAM intraoral scanning:Digital impression workflows are compressing fabrication timelines and reducing chairside labor costs for orthodontic clinics across Gulf states.
- Polyurethane formulation advances:Enhanced stain resistance and elastic recovery properties are capturing margin pools among high-end providers serving aesthetic-conscious patient segments.
Market Restraints
- Petrochemical feedstock volatility:Thermoplastic polyurethane and multilayer PETG sheet production faces margin pressure from crude-linked raw material cost swings.
- Equipment capital barriers:Precision injection molding and automated vacuum forming systems require substantial upfront investment, limiting indigenous manufacturing scale-up in North African markets.
- SFDA polymer traceability mandates:Lot-level documentation requirements extend certification timelines and elevate working capital needs for import-dependent distributors.
Strategic Opportunities
- South Africa public-sector tenders:ISO 13485-aligned procurement specifications create qualified supplier status for manufacturers willing to navigate extended validation cycles.
- Localized Gulf manufacturing partnerships:Joint ventures with Saudi industrial zone operators can bypass cross-border certification delays and capture government localization incentives.
- AI-driven treatment planning convergence:Machine learning algorithms integrated with thermoforming parameters enable mass-customization at unit economics competitive with standardized offerings.
Industry Challenges
- Biomedical polymer engineering talent scarcity:Formulation chemists with dental device experience command premium compensation in Dubai and Riyadh labor markets.
- Legacy impression-to-digital workflow integration:Mid-tier clinics struggle to amortize scanner investments while maintaining hybrid service capabilities.
- Harmonized Gulf substance restriction timelines:Divergent implementation schedules between SFDA and MOHAP create inventory segmentation complexity for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aligner Sheet Market |
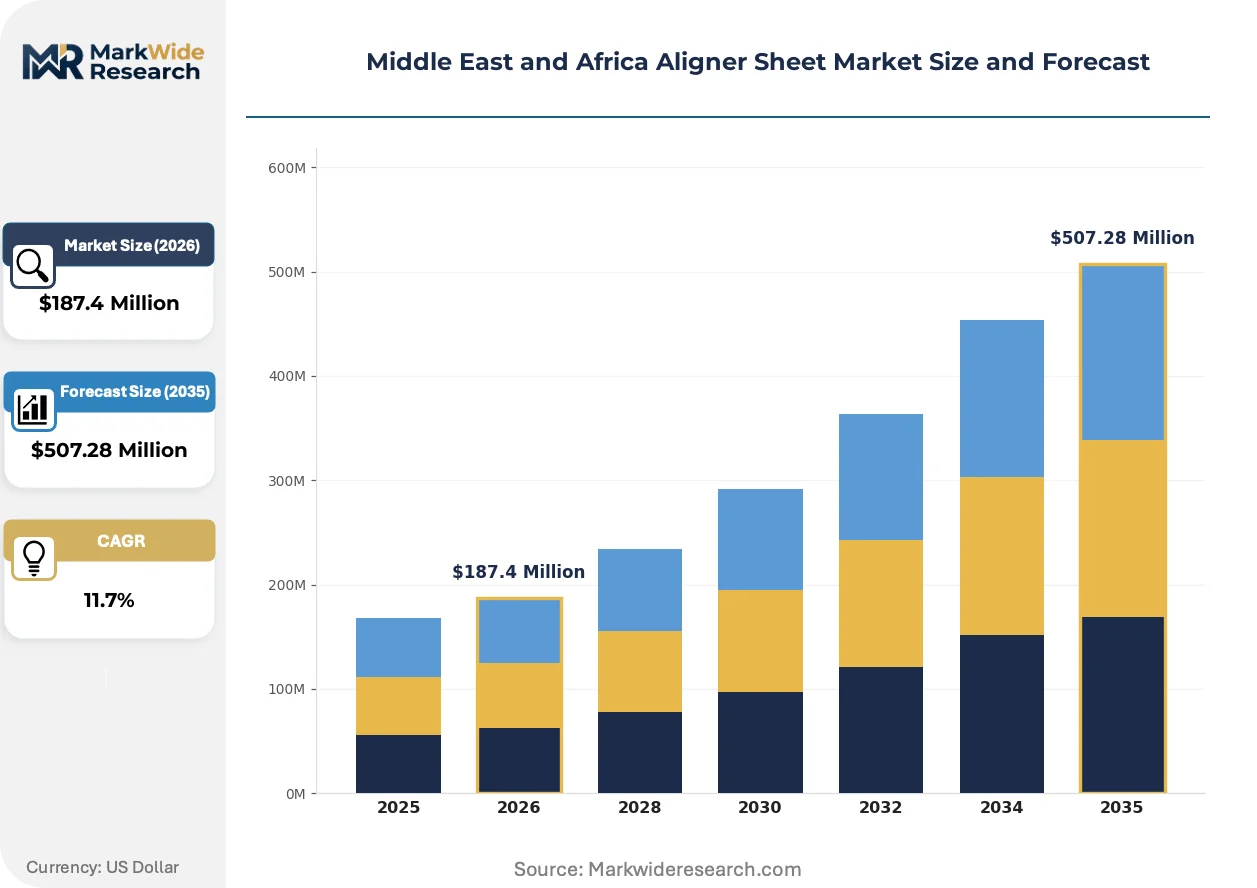
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Polycarbonate, Polyurethane, Others End User: Orthodontic Clinics, Dental Hospitals, Dental Laboratories, Individual Practitioners Technology: 3D Printing, Injection Molding, CAD/CAM, Vacuum Forming Distribution Channel: Online Stores, Direct Sales, Distributors, Third-Party Retailers |
| Companies Covered | Align Technology, Inc., Dentsply Sirona Inc., Straumann Holding AG, Ormco Corporation, 3M Company, Henry Schein, Inc., Envista Holdings Corporation, AccuAligners, Institut Straumann AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aligner Sheet Market Shifts & Advancements
Digital fabrication protocols and regulatory transparency mandates are converging to reshape how aligner sheet specifications propagate from manufacturer to end-user across Middle Eastern and African supply chains.
Multilayer co-extrusion technology combining rigid structural cores with soft-tissue contact layers is rewriting performance benchmarks for extended-wear orthodontic appliances. Premium clinics in Dubai and Jeddah are adopting these formulations at accelerated rates to differentiate patient comfort claims. The technology is compressing competitive differentiation around traditional single-material sheets and elevating R&D spend thresholds for regional market entry.
MOHAP's 2024 biocompatibility disclosure requirements for dental polymers are forcing reformulation documentation across UAE import channels. Manufacturers must now submit comprehensive migration testing data for all polymer additives, extending product registration timelines by four to six months. Small-scale Asian suppliers lacking dedicated regulatory affairs capabilities are retreating from Dubai distribution networks as compliance costs escalate.
Direct-to-clinic digital procurement platforms are displacing traditional dental distributor intermediaries across Saudi Arabia's consolidated orthodontic chains. Hospital groups in Riyadh and Khobar are centralizing aligner sheet purchasing through integrated supply portals that link inventory management with treatment planning software. This channel compression is most visible among mid-tier clinic networks seeking to recover margin lost to premium brand licensing fees.
Middle East and Africa Aligner Sheet Market Segmentation
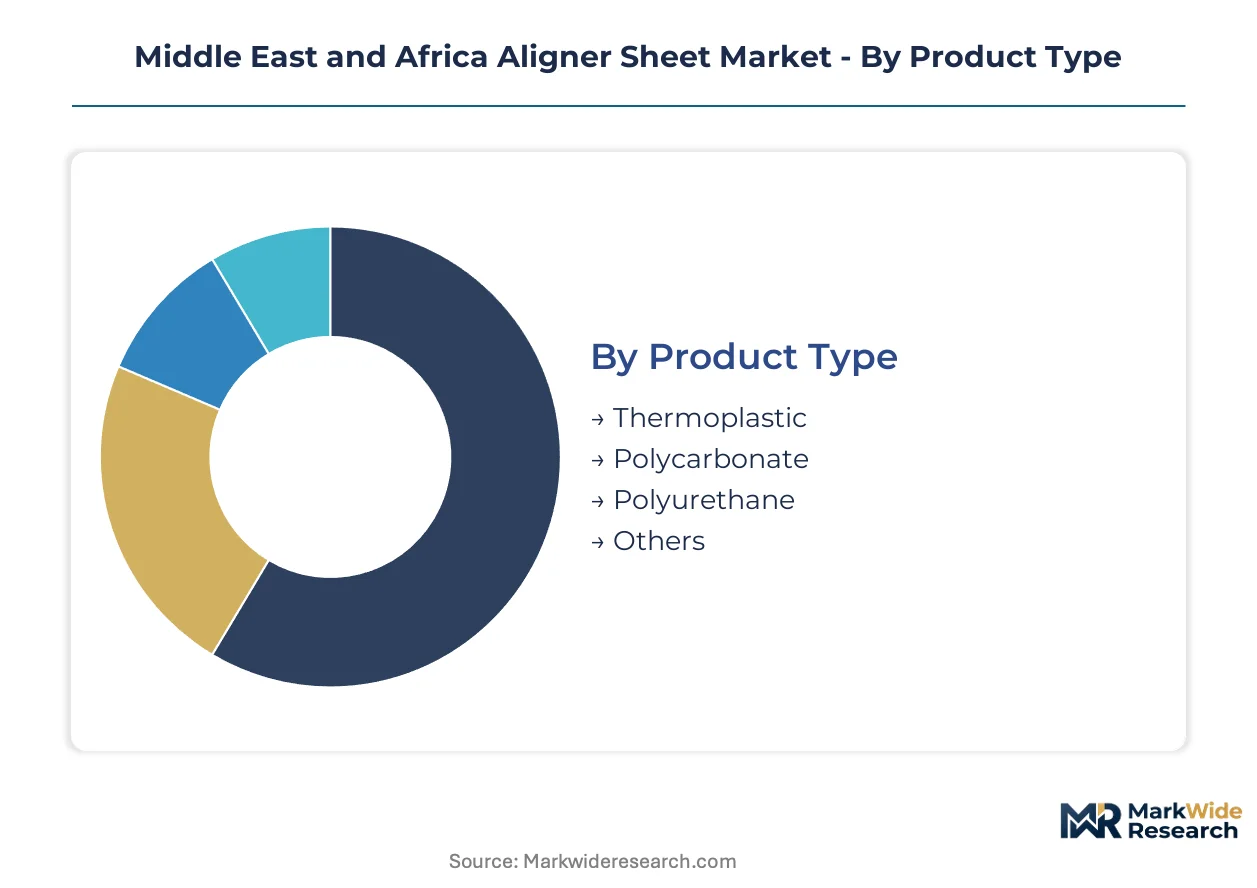
Segmentation in the Middle East and Africa Aligner Sheet Market reveals how material specifications, fabrication technologies, and procurement channels stratify competitive positioning across diverse clinical and economic environments. Understanding these divisions illuminates where formulation investments concentrate and which access routes dominate regional supply.
Product Type:
Material composition determines elastic modulus, optical clarity, and biocompatibility certification pathways across Gulf and African regulatory environments.
- Thermoplastic:Multilayer PETG and TPU formulations deliver controlled force delivery and broad intraoral scanner compatibility. Orthodontic clinics in Saudi Arabia and the UAE standardize procurement around thermoplastic sheets due to established vacuum forming workflows and cost predictability amid petrochemical feedstock fluctuations.
- Polyurethane:Advanced aliphatic polyurethane compositions offer superior stain resistance and elastic recovery for extended wear cycles. Premium providers in Dubai and Jeddah capture margin pools by specifying these formulations for aesthetic-conscious patient segments seeking discreet treatment options.
- Polycarbonate:High-impact transparent polymers serve price-sensitive North African markets where equipment capital constraints limit multilayer co-extrusion adoption.
- Others:Experimental biodegradable polymers and shape-memory alloys occupy niche research pipelines without commercial scale in regional distribution channels.
Thermoplastic leads on scale; polyurethane leads on momentum.
End User:
Customer type segmentation tracks consolidation patterns and procurement centralization across public and private dental delivery systems.
- Orthodontic Clinics:Specialized practices in Riyadh and Khobar drive volume through direct-to-clinic digital procurement platforms that compress distributor margins and accelerate inventory turnover.
- Dental Hospitals:Consolidated hospital chains across Saudi Arabia and the UAE centralize purchasing decisions through integrated supply portals linking inventory management with treatment planning software.
- Dental Laboratories:Independent fabrication facilities in South Africa serve mid-tier clinics with hybrid analog-digital workflows, absorbing scanner investment costs on behalf of smaller practitioners.
- Individual Practitioners:Solo operators in North African markets remain tethered to traditional distributor networks due to fragmented demand and limited capital for digital infrastructure.
Dental hospitals lead on scale; orthodontic clinics lead on momentum.
Technology:
Fabrication method segmentation captures the displacement trajectory from analog vacuum forming toward precision digital protocols.
- CAD/CAM:Computer-aided design and manufacturing compresses fabrication timelines from weeks to days, with intraoral scanning penetration deepest among premium Gulf state clinics seeking chairside labor cost reduction.
- Vacuum Forming:Conventional thermoforming retains substantial share in price-sensitive North African markets where automated precision injection molding systems remain capital-prohibitive for indigenous manufacturers.
- 3D Printing:Direct photopolymer fabrication of aligner shells is gaining traction among Dubai-based laboratories experimenting with mass-customization at unit economics competitive with thermoforming.
- Injection Molding:Precision multilayer co-extrusion enables rigid-soft composite structures for extended-wear appliances, though equipment costs limit adoption to large-scale regional production facilities.
Vacuum forming leads on scale; CAD/CAM leads on momentum.
Distribution Channel:
Route-to-market segmentation reflects channel compression as consolidated clinic networks bypass traditional intermediaries.
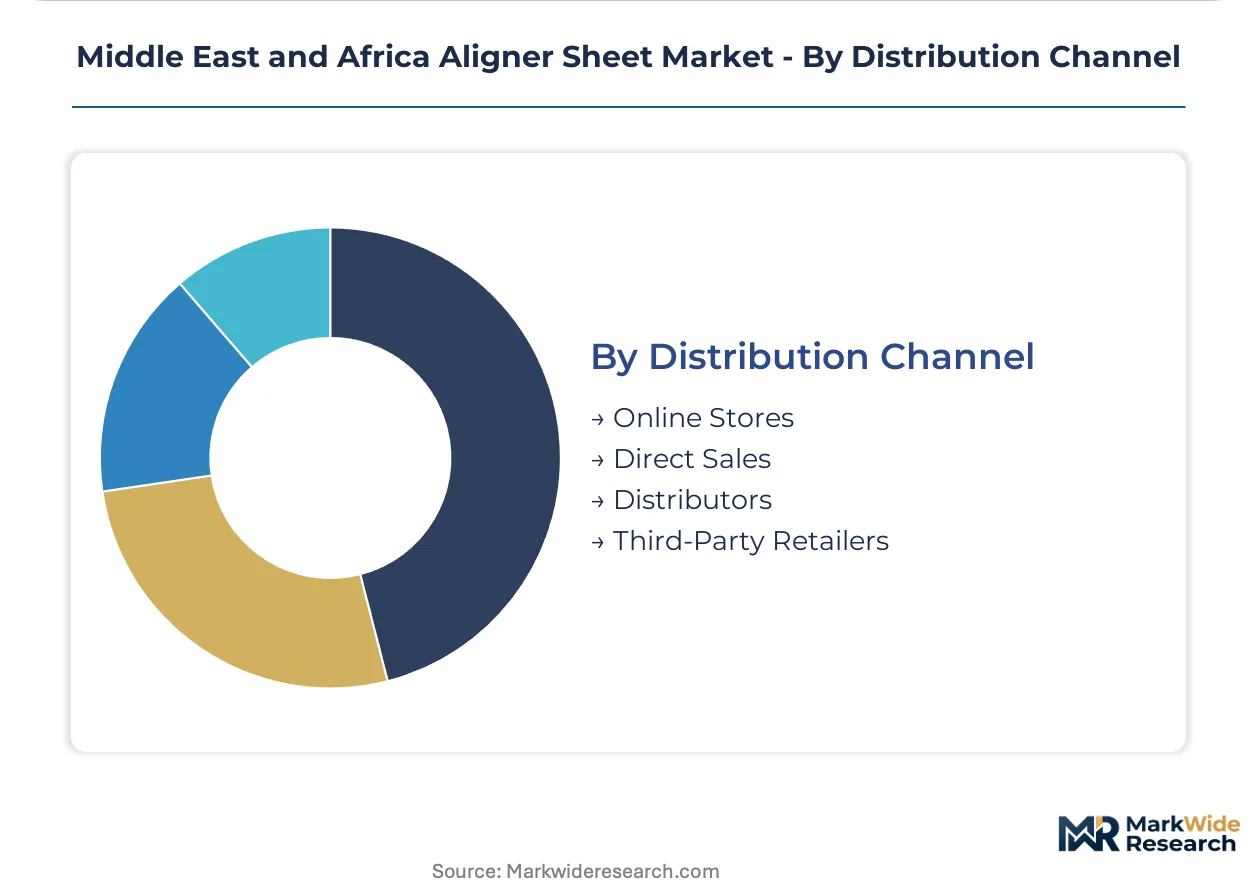
- Direct Sales:Manufacturer-to-clinic relationships dominate Saudi Arabia's consolidated orthodontic chains, with hospital groups in Riyadh centralizing aligner sheet purchasing through proprietary supply portals.
- Distributors:Traditional dental supply intermediaries retain relevance in North African territories and among smaller South African laboratories lacking volume leverage for direct manufacturer negotiations.
- Online Stores:Digital procurement platforms are displacing conventional distribution across mid-tier clinic networks seeking to recover margin lost to premium brand licensing fees.
- Third-Party Retailers:General medical supply houses serve fragmented individual practitioner demand with limited product specialization and extended fulfillment timelines.
Distributors lead on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands premium aligner sheet volume while South Africa anchors mid-tier fabrication capacity across the African continent. Divergent regulatory timelines between Gulf Cooperation Council members and sub-Saharan markets create distinct procurement corridors for sheet suppliers.
Saudi Arabia
Vision 2030 healthcare privatization directs sovereign investment toward specialized dental services in Riyadh and Jeddah. SFDA enforces lot-level polymer traceability mandates that extend certification timelines for import-dependent distributors. The King Abdullah Financial District cluster hosts consolidated orthodontic chains centralizing procurement through proprietary digital supply portals.
United Arab Emirates
Dubai's premium clinic networks drive polyurethane formulation adoption for aesthetic-conscious patient segments. MOHAP's 2024 biocompatibility disclosure requirements force comprehensive migration testing documentation for all polymer additives. Jebel Ali industrial zones attract localized manufacturing partnerships seeking government localization incentives.
South Africa
Dental laboratories in Johannesburg and Cape Town absorb scanner investment costs on behalf of mid-tier clinics with hybrid analog-digital workflows. The national health regulator applies ISO 13485-aligned quality system requirements shaping public-sector tender specifications. Independent fabrication facilities concentrate in Gauteng province serving price-sensitive practitioners.
Egypt
Cairo-based orthodontic clinics remain tethered to traditional distributor networks due to fragmented demand and limited capital for digital infrastructure. The country's national pharmaceutical regulator maintains evolving biocompatibility standards for imported dental polymers. Equipment capital barriers limit indigenous manufacturing scale-up in Nile Delta industrial corridors.
Israel
Tel Aviv medical technology clusters pioneer AI-driven treatment planning convergence with thermoforming parameter optimization. The national health regulator enforces stringent polymer substance restrictions aligned with European medical device directives. Research partnerships between Haifa-based universities and fabrication laboratories accelerate experimental biodegradable polymer development.
Middle East and Africa Aligner Sheet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material formulation and distribution channel access. The vendor base stratifies into three tiers: multinational dental device conglomerates with integrated digital workflows, regional thermoplastic distributors serving price-sensitive markets, and emerging polyurethane specialists capturing premium margin pools. Consolidation pressures intensify as direct-to-clinic procurement platforms compress traditional intermediary margins. Dominant competitive moves include backward integration into polymer compounding capabilities and strategic partnerships with Gulf industrial zone operators.
Within the multinational conglomerate tier, Align Technology, Inc. and Dentsply Sirona Inc. exemplify divergent route-to-market strategies. Align Technology occupies a position emphasizing direct-to-practitioner digital workflow integration. Dentsply Sirona anchors regional presence through distributor partnerships extending into North African territories. Straumann Holding AG sits within the premium formulation specialist archetype, with its AG corporate structure indicating Swiss-based biomedical materials expertise.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona Inc. |
| Straumann Holding AG |
| Ormco Corporation |
| 3M Company |
| Henry Schein, Inc. |
| Envista Holdings Corporation |
| AccuAligners |
| Institut Straumann AG |
| Others |
Supply & Pricing Matrix
Biomedical polymer engineering talent scarcity in Dubai and Riyadh labor markets widens pricing-tier spreads between premium polyurethane formulations and commodity thermoplastic alternatives, as specialized formulation chemists command compensation premiums that propagate through finished sheet costs.
Pricing Analysis
Capacity additions in Saudi Arabia's industrial zones are reshaping price floors for multilayer thermoplastic sheets by reducing import-dependent logistics overhead. Pricing stratifies across premium polyurethane, standard PETG, and economy polycarbonate tiers based on biocompatibility certification grade and elastic modulus performance. Cost compression in the polycarbonate tier is intensifying because equipment capital barriers in North Africa limit indigenous manufacturing scale-up. Dental hospital chains exhibit lowest price sensitivity due to centralized procurement volume leverage, while individual practitioners in Egypt remain most price-constrained.
Supply Chain Analysis
Saudi localization incentives and domestic-content mandates for healthcare procurement are reshaping sourcing patterns away from Asian import dependency toward Gulf-based manufacturing partnerships. Raw material supply draws from petrochemical feedstock concentrations in Saudi Arabia, specialty additive suppliers in Germany, and precision molding equipment from Japan. Single-source vulnerability persists for aliphatic polyurethane resin grades certified to SFDA traceability standards. Distribution runs through direct-to-clinic digital portals for consolidated orthodontic chains and traditional dental distributors for fragmented North African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Aligner Sheet Market functions as a stable compounder, with healthcare privatization mandates under Saudi Vision 2030 channeling sovereign investment into specialized dental services that sustain recurring demand for premium materials.
For Market Incumbents: Lock in backward integration into polymer compounding capabilities to defend margin position against petrochemical feedstock volatility. Secure SFDA and MOHAP biocompatibility certifications ahead of harmonized Gulf substance restriction timelines to create switching costs for clinic procurement committees.
For New Entrants and Emerging Players: The price-point gap between premium polyurethane and economy polycarbonate tiers offers white-space entry for mid-tier thermoplastic specialists. Target South African public-sector tenders where ISO 13485-aligned procurement specifications favor qualified new suppliers willing to navigate extended validation cycles. Pursue joint venture structures with Jebel Ali industrial zone operators to bypass cross-border certification delays.
For Investors and Strategic Acquirers: Dental device conglomerates seeking digital workflow integration are the most active acquirer in this space. The 5-10 year viability window favors targets with captive polymer formulation expertise and established Gulf regulatory affairs capabilities. Monitor AI-driven treatment planning convergence with thermoforming parameter optimization as the inflection signal for mass-customization economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Gulf Manufacturing Partnership | Joint ventures with Saudi industrial zone operators capture government localization incentives and bypass SFDA certification delays. |
| Biocompatibility Certification Investment | Comprehensive migration testing documentation for MOHAP disclosure requirements extends product registration timelines but creates barriers against unvalidated imports. |
| Direct-to-Clinic Digital Procurement Platform | Integrated supply portals linking inventory management with treatment planning software compress distributor margins and accelerate inventory turnover. |
| Multilayer Co-Extrusion Technology Adoption | Rigid structural cores combined with soft-tissue contact layers rewrite performance benchmarks for extended-wear orthodontic appliances in Dubai and Jeddah. |
| AI-Driven Treatment Planning Integration | Machine learning algorithms optimizing thermoforming parameters enable mass-customization at unit economics competitive with standardized offerings. |
Research Methodology
Coverage spans Saudi Arabia, the United Arab Emirates, South Africa, Egypt, and Israel, with primary inputs from each market combining structured interviews with orthodontic clinic directors, dental hospital procurement managers, biomedical polymer formulation chemists, and regulatory affairs specialists at SFDA and MOHAP with secondary validation from customs trade data, SEC 10-K filings of listed dental device manufacturers, hospital procurement databases, and GPO contracts. Bottom-up volume estimates triangulate against top-down market sizing across material type and end-user segments.
Granularity-level modeling disaggregates the Middle East and Africa Aligner Sheet Market by product type, end user, technology, and distribution channel, with additional dimensional analysis across regional regulatory clusters and certification grade tiers. CAGRs derive from fitted growth curves applied to base-year volume and value estimates, incorporating petrochemical feedstock price indices, intraoral scanner penetration rates, and healthcare privatization investment flows as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for 3D-printed photopolymer fabrication would alter the outlook if unit economics compress faster than thermoforming parameter optimization. Forecasts reflect assumptions regarding SFDA-MOHAP regulatory harmonization schedules and sovereign healthcare investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Heat Therapy Units Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Implantable Drug Delivery Devices Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Japan Hemostats Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market