
 Cardiopulmonary Auto-Transfusion System Market | 2026-2036
Cardiopulmonary Auto-Transfusion System Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiopulmonary Auto-Transfusion System Market Analysis
CE marking under the EU Medical Device Regulation is expanding the cost-of-entry calculus for auto-transfusion system manufacturers seeking European market access. Haemonetics Corporation leverages its integrated plasma collection and processing portfolio to anchor its position in automated blood recovery workflows. LivaNova PLC sustains competitive differentiation through its specialized cardiac surgery equipment ecosystem. Fresenius SE & Co. KGaA dominates hospital dialysis and transfusion service channels, extending its reach into perioperative blood management.
A cardiopulmonary auto-transfusion system is a sterile extracorporeal device that collects, filters, and reinfuses a patient's shed blood during or after surgery, typically processing volumes of 500–2000 mL per cycle through centrifugal wash or filtration protocols. Its primary purpose is to reduce allogeneic blood transfusion requirements, lower infection risk, and conserve blood bank inventory in high-bleeding surgical procedures. Closed systems command the largest installed base due to their lower contamination risk and streamlined workflow integration in cardiac surgery, while automated systems are capturing the fastest expansion as hospitals prioritize labor reduction and standardized wash protocols. Orthopedic surgery represents a growing application segment where prolonged tourniquet release and intraoperative blood loss create substantial reinfusion opportunity.
The FDA enforces 510(k) premarket notification requirements and quality system regulation compliance for auto-transfusion devices, directly shaping product development timelines and clinical validation burdens. EMA's Medical Device Regulation mandates post-market surveillance and unique device identification, tightening traceability standards across European hospital supply chains. Health Canada and Japan's PMDA impose parallel but distinct software validation and biocompatibility testing protocols, fragmenting regulatory pathways for multinational manufacturers. Stakeholders must monitor evolving software-as-a-medical-device classifications and predicate device strategies to anticipate submission complexity and time-to-market exposure.
Market Dynamics
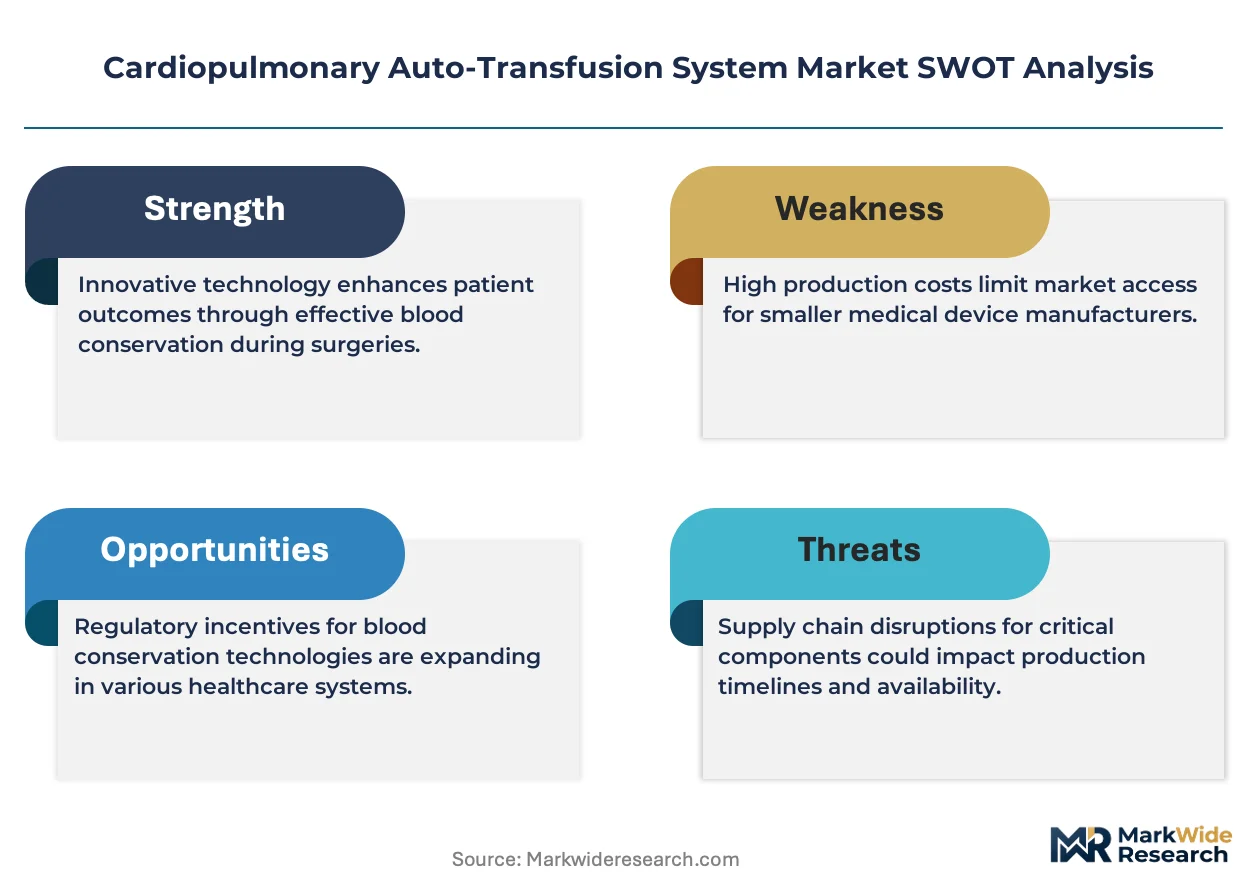
Automated wash protocol standardization is compressing manual processing margins while FDA software validation requirements extend product development timelines for device manufacturers.
Growth Catalysts
- 510(k) pathway clarity:FDA's streamlined predicate device recognition for closed-system auto-transfusion hardware accelerates hospital procurement cycles in the United States.
- Cardiac surgery volume concentration:High-bleeding procedures in tertiary centers create predictable installed-base expansion for intraoperative blood recovery platforms.
- Centrifugal wash automation:Labor reduction in perfusion teams drives replacement demand from semi-automated to fully automated processing systems.
Market Restraints
- Single-use consumable cost structure:Blood bags, filters, and tubing sets account for recurring per-procedure expenses that strain fixed DRG reimbursement in cardiac surgery.
- European supply concentration:CE marking under MDR consolidates notified body capacity in Germany and the Netherlands, creating submission bottlenecks for mid-tier manufacturers.
- Filtration protocol limitations:Fat microemboli and activated leukocyte clearance rates in orthopedic shed blood remain inferior to centrifugal wash performance.
Strategic Opportunities
- Japan's aging surgical population:PMDA's accelerated review pathway for blood conservation devices opens penetration in Tokyo and Osaka metropolitan hospital networks.
- Orthopedic trauma expansion:Pelvic fracture and revision arthroplasty procedures generate substantial unprocessed blood loss suitable for recovery system deployment.
- EU Green Deal alignment:Blood bank inventory reduction programs qualify for sustainability-linked procurement preferences in French and Italian public hospital tenders.
Industry Challenges
- Perfusionist workforce scarcity:Specialized training requirements for extracorporeal circuit management limit operational scaling in mid-volume surgical centers.
- Legacy EMR integration friction:Blood loss documentation and reinfusion volume tracking require custom HL7 interface development for hospital information systems.
- Software-as-medical-device reclassification:Algorithm-driven wash parameter adjustment triggers additional clinical validation burdens under evolving FDA guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiopulmonary Auto-Transfusion System Market |
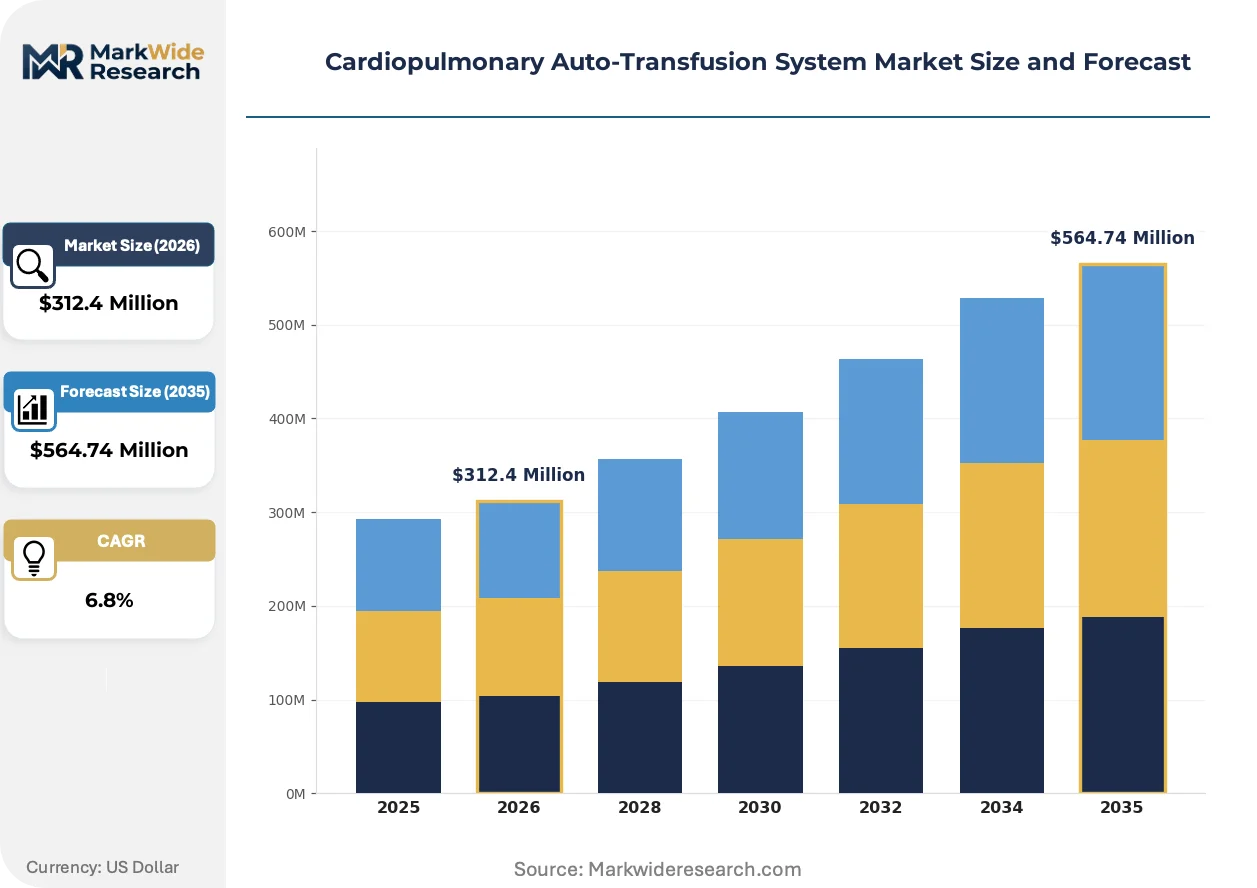
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed System, Open System, Semi-Closed System, Automated System End User: Hospitals, Surgical Centers, Blood Banks, Emergency Services Technology: Centrifugation, Filtration, Reservoir Management, Infusion Pump Application: Cardiac Surgery, Orthopedic Surgery, Trauma Surgery, Transplant Surgery |
| Companies Covered | Haemonetics Corporation, LivaNova PLC, Medtronic, Fresenius SE & Co. KGaA, Zimmer Biomet, BD, Teleflex Incorporated, Braile Biomédica, Atrium Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiopulmonary Auto-Transfusion System Market Emerging Trajectories
Device intelligence and regulatory digitization are restructuring competitive advantage around data integrity and post-market surveillance capabilities rather than hardware durability alone.
Closed-loop sensor arrays with real-time hematocrit monitoring are consolidating quality control functions previously requiring manual sampling and laboratory turnaround. Cardiac surgery suites in Germany and Japan are deploying these systems to reduce perfusionist cognitive load during prolonged bypass procedures. The technology is consolidating vendor selection criteria around software validation depth rather than mechanical reliability metrics.
EMA's Medical Device Regulation mandates unique device identification and enhanced post-market surveillance traceability across European hospital supply chains. Manufacturers must maintain electronic technical documentation accessible to notified bodies for unannounced audits. Class III auto-transfusion devices face tightened clinical evidence requirements for renewal of CE certificates, favoring incumbents with established PMCF study infrastructure.
Hospital value analysis committees now require total cost-of-ownership modeling that incorporates consumable spend, device utilization rates, and avoided allogeneic transfusion costs. This purchasing behavior shift favors vendors offering per-procedure service contracts over capital equipment sales in United States integrated delivery networks. The model compresses sales cycles but demands robust utilization analytics platforms to demonstrate reinfusion volume capture rates.
Cardiopulmonary Auto-Transfusion System Market Segmentation
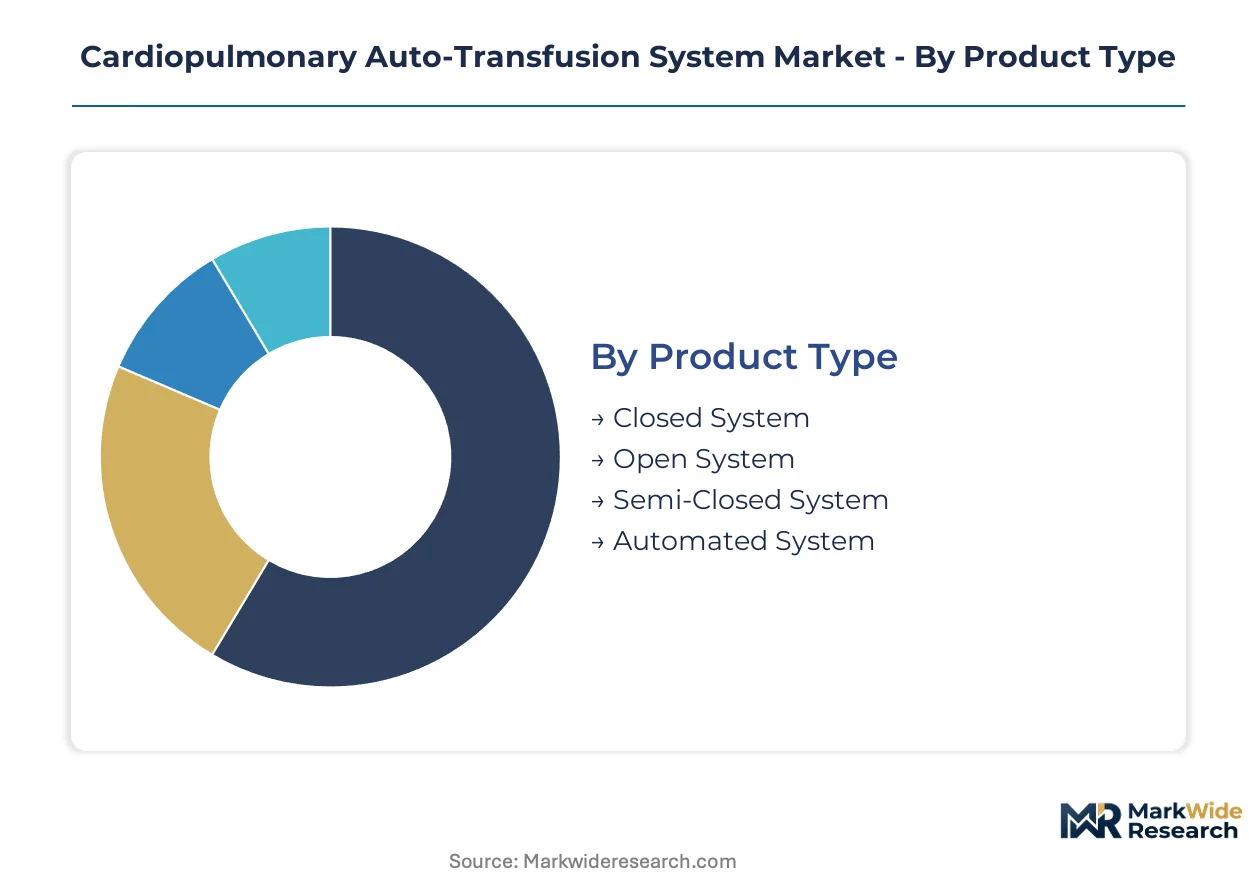
Segmentation in the cardiopulmonary auto-transfusion system market reveals how technology integration depth shapes procurement patterns across surgical workflows. Hospitals prioritize systems that minimize perfusionist intervention while maximizing blood recovery yield in high-bleeding procedures.
Product Type:
Closed systems operate as standalone units with sealed circuits, while automated platforms embed intelligence for wash protocol optimization.
- Closed System:Sealed extracorporeal circuits with integrated blood bags and filtration manifolds eliminate atmospheric exposure during collection and reinfusion. Demand concentrates in United States tertiary cardiac centers where Joint Commission infection control standards drive preference for barrier-protected workflows. The installed base remains largest due to proven reliability in prolonged cardiopulmonary bypass procedures.
- Automated System:Microprocessor-controlled centrifugal wash platforms adjust saline volumes and spin parameters based on real-time hematocrit feedback. German university hospitals deploy these systems to reduce perfusionist staffing ratios in high-volume surgical suites. Labor reduction and standardized output quality accelerate replacement demand from semi-automated predecessors.
- Open System:Manually operated collection reservoirs requiring direct technician handling during processing steps.
- Semi-Closed System:Hybrid designs with partial automation of wash cycles but manual transfer between collection and reinfusion stages.
Volume placements concentrate in Closed System configurations; the faster expansion belongs to Automated System platforms.
End User:
Procurement authority and reimbursement structures vary sharply across facility types, with capital allocation cycles spanning months for hospitals versus weeks for surgical centers.
- Hospitals:Tertiary medical centers with dedicated perfusion departments and cardiac surgery volume above 500 procedures annually. United States integrated delivery networks bundle auto-transfusion into value-based cardiac care contracts with commercial payers. DRG reimbursement constraints favor per-procedure service agreements over equipment purchases.
- Surgical Centers:Ambulatory facilities focusing on orthopedic and trauma procedures with shorter length-of-stay requirements. Japan's metropolitan outpatient surgical networks adopt compact filtration-based systems for same-day joint replacement protocols. Lower capital thresholds and faster procurement cycles attract mid-tier equipment vendors.
- Blood Banks:Regional collection and processing facilities extending into perioperative blood management services.
- Emergency Services:Pre-hospital and trauma bay applications requiring portable, rapid-deployment configurations.
Capital deployment concentrates in Hospitals; Surgical Centers are gaining share fastest as outpatient arthroplasty volumes climb.
Technology:
Wash methodology determines cellular salvage efficiency and fat microemboli clearance, with centrifugation commanding premium positioning over filtration in cardiac applications.
- Centrifugation:Density-gradient separation protocols achieving hematocrit concentrations of 50-60% with leukocyte depletion exceeding 95%. Cardiac surgery suites in Japan and Germany specify centrifugal wash for allogeneic transfusion avoidance in Jehovah's Witness patient populations. The technology anchors premium system pricing due to component complexity and validated clinical outcomes.
- Filtration:Membrane-based separation using pore-size exclusion for rapid processing without centrifugal mechanics. Orthopedic trauma units in United States Level I centers deploy filtration for pelvic fracture cases where speed outweighs cellular concentration precision. Lower capital cost and disposable simplicity expand addressable market into mid-volume surgical settings.
- Reservoir Management:Collection and temporary storage systems without active wash capability, serving as adjuncts to primary processing technologies.
- Infusion Pump:Controlled reinfusion delivery mechanisms integrated into broader auto-transfusion workflows or standalone cell salvage support.
Clinical validation concentrates in Centrifugation; Filtration is climbing the fastest as orthopedic applications multiply.
Application:
Procedure-specific bleeding patterns dictate system specification, with cardiopulmonary bypass creating predictable high-volume recovery opportunities.
- Cardiac Surgery:Coronary artery bypass grafting, valve replacement, and aortic procedures generating 1000-3000 mL recoverable blood loss per case. United States academic medical centers mandate auto-transfusion availability for all on-pump procedures to conserve banked blood inventory. Reimbment stability and procedural standardization sustain predictable equipment refresh cycles.
- Orthopedic Surgery:Revision arthroplasty, spinal fusion, and pelvic trauma with tourniquet-release bleeding profiles. German trauma networks deploy portable recovery systems for complex fracture fixation in hybrid operating rooms. Prolonged surgical duration and substantial intraoperative loss create reinfusion economics favorable to system adoption.
- Trauma Surgery:Emergency laparotomy and thoracotomy with uncontrolled hemorrhage requiring rapid volume resuscitation.
- Transplant Surgery:Liver and lung transplantation with massive transfusion protocol integration and coagulopathy management complexity.
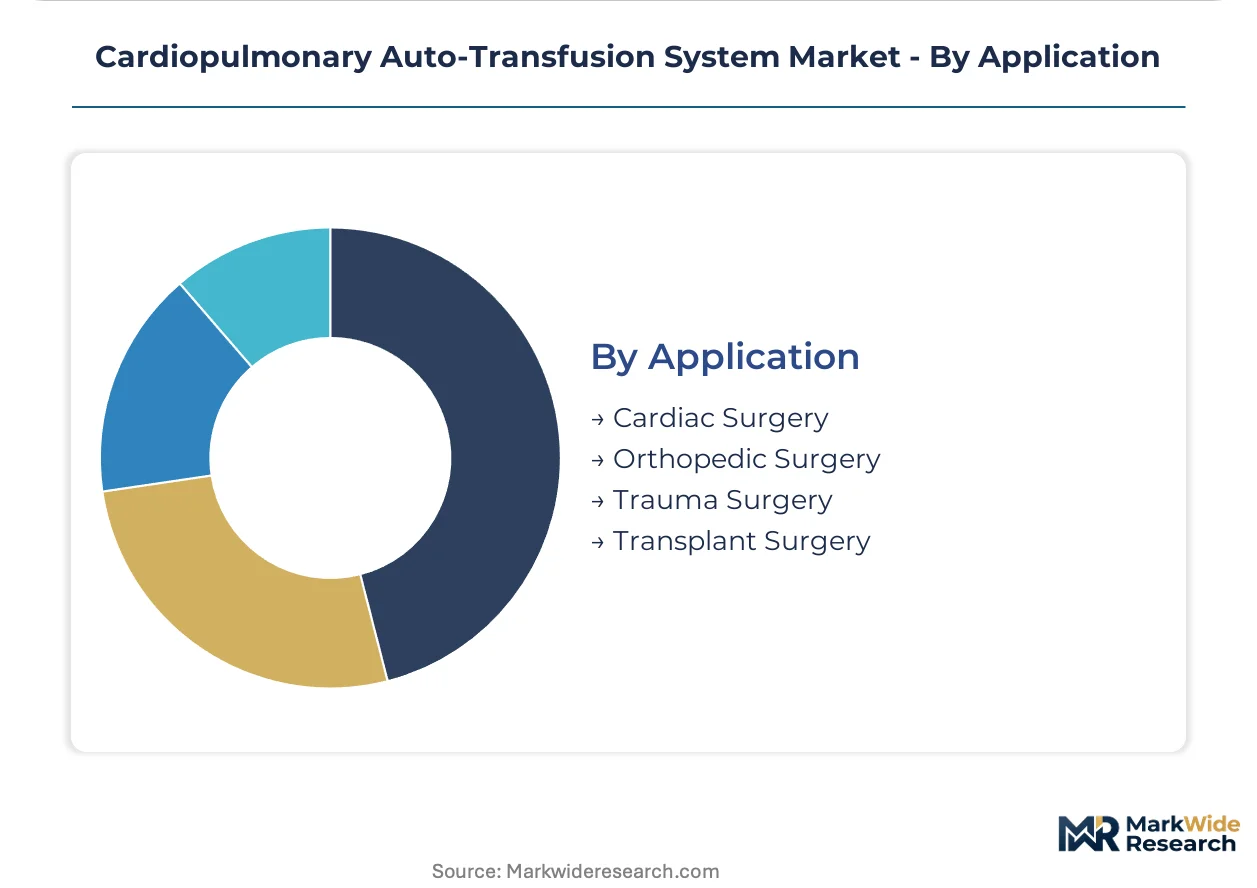
Installed base concentrates in Cardiac Surgery; Orthopedic Surgery represents the steepest expansion trajectory as joint replacement volumes grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgery volume concentration in the United States, Germany, and Japan generates the bulk of installed-base demand, with regulatory frameworks in each jurisdiction dictating procurement timelines and compliance costs for device manufacturers.
United States
Tertiary cardiac centers in Cleveland and Houston drive replacement demand for automated centrifugal wash systems as perfusionist staffing costs climb. FDA's 510(k) predicate device pathway accelerates hospital procurement cycles for closed-system hardware. The Texas Medical Center cluster anchors national utilization benchmarking for intraoperative blood recovery protocols.
Germany
University hospitals in Munich and Berlin deploy automated platforms to standardize wash protocols across high-volume surgical suites. EMA's Medical Device Regulation consolidates notified body capacity, creating submission bottlenecks for mid-tier manufacturers seeking CE marking. The Baden-Württemberg medical technology corridor concentrates European R&D for extracorporeal circuit innovations.
Japan
Tokyo and Osaka metropolitan hospital networks adopt compact filtration systems for aging surgical populations requiring blood conservation. PMDA's accelerated review pathway for blood conservation devices compresses regulatory timelines for qualified submissions. The Kanto region's integrated delivery networks bundle auto-transfusion into value-based cardiac care contracts.
United Kingdom
NHS England's blood bank inventory reduction programs incentivize perioperative blood management investments in London and Manchester cardiac units. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment complexity for new market entrants. The Oxford-Cambridge arc hosts clinical validation trials for next-generation sensor-integrated recovery platforms.
France
Public hospital tenders in Paris and Lyon incorporate sustainability-linked procurement preferences for blood conservation technologies under EU Green Deal alignment. ANSM's vigilance reporting requirements tighten post-market surveillance obligations for Class III device manufacturers. The Île-de-France region concentrates national cardiac surgery volume and associated equipment procurement authority.
Cardiopulmonary Auto-Transfusion System Market Vendor Landscape
United States producers anchor one tier; European specialists hold regulatory compliance advantages in CE-marked segments. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with transfusion service channel control, cardiac surgery equipment specialists with integrated perfusion portfolios, and regional manufacturers competing on capital cost. M&A activity concentrates on perioperative blood management service capabilities, while technology licensing agreements accelerate automated wash protocol standardization.
Among diversified medical technology conglomerates, Haemonetics Corporation and Fresenius SE & Co. KGaA exemplify the transfusion service channel dominance archetype, leveraging integrated plasma collection and hospital dialysis infrastructure to extend reach into perioperative blood management. LivaNova PLC occupies a position within the cardiac surgery specialization tier, anchoring competitive differentiation through dedicated extracorporeal equipment ecosystems. These three entities represent distinct strategic postures: channel breadth versus surgical workflow integration versus segment focus.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| LivaNova PLC |
| Medtronic |
| Fresenius SE & Co. KGaA |
| Zimmer Biomet |
| BD |
| Teleflex Incorporated |
| Braile Biomédica |
| Atrium Medical Corporation |
| Others |
Supply Flow & Price Mechanics
Captive production of centrifugal wash bowls and sterile tubing sets in Germany and the United States anchors pricing power for tier-one manufacturers while locking mid-tier competitors into higher component sourcing costs. This vertical integration into precision-molded polymers and sensor arrays concentrates margin capture with incumbents who control both FDA-validated device platforms and recurring consumable revenue streams.
Pricing Analysis
High-volume automated systems trade margin for installed-base lock-in while premium closed-system configurations sustain pricing premiums through Joint Commission compliance bundling. Price differentiation rests on FDA 510(k) predicate validation depth and perfusionist training certification tiers. Cost compression in semi-automated segments intensifies as German university hospitals consolidate procurement through group purchasing organizations. Surgical centers exhibit highest price sensitivity due to capital constraints and shorter equipment depreciation cycles.
Supply Chain Analysis
CE marking under EU MDR and FDA 510(k) clearance serve as dual qualification gates that filter supplier eligibility to a concentrated tier of polymer processors and sensor integrators. Component manufacturing clusters in Germany, Switzerland, and Japan feed final assembly operations tethered to major hospital supply chains. Single-source vulnerability concentrates in precision hematocrit sensor modules sourced from Swiss specialty manufacturers. Distribution runs through integrated delivery networks in the United States and university hospital procurement consortia in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory validation burdens are compressing viable competitor counts, positioning this market as a consolidation play where MDR compliance infrastructure and FDA predicate libraries determine survival.
For Market Incumbents: Acquire perioperative blood management service capabilities to deepen hospital relationship stickiness beyond equipment sales. Haemonetics and LivaNova should expand per-procedure contracting footprints in United States integrated delivery networks before emerging filtration-based entrants gain orthopedic trauma share. Locking perfusionist training certification pathways defends against software-as-medical-device challengers. For New Entrants and Emerging Players: The mid-tier pricing gap between premium centrifugal systems and economy filtration platforms opens penetration pathways in Japan's metropolitan surgical centers and German trauma networks. Target compact filtration configurations for same-day joint replacement protocols where speed outweighs cellular concentration precision. Pursue private-label partnerships with regional distributors lacking MDR compliance infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medtech conglomerates seeking transfusion service channel control. Long-term viability favors vendors with established PMCF study infrastructure and predicate device libraries spanning multiple regulatory jurisdictions. Watch FDA software-as-medical-device reclassification guidance as the inflection signal for valuation compression in algorithm-dependent platform developers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance infrastructure determines European market access timelines for mid-tier manufacturers. |
| Hospital System Partnership | Per-procedure service contracts with Cleveland Clinic and Texas Medical Center anchor utilization benchmarking. |
| Software Companion Development | Real-time hematocrit monitoring algorithms trigger additional FDA validation burdens under evolving guidance. |
| Reimbursement Strategy | DRG bundling in United States cardiac surgery constrains capital equipment sales toward consumable-based models. |
| FDA Submission | 510(k) predicate device recognition accelerates procurement cycles for closed-system hardware configurations. |
Methodological Framework
Independent corroboration across perfusionist interviews, hospital purchasing committee discussions, and GPO contracts analysis underwrites the qualitative findings in this study. Primary fieldwork engaged cardiac surgery directors, biomedical engineering leads, and transfusion service managers at tertiary centers in the United States, Germany, and Japan. Secondary validation drew from FDA 510(k) databases, EMA MDR technical documentation filings, and hospital procurement records. Bottom-up demand modeling triangulated against top-down manufacturer revenue segmentation.
Comparable-period anchoring to historical cardiac surgery volume trends and orthopedic procedure growth patterns established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product type automation level, end-user facility scale, wash technology methodology, and application-specific bleeding profiles. CAGRs derived from fitted growth curves applied to installed-base replacement cycles and greenfield adoption rates in emerging surgical center networks. Perfusionist workforce scarcity and DRG reimbursement stability served as key demand-side inputs.
Underlying measurement precision varies by segment; cardiac surgery applications carry tighter precision than orthopedic trauma given procedural standardization and documented reinfusion volumes. Forecasts reflect assumptions about regulatory pathway stability and predicate device availability that material shifts in FDA software guidance or MDR notified body capacity would revise. A model refresh is warranted upon material change in perfusionist training pipeline output or allogeneic blood unit pricing volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Cardiac Ultrasound Systems Market