
 Global PC-Based Audiometer Market | 2026-2036
Global PC-Based Audiometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global PC-Based Audiometer Market Foresight
Software-defined signal processing is reshaping how PC-based audiometers deliver calibrated tone and speech stimuli through standard computing hardware. Grason-Stadler leverages decades of transducer engineering to sustain precision in bone conduction testing modules. Intelligent Hearing Systems anchors its position in research-intensive settings with flexible stimulus protocols. Natus Medical Incorporated competes through broad distribution across hospital audiology departments.
A PC-based audiometer is a software-controlled diagnostic instrument that generates precise pure-tone and speech stimuli at calibrated intensity levels, routing signals through standard or specialized transducers to measure hearing thresholds. The device automates threshold-seeking algorithms, stores patient data in structured databases, and integrates with electronic health record systems for clinical workflow efficiency. Diagnostic audiometers command the largest installed base in hospital ENT departments, while portable audiometers represent the fastest-expanding category as occupational health programs decentralize testing to factory floors and remote community sites. Screening audiometers serve high-volume school and workplace programs where throughput priority limits test depth.
The FDA oversees diagnostic audiometer software as Class II medical devices under 510(k) premarket notification pathways, requiring clinical validation of automated threshold algorithms. The EU Medical Device Regulation mandates notified body conformity assessment for PC-based systems with patient-data connectivity, extending compliance burdens to software update cycles. Clinics and audiology centers must monitor how calibration traceability standards from ISO 60601-1 and regional metrology institutes evolve for software-controlled devices. Stakeholders should evaluate whether their quality management systems can absorb more frequent regulatory audits as algorithm-driven diagnostics attract closer scrutiny.
Market Dynamics
Software-defined calibration protocols are compressing hardware refresh cycles while forcing manufacturers to maintain dual competency in acoustic engineering and cybersecurity architecture.
Growth Catalysts
- EU MDR software validation mandates:Stricter conformity assessment for patient-data connectivity creates upgrade demand among legacy-installed ENT clinics across Germany and France.
- Tele-audiology infrastructure:Remote diagnostic reimbursement codes in the United States are pulling cloud-integrated platforms into rural health networks.
- Ototoxicity monitoring protocols:Oncology centers are embedding automated high-frequency testing into chemotherapy patient management workflows.
Market Restraints
- Transducer supply concentration:Precision bone conduction oscillator fabrication concentrates among three German and Japanese component specialists.
- ISO 60601-1 third-edition compliance costs:Calibration traceability documentation requirements inflate quality management system overhead for mid-tier manufacturers.
- Tablet-based screening substitutes:Lower-cost mobile health applications capture school and workplace screening volume outside clinical diagnostic standards.
Strategic Opportunities
- Occupational health decentralization:Factory-floor testing stations in Mexico and Vietnam bypass hospital infrastructure constraints.
- FDA breakthrough device designation pathway:AI-assisted threshold prediction algorithms qualify for expedited review and differentiated reimbursement positioning.
- Hearing aid retail vertical integration:Costco and Amplifon are acquiring diagnostic capabilities to close loop from test to fitting.
Industry Challenges
- Embedded firmware cybersecurity certification:FDA premarket submission now requires SBOM documentation and penetration testing protocols unfamiliar to acoustic engineering teams.
- Interoperability with proprietary EHR architectures:Epic and Cerner custom integration demands consume six-to-nine month implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PC-Based Audiometer Market |
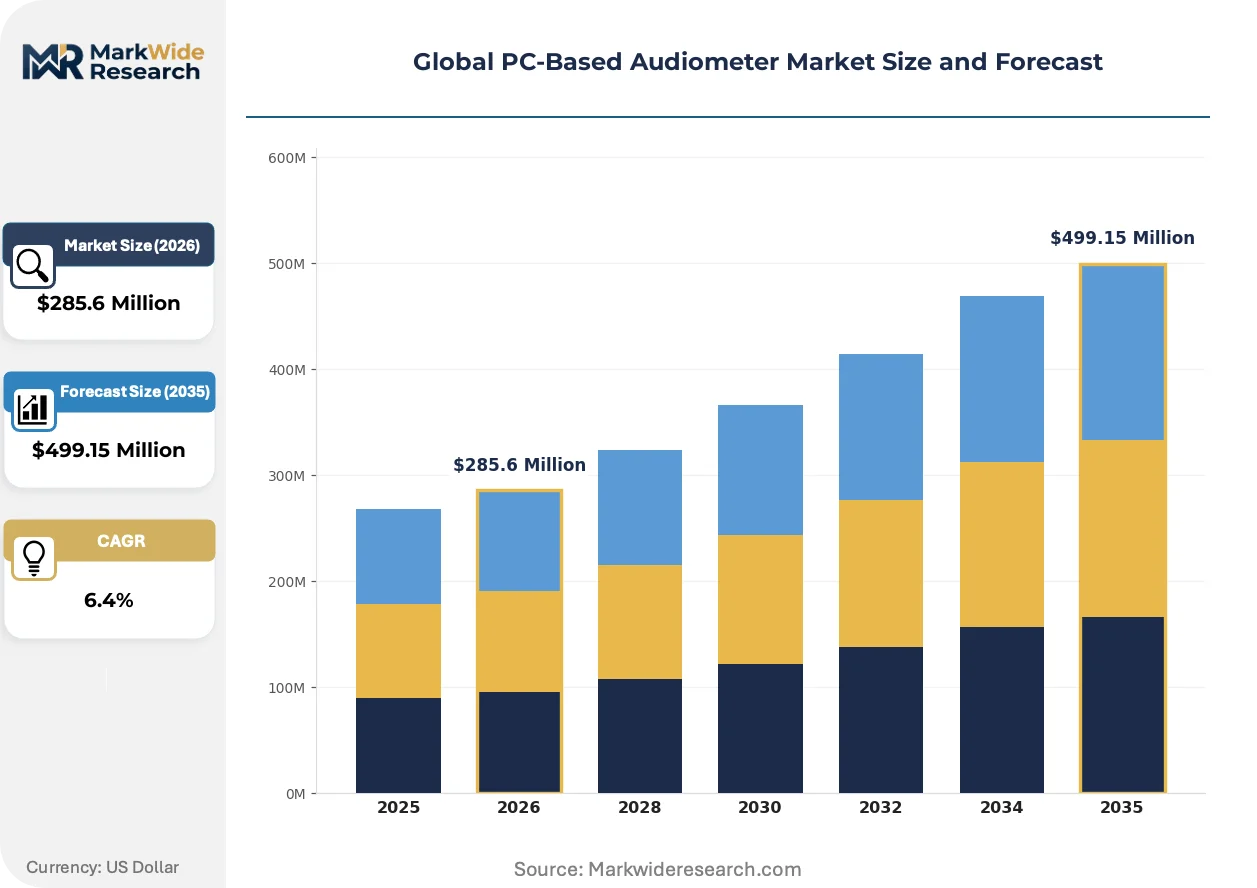
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $499.15 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Audiometers, Screening Audiometers, Portable Audiometers, Clinical Audiometers Technology: Bone Conduction, Air Conduction, Sound Level Calibration, Speech Audiometry, Automated Audiometry Application: Hearing Screening, Hearing Diagnostics, Occupational Health, Educational Institutions, Research Labs End User: ENT Clinics, Audiology Centers, Rehabilitation Facilities, Hearing Aid Dispensers |
| Companies Covered | Interacoustics, MAICO Diagnostics GmbH, Grason-Stadler, Otometrics, GN Store Nord, William Demant Holding Group, Intelligent Hearing Systems, Starkey Hearing Technologies, Natus Medical Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PC-Based Audiometer Market Shifts & Advancements
Signal processing architectures are collapsing the distinction between clinical-grade and portable form factors, enabling single-platform strategies that span hospital, retail, and industrial deployment contexts.
Machine learning inference at the edge is hybridizing traditional threshold-seeking algorithms with patient-response prediction models. Large audiology center chains in Texas and California are piloting these hybrid workflows to compress test duration without sacrificing diagnostic validity. The technology is hybridizing hardware procurement patterns, as identical computing cores serve both fixed diagnostic suites and mobile screening units through software configuration.
EU AI Act risk classification rules are extending conformity obligations to diagnostic algorithms that automate threshold interpretation. Notified bodies in Germany and the Netherlands are developing specialized assessment frameworks for machine-learning-enabled audiometers. Research-intensive university hospitals are front-loading validation studies to secure CE marking ahead of smaller competitors.
Subscription-based calibration and software maintenance contracts are displacing perpetual license models in hospital procurement. Audiology departments in the United Kingdom and Australia are unbundling hardware acquisition from ongoing validation services, compressing upfront capital requirements while extending vendor relationship duration. This shift is most visible in National Health Service trusts where capital budget constraints meet pressure to modernize aging installed bases.
Global PC-Based Audiometer Market Segmentation
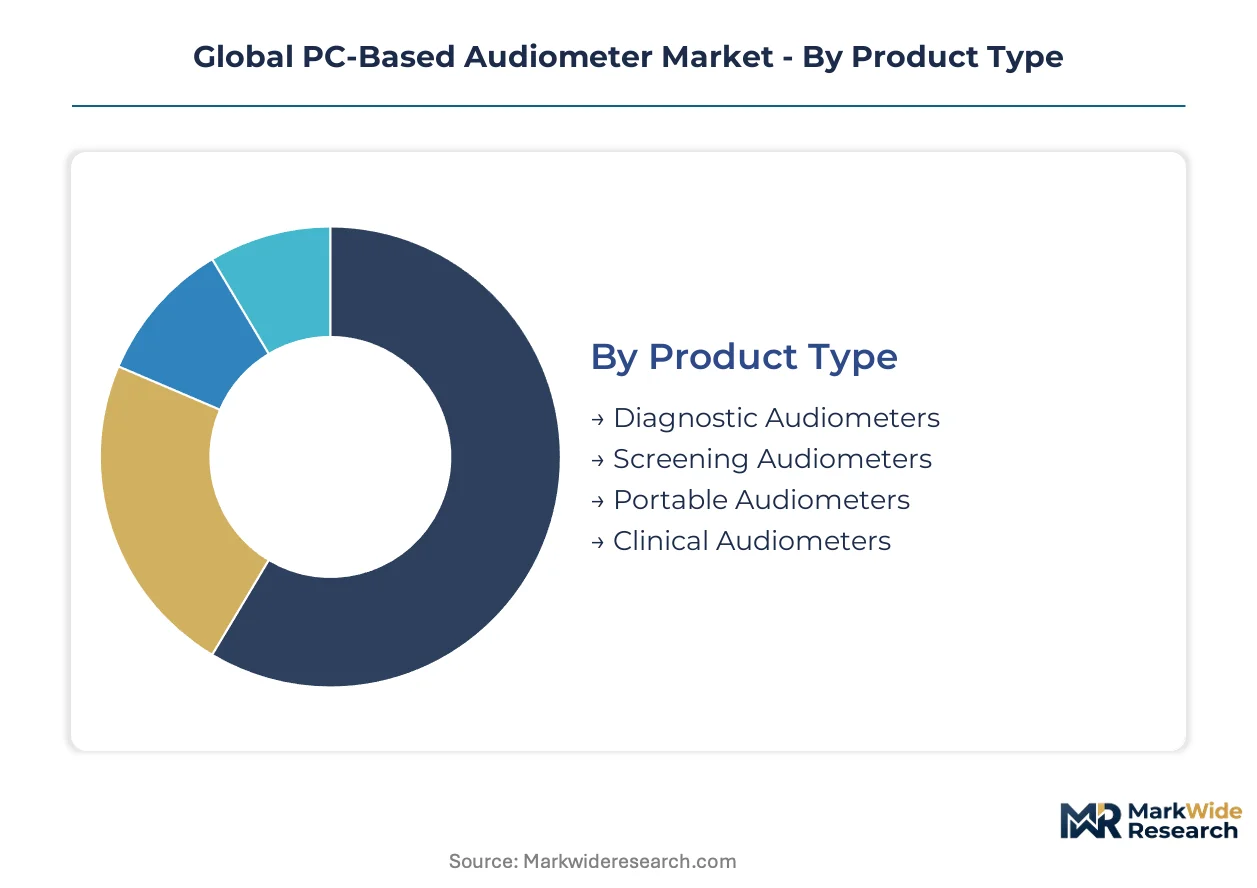
PC-based audiometer segmentation reveals how software-defined architectures compress multiple clinical functions into modular hardware platforms. Manufacturers configure identical computing cores across diagnostic, screening, and portable deployments through firmware licensing rather than physical redesign.
Product Type:
Use-case spectrum spans fixed clinical installations to factory-floor mobility, with software licensing determining functional depth rather than hardware differentiation.
- Diagnostic Audiometers:Full-spectrum pure-tone and speech testing with automated threshold-seeking algorithms and structured database integration. Hospital ENT departments in Germany and the United States concentrate procurement here, driven by EU MDR software validation mandates requiring documented algorithm traceability.
- Portable Audiometers:Battery-powered units with calibrated transducers and cloud-sync capability for off-site deployment. Occupational health programs in Mexico and Vietnam favor this category as manufacturing hubs decentralize hearing conservation beyond hospital infrastructure.
- Screening Audiometers:Simplified pass-fail protocols optimized for high-throughput school and workplace programs.
- Clinical Audiometers:Fixed-installation systems with specialized transducer arrays for comprehensive auditory evaluation.
Established volume favors Diagnostic Audiometers; emerging adoption favors Portable Audiometers.
Technology:
Signal pathway specialization determines calibration complexity and regulatory scrutiny intensity across deployment contexts.
- Automated Audiometry:Algorithm-driven threshold detection with machine learning inference at the edge. Large audiology center chains in Texas and California pilot these hybrid workflows to compress test duration without sacrificing diagnostic validity.
- Bone Conduction:Skull-vibration stimulus delivery bypassing outer and middle ear structures for sensorineural assessment. Precision oscillator fabrication concentrates among German and Japanese component specialists, creating supply vulnerability.
- Air Conduction:Standard headphone-delivered pure-tone testing across frequency and intensity ranges.
- Speech Audiometry:Calibrated word and sentence recognition testing with norm-referenced scoring.
- Sound Level Calibration:Continuous monitoring and self-adjustment protocols maintaining ISO 60601-1 traceability.
Regulatory complexity clusters around Automated Audiometry; supply constraints concentrate in Bone Conduction.
Application:
Reimbursement coding and regulatory classification split volume between clinical diagnostic depth and screening throughput priorities.
- Hearing Diagnostics:Comprehensive threshold profiling with medical-grade documentation for treatment planning. ENT clinics across France and the United Kingdom anchor demand here, compelled by tightening conformity assessment for patient-data connectivity under EU MDR.
- Occupational Health:Regulatory-mandated baseline and periodic testing for noise-exposed workers. Factory-floor stations in Vietnam and Mexico expand fastest as multinational manufacturers internalize compliance.
- Hearing Screening:Rapid triage protocols for pediatric and adult population surveillance.
- Educational Institutions:School-based identification programs with simplified logistics and lower per-test cost.
- Research Labs:Flexible stimulus protocols supporting experimental paradigms beyond clinical standards.
Reimbursement stability favors Hearing Diagnostics; volume expansion favors Occupational Health.
End User:
Procurement consolidation among large chains versus fragmented independent practice shapes pricing and service bundling strategies.
- Audiology Centers:Dedicated hearing healthcare facilities with high test volume and multi-manufacturer equipment portfolios. Chains in the United States consolidate procurement, pulling cloud-integrated platforms into rural networks through remote diagnostic reimbursement codes.
- ENT Clinics:Otolaryngology practices integrating audiological evaluation with surgical and medical management. German clinics expand automated platform adoption fastest under EU MDR upgrade pressure.
- Hearing Aid Dispensers:Retail-focused operations closing loop from test to fitting, with Costco and Amplifon acquiring diagnostic capabilities.
- Rehabilitation Facilities:Post-intervention monitoring and cochlear implant programming services.
Scale economies favor Audiology Centers; vertical integration momentum favors Hearing Aid Dispensers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in the United States, Germany, and Japan concentrate volume for diagnostic-grade systems, while occupational health managers in Vietnam and Mexico drive portable unit expansion. Regulatory divergence between FDA 510(k) pathways and EU MDR conformity assessment shapes vendor prioritization. Cloud-integrated platforms penetrate rural networks where reimbursement codes now cover remote diagnostic delivery.
United States
Large audiology center chains in Texas and California consolidate equipment procurement, pulling identical computing cores into fixed diagnostic suites and mobile screening units. FDA Class II oversight of diagnostic audiometer software under 510(k) premarket notification mandates clinical validation of automated threshold algorithms. The Pacific Northwest hosts pilot programs for hybrid machine-learning workflows that compress test duration.
Germany
ENT clinics across Bavaria and North Rhine-Westphalia expand automated audiometry platform adoption fastest under EU MDR software validation pressure. The EU Medical Device Regulation mandates notified body conformity assessment for systems with patient-data connectivity, extending compliance burdens to software update cycles. Precision bone conduction oscillator fabrication concentrates in Baden-Württemberg component specialists.
Japan
Research-intensive university hospitals in Tokyo and Osaka front-load validation studies for machine-learning-enabled audiometers to secure CE marking ahead of smaller competitors. METI standards intersect with ISO 60601-1 third-edition calibration traceability requirements. The Kansai region anchors demand for flexible stimulus protocols supporting experimental paradigms beyond clinical standards.
Vietnam
Multinational manufacturers internalize hearing conservation compliance through factory-floor testing stations in Ho Chi Minh City and Binh Duong province. Occupational health decentralization bypasses hospital infrastructure constraints entirely. Northern industrial zones in Hai Phong and Bac Ninh expand fastest as electronics and textile exporters face customer-mandated worker safety audits.
Mexico
Automotive and aerospace suppliers in Nuevo León and Baja California deploy battery-powered portable units with cloud-sync capability for off-site worker screening. OSHA-aligned baseline and periodic testing protocols drive procurement even without equivalent domestic regulatory mandate. The Bajío region's medical device manufacturing clusters absorb calibration service contracts from United States-based vendors.
Global PC-Based Audiometer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The vendor base compresses around manufacturers maintaining dual competency in acoustic engineering and cybersecurity architecture, while mid-tier competitors absorb inflated quality management system overhead. Strategic archetypes include transducer-integrated system houses, software-defined platform vendors, and research-protocol specialists. Dominant competitive moves encompass subscription-based calibration contract unbundling and hearing aid retail vertical integration from test to fitting.
Within the transducer-engineering tier, Grason-Stadler and MAICO Diagnostics GmbH represent precision bone conduction testing heritage. Intelligent Hearing Systems occupies a position among research-intensive platform vendors with flexible stimulus protocol architecture. Natus Medical Incorporated anchors the hospital distribution archetype across broad audiology department networks. These three exemplify how vendor positioning stratifies between acoustic hardware depth, software configurability, and channel reach density.
| Leading Market Players |
|---|
| Interacoustics |
| MAICO Diagnostics GmbH |
| Grason-Stadler |
| Otometrics |
| GN Store Nord |
| William Demant Holding Group |
| Intelligent Hearing Systems |
| Starkey Hearing Technologies |
| Natus Medical Incorporated |
| Others |
Supply & Pricing Matrix
Single-source dependency on precision bone conduction oscillator fabrication in Baden-Württemberg and Osaka prefecture compresses margin buffers across all pricing tiers while forcing buyers into multi-year calibration service contracts that embed supply security premiums into total cost of ownership.
Pricing Analysis
Cost-plus contracts with raw material indexation to rare earth magnet pricing govern transducer procurement between German component specialists and system integrators. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated diagnostic suites from CE-marked clinical units and unbundled software licenses for research applications. Pricing pressure stems from subscription-based calibration contracts displacing perpetual licenses in NHS trusts and Australian hospital networks. Occupational health programs in Vietnam and Mexico exhibit highest price sensitivity due to capital budget constraints, while research-intensive university hospitals in Japan and Germany absorb premium tiers for flexible stimulus protocol access.
Supply Chain Analysis
Export-control restrictions on precision piezoelectric materials under Japanese METI and German BAFA dual-use frameworks limit oscillator technology transfer to third-country manufacturers. Component fabrication concentrates in Germany, Japan, and South Korea, with final assembly and software integration distributed across the United States, Denmark, and China. Supply chains draw from rare earth processing facilities in Inner Mongolia and Malaysian separation plants, creating tariff exposure through US-China trade friction. Distribution runs through audiology equipment distributors with GPO contracts in hospital systems and direct OEM relationships with hearing aid retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defense where EU MDR software validation requirements and FDA 510(k) clinical validation barriers create switching costs that entrench incumbent positions for diagnostic-grade platforms.
For Market Incumbents: Pre-empt margin erosion from tablet-based screening substitutes by unbundling hardware from subscription calibration services that lock hospital audiology departments into recurring revenue streams. Acquire precision transducer engineering capabilities in Baden-Württemberg or Osaka to secure supply continuity against export-control tightening. Fortify cybersecurity architecture teams ahead of FDA SBOM documentation mandates that will disqualify acoustic-engineering-only competitors from Class II submissions. For New Entrants and Emerging Players: Mid-tier occupational health programs in Mexico and Vietnam represent the most penetrable entry point, where factory-floor testing stations bypass hospital procurement complexity and cloud-sync capability substitutes for EHR integration depth. Target research-intensive university hospitals in the Pacific Northwest and Kansai region with flexible stimulus protocol platforms that command premium pricing outside reimbursement-constrained clinical markets. Lead with AI-assisted threshold prediction algorithms that qualify for FDA breakthrough device designation and expedited review timelines. For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape by extending conformity obligations to diagnostic algorithms and inflating compliance costs for machine-learning-enabled platforms. Position for consolidation around vendors maintaining dual competency in acoustic engineering and cybersecurity architecture, as mid-tier competitors absorb quality management system overhead that compresses margins below investable thresholds. Monitor notified body capacity constraints in Germany and the Netherlands as the signal for valuation inflection, as CE marking delays will strand capital in validation pipelines and force distressed exits.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Notified body conformity assessment for patient-data connectivity extends compliance burdens to software update cycles under EU MDR. |
| Hospital System Partnership | GPO contracts with audiology center chains in Texas and California consolidate procurement volume and compress vendor margins. |
| Software Companion Development | Cloud-integrated platforms with remote diagnostic reimbursement codes penetrate rural health networks beyond hospital infrastructure. |
| Reimbursement Strategy | FDA breakthrough device designation for AI-assisted threshold prediction algorithms unlocks expedited review and differentiated positioning. |
| Backward Integration | Acquisition of precision bone conduction oscillator fabrication in Baden-Württemberg secures supply against German-Japanese component concentration. |
Research Methodology
A standing panel of hospital audiology department heads, ENT clinic procurement officers, occupational health program managers, and biomedical engineering directors provided ongoing calibration against secondary validation from FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, ISO 60601-1 third-edition calibration traceability documentation, and hospital GPO contract databases. Bottom-up demand modeling across diagnostic, portable, and screening product types triangulated with top-down market sizing through equipment manufacturer revenue disclosures and audiology center chain capital expenditure patterns.
Scenario-bracketing around regulatory implementation timelines and tele-audiology reimbursement code expansion shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type, signal pathway technology, application context, and end-user procurement archetype. CAGRs derived from installed base replacement cycles, software-defined calibration protocol adoption curves, and occupational health decentralization rates in manufacturing export zones.
Practitioners should monitor notified body capacity utilization rates in Germany and the Netherlands, FDA cybersecurity guidance document finalization, and rare earth magnet price volatility for early signals of forecast deviation. Material shifts in EU AI Act diagnostic algorithm classification implementation or US-China trade friction escalation through precision component tariff schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Medical Electrodes Market
Medical Devices
Smart Stairlift Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Smart Syringe Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Italy Contraceptive Devices Market