
 Cyberknife Market | 2026-2036
Cyberknife Market Size, Share, and Industry Trends Forecast 2026-2036
Cyberknife Market Intelligence
The EU Medical Device Regulation is expanding compliance requirements for robotic radiotherapy platforms across European cancer centers. Accuray Incorporated sustains technology leadership through its proprietary robotic arm architecture and real-time tumor tracking systems. Varian Medical Systems dominates linear accelerator integration, while Brainlab AG specializes in software-driven treatment planning workflows for cranial and spinal indications.
CyberKnife systems deliver stereotactic radiosurgery and stereotactic body radiation therapy through a robotic manipulator mounting a compact linear accelerator, achieving sub-millimeter precision via real-time image guidance and respiratory tracking. The robotic system segment anchors capital expenditure flows, while treatment planning software captures recurring license revenue as clinics upgrade computational algorithms. Cancer centers represent the fastest-growing end-user category as standalone facilities compete with hospital-integrated programs for complex case volumes.
The FDA's 510(k) clearance framework governs US market entry for new CyberKnife configurations, while the EU MDR and CE marking requirements shape European commercialization timelines. Japan's PMDA and METI standards additionally constrain software validation and robotic safety protocols for Asian deployments. Stakeholders must monitor reimbursement parity between robotic radiosurgery and conventional linac treatments as health technology assessment bodies recalibrate value thresholds.
Market Dynamics
Real-time tumor tracking algorithms are compressing treatment margins and forcing capital equipment refresh cycles across tertiary oncology networks. The shift from frame-based to frameless stereotactic delivery is redrawing competitive differentiation among robotic radiosurgery platforms.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined US regulatory route accelerates technology diffusion for robotic surgical configurations. Cancer centers in Texas and California leverage this framework to expand stereotactic body radiation therapy programs.
- Value-Based Reimbursement:CMS bundled payment models reward precision outcomes over treatment volume. Hospital-integrated oncology departments in Florida and New York restructure capital allocation around robotic platforms.
- Respiratory Tracking Algorithms:Synchrony motion management systems enable lung and liver treatments previously excluded from radiosurgery candidacy. Standalone cancer facilities in Arizona compete for complex thoracic case volumes.
Market Restraints
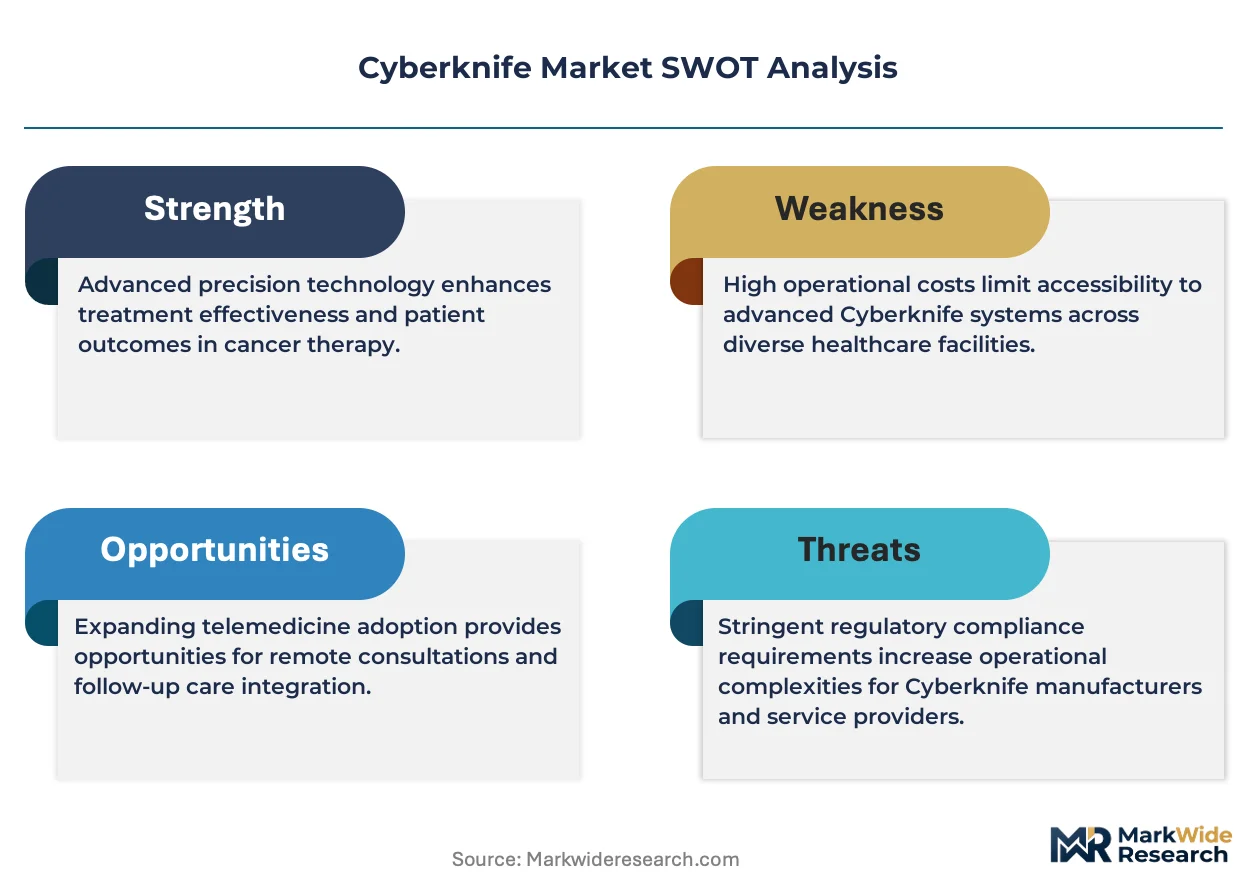
- Cobalt-60 Supply Concentration:Radioisotope production clusters in Ontario and South Africa create vulnerability for gamma knife alternatives. CyberKnife linac architectures avoid this dependency but face tungsten target supply constraints.
- EU MDR Compliance Burden:The expanded Medical Device Regulation elongates European commercialization timelines for software-upgradable treatment planning modules. Notified body capacity bottlenecks in Germany and the Netherlands delay CE marking.
- Conventional Linac Substitution:Volumetric modulated arc therapy on standard linear accelerators encroaches on cranial indications. Community hospitals in Ohio and Illinois defer robotic capital commitments.
Strategic Opportunities
- Indian Tertiary Expansion:The country's national pharmaceutical regulator streamlines medical device registration for radiation therapy platforms. Apollo and Max Healthcare networks in Delhi and Mumbai deploy first robotic radiosurgery units.
- Prostate Focal Therapy Convergence:MRI-ultrasound fusion biopsy workflows integrate with robotic delivery for organ-sparing protocols. Urology-oncology joint ventures in Georgia and North Carolina pilot combined service lines.
- Japan METI Robotics Incentives:The ministry's healthcare robot subsidy program offsets capital acquisition costs for university hospitals. Keio and Tokyo Medical University accelerate stereotactic lung program development.
Industry Challenges
- Medical Physics Talent Scarcity:Board-certified radiosurgery physicist training programs in Illinois and Massachusetts produce insufficient graduates. Treatment planning complexity outpaces workforce pipeline expansion.
- Legacy PACS Integration:Hospital IT infrastructure in Pennsylvania and Michigan requires middleware development for DICOM-RT compatibility. Vendor-neutral archive architectures resist robotic system data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyberknife Market |
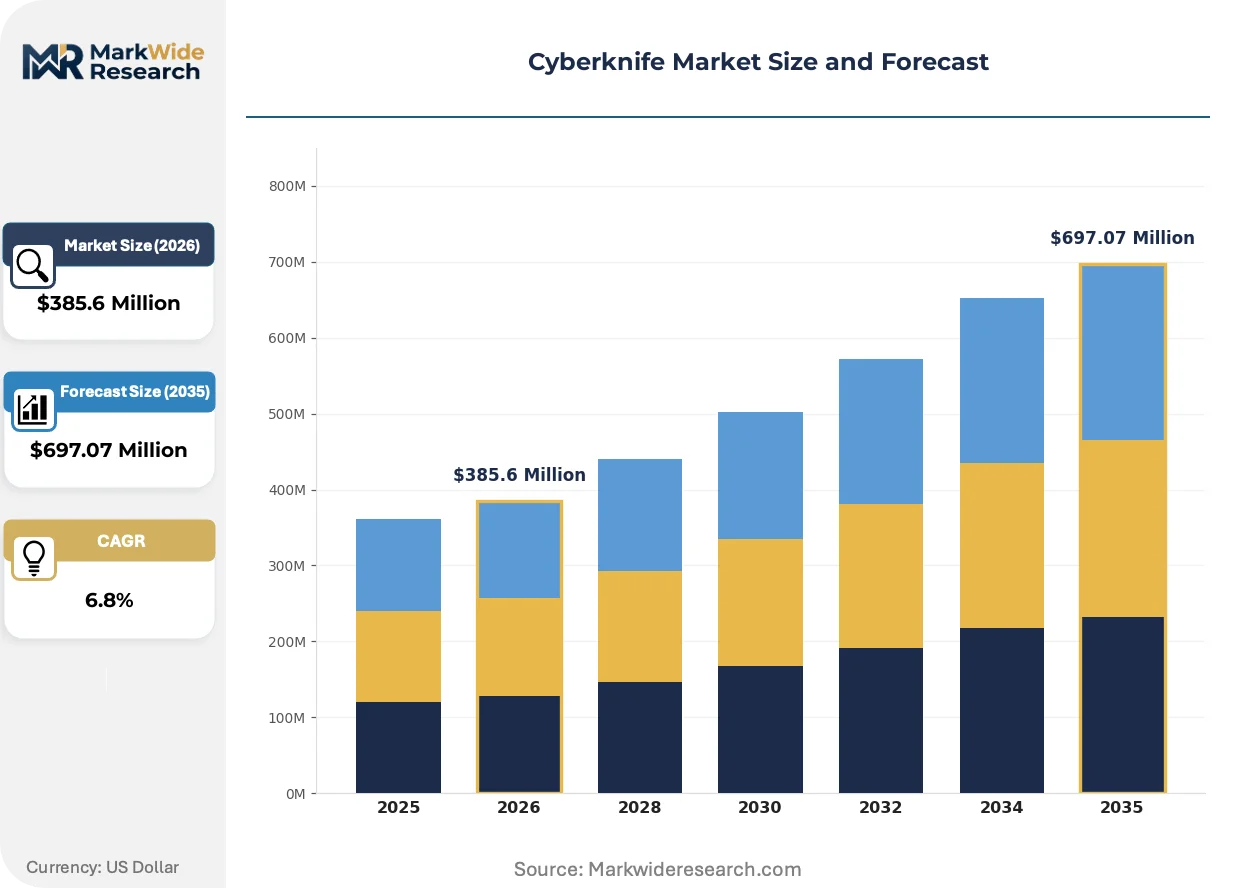
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic System, Treatment Planning Software, Patient Management System, Accessories End User: Hospitals, Clinics, Cancer Centers, Research Institutions Installation Type: Fixed Installation, Mobile Installation, Upgraded Systems, New Installations Service Type: Maintenance Services, Training Services, Technical Support, Consulting Services |
| Companies Covered | Accuray Incorporated, Elekta AB, Varian Medical Systems, Brainlab AG, Siemens Healthineers, ViewRay, GE Healthcare, IBA Group, Mevion Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyberknife Market Strategic Shifts & Innovations
Artificial intelligence inference engines are compressing treatment planning duration from hours to minutes while maintaining dosimetric equivalence. This computational acceleration is redrawing staffing models and patient throughput assumptions across robotic radiosurgery programs.
Multi-leaf collimator-free beam sculpting is rewriting the precision-speed tradeoff in intracranial radiosurgery. The Iris variable aperture collimator enables automated field shaping without mechanical leaf latency. Academic medical centers in Massachusetts and California adopt this architecture for trigeminal neuralgia and vestibular schwannoma protocols. Sub-millimeter conformity indices are compressing the clinical gap between robotic platforms and proton beam alternatives.
Japan's PMDA software as a medical device framework is tightening validation requirements for adaptive replanning algorithms. The regulator demands prospective clinical evidence for AI-generated contour modifications. CyberKnife treatment planning vendors in Tokyo and Osaka extend development timelines to satisfy METI safety documentation standards. Asian commercialization schedules lag US and European counterparts by eight to fourteen months.
Equipment utilization guarantees are displacing traditional capital purchase models in hospital-integrated oncology departments. Third-party managed service organizations in Florida and Texas assume technical performance risk for beam-on-time metrics. Per-fraction pricing structures align vendor incentives with patient volume growth. This arrangement concentrates among cancer centers with annual stereotactic case loads exceeding four hundred procedures.
Cyberknife Market Segmentation
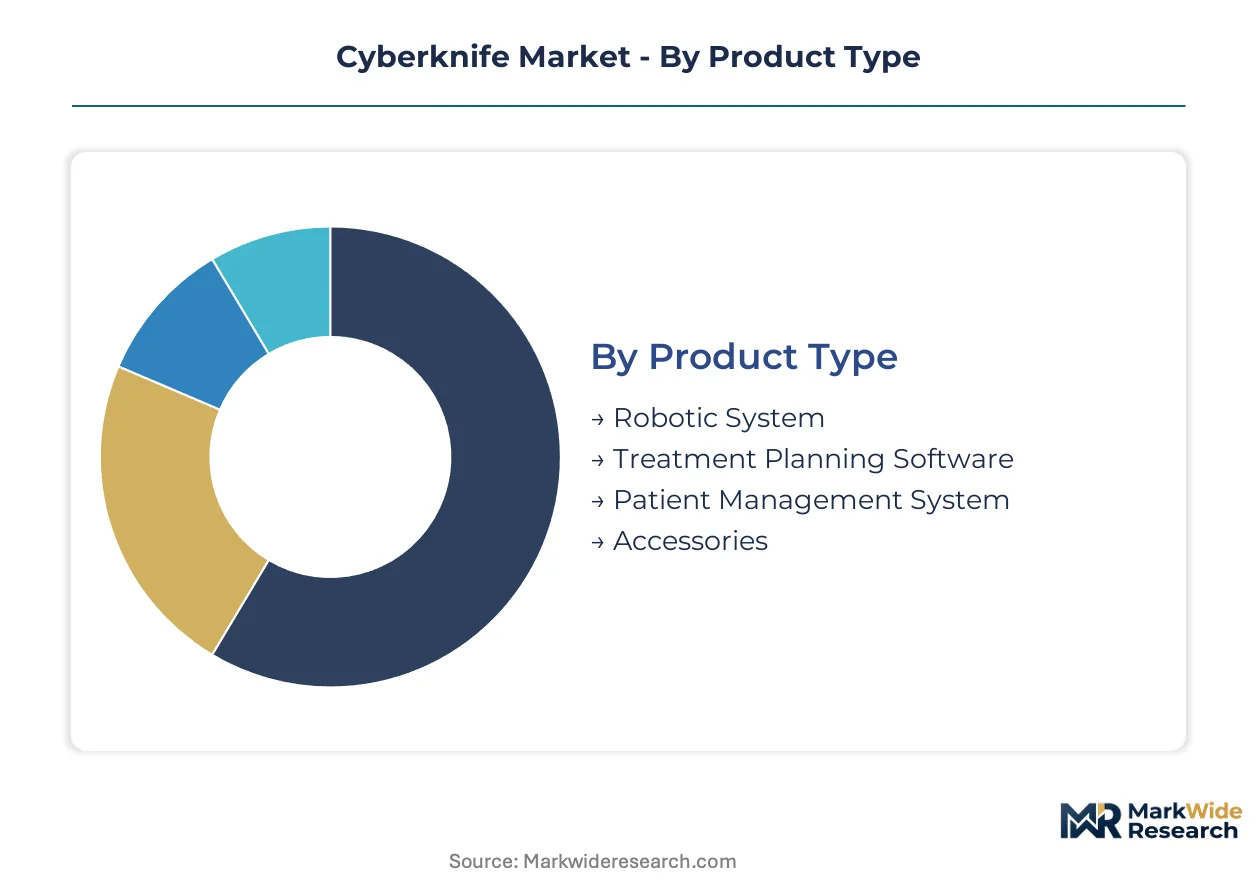
Capital allocation patterns across CyberKnife deployments diverge sharply by segment, with hardware procurement cycles spanning seven to ten years while software generates recurring license streams. Understanding these structural differences enables vendors to calibrate pricing models and service bundling strategies.
Product Type:
Capital intensity peaks in hardware segments requiring radiation-shielded vault construction and robotic arm precision engineering, while software modules demand minimal physical infrastructure.
- Robotic System:The robotic manipulator mounting a compact linear accelerator achieves sub-millimeter targeting precision through real-time image guidance and respiratory tracking. Demand concentrates in tertiary oncology hubs across the United States, Germany, and Japan as cancer centers compete for complex cranial and spinal case volumes.
- Treatment Planning Software:Computational algorithms for dose optimization and contour generation capture recurring subscription revenue as clinics upgrade to AI-accelerated planning modules. Academic medical centers in Massachusetts and California drive adoption of adaptive replanning capabilities that compress treatment duration from hours to minutes.
- Patient Management System:Workflow orchestration platforms integrate scheduling, billing, and clinical documentation for high-throughput radiosurgery programs.
- Accessories:Immobilization devices, tracking fiducials, and consumable collimator components complete the treatment delivery ecosystem.
Most installed capacity flows through Robotic System purchases. Expansion is steepest in Treatment Planning Software as artificial intelligence inference engines reshape staffing models.
End User:
Customer archetypes span integrated health systems with centralized procurement authority to standalone facilities competing on subspecialty reputation.
- Hospitals:Hospital-integrated oncology departments in Florida and Texas leverage bundled payment models to justify capital commitments, restructuring allocation around robotic platforms that reward precision outcomes over treatment volume.
- Cancer Centers:Standalone facilities in Arizona and North Carolina compete aggressively for thoracic and prostate case volumes, deploying respiratory tracking systems to expand radiosurgery candidacy. These centers represent the steepest expansion trajectory as they differentiate through subspecialty concentration.
- Clinics:Community-based practices in Ohio and Illinois defer robotic capital commitments while conventional linear accelerators encroach on cranial indications.
- Research Institutions:Academic medical centers in Tokyo and Osaka extend development timelines to satisfy PMDA software validation standards for adaptive algorithms.
Procurement authority concentrates in Hospitals. Volume growth is climbing fastest in Cancer Centers as standalone facilities capture complex case migrations.
Installation Type:
Deployment economics vary dramatically between greenfield construction requiring radiation vault engineering and retrofit upgrades preserving existing shielding infrastructure.
- New Installations:Greenfield deployments in Delhi and Mumbai by Apollo and Max Healthcare networks require complete radiation-shielded vault construction and robotic system commissioning.
- Upgraded Systems:Legacy platform replacements in Pennsylvania and Michigan leverage existing vault infrastructure while integrating Iris variable aperture collimators for automated field shaping.
- Fixed Installation:Permanent robotic arm configurations dominate tertiary oncology networks with predictable case volume profiles.
- Mobile Installation:Transportable systems serve distributed hospital networks seeking equipment utilization guarantees through third-party managed service arrangements.
Deployment volume flows predominantly through New Installations. Upgrade activity is accelerating fastest as first-generation systems reach replacement age.
Service Type:
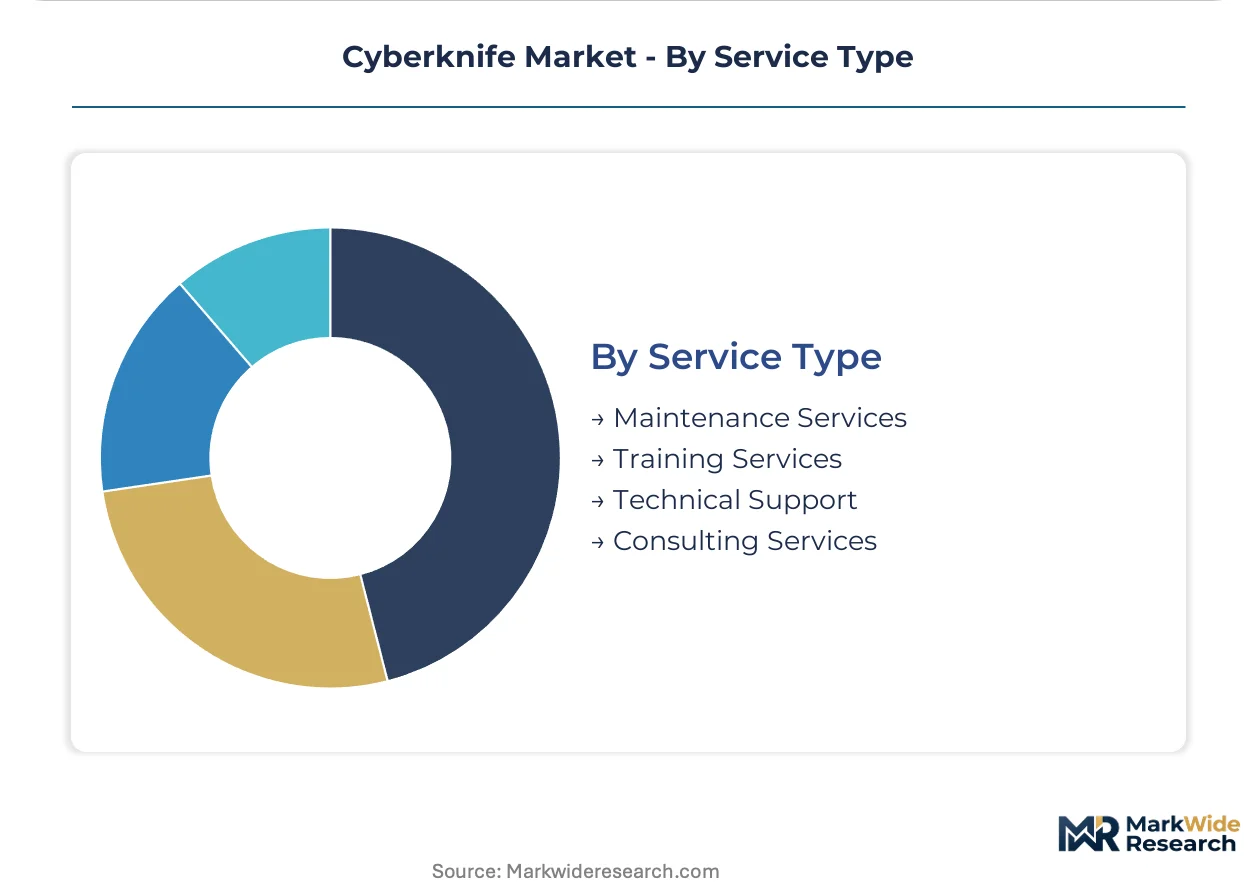
Revenue stability correlates inversely with capital intensity, with technical support and maintenance generating predictable recurring streams against lumpy training and consulting engagements.
- Maintenance Services:Beam-on-time guarantees and preventive maintenance contracts align vendor incentives with equipment reliability metrics in Florida and Texas cancer centers.
- Technical Support:Remote diagnostics and software troubleshooting capabilities compress system downtime for high-throughput programs.
- Training Services:Medical physicist certification programs in Illinois and Massachusetts address workforce pipeline constraints for treatment planning complexity.
- Consulting Services:Workflow optimization and program development advisory supports standalone cancer centers entering robotic radiosurgery.
Contract value concentrates in Maintenance Services. Training Services are expanding most quickly as medical physics talent scarcity intensifies across tertiary networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CyberKnife modality originated at Stanford University in the 1990s, establishing the United States as the foundational market for robotic radiosurgery. Capital deployment now spans tertiary oncology networks across multiple continents as regulatory pathways mature.
United States
Cancer centers in Texas and Florida drive system acquisitions through CMS bundled payment models that reward precision outcomes. The FDA's 510(k) clearance pathway accelerates technology diffusion for robotic surgical configurations. Hospital-integrated oncology departments in New York and California compete for complex cranial and spinal case volumes.
Germany
University hospitals in Munich and Heidelberg anchor European adoption of frameless stereotactic delivery systems. The EU Medical Device Regulation elongates commercialization timelines for software-upgradable treatment planning modules. Notified body capacity bottlenecks in Berlin and Hamburg delay CE marking for next-generation platforms.
Japan
Academic medical centers in Tokyo and Osaka extend development timelines to satisfy PMDA software validation standards. METI's healthcare robot subsidy program offsets capital acquisition costs for university hospitals. Keio and Tokyo Medical University accelerate stereotactic lung program development through government incentives.
India
Apollo and Max Healthcare networks in Delhi and Mumbai deploy first robotic radiosurgery units as tertiary expansion accelerates. The country's national pharmaceutical regulator streamlines medical device registration for radiation therapy platforms. Greenfield installations require complete radiation-shielded vault construction in emerging metropolitan clusters.
United Kingdom
NHS England's specialized commissioning frameworks govern access to stereotactic radiosurgery for cranial indications. The MHRA operates under EU MDR transitional arrangements for legacy device registrations. London teaching hospitals and Manchester cancer centers concentrate robotic program development in academic settings.
Cyberknife Market Key Industry Players
Premium-margin players sit above commodity-margin players across the precision-delivery technology spectrum. The vendor base concentrates around integrated radiation oncology platforms and specialized software workflows. Three strategic archetypes dominate: linac-integrated robotics specialists, treatment planning software vendors, and proton therapy diversifiers. Competitive moves center on regulatory pathway optimization and managed service contracting models that transfer technical performance risk.
Among US-based radiation therapy platform developers, Accuray Incorporated and Varian Medical Systems exemplify contrasting approaches to robotic delivery architecture. Brainlab AG anchors the European software-driven treatment planning segment. These three occupy positions spanning hardware integration, computational workflow optimization, and cranial-spinal indication specialization.
| Leading Market Players |
|---|
| Accuray Incorporated |
| Elekta AB |
| Varian Medical Systems |
| Brainlab AG |
| Siemens Healthineers |
| ViewRay |
| GE Healthcare |
| IBA Group |
| Mevion Medical Systems |
| Others |
Cost & Logistics Intelligence
CMS bundled payment models rewarding precision outcomes over treatment volume are restructuring capital allocation across hospital-integrated oncology departments. This demand-side shift forces supply responses toward outcome-guarantee contracting and per-fraction service models that compress upfront pricing while extending vendor revenue duration.
Pricing Analysis
Equipment utilization guarantees displacing traditional capital purchases dominate pricing architecture across high-throughput cancer centers. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with adaptive replanning modules from community hospitals with basic configurations and mobile service providers with managed equipment arrangements. Pricing pressure stems from volumetric modulated arc therapy on conventional linear accelerators encroaching on cranial indications. Community hospitals in Ohio and Illinois exhibit highest price sensitivity, deferring robotic commitments, while tertiary oncology hubs in Texas and Florida absorb premium tiering for competitive positioning.
Supply Chain Analysis
Regional distribution centers in California and Massachusetts coordinate hub-and-spoke patterns for robotic arm assemblies and linear accelerator components. Manufacturing concentration clusters in the United States, Germany, and Japan for precision robotic manipulators, with tungsten target sourcing drawing from Chinese and Russian mining operations. Single-source vulnerability concentrates in compact linac magnet supply chains governed by export control classifications. Distribution runs through authorized service organizations that assume technical performance risk for beam-on-time metrics in Florida and Texas cancer center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CyberKnife market functions as a regulatory compounder where FDA 510(k) clearance acceleration and EU MDR compliance elongation create divergent competitive timelines that reward pathway optimization expertise.
For Market Incumbents: Anticipate conventional linac substitution threats by embedding Iris variable aperture collimators into upgrade pathways for legacy installations. Defensive consolidation through managed service organization partnerships transfers technical performance risk while capturing recurring revenue streams. Capacity addition in Indian metropolitan clusters leverages streamlined CDSCO registration pathways before local competition intensifies. For New Entrants and Emerging Players: Launch via third-party equipment utilization guarantee models that assume beam-on-time risk for cancer centers exceeding four hundred annual stereotactic procedures. White-space concentration sits with prostate focal therapy convergence opportunities in Georgia and North Carolina urology-oncology joint ventures. Go-to-market positioning targets standalone cancer centers in Arizona competing for thoracic case volumes through respiratory tracking differentiation. For Investors and Strategic Acquirers: Asymmetric upside sits with treatment planning software vendors possessing adaptive replanning algorithms validated under PMDA software as a medical device frameworks. Long-term viability across the projection horizon favors computational workflow specialists over hardware-integrated robotics platforms facing capital expenditure cyclicality. Signal to monitor: reimbursement parity determinations from health technology assessment bodies recalibrating value thresholds between robotic radiosurgery and conventional linac treatments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerated clearance timelines compress competitive entry barriers for next-generation Synchrony motion management configurations. |
| CE Marking Pathway | Notified body capacity bottlenecks in Germany and Netherlands elongate European commercialization for software-upgradable modules. |
| Hospital System Partnership | Florida and Texas cancer centers leverage bundled payment models to justify robotic capital commitments through outcome guarantees. |
| Software Companion Development | AI inference engines for treatment planning compression reshape staffing models across Massachusetts and California academic centers. |
| Reimbursement Strategy | CMS value-based frameworks reward precision outcomes over volume, restructuring procurement authority in hospital-integrated departments. |
Research Approach
Bottom-up cancer center and hospital procurement modeling reconciled against top-down robotic system installation tracking forms the analytical core. Primary interviews with radiation oncology department heads, medical physicists, GPO contracts managers, and biomedical engineers combine with secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body registries. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices map robotic system shipments, treatment planning software licenses, and service contract values against demographic cancer incidence patterns and capital expenditure cycles. Segmentation dimensions span product type, end-user archetype, installation configuration, and service arrangement across the analysis window. CAGRs derive from equipment replacement age distributions and software upgrade adoption curves. Forecast inputs incorporate respiratory tracking algorithm advancement rates and PMDA software validation timeline extensions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement parity disruptions or cobalt-60 supply chain shocks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Inversion Table Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Embolization Plugs Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Medication Management System Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Digital Phoropter Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Medical Coatings Market