
 Centrifugal Blood Pumps Market | 2026-2036
Centrifugal Blood Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Blood Pumps Market Intelligence
China's expanding cardiovascular device manufacturing corridor is reconfiguring regional supply dynamics for precision-machined pump housings and magnetic bearing assemblies. Abbott Laboratories leverages vertically integrated catheter-pump ecosystems to sustain pricing power across integrated delivery networks. Medtronic anchors North American hospital contracting through decades of perfusionist training infrastructure. LivaNova competes in European cardiac surgery centers with specialized centrifugal platforms for minimally invasive procedures.
A centrifugal blood pump is a non-pulsatile mechanical circulatory device that uses an impeller rotating within a volute chamber to generate continuous blood flow, typically operating at 1,500–5,000 RPM with hemolysis indices below 0.05 g/100L. Its primary purpose is to replace or assist native cardiac function during open-heart surgery, extracorporeal membrane oxygenation, or bridge-to-transplant protocols. Implantable pumps command premium positioning due to chronic hemodynamic support applications, while disposable pumps dominate procedural volume in cardiac surgery suites where single-use protocols reduce infection risk. Magnetic levitation technology leads R&D allocation as bearing wear and thrombogenicity constraints drive next-generation platform development.
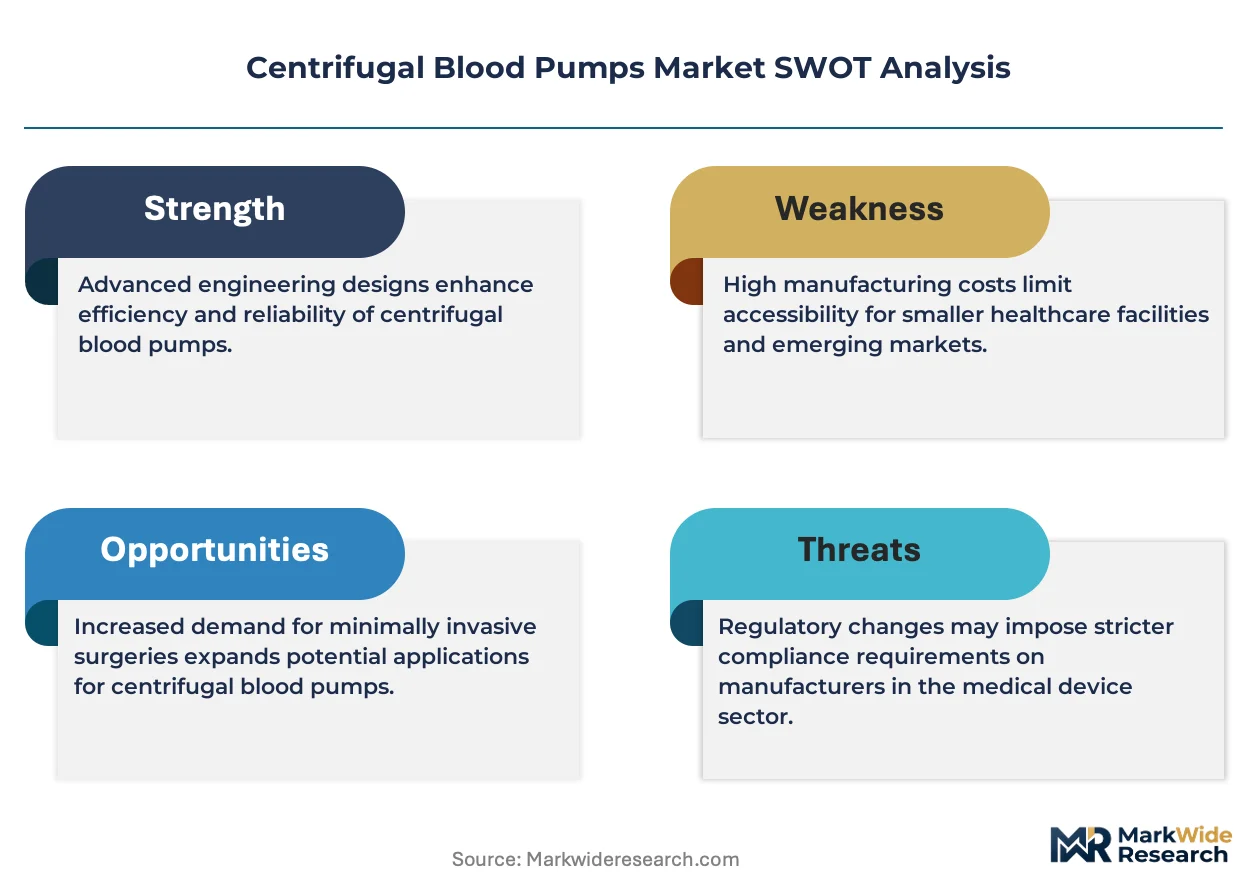
The FDA's premarket approval framework and the EU Medical Device Regulation impose clinical evidence thresholds that extend development timelines and consolidate market access among well-capitalized manufacturers. ISO 14708 active implantable device standards and IEC 60601 electrical safety requirements further shape product design specifications for international commercialization. Stakeholders must monitor evolving CMS technology add-on payment determinations and parallel European DRG refinement for mechanical circulatory support, as reimbursement clarity will determine adoption velocity for next-generation ambulatory pump platforms.
Market Dynamics
Magnetic levitation bearing systems are compressing thrombogenicity failure modes while extending device longevity, forcing incumbent manufacturers to retool core impeller architectures or cede chronic support applications to specialized entrants.
Growth Catalysts
- ECMO Protocol Standardization:Tertiary cardiac surgery suites in the United States are embedding centrifugal pumps into standardized extracorporeal membrane oxygenation workflows, creating procedural pull-through for disposable pump sets.
- CMS Reimbursement Codes:Mechanical circulatory support procedure codes in the United States reimburse hospital systems for bridge-to-transplant interventions, anchoring volume for implantable centrifugal platforms.
- Magnetic Bearing R&D Allocation:Bearing wear elimination through magnetic levitation is redirecting engineering resources toward chronic hemodynamic support applications previously served by pulsatile devices.
Market Restraints
- Titanium Alloy Supply Concentration:Precision-machined pump housings depend on titanium billet suppliers concentrated in China's cardiovascular device manufacturing corridor, exposing cost volatility to regional industrial policy shifts.
- FDA PMA Timeline Friction:Class III cardiovascular device premarket approval pathways extend development cycles to 18-36 months, consolidating market access among manufacturers with capitalized regulatory affairs infrastructure.
- Peristaltic Pump Substitution:Roller pump systems retain cost advantages in short-duration cardiopulmonary bypass procedures, limiting centrifugal penetration in price-sensitive acute surgical settings.
Strategic Opportunities
- Ambulatory Platform White Space:Next-generation wearable centrifugal systems for chronic outpatient support remain underdeveloped, with reimbursement clarity from CMS technology add-on payment determinations pending.
- Minimally Invasive Surgical Convergence:Integration of centrifugal pumps with percutaneous cannulation techniques is opening catheter-based cardiac support procedures in European specialized centers.
- EU MDR Regulatory Tailwind:The European Medical Device Regulation's clinical evidence requirements favor manufacturers with established post-market surveillance infrastructure, creating compliance barriers for new entrants.
Industry Challenges
- Perfusionist Training Pipeline Constraints:Specialized clinical expertise for centrifugal pump operation remains concentrated in legacy academic medical centers, limiting deployment velocity in community hospital settings.
- ISO 14708 Certification Complexity:Active implantable medical device standards require extensive electrical safety and biocompatibility documentation, compressing product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Blood Pumps Market |
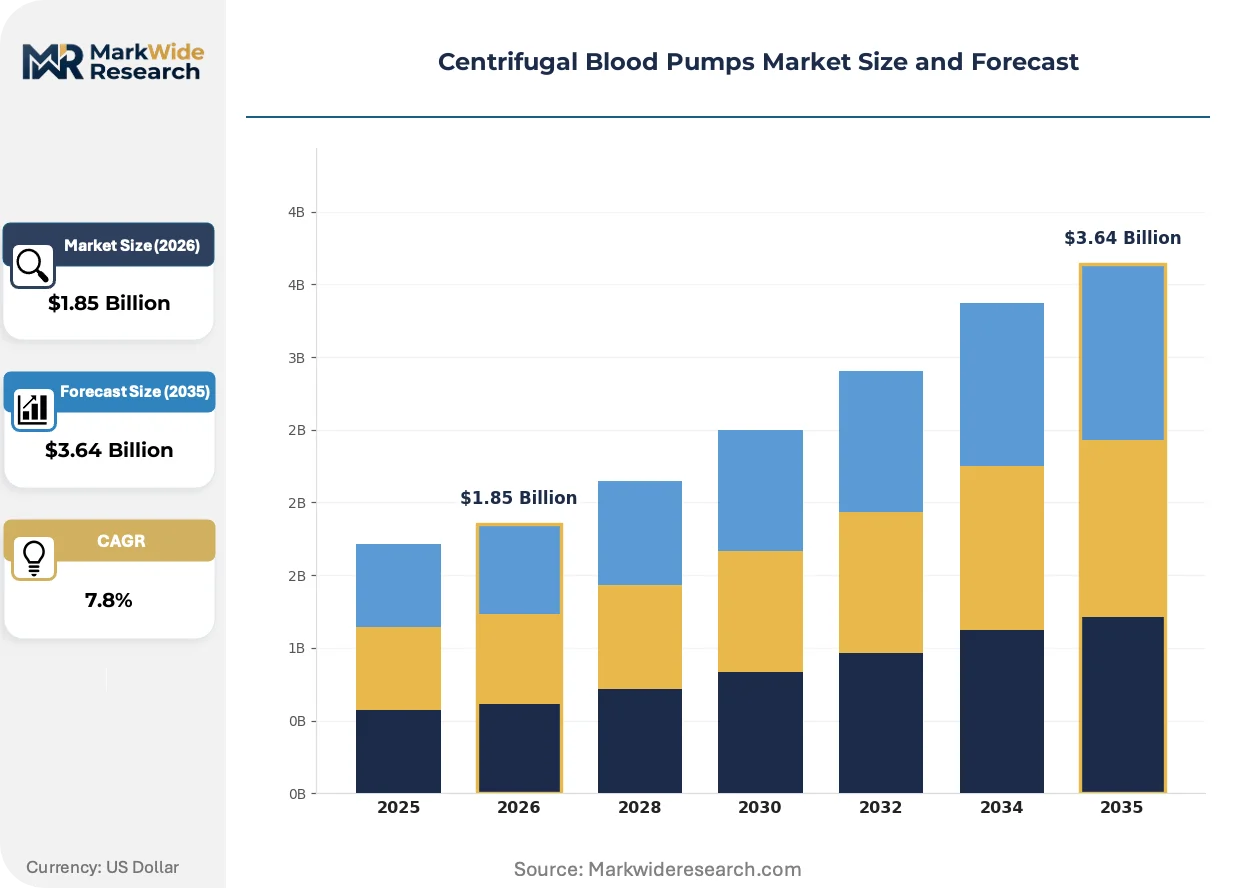
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Pumps, Miniaturized Pumps, Implantable Pumps, Disposable Pumps End User: Hospitals, Surgical Centers, Cardiac Clinics, Research Institutions Application: Cardiac Surgery, Hemodynamic Support, Organ Transplantation, Extracorporeal Circulation Technology: Pneumatic Control, Electrical Control, Magnetic Levitation, Smart Sensing |
| Companies Covered | Abbott Laboratories, Medtronic, LivaNova, Terumo Corporation, Getinge AB, Braile Biomedica, Qura, Baxter International, Procyrion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Blood Pumps Market Strategic Shifts & Innovations
Computational fluid dynamics simulation and additive manufacturing are collapsing prototype-to-validation cycles, while regulatory science advances compress evidence-generation timelines for breakthrough device designations.
Magnetic levitation impeller suspension eliminates mechanical bearing contact, reducing hemolysis indices below threshold levels for chronic support. Pediatric cardiac centers and bridge-to-transplant programs are adopting these platforms for multi-week support durations. Contact-free rotation is rendering obsolete conventional ceramic bearing assemblies in next-generation pump architectures.
The FDA's breakthrough device designation pathway accelerates premarket review for technologies addressing unmet needs in mechanical circulatory support. Manufacturers submitting magnetic levitation platforms receive prioritized review and enhanced FDA engagement. Implantable centrifugal segments with chronic hemodynamic applications are restructuring clinical trial designs to capture real-world evidence under this framework.
Hospital procurement committees are consolidating mechanical circulatory support device purchasing through integrated delivery network contracts. Single-source agreements bundle pumps, disposables, and technical support, displacing fragmented supplier relationships. This concentration is most visible in United States tertiary systems where Abbott and Medtronic anchor multi-year service agreements.
Centrifugal Blood Pumps Market Segmentation
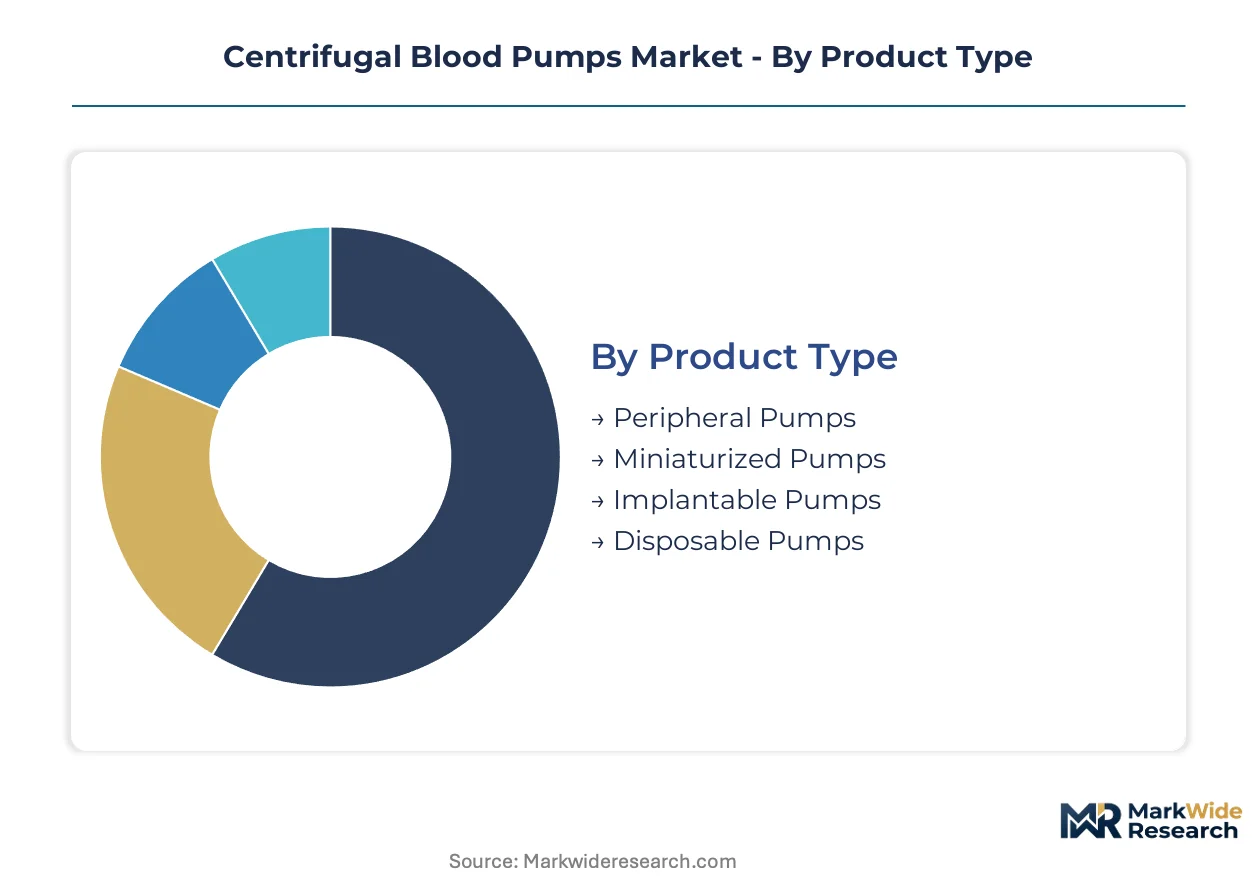
Segmentation in centrifugal blood pumps reveals distinct procurement rhythms and margin profiles across product categories. Cycle times vary dramatically—from single-use disposables replaced per procedure to implantable platforms requiring years of clinical validation.
Product Type:
Disposable pumps turn over fastest with each cardiac procedure, while implantable platforms demand extended development cycles and chronic reimbursement pathways.
- Implantable Pumps:Titanium-alloy housings with magnetic levitation bearings support multi-week to multi-month chronic hemodynamic support. Bridge-to-transplant programs in United States tertiary centers drive demand as CMS reimbursement codes anchor procedural economics.
- Disposable Pumps:Single-use polymer pump heads with integrated tubing sets eliminate sterilization logistics between cardiac surgery cases. Tertiary hospital cardiac surgery suites in the United States embed these into standardized ECMO protocols, creating consistent procedural pull-through.
- Peripheral Pumps:External centrifugal units for temporary circulatory support during high-risk PCI or post-cardiotomy failure.
- Miniaturized Pumps:Compact platforms designed for pediatric applications or percutaneous delivery through smaller access vessels.
Disposable pumps anchor the volume base while implantable pumps gain share at the steepest rate.
End User:
Customer concentration shapes contracting leverage, with integrated delivery networks consolidating purchasing power differently across facility types.
- Hospitals:Tertiary academic medical centers with perfusionist training infrastructure and ECMO capabilities command the highest procedural complexity. United States hospital procurement committees bundle pumps, disposables, and technical support through multi-year single-source agreements.
- Surgical Centers:Ambulatory surgical facilities focus on short-duration cardiopulmonary bypass with cost-sensitive disposable pump procurement.
- Cardiac Clinics:Outpatient settings increasingly involved in pre-operative assessment and post-implant patient monitoring.
- Research Institutions:University-affiliated centers driving magnetic levitation platform development through FDA breakthrough device designation pathways.
Hospitals capture the dominant revenue share while surgical centers expand most quickly as minimally invasive procedures migrate to lower-acuity settings.
Application:
Clinical use cases stratify by support duration, from hours in routine cardiac surgery to weeks in bridge-to-transplant protocols.
- Cardiac Surgery:Cardiopulmonary bypass during coronary artery bypass grafting and valve replacement procedures. United States surgical volumes concentrate in tertiary centers with dedicated perfusion teams.
- Extracorporeal Circulation:ECMO protocols for respiratory and cardiac failure requiring days to weeks of support. Standardization in United States tertiary cardiac surgery suites drives disposable pump set consumption.
- Hemodynamic Support:Temporary mechanical circulatory support during high-risk interventions or cardiogenic shock.
- Organ Transplantation:Bridge-to-transplant and bridge-to-recovery applications demanding chronic device reliability.
Cardiac surgery anchors the volume base while extracorporeal circulation gains share at the steepest rate.
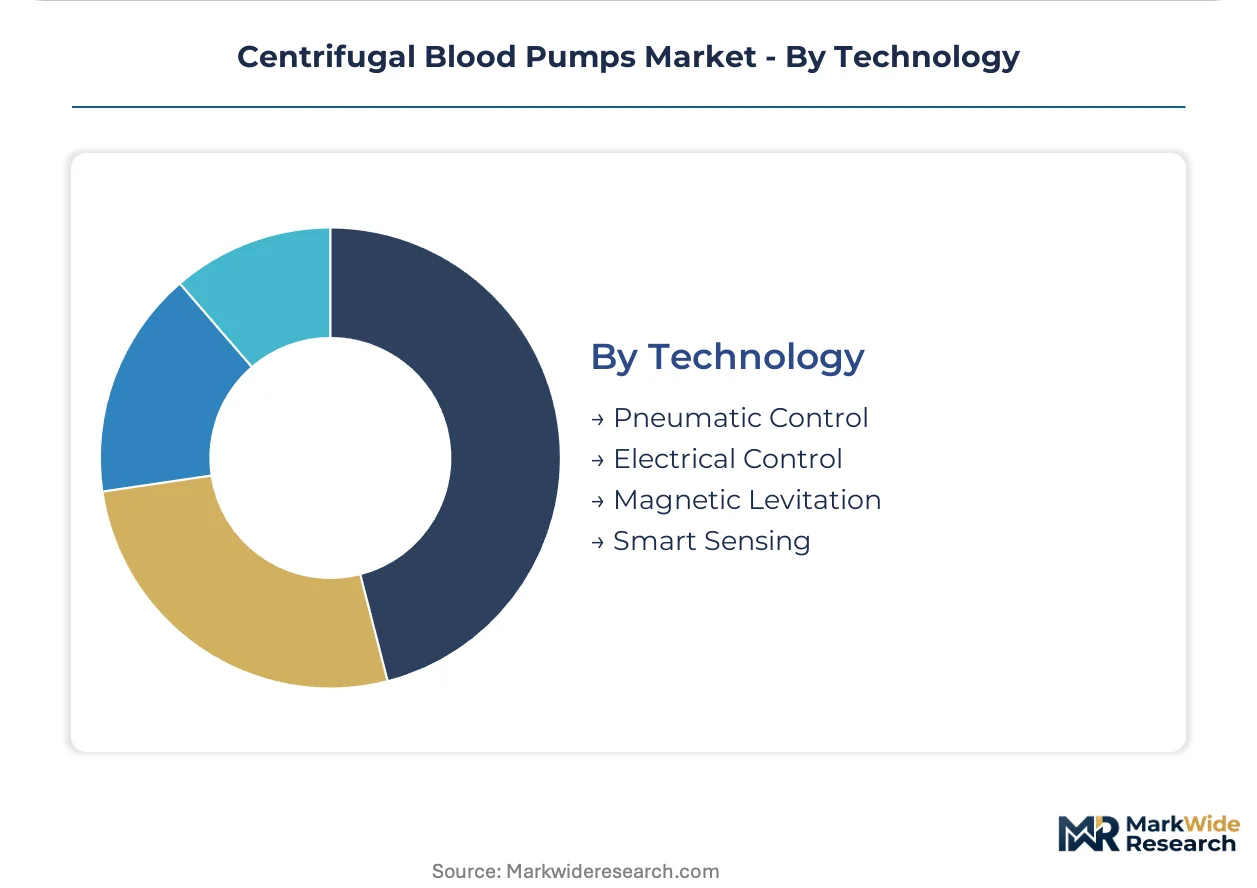
Technology:
Control architectures differentiate by precision, thrombogenicity profile, and regulatory validation burden.
- Magnetic Levitation:Contact-free impeller suspension eliminates bearing wear and reduces hemolysis indices below 0.05 g/100L thresholds. FDA breakthrough device designation accelerates premarket review for manufacturers addressing unmet chronic support needs.
- Electrical Control:Brushless DC motor systems with closed-loop flow feedback dominate contemporary disposable pump platforms.
- Pneumatic Control:Compressed air-driven mechanisms retain presence in legacy perfusion systems with lower capital requirements.
- Smart Sensing:Integrated pressure, flow, and bubble detection with predictive algorithms for thrombus formation.
Electrical control anchors the volume base while magnetic levitation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's cardiovascular device manufacturing corridor, where titanium billet suppliers and precision-machining clusters feed pump housing production for global medical device OEMs.
United States
Tertiary cardiac surgery suites in Cleveland Clinic and Mayo Clinic anchor ECMO protocol standardization, driving disposable pump set consumption. The FDA's Class III premarket approval pathway extends development timelines to 18-36 months, consolidating market access among capitalized manufacturers. Boston's Route 128 corridor hosts perfusionist training infrastructure that reinforces Medtronic's hospital contracting leverage.
Germany
Baden-Württemberg's industrial automation cluster supplies magnetic bearing assemblies for next-generation pump architectures. The EU Medical Device Regulation's clinical evidence requirements favor manufacturers with established post-market surveillance infrastructure. Berlin-Brandenburg research institutions collaborate with LivaNova on minimally invasive surgical platforms.
China
Jiangsu province's precision-machining ecosystem produces titanium pump housings for domestic and export markets. NMPA regulatory harmonization with ISO 14708 standards accelerates local manufacturer certification timelines. The Yangtze River Delta cardiovascular device corridor is reconfiguring regional supply dynamics for magnetic levitation components.
Japan
Tokyo's academic medical centers drive adoption of chronic hemodynamic support platforms in bridge-to-transplant programs. PMDA's breakthrough device designation pathway parallels FDA mechanisms for prioritized review. The Kansai region's ceramic bearing manufacturers supply legacy pump architectures while transitioning to contact-free magnetic levitation systems.
Switzerland
Swissmedic's streamlined approval processes for ISO 13485-certified manufacturers attract European headquarters for precision pump component suppliers. The Basel-Zurich corridor concentrates active implantable device expertise from cardiac rhythm management heritage. Geneva-based research institutions contribute to IEC 60601 electrical safety standard development for international commercialization.
Centrifugal Blood Pumps Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in bearing, magnet, and biocompatible housing supply. The vendor base concentrates around three strategic archetypes: diversified cardiovascular conglomerates with catheter-pump ecosystems, dedicated perfusion equipment manufacturers with decades of clinical training infrastructure, and emerging magnetic levitation specialists targeting chronic support white space. Competitive moves center on multi-year single-source IDN contracting and backward integration into titanium billet supply.
Among diversified cardiovascular conglomerates, Abbott Laboratories and Medtronic occupy positions spanning implantable and disposable pump platforms. LivaNova represents the dedicated cardiac surgery equipment archetype with specialized centrifugal platforms for European minimally invasive centers. These three anchors exemplify how regulatory capital, clinical training infrastructure, and magnetic levitation R&D allocation separate tier-one positioning from component-supplier margins.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| LivaNova |
| Terumo Corporation |
| Getinge AB |
| Braile Biomedica |
| Qura |
| Baxter International |
| Procyrion |
| Others |
Cost & Logistics Intelligence
Titanium alloy supply concentration in China's Jiangsu province determines both pricing tier spreads and supply chain shape, as precision-machined pump housing costs feed directly into implantable platform premiums while disposable polymer sets compete on procurement volume discounts. FDA PMA timeline friction compresses margin recovery windows for magnetic levitation R&D, forcing manufacturers to amortize development costs across extended contracting cycles with integrated delivery networks.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with three-tier pricing stratification across premium magnetic levitation implantables, standard electrical-control disposables, and economy pneumatic legacy systems. Price differentiation hinges on FDA breakthrough device designation status and ISO 14708 certification tier, with magnetic levitation platforms commanding substantial premiums for chronic hemodynamic support applications. Pricing pressure intensifies in disposable pump segments as peristaltic roller systems retain cost advantages for short-duration cardiopulmonary bypass procedures. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while tertiary academic medical centers prioritize device reliability and perfusionist training compatibility over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for titanium billet and precision-machined pump housing procurement. Manufacturing gravity centers on China for titanium alloy feedstock, Germany for magnetic bearing assemblies, and Switzerland for active implantable device electrical components. Raw material dependencies include titanium billet, neodymium rare-earth magnets, and biocompatible polymer formulations for disposable pump heads. Single-source vulnerability concentrates in China's Yangtze River Delta cardiovascular device corridor, where regional industrial policy shifts could disrupt global OEM supply. Distribution runs through integrated delivery network contracting offices in United States tertiary hospital systems, with multi-year single-source agreements bundling pumps, disposables, and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifugal blood pumps market sits at a platform-economics inflection driven by magnetic levitation ecosystem convergence, where catheter-pump interoperability and standardized ECMO protocols are restructuring competitive boundaries around integrated clinical training infrastructure rather than discrete device specifications.
For Market Incumbents: Pre-empt emerging magnetic levitation specialists by backward integration into titanium billet supply and captive production of precision-machined pump housings in China's Jiangsu province. Anchor hospital contracting leverage through expanded perfusionist training infrastructure in United States academic medical centers, creating switching costs that neutralize price competition from disposable pump entrants. Prioritize FDA breakthrough device designation submissions for chronic hemodynamic support platforms to compress premarket review timelines and establish regulatory moats. For New Entrants and Emerging Players: Pursue ambulatory platform white space in wearable centrifugal systems for chronic outpatient support, where CMS technology add-on payment determinations remain pending and reimbursement clarity will determine adoption velocity. Target European specialized cardiac surgery centers with minimally invasive percutaneous cannulation platforms, leveraging EU MDR clinical evidence requirements that favor new entrants with focused post-market surveillance infrastructure. Lead with magnetic levitation R&D partnerships with Baden-Württemberg industrial automation clusters to access bearing assembly expertise without captive manufacturing investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with catheter-pump ecosystem breadth over component specialists. Long-term viability over the next decade hinges on reimbursement policy alignment and magnetic levitation technology maturation for multi-month chronic support applications. Acquisition target archetype: magnetic levitation specialists with FDA breakthrough device designation progress and established relationships with United States tertiary transplant centers. Signal to watch: CMS technology add-on payment determinations for ambulatory mechanical circulatory support platforms as inflection indicator for next-generation market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review for magnetic levitation platforms addressing unmet chronic support needs. |
| Hospital System Partnership | Locks in multi-year single-source agreements through integrated delivery network contracting consolidation. |
| Backward Integration into Titanium Supply | Secures precision-machined pump housing feedstock against China tariff exposure and regional policy shifts. |
| Perfusionist Training Infrastructure Expansion | Creates clinical switching costs that reinforce contracting leverage in United States tertiary centers. |
| Reimbursement Strategy | Aligns CMS technology add-on payment submissions with magnetic levitation chronic support platform launches. |
Research Approach
A standing panel of cardiac surgeons, perfusionists, hospital purchasing committee chairs, and biomedical engineers provided ongoing calibration across primary interview cycles and secondary validation. Stakeholder input combined with FDA PMA filing databases, CMS Medicare reimbursement code determinations, hospital procurement contract registries, and ISO 14708 certification records. Bottom-up pump shipment modeling and top-down mechanical circulatory support market sizing were triangulated to reconcile volume estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with magnetic levitation adoption curves, ECMO protocol standardization rates, and CMS reimbursement policy trajectories as key segmentation dimensions. CAGRs derived from installed base turnover analysis and replacement cycle assumptions for disposable versus implantable platforms. Industry-specific forecast inputs included perfusionist training pipeline capacity and China titanium alloy supply elasticity.
Sensitivities concentrate around FDA PMA timeline extensions, China export policy shifts for titanium billet, and CMS technology add-on payment determinations for ambulatory platforms. Forecasts reflect documented assumptions regarding magnetic levitation reliability maturation and ECMO protocol penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Perfusion Systems Market