
 Automated Compounding Systems Market | 2026-2036
Automated Compounding Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Compounding Systems Market Outlook
Hospital pharmacies are rotating toward automated compounding as the dominant buyer archetype, displacing traditional manual workflows in smaller clinic settings. Baxter International Inc. leverages its integrated infusion therapy portfolio to anchor large-scale hospital deployments across North America. ICU Medical, Inc competes through specialized closed-system transfer device compatibility with automated platforms. Omnicell, Inc differentiates via software-controlled inventory synchronization that extends beyond compounding into broader pharmacy automation.
Automated compounding systems are electromechanical platforms that combine robotic manipulation, gravimetric verification, and laminar airflow containment to prepare sterile injectable medications with precision measured to milligram or milliliter tolerances. Their primary purpose is eliminating human exposure to hazardous drugs while ensuring dose accuracy in parenteral preparations. Centralized systems dominate current installed base due to regulatory preference for dedicated cleanroom infrastructure, though decentralized units are capturing fastest-growing demand from satellite infusion centers seeking point-of-care flexibility. Gravimetric technology leads in new installations because real-time weight verification satisfies both FDA 503B requirements and institutional risk-management protocols.
The US FDA, EU EMA through its GMP Annex 1 revisions, and Japan's PMDA collectively shape product standards by mandating isolator-based containment and environmental monitoring documentation for sterile compounding. These frameworks create compliance-driven replacement cycles that sustain equipment demand even absent volume growth. Stakeholders must monitor evolving pharmacopeial standards for robotic verification methods as regulators weigh algorithmic inspection against traditional visual checks.
Market Dynamics
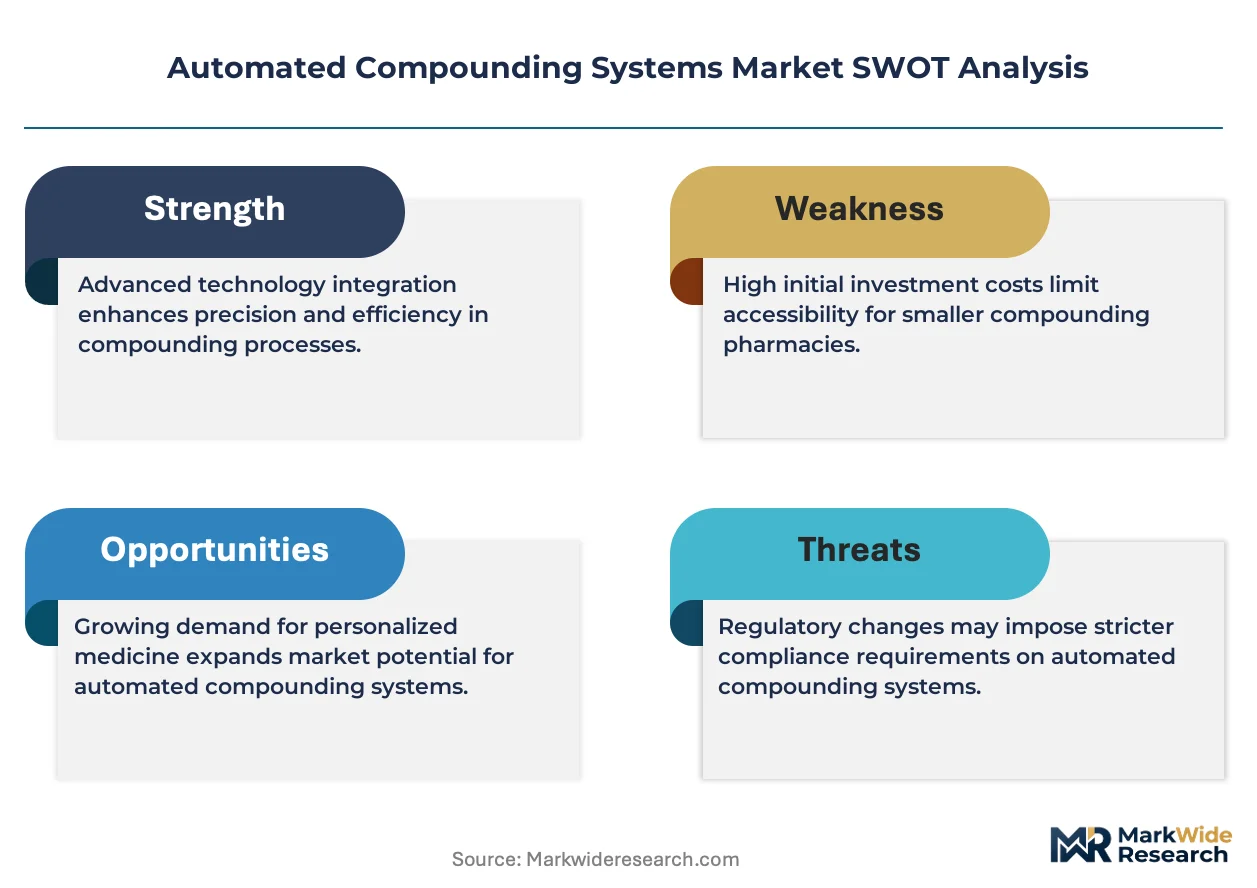
Hospital pharmacy consolidation is compressing procurement timelines while simultaneously elevating sterility assurance requirements, forcing equipment vendors to bundle validation services with hardware sales.
Growth Catalysts
- FDA 503B Outsourcing Facility Guidance:The updated sterility assurance mandates compel hospital systems to replace manual compounding workflows with validated robotic platforms to maintain compliance and avoid enforcement actions.
- Oncology infusion expansion:Rising parenteral chemotherapy volumes in tertiary care centers create throughput pressure that robotic systems resolve through 24-hour continuous operation capabilities.
- Gravimetric verification protocols:Real-time weight-based dose confirmation technology satisfies institutional risk-management requirements while reducing labor-intensive secondary checks.
Market Restraints
- Stainless steel and medical-grade polymer input costs:Volatility in specialty material pricing compresses equipment margins and extends quote-to-delivery cycles for custom isolator configurations.
- Cleanroom infrastructure dependency:Centralized systems require dedicated HVAC and environmental monitoring investments that smaller satellite facilities cannot justify, limiting addressable market penetration.
- Visual inspection persistence:Pharmacopeial standards in multiple jurisdictions still mandate human verification for final product release, creating regulatory friction against fully automated quality systems.
Strategic Opportunities
- Decentralized point-of-care deployment:Compact automated units for satellite infusion centers in Germany and Japan address flexibility demands without full cleanroom construction.
- EMA GMP Annex 1 alignment services:Compliance consulting bundled with equipment sales captures value from facilities navigating isolator-based containment upgrades across European markets.
- Closed-system transfer device convergence:Integration of automated compounding with hazardous drug containment hardware creates unified workflow platforms for oncology pharmacies.
Industry Challenges
- Specialized pharmacy technician scarcity:Robotic maintenance and aseptic technique certification programs face enrollment gaps that delay deployment timelines and increase training costs.
- Legacy pharmacy information system integration:Automated compounding platforms require custom middleware development to synchronize with existing electronic health record and inventory management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Compounding Systems Market |
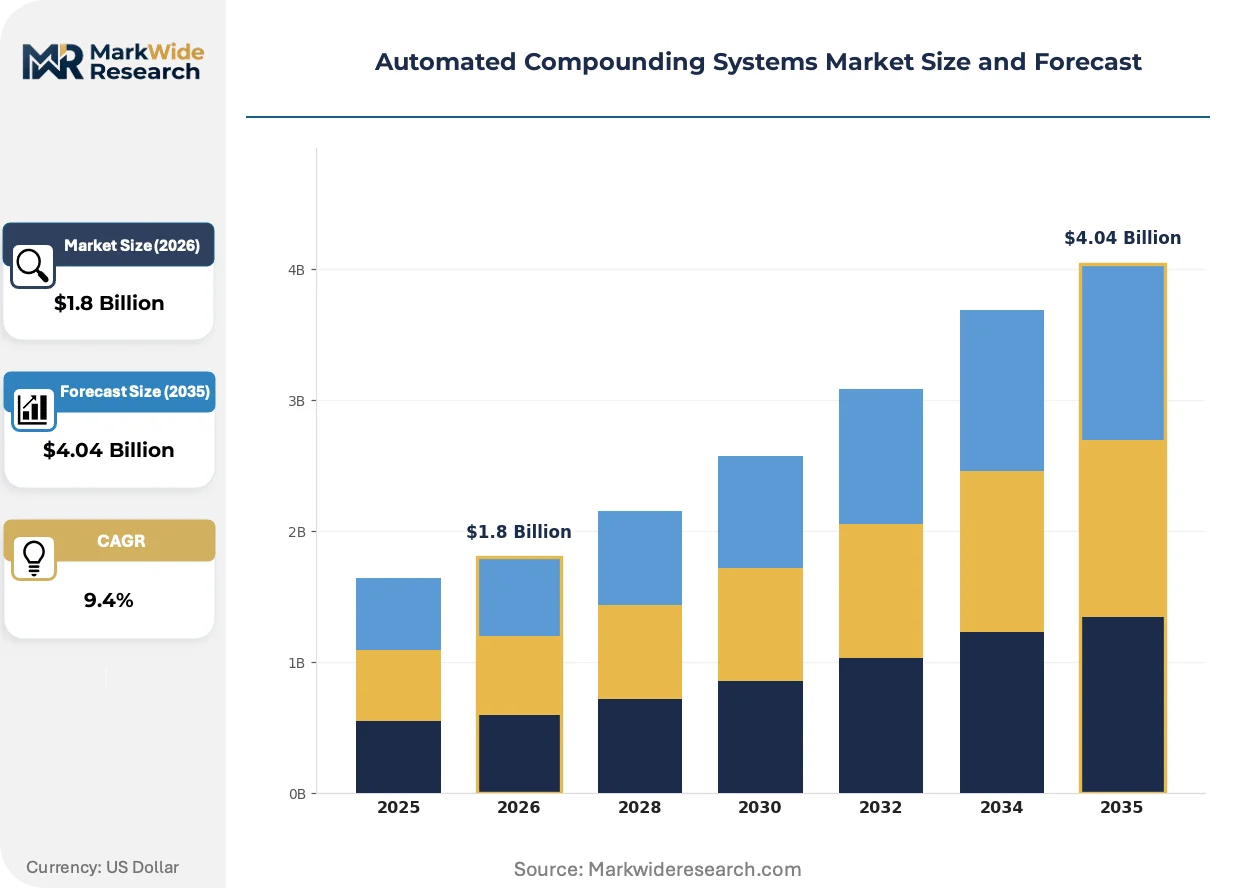
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized, Decentralized, Software, Hardware End User: Hospitals, Pharmacies, Home Care, Research Institutions Technology: Robot-Assisted, Automated Dispensing, Visual Inspection, Gravimetric Application: Oncology, Pain Management, Parenteral Nutrition, Antibiotics |
| Companies Covered | Baxter International Inc., ICU Medical, Inc, Omnicell, Inc, Grifols, S.A., COMECER S.p.A., ARxIUM, EQUASHIELD, B. Braun Medical Inc., BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Compounding Systems Market Strategic Shifts
Gravimetric verification architectures are displacing volumetric measurement as the default engineering standard, while regulatory documentation requirements push vendors toward integrated environmental monitoring suites.
Closed-system transfer device integration is supplanting standalone compounding robots as the preferred hospital pharmacy configuration. Oncology departments at academic medical centers in the United States are specifying unified platforms that combine robotic manipulation with hazardous drug containment. This convergence is compressing vendor R&D cycles toward single-source procurement decisions that favor integrated technology portfolios over best-of-breed component assembly.
EMA's GMP Annex 1 revision mandates continuous environmental monitoring documentation for sterile compounding operations. Pharmaceutical manufacturers and 503B outsourcing facilities must retrofit existing cleanrooms with automated data capture systems or face inspection deficiencies. The isolator-based containment segment is responding fastest, with vendors pre-integrating particle counters and pressure differential loggers into standard equipment configurations.
Pharmacy procurement committees are consolidating vendor relationships through multi-year service contracts that bundle equipment, validation, and consumables. Independent community hospitals and regional health systems are abandoning transactional purchasing for partnership models that transfer uptime risk to manufacturers. This behavioral shift is most visible in United States integrated delivery networks, where standardization across dozens of facilities creates volume leverage for sole-source negotiations.
Automated Compounding Systems Market Segmentation
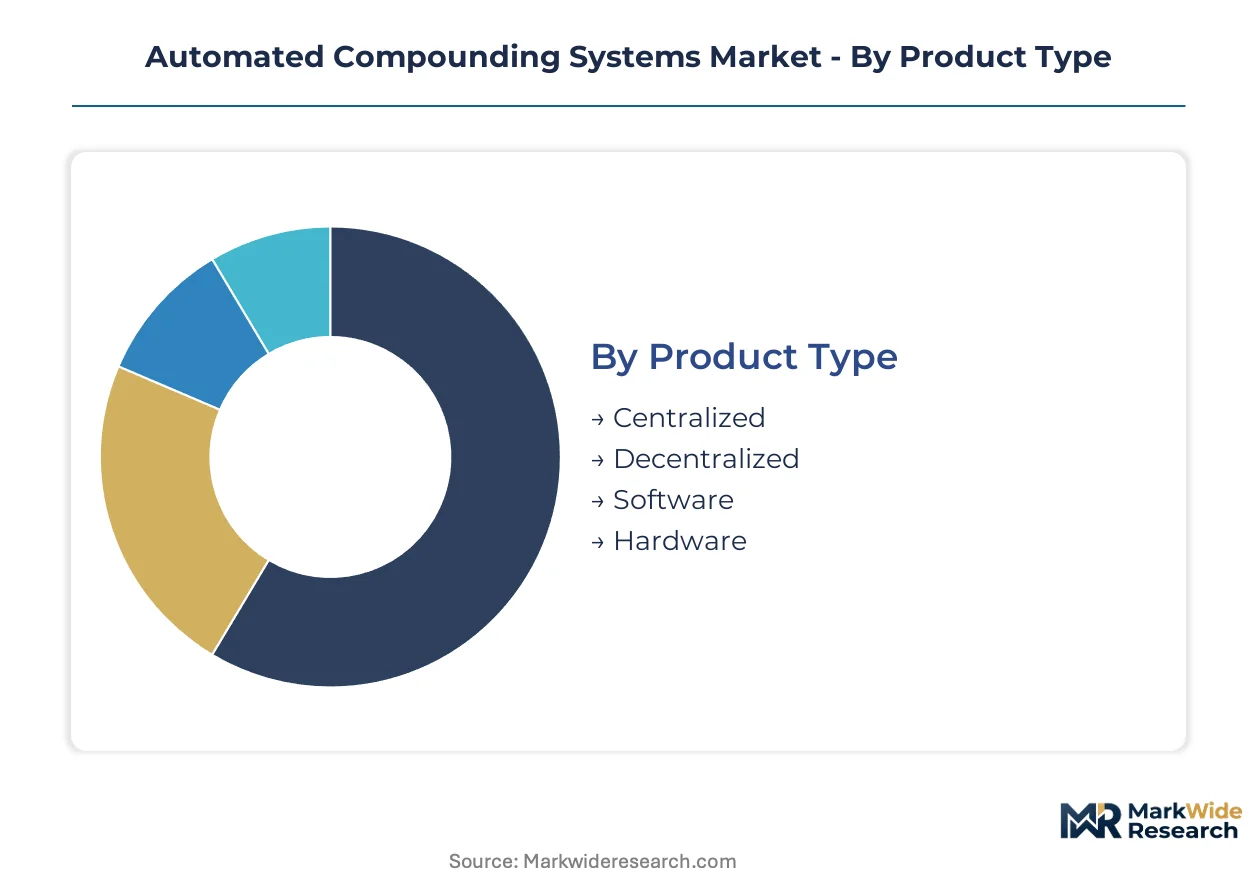
Segmentation in automated compounding systems reveals distinct procurement patterns across hospital networks, with product architecture and end-use setting determining validation requirements and service bundling intensity. Channel strategies diverge sharply between capital-intensive centralized installations and compact point-of-care units.
Product Type:
Centralized systems flow through integrated delivery network procurement committees with multi-site standardization mandates, while decentralized units reach satellite facilities through specialized distributors serving regional infusion centers.
- Centralized:Large-scale robotic platforms requiring dedicated cleanroom infrastructure and HVAC integration. Demand concentrates in United States academic medical centers and German tertiary hospitals where FDA 503B and EMA GMP Annex 1 compliance costs amortize across high chemotherapy volumes.
- Decentralized:Compact units designed for satellite infusion centers without full environmental containment. Japan's regional cancer centers and United States ambulatory surgery networks are expanding deployment fastest, driven by point-of-care flexibility requirements and avoidance of centralized pharmacy bottlenecks.
- Software:Validation documentation suites and environmental monitoring data management platforms.
- Hardware:Robotic manipulators, isolators, and gravimetric verification modules as standalone capital purchases.
By volume, Centralized leads. By growth pace, Decentralized is climbing the fastest.
End User:
Cost tiers stratify sharply, with hospital systems absorbing full validation service bundles while home care segments drive hardware-only procurement through reimbursement-constrained channels.
- Hospitals:Tertiary care institutions with 24-hour oncology infusion operations and dedicated pharmacy automation budgets. United States integrated delivery networks and German university hospitals represent the core revenue concentration, with procurement committees demanding uptime guarantees and multi-year service contracts.
- Pharmacies:503B outsourcing facilities and health system central fill operations subject to FDA sterility assurance mandates. The segment shows strong replacement cycle activity as older manual workflows face enforcement pressure.
- Home Care:Limited penetration due to infrastructure requirements, with niche demand for portable parenteral nutrition compounding in Germany and Japan.
- Research Institutions:Preclinical and clinical trial material preparation with specialized containment needs for investigational oncology compounds.
By installed base, Hospitals dominate. By contract value expansion, Pharmacies are gaining share fastest.
Technology:
Application intensity varies by therapeutic risk profile, with oncology workflows demanding the highest verification redundancy while pain management permits simpler automated dispensing configurations.
- Gravimetric:Real-time weight-based dose confirmation technology that satisfies both FDA 503B requirements and institutional risk-management protocols. New installation preference is strongest in United States and Japanese facilities where regulatory documentation standards are most stringent.
- Robot-Assisted:Multi-axis manipulators for hazardous drug handling in isolator environments. German oncology pharmacies specify these platforms most heavily, driven by EMA GMP Annex 1 alignment and worker exposure limits.
- Automated Dispensing:Carousel and vault systems for non-hazardous medication preparation with lower regulatory burden.
- Visual Inspection:Camera-based verification systems facing regulatory friction as pharmacopeial standards in multiple jurisdictions still mandate human release for final products.
By deployment share, Gravimetric leads. By technology transition momentum, Robot-Assisted shows the steepest expansion trajectory.
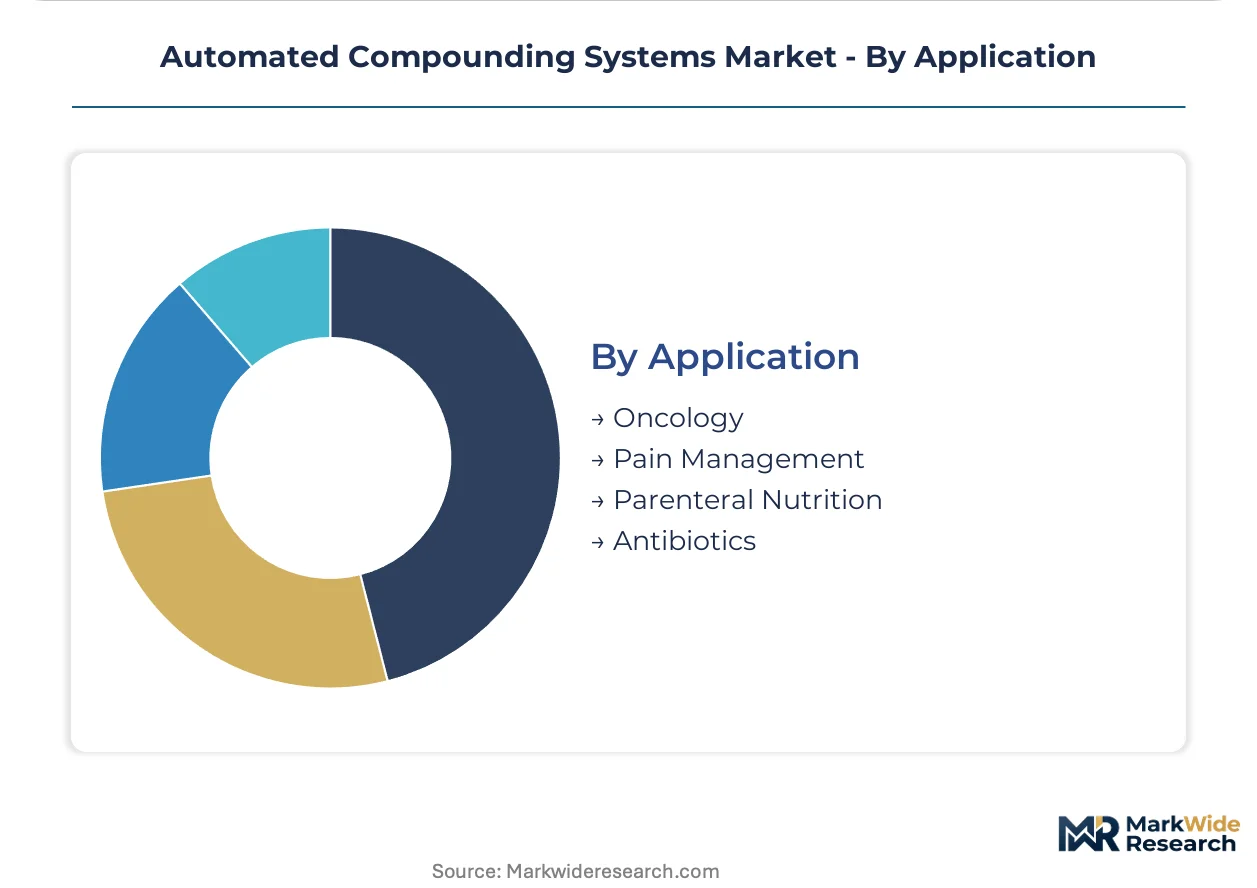
Application:
Customer maturity determines specification intensity, with oncology commanding isolator-grade containment while antibiotics permit simpler automated dispensing configurations in cost-sensitive settings.
- Oncology:Parenteral chemotherapy preparation requiring closed-system transfer device integration and hazardous drug containment. United States academic medical centers and Japanese national cancer centers drive specification development, with 24-hour throughput demands justifying capital investment.
- Parenteral Nutrition:Complex multi-chamber bag compounding for critical care and home infusion. German hospital pharmacies show strongest adoption, linked to reimbursement structures supporting pharmacy automation.
- Pain Management:Opioid and analgesic preparation with controlled substance tracking requirements.
- Antibiotics:High-volume sterile preparation with shorter stability windows and less stringent containment needs.
By revenue concentration, Oncology leads. By volume expansion, Parenteral Nutrition is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites Europe's central role in sterile drug distribution, while Japan's Shinkansen freight network enables rapid parenteral medication transport between regional cancer centers.
United States
Academic medical centers in Boston and Houston drive centralized system procurement for 24-hour oncology operations. FDA 503B sterility assurance mandates compel hospital systems to replace manual compounding workflows with validated robotic platforms. The Texas Medical Center cluster anchors large-scale deployments serving multiple institutions through shared pharmacy infrastructure.
Germany
Tertiary hospitals in Munich and Heidelberg specify robot-assisted platforms for hazardous drug handling under worker exposure limits. EMA GMP Annex 1 alignment requirements push facilities toward isolator-based containment retrofits. The Rhine-Main pharmaceutical corridor concentrates vendor service operations and validation consulting capacity.
Japan
National cancer centers in Osaka and Nagoya deploy gravimetric verification systems to satisfy PMDA documentation standards for sterile preparation. METI reimbursement structures support pharmacy automation capital investment in regional hospitals. The Kanto region's aging demographic profile accelerates parenteral nutrition compounding demand for home infusion programs.
United Kingdom
NHS trusts in London and Manchester consolidate procurement through integrated pharmacy networks seeking multi-site standardization. MHRA guidance on aseptic preparation aligns with EU regulatory frameworks post-Brexit transition. The Cambridge-Oxford life sciences arc generates research institution demand for specialized containment in investigational oncology.
Switzerland
University hospitals in Basel and Zurich invest in closed-system transfer device convergence for oncology pharmacy workflows. Swissmedic inspection standards exceed baseline EU requirements, creating premium-tier equipment specifications. The Basel pharmaceutical manufacturing cluster sustains demand for high-throughput centralized compounding serving clinical trial material preparation.
Automated Compounding Systems Market Competitive Environment
Concentration sits with diversified medical technology conglomerates that leverage integrated infusion therapy portfolios to anchor hospital system deployments. The vendor base spans three strategic tiers: full-platform providers bundling hardware with validation services, specialized isolator manufacturers focusing on containment engineering, and software-centric vendors emphasizing inventory synchronization. Competitive moves center on multi-year service contracts transferring uptime risk to manufacturers, and pre-integrated environmental monitoring suites responding to EMA documentation mandates.
Among diversified healthcare technology providers, Baxter International Inc. and ICU Medical, Inc occupy positions exemplifying platform-scale archetypes, while Omnicell, Inc represents the pharmacy automation convergence vector. These entities anchor procurement committee discussions through bundled offerings that extend beyond compounding into broader medication management infrastructure.
| Leading Market Players |
|---|
| Baxter International Inc. |
| ICU Medical, Inc |
| Omnicell, Inc |
| Grifols, S.A. |
| COMECER S.p.A. |
| ARxIUM |
| EQUASHIELD |
| B. Braun Medical Inc. |
| BD |
| Others |
Value Chain & Pricing Dynamics
Multi-year service contracts with uptime guarantees lock in supply access for hospital systems while freezing price visibility across the contract term, insulating buyers from stainless steel and medical-grade polymer volatility that compresses equipment margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated platforms with full validation bundles from standalone robotic units and refurbished legacy systems. Price differentiation hinges on FDA 503B certification tier and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because specialty material input volatility extends quote-to-delivery cycles. 503B outsourcing facilities show highest price sensitivity due to reimbursement constraints, while United States academic medical centers absorb premium pricing for compliance assurance.
Supply Chain Analysis
Port congestion on trans-Pacific lanes from Chinese and Japanese component hubs elevates inbound logistics costs for robotic manipulator and gravimetric sensor modules. Manufacturing concentration rests on Germany for precision isolator engineering, Japan for gravimetric verification components, and the United States for software-controlled inventory platforms. Single-source vulnerability runs through medical-grade polymer feedstock suppliers subject to pharmaceutical-grade certification bottlenecks. Distribution runs through integrated delivery network procurement committees with multi-site standardization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated compounding systems sit in early-cycle expansion, with FDA 503B enforcement pressure and EMA GMP Annex 1 retrofits creating sustained replacement demand even absent volume growth in sterile preparation.
For Market Incumbents: Secure long-term service contracts that transfer uptime risk to manufacturers, insulating against emerging software-centric vendors emphasizing inventory synchronization over hardware. Deepen backward integration into medical-grade polymer supply to offset input cost volatility compressing equipment margins. Prioritize isolator-based containment certification investments that exceed baseline regulatory thresholds. For New Entrants and Emerging Players: Differentiate on compact decentralized units for satellite infusion centers in Germany and Japan where point-of-care flexibility commands premium positioning without full cleanroom construction. Target 503B outsourcing facilities facing enforcement-driven replacement cycles with validation-documentation-as-a-service bundles. Pursue hazardous drug containment hardware convergence as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap isolator engineering specialists with EMA GMP Annex 1 alignment capabilities and existing hospital system validation relationships. Long-term viability centers on compliance consulting revenue streams that persist through equipment replacement cycles. Watch for PMDA documentation standard tightening as the inflection signal accelerating gravimetric verification adoption in Japanese regional cancer centers.| Strategic Initiative | Industry Significance |
|---|---|
| EMA GMP Annex 1 Alignment Services | Compliance consulting bundled with equipment captures value from European isolator retrofit mandates. |
| Closed-System Transfer Device Convergence | Unified workflow platforms address oncology pharmacy specifications at United States academic medical centers. |
| Decentralized Point-of-Care Deployment | Compact units serve satellite infusion centers in Japan and Germany without full cleanroom construction. |
| Multi-Year Service Contract Standardization | Uptime risk transfer models align vendor incentives with integrated delivery network procurement committees. |
| Gravimetric Verification Architecture Migration | Real-time weight-based dose confirmation satisfies FDA 503B and institutional risk-management protocols. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hospital pharmacy directors, 503B facility compliance officers, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 503B guidance documents, EMA GMP Annex 1 revisions, PMDA sterility standards, hospital procurement databases, and equipment vendor SEC filings. Bottom-up and top-down triangulation cross-validated installation base estimates with capital expenditure disclosures from United States integrated delivery networks.
Across the projection horizon, the analytical framework modeled demand across product architecture, end-use setting, technology type, and application intensity with regional regulatory cluster overlays. CAGRs were derived from segment-level adoption curves weighted by compliance-driven replacement cycle timing. Forecast inputs incorporated chemotherapy volume trajectories at tertiary care centers and METI reimbursement structures supporting Japanese pharmacy automation investment.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement pressure and EMA documentation mandate adherence would require recalibration. Forecasts reflect assumptions regarding stainless steel and medical-grade polymer supply stability, specialized pharmacy technician certification program enrollment, and legacy pharmacy information system integration feasibility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Saliva Collection Devices Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Asia-Pacific Electrophysiology Market