
 Lupus Anticoagulant Testing Market | 2026-2036
Lupus Anticoagulant Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Lupus Anticoagulant Testing Market Foresight
Germany is tilting toward expanded automated hemostasis capacity as academic medical centers upgrade coagulation laboratories. F. Hoffmann-La Roche leverages its installed base of cobas analyzers to sustain recurring reagent revenue across European hospital networks. Abbott Laboratories anchors its position through point-of-care coagulation platforms that extend testing beyond centralized labs. Diagnostica Stago specializes in niche hemostasis instrumentation that dominates reference laboratory workflows for complex antibody detection.
Lupus anticoagulant testing comprises a panel of phospholipid-dependent coagulation assays designed to detect antibodies that paradoxically prolong clotting times despite their association with thrombotic risk; the dRVVT and aPTT-based mixing studies remain the functional core of clinical evaluation, with silica clotting time and hexagonal phase phospholipid neutralization providing confirmatory specificity. Assay kits and reagents command the recurring revenue base as laboratories process high-frequency screening protocols, while automated systems capture capital investment cycles as mid-sized hospitals replace manual workflows. Diagnostic labs represent the volume concentration point where throughput economics and regulatory accreditation requirements create durable supplier relationships.
The FDA and Clinical Laboratory Improvement Amendments shape analytical performance standards and proficiency testing mandates that determine market access for assay manufacturers, while the EU's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements on hemostasis reagent kits sold across European member states. Laboratories must navigate divergent premarket pathways as the FDA's de novo classification process for novel coagulation markers runs parallel to EMA-notified body conformity assessments. Stakeholders should monitor how consolidated procurement within US integrated delivery networks and European hospital alliances reshapes pricing leverage and exclusivity terms for testing platforms.
Market Dynamics
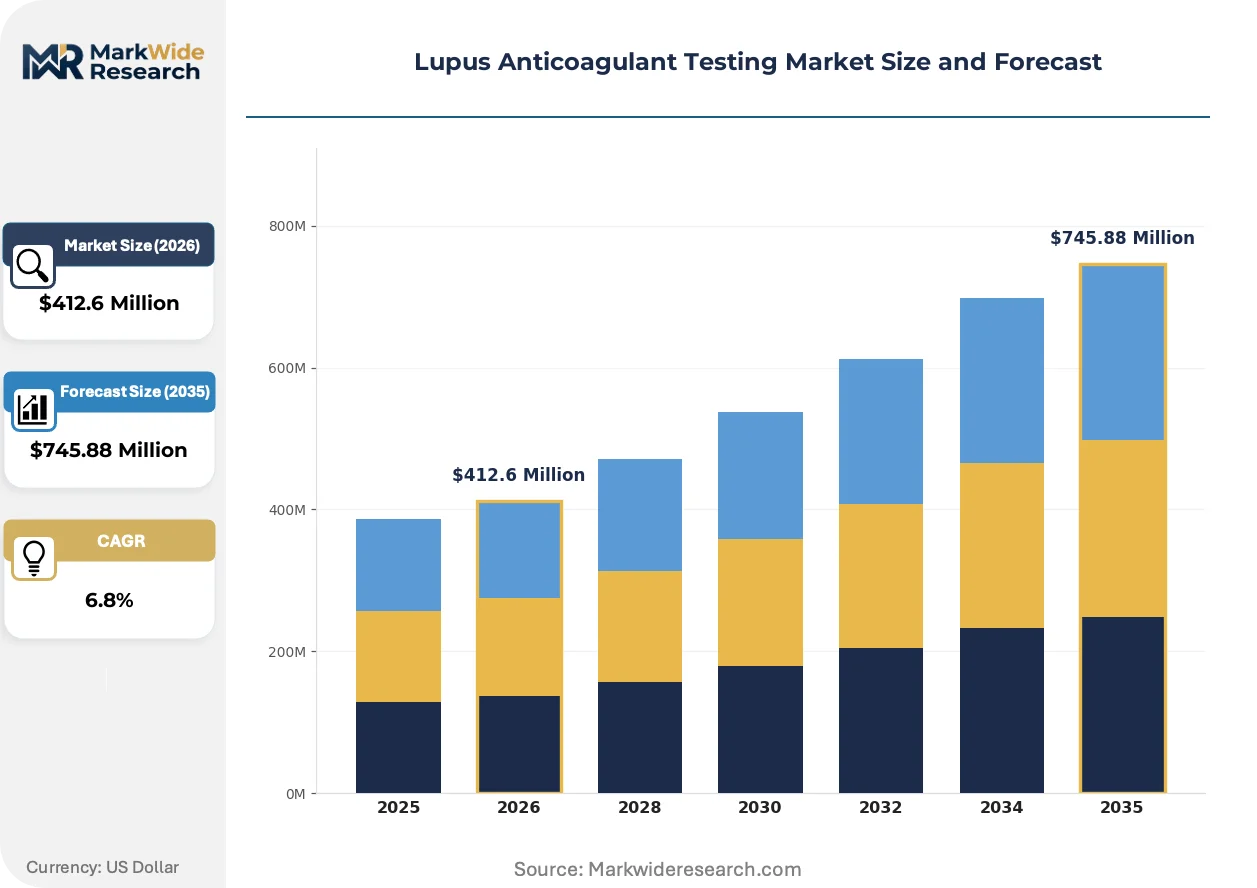
Automated hemostasis platforms are compressing manual coagulation workflows as mid-sized hospitals replace labor-intensive dRVVT and aPTT mixing studies with integrated analyzer systems. This capital replacement cycle concentrates purchasing power within integrated delivery networks and European hospital alliances.
Growth Catalysts
- Antiphospholipid syndrome screening protocols:Academic medical centers in Germany are expanding coagulation laboratory capacity to handle rising referral volumes from rheumatology and obstetrics departments.
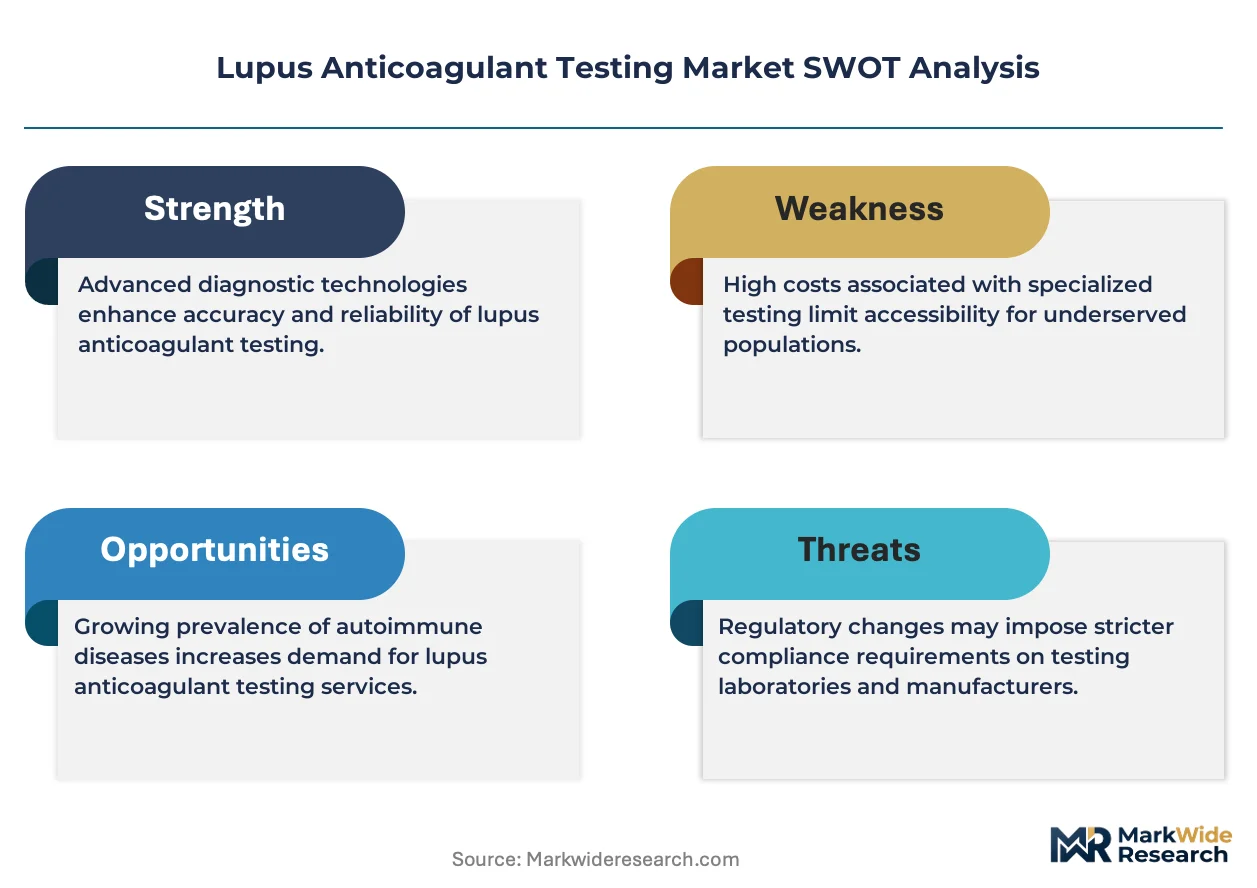
- FDA Clinical Laboratory Improvement Amendments:Updated quality control mandates for hemostasis assays are forcing laboratory consolidation, driving replacement demand for compliant automated systems.
- Silica clotting time standardization:Reference laboratories are adopting hexagonal phase phospholipid neutralization confirmatory testing to reduce false-positive rates in complex antibody detection.
Market Restraints
- Reagent cost volatility:Phospholipid-dependent coagulation reagents face input pressure from purified phospholipid supply constraints sourced through specialized chemical suppliers.
- Technical standardization gaps:Inter-laboratory variability in dRVVT interpretation persists due to lack of harmonized cutoff thresholds across testing platforms.
- EU In Vitro Diagnostic Regulation:Stricter clinical evidence requirements for hemostasis reagent kits are extending time-to-market and compliance costs for manufacturers serving European member states.
Strategic Opportunities
- Point-of-care coagulation platforms:Extension of testing beyond centralized laboratories into emergency departments and anticoagulation clinics creates new placement channels.
- EMA-notified body pathway optimization:Manufacturers can accelerate European market access by structuring clinical validation studies to parallel FDA de novo classification processes.
- Regional hub consolidation:United States integrated health networks are centralizing reference testing, creating volume concentration points for exclusive supplier arrangements.
Industry Challenges
- Specialized coagulation technologist shortage:Complex antibody detection workflows require expertise in mixing study interpretation that training programs are not producing at sufficient rates.
- Legacy analyzer integration:Mid-sized hospital laboratories face workflow disruption when connecting new automated systems to existing laboratory information management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lupus Anticoagulant Testing Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assay Kits, Reagents, Instrumentation, Consumables End User: Hospitals, Diagnostic Labs, Research Centers, Clinics Technology: ELISA, Lateral Flow, Automated Systems, Hemostasis Testing Application: Clinical Diagnosis, Research Studies, Routine Testing, Emergency Care |
| Companies Covered | Laboratory Corporation of America Holdings, ARUP Laboratories, Mayo Clinic Laboratories, Quest Diagnostics, Precision Biologics, Diagnostica Stago, F. Hoffmann-La Roche, Abbott Laboratories, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lupus Anticoagulant Testing Market Shifts & Advancements
Functional coagulation testing is migrating toward fully automated, random-access platforms that compress turnaround times for antiphospholipid syndrome workups. This technological shift is reshaping capital allocation patterns across hospital laboratory networks.
Next-generation hemostasis analyzers are migrating from batch-processed, semi-automated dRVVT workflows to continuous-loading, STAT-capable systems. Academic medical centers in Germany are adopting these platforms to handle unpredictable emergency department volumes. The technology is migrating from high-complexity reference laboratories into mid-sized hospital coagulation departments, compressing the addressable market for manual assay methods.
The EU In Vitro Diagnostic Regulation is imposing stricter post-market surveillance and clinical evidence requirements on hemostasis reagent manufacturers. Industrial consequence includes extended conformity assessment timelines and expanded documentation burdens for phospholipid-dependent assay kits. Reference laboratories across European member states are responding by consolidating supplier relationships to reduce regulatory validation overhead.
Integrated delivery networks are unbundling after-sales service contracts from analyzer hardware procurement, treating reagent supply and maintenance as separately negotiated line items. This purchasing behavior change disrupts traditional bundled pricing models and shifts negotiation leverage toward procurement departments. The pattern is most visible in United States health systems consolidating regional reference testing into centralized hubs.
Lupus Anticoagulant Testing Market Segmentation
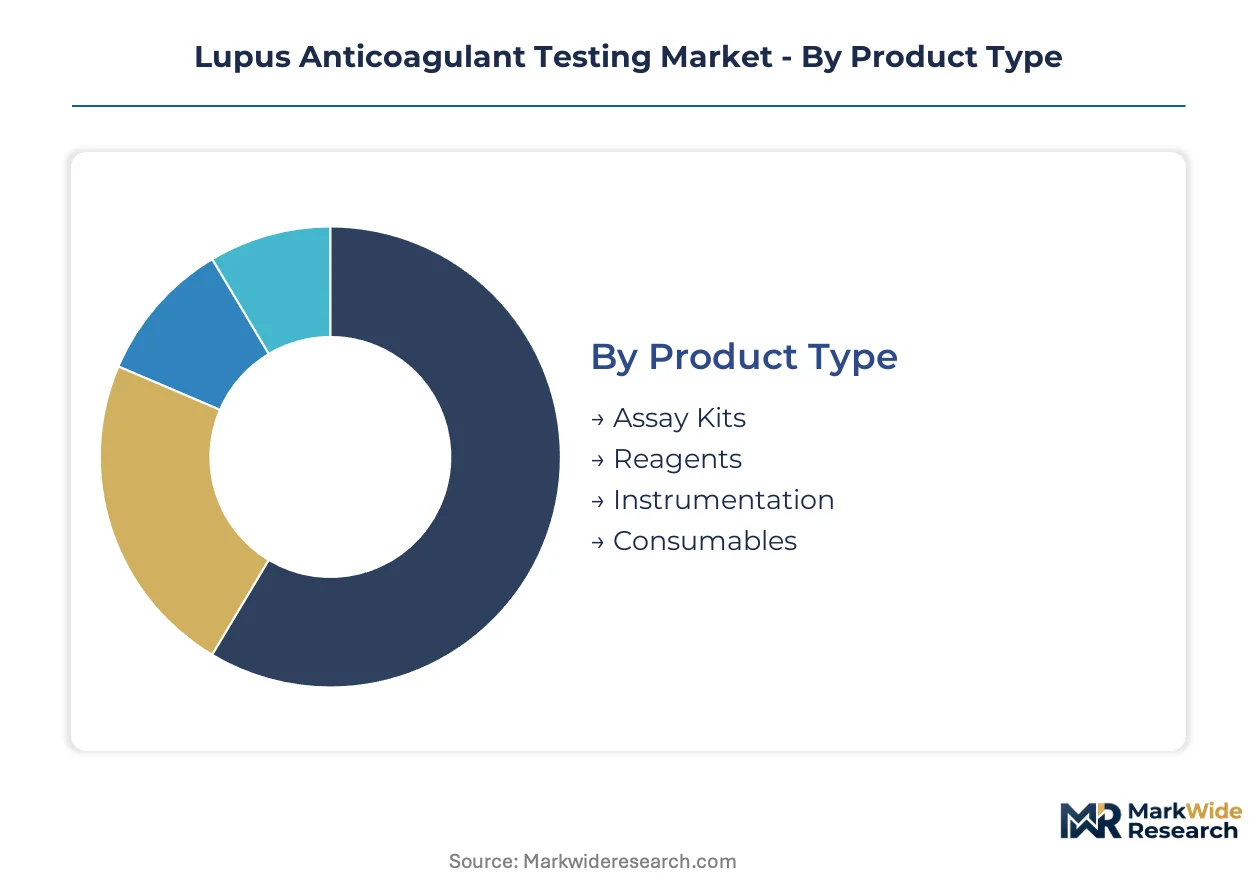
Segmentation in lupus anticoagulant testing reflects divergent purchasing rhythms: capital equipment cycles for analyzers, recurring reagent contracts, and point-of-care consumables each command distinct procurement channels. Laboratories prioritize product categories based on workflow automation levels and regulatory accreditation requirements.
Product Type:
Cost tier stratification separates recurring consumables from capital-intensive instrumentation, with reagent economics dominating long-term supplier relationships.
- Assay Kits:Pre-configured phospholipid-dependent coagulation panels bundle dRVVT and aPTT-based mixing studies for standardized antiphospholipid syndrome workups. Hospital laboratories in Germany are consolidating kit procurement through European hospital alliances to reduce per-test costs.
- Reagents:Purified phospholipid formulations and activated partial thromboplastin reagents constitute the recurring revenue foundation for hemostasis suppliers. Supply constraints on specialized chemical inputs are compressing margins for manufacturers serving high-throughput diagnostic labs.
- Instrumentation:Automated hemostasis analyzers with random-access STAT capability anchor capital replacement cycles.
- Consumables:Cuvettes, pipette tips, and reaction vessels complete assay workflows.
Assay kits hold installed capacity. Reagents are rotating up the share rankings.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating reference testing into centralized hubs that command exclusive supplier negotiations.
- Hospitals:Academic medical centers maintain high-complexity coagulation laboratories handling emergency department STAT volumes and obstetrics referrals. Mid-sized hospitals are replacing manual dRVVT workflows with integrated analyzer systems to address specialized technologist shortages.
- Diagnostic Labs:Reference laboratories concentrate throughput economics for complex antibody detection, requiring hexagonal phase phospholipid neutralization confirmatory testing. FDA Clinical Laboratory Improvement Amendments proficiency testing mandates are forcing consolidation among independent labs.
- Research Centers:Academic institutions pursue novel coagulation marker discovery.
- Clinics:Anticoagulation clinics and rheumatology practices drive point-of-care placement.
Diagnostic labs hold installed capacity. Hospitals are rotating up the share rankings.
Technology:
Application maturity varies across detection methodologies, with automated platforms displacing manual ELISA workflows in high-throughput settings.
- Automated Systems:Continuous-loading hemostasis analyzers compress turnaround times for unpredictable emergency department volumes. German academic medical centers are adopting these platforms to handle antiphospholipid syndrome screening referrals from obstetrics departments.
- Hemostasis Testing:Functional coagulation assays including silica clotting time and dRVVT remain the clinical evaluation core. Inter-laboratory variability in cutoff thresholds persists due to lack of harmonized standards across testing platforms.
- ELISA:Enzyme-linked immunosorbent assays detect specific antiphospholipid antibodies.
- Lateral Flow:Point-of-care immunoassays extend testing beyond centralized laboratories.
Automated systems hold installed capacity. Hemostasis testing is rotating up the share rankings.
Application:
Volume concentration aligns with clinical urgency, where STAT-capable emergency care commands premium placement and routine screening drives reagent consumption.
- Clinical Diagnosis:Definitive antiphospholipid syndrome identification requires sequential dRVVT screening, mixing studies, and confirmatory hexagonal phase phospholipid neutralization. EU In Vitro Diagnostic Regulation post-market surveillance is extending validation timelines for diagnostic claim submissions.
- Routine Testing:High-frequency screening protocols for rheumatology and obstetrics departments generate recurring reagent demand. Integrated health networks are unbundling service contracts from analyzer procurement, shifting negotiation leverage toward procurement departments.
- Research Studies:Novel coagulation marker validation supports assay pipeline expansion.
- Emergency Care:STAT turnaround requirements drive point-of-care platform adoption.
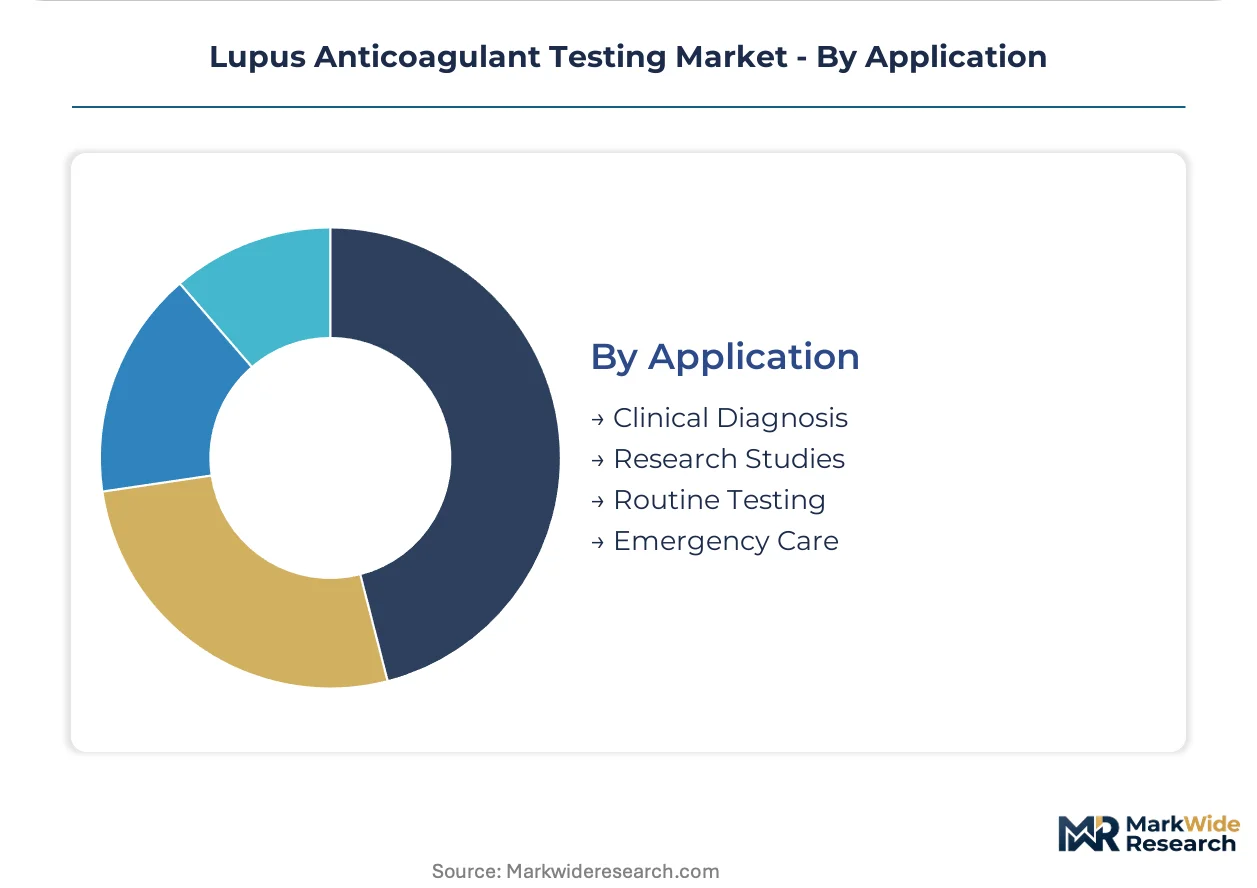
Clinical diagnosis holds installed capacity. Routine testing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic reagent manufacturing clusters in Germany and the United States anchor supply capacity for phospholipid-dependent coagulation assays. Automated hemostasis platform assembly concentrates in Swiss and Japanese industrial zones. Regulatory divergence between FDA and EMA pathways shapes regional market access timelines.
United States
Integrated delivery networks in Texas and California are consolidating reference testing into centralized regional hubs that command exclusive supplier negotiations. FDA Clinical Laboratory Improvement Amendments proficiency testing mandates are forcing independent laboratory consolidation. The Research Triangle Park corridor in North Carolina hosts contract research organizations validating novel coagulation markers for de novo classification submissions.
Germany
Academic medical centers in Bavaria and Baden-Württemberg are expanding coagulation laboratory capacity to handle rising antiphospholipid syndrome referrals from rheumatology departments. EU In Vitro Diagnostic Regulation post-market surveillance requirements are extending conformity assessment timelines for hemostasis reagent kits. The Frankfurt-Rhine-Main metropolitan region anchors distribution logistics for European hospital alliance procurement.
Japan
PMDA regulatory pathways for in vitro diagnostics are harmonizing with international standards to accelerate market entry for automated hemostasis platforms. The Kanto region surrounding Tokyo concentrates reference laboratory capacity for complex antibody detection workflows. Osaka-based hospital networks are adopting STAT-capable analyzers to address emergency department volume unpredictability.
Switzerland
Swissmedic oversight of medical devices maintains stringent quality benchmarks that shape global hemostasis analyzer design specifications. The Basel metropolitan area anchors pharmaceutical and diagnostic technology clusters with integrated reagent manufacturing. Geneva-based hospital networks serve as early adoption sites for hexagonal phase phospholipid neutralization confirmatory testing protocols.
United Kingdom
NHS England procurement frameworks are consolidating coagulation testing contracts into regional pathology networks that reshape supplier pricing leverage. The Medicines and Healthcare products Regulatory Agency post-Brexit regulatory pathway diverges from EU MDR timelines. London teaching hospitals maintain high-complexity reference laboratory capacity for specialized mixing study interpretation.
Lupus Anticoagulant Testing Market Competitive Landscape
Full-service diagnostic conglomerates and specialized hemostasis instrumentation developers split the market between bundled platform-reagent contracts and niche reference laboratory workflows. Consolidated purchasing power within US integrated delivery networks and European hospital alliances compresses margins for mid-tier suppliers. Two dominant strategic archetypes emerge: installed-base leverage through recurring reagent revenue, and point-of-care platform extension beyond centralized laboratories. Competitive moves concentrate on exclusive supplier arrangements with regional hub consolidators and parallel regulatory pathway optimization across FDA and EMA frameworks.
Among US-based laboratory service networks, Laboratory Corporation of America Holdings, Quest Diagnostics, and Mayo Clinic Laboratories occupy positions as volume aggregators that dictate reagent procurement terms for high-throughput antiphospholipid syndrome screening. These entities exemplify the reference laboratory archetype where throughput economics and regulatory accreditation requirements create durable supplier relationships. Within the instrumentation tier, European manufacturers anchor positions through automated platform ecosystems that capture capital replacement cycles.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| ARUP Laboratories |
| Mayo Clinic Laboratories |
| Quest Diagnostics |
| Precision Biologics |
| Diagnostica Stago |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Becton Dickinson |
| Others |
Supply & Pricing Matrix
Purified phospholipid supply concentration in Germany and Switzerland anchors margin pools downstream in reagent kit manufacturing, where FDA Clinical Laboratory Improvement Amendments compliance costs create tiered pricing separation between accredited reference laboratories and mid-sized hospital labs.
Pricing Analysis
FDA Clinical Laboratory Improvement Amendments dictates the pricing tier structure across the lupus anticoagulant testing landscape. Three-tier pricing structure across premium, standard, and economy levels separates high-complexity reference laboratories with STAT-capable analyzers from mid-sized hospitals running batch-processed workflows. Cost compression in economy-tier manual assay methods is intensifying because specialized coagulation technologist shortages force labor cost premiums. Diagnostic labs with exclusive supplier arrangements command least price sensitivity, while independent laboratories facing consolidation pressure exhibit highest procurement negotiation leverage.
Supply Chain Analysis
Contract manufacturing concentration for hemostasis analyzers rests with Swiss and Japanese industrial zones, where precision instrumentation assembly feeds global distribution networks. Purified phospholipid formulations draw from specialized chemical suppliers in Germany and the United States, while automated platform components source from Japanese precision electronics clusters. Single-source vulnerability in phospholipid-dependent reagent inputs creates structural exposure to input cost volatility. Distribution runs through European hospital alliance procurement hubs and United States integrated delivery network regional consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in lupus anticoagulant testing centers on analyzer-reagent ecosystem interoperability, where installed-base leverage through recurring consumable revenue is displacing standalone capital equipment sales.
For Market Incumbents: Insulate recurring reagent revenue streams by embedding hexagonal phase phospholipid neutralization protocols into exclusive service contracts with consolidating United States integrated delivery networks. Extend backward integration into purified phospholipid manufacturing to buffer margin compression from specialized chemical supplier constraints. Counter point-of-care platform entrants by anchoring STAT-capable analyzer placements in academic medical center emergency departments. For New Entrants and Emerging Players: Pursue white-space placement in anticoagulation clinic point-of-care channels, where rheumatology practices seek rapid turnaround outside centralized laboratory workflows. Target mid-sized German hospitals replacing manual dRVVT methods as the most penetrable automation upgrade segment. Deploy lateral flow immunoassay technology as the go-to-market angle for decentralized testing expansion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic service networks consolidating reference laboratory capacity in Texas and California regional hubs. Five-to-ten year viability hinges on exclusive supplier arrangement durability within integrated delivery network procurement structures. Monitor EMA-notified body conformity assessment timeline compression as the signal to watch for European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Manufacturing Backward Integration | In-house phospholipid production reduces exposure to German chemical supplier concentration. |
| Point-of-Care Platform Launch | Emergency department placement extends testing beyond centralized laboratory infrastructure. |
| Hospital System Partnership | Exclusive supplier arrangements with Bavarian academic medical centers lock in recurring revenue. |
| CE Marking Pathway Optimization | Parallel FDA de novo classification accelerates European market entry timelines. |
| Software Companion Development | Integrated analyzer-LIS connectivity addresses mid-sized hospital workflow disruption concerns. |
Research Methodology
A spread of perspectives from hemostasis laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA notified body conformity assessments, Clinical Laboratory Improvement Amendments proficiency testing records, and hospital procurement databases. Bottom-up test volume modeling and top-down reagent revenue triangulation anchored market size estimation.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type, end user category, technology platform, and application urgency tier. CAGRs derived from installed base replacement cycles and reagent consumption intensity curves modeled over the projection horizon. Antiphospholipid syndrome screening protocol adoption rates and EU In Vitro Diagnostic Regulation compliance cost trajectories informed forecast sensitivity ranges.
Sensitivities concentrate around phospholipid input cost volatility, specialized technologist training pipeline constraints, and integrated delivery network procurement consolidation velocity. Forecasts reflect assumptions about analyzer replacement cycle timing and reference laboratory accreditation consolidation patterns. Quarterly review of FDA proficiency testing mandate enforcement intensity and European hospital alliance contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Cell Free DNA Testing Market