
 Australia Facial Injectable Market | 2026-2036
Australia Facial Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Facial Injectable Market Intelligence
AHPRA registration and the Medical Board of Australia's cosmetic medicine standards is redrawing competitive boundaries in who may administer facial injectables. Allergan Aesthetics leverages its Botox portfolio to dominate the botulinum toxin segment across dermatology clinics. Galderma sustains its position through hyaluronic acid filler specialization and direct practitioner training programs. Merz Aesthetics anchors its presence with differentiated calcium hydroxylapatite formulations targeting facial contouring applications.
Facial injectables comprise sterile biocompatible substances administered subcutaneously or intramuscularly to modify soft tissue structure, employing formulations with particle sizes ranging from 200 to 1,000 micrometers depending on volumizing or wrinkle-reduction intent. Their primary commercial purpose centers on non-surgical aesthetic enhancement with minimal recovery intervals. Hyaluronic acid products lead volume due to reversible action and broad indication coverage, while botulinum toxin commands premium positioning in wrinkle reduction protocols. Poly-L-lactic acid competes in the facial contouring segment where collagen biostimulation drives longer treatment intervals and higher per-session economics.
TGA oversees product registration and post-market surveillance for all facial injectables entering Australian distribution, while AHPRA governs practitioner scope and advertising restrictions that directly constrain clinic expansion models. The Medical Board of Australia's cosmetic medicine guidelines mandate specific training thresholds and informed consent documentation that shape patient acquisition costs and liability structures. Stakeholders must monitor evolving TGA reclassification deliberations for longer-duration fillers and anticipate how AHPRA advertising enforcement against before-and-after imagery will redirect clinic marketing investment toward practitioner credentialing and patient education platforms.
Market Dynamics
AHPRA's tightening cosmetic medicine standards are redrawing practitioner eligibility boundaries, forcing clinic operators to restructure staffing models and training investment timelines. This regulatory compression is the dominant force reshaping competitive access across New South Wales and Victoria.
Growth Catalysts
- Medical Board of Australia Guidelines:Mandatory training thresholds elevate practitioner credential quality, reducing adverse event liability and strengthening patient trust in clinic brands.
- Metropolitan Clinic Density:Sydney and Melbourne's concentrated dermatology and cosmetic surgery networks create referral ecosystems that accelerate patient acquisition for injectable services.
- Hyaluronic Acid Reversibility:The enzymatic dissolution capability of HA fillers reduces treatment anxiety among first-time patients, expanding addressable demand beyond traditional cosmetic surgery candidates.
Market Restraints
- TGA Registration Timelines:Extended product approval cycles for novel botulinum toxin formulations delay market entry for international manufacturers, preserving incumbent positioning.
- Practitioner Supply Concentration:AHPRA-registered cosmetic physicians cluster disproportionately in eastern seaboard capitals, constraining service expansion into Perth, Adelaide, and regional Queensland.
- Allogeneic Biostimulator Limitations:Poly-L-lactic acid's delayed onset of action and requirement for multiple sessions creates treatment abandonment risk compared to immediate-result alternatives.
Strategic Opportunities
- Queensland and Western Australia Penetration:Brisbane and Perth exhibit clinic-per-capita deficits relative to Sydney and Melbourne, presenting whitespace for compliant operators.
- Men's Aesthetic Segment:Jawline contouring and masseter reduction applications for male patients remain underdeveloped relative to female-targeted wrinkle protocols.
- Direct Practitioner Training Platforms:Manufacturer-sponsored education programs bypass traditional medical college pathways, accelerating credential acquisition for regional GPs transitioning into cosmetic medicine.
Industry Challenges
- AHPRA Advertising Enforcement:Restrictions on before-and-after imagery and testimonial content force clinics to rebuild digital marketing strategies around practitioner biography and educational content.
- Informed Consent Documentation Burden:Medical Board of Australia requirements for procedure-specific consent forms increase administrative overhead and consultation duration, compressing daily patient throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Facial Injectable Market |
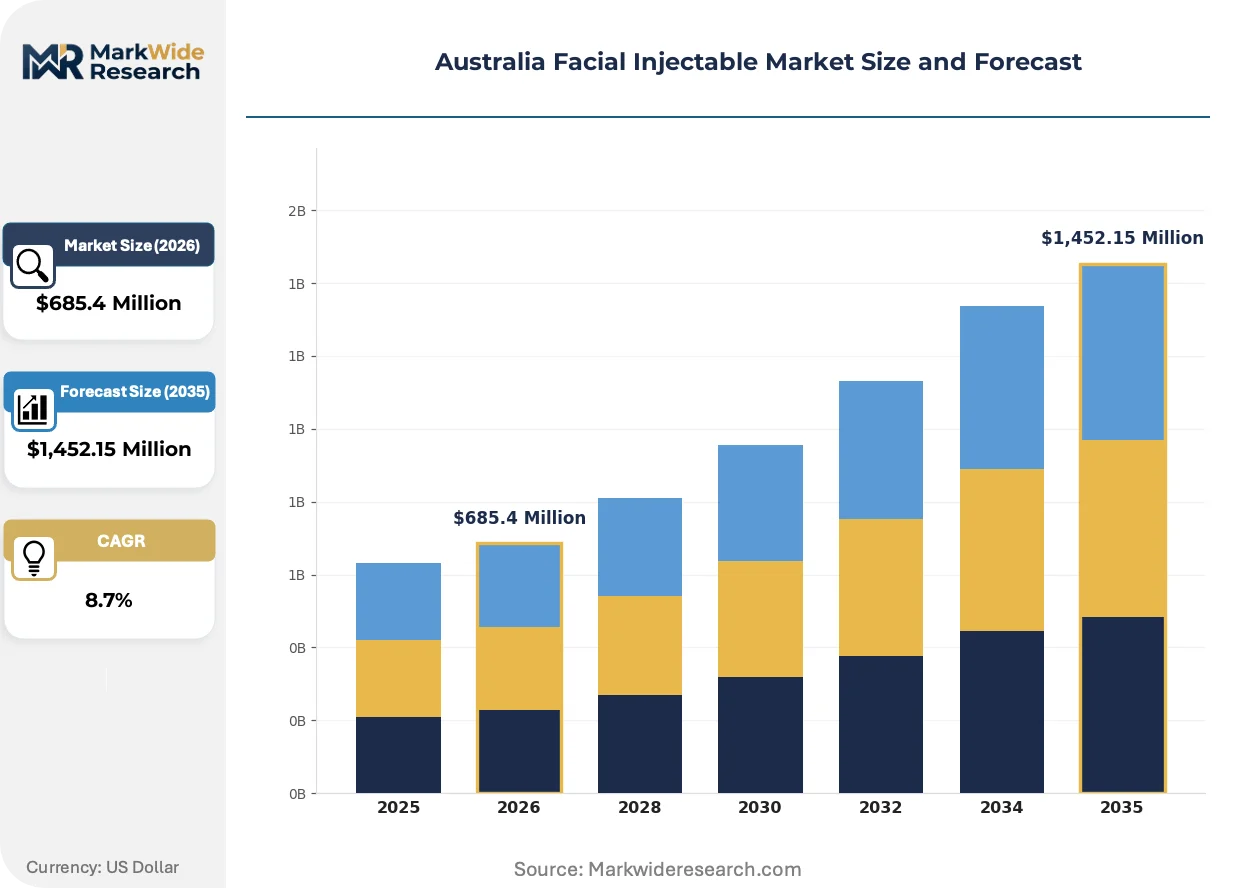
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-Lactic Acid End User: Dermatology Clinics, Aesthetic Centers, Hospitals, Medical Spas Application: Wrinkle Reduction, Lip Augmentation, Facial Contouring, Scar Treatment Injection Site: Forehead, Cheeks, Lips, Jawline |
| Companies Covered | Allergan Aesthetics, Galderma, Merz Aesthetics, Teoxane Laboratories, Sinclair Pharma, AbbVie, Prollenium Medical Technologies, Medytox, LG Chem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Facial Injectable Market Strategic Shifts & Innovations
Injectable formulation science and patient acquisition channels are diverging simultaneously, with product differentiation strategies and regulatory compliance requirements pulling clinic investment in competing directions. These forces are fragmenting how value is captured across the treatment journey.
Microsphere and cross-linking technology is fragmenting the hyaluronic acid filler landscape into viscosity-specific subcategories optimized for distinct facial planes. Dermatology clinics in Sydney are adopting five-plus distinct product lines where three sufficed previously. This specialization is fragmenting inventory management and practitioner training requirements while compressing margin per syringe through product proliferation.
TGA's post-market surveillance expansion for longer-duration fillers is extending adverse event reporting obligations from manufacturers to clinic operators. The regulator's reclassification deliberations for collagen biostimulators are forcing product sponsors to submit additional safety data. Dermatology networks are responding by centralizing complication documentation and strengthening indemnity coverage before the framework finalizes.
Patient education platforms are displacing traditional referral networks as the primary patient acquisition channel for metropolitan clinics. Instagram and TikTok content featuring practitioner credentialing rather than treatment outcomes is redirecting marketing spend from display advertising toward video production and compliance review. This shift is most visible in Melbourne's competitive inner-suburban corridors where clinic density exceeds 15 per square kilometer.
Australia Facial Injectable Market Segmentation
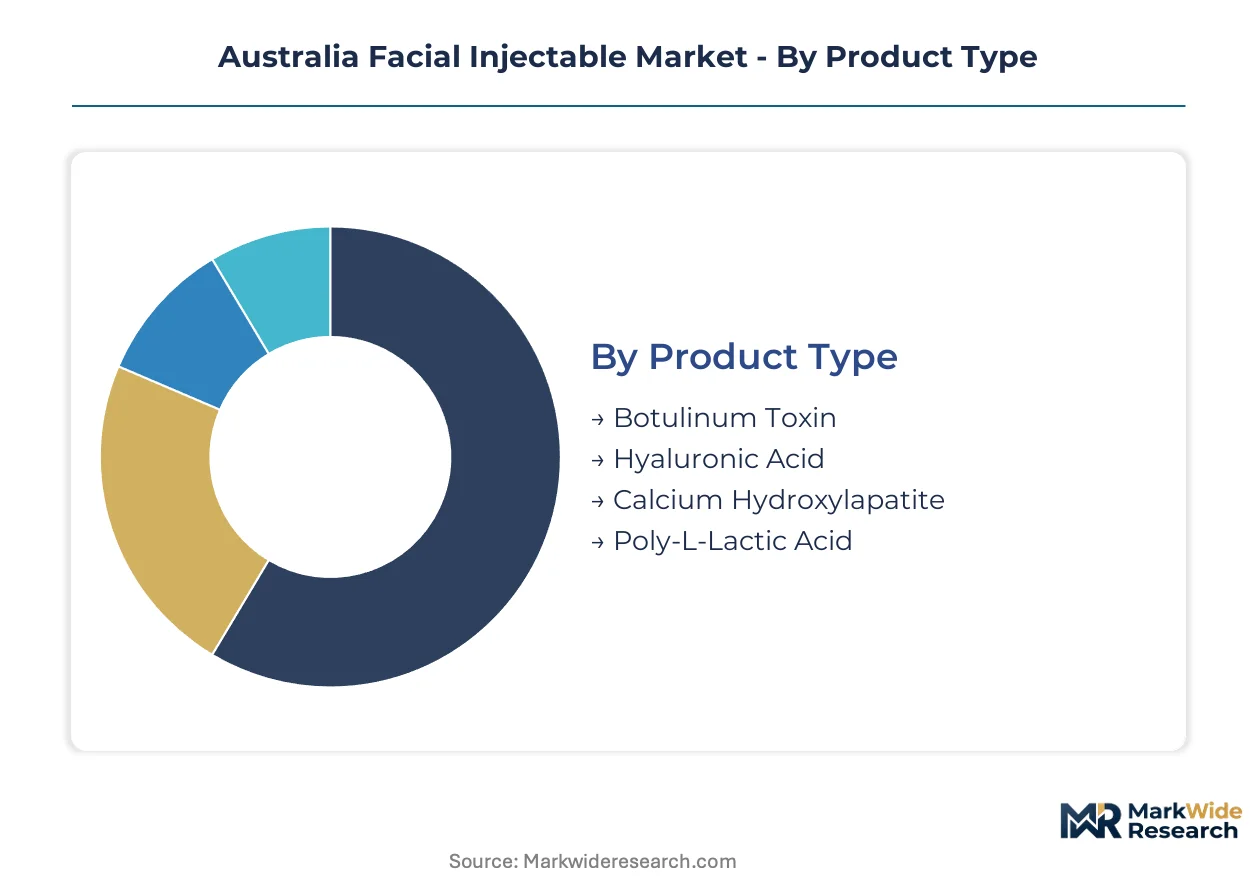
Product differentiation and practitioner specialization fragment the Australia Facial Injectable Market into distinct commercial zones. Each segmentation axis reveals where margin concentrates and how regulatory compliance reshapes competitive positioning across Sydney, Melbourne, and emerging state markets.
Product Type:
Margin pools concentrate in reversible formulations where practitioner liability exposure and patient retention economics align most favorably.
- Hyaluronic Acid:Cross-linked gel formulations with particle sizes calibrated to facial plane depth dominate volume throughput in New South Wales dermatology networks. The enzymatic reversal capability with hyaluronidase reduces informed consent friction and accelerates first-time patient conversion in Melbourne's saturated inner-suburban corridors.
- Botulinum Toxin:Purified neurotoxin complexes targeting neuromuscular junctions command premium per-unit economics despite standardized dosing protocols. Sydney medical spas bundle toxin with hydration therapies to lift average transaction value where standalone margins compress under AHPRA advertising restrictions.
- Calcium Hydroxylapatite:Microsphere suspensions in carboxymethylcellulose gel matrix target subdermal volumizing with longer duration than HA equivalents.
- Poly-L-Lactic Acid:Biostimulatory particles requiring reconstitution and multi-session protocols concentrate in facial contouring applications.
Hyaluronic Acid holds installed capacity. Botulinum Toxin is rotating up the share rankings.
End User:
Patient acquisition cost structures diverge sharply between institutional settings and independent practice models.
- Dermatology Clinics:Specialist-led facilities with AHPRA-registered cosmetic physicians anchor the highest-value segment through referral network integration and complication management credibility. These operators absorb TGA documentation burdens more efficiently than smaller competitors.
- Medical Spas:Nurse injector-led models with physician oversight are expanding service menus fastest in Queensland and Western Australia whitespace markets. Lower fixed cost bases enable aggressive pricing to capture patients from traditional clinic channels.
- Aesthetic Centers:Mixed specialty practices combining surgical and non-surgical services.
- Hospitals:Tertiary settings handling complex reconstructive cases and adverse event referrals.
Dermatology Clinics command premium positioning. Medical Spas are climbing the fastest.
Application:
Treatment complexity and session frequency determine how practitioners allocate product inventory across service lines.
- Wrinkle Reduction:Glabellar and crow's foot protocols utilizing botulinum toxin represent the highest-frequency indication with standardized technique. Melbourne clinic networks report this application as the entry point for male patient segments previously excluded from aesthetic services.
- Facial Contouring:Jawline definition and cheek volumizing applications demand higher product volumes per session and attract patients with greater price elasticity. Sydney operators target this segment to offset compressed margins on routine toxin maintenance.
- Lip Augmentation:Vermilion border and philtral column enhancement using hyaluronic acid fillers.
- Scar Treatment:Subcision combined with biostimulatory filler protocols for acne and traumatic scars.
Wrinkle Reduction maintains volume leadership. Facial Contouring is gaining share fastest.
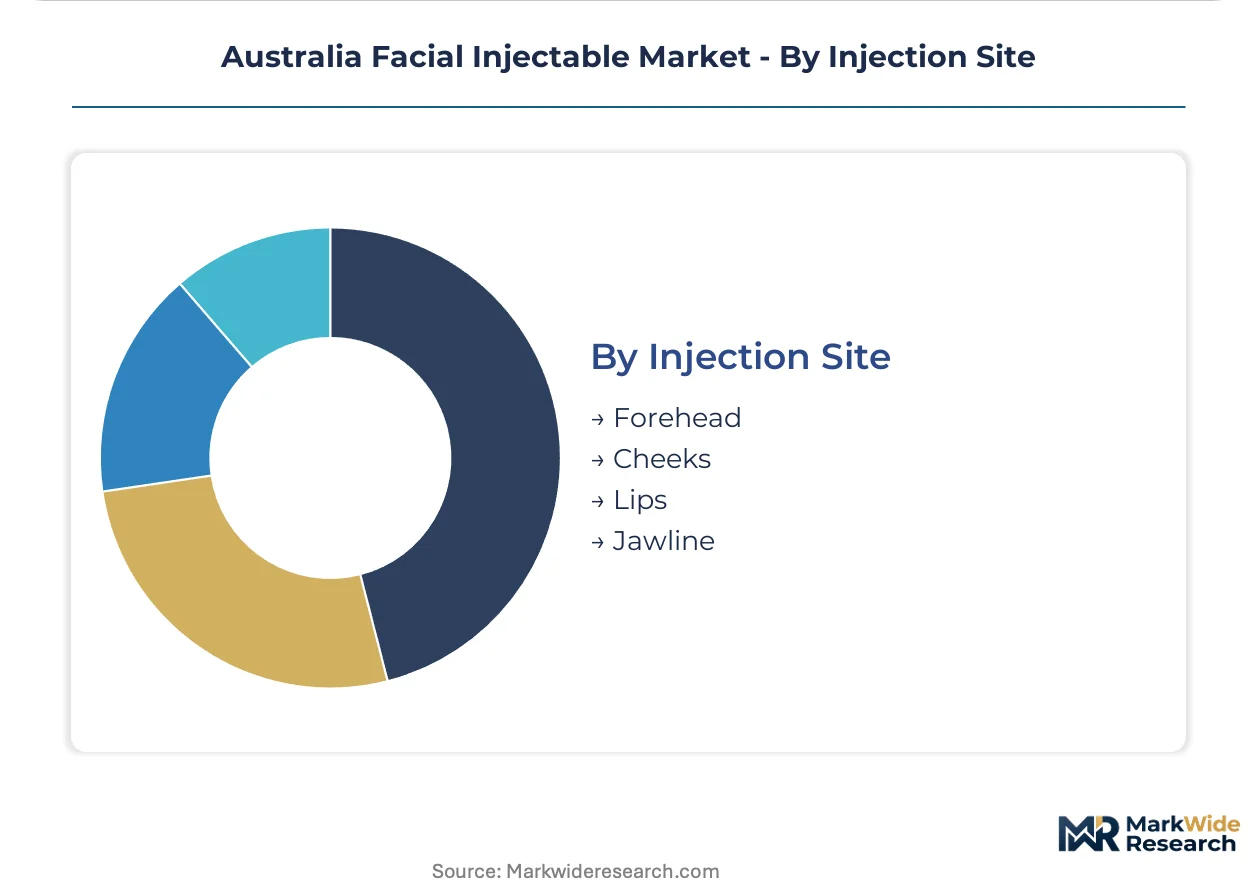
Injection Site:
Anatomical risk profiles and vascular complication potential shape practitioner training investment and indemnity coverage requirements.
- Forehead:Frontalis muscle targeting for horizontal rhytides carries lowest vascular risk and enables rapid patient turnover. AHPRA's cosmetic medicine guidelines emphasize this site in mandatory training curricula for new registrants.
- Jawline:Masseter reduction and mandibular angle definition require advanced anatomical knowledge given facial artery proximity. Perth clinics report this site as the primary driver of male patient acquisition where demand concentrates in professional services demographics.
- Cheeks:Malar and submalar volumizing with intermediate vessel risk profiles.
- Lips:Labial arteries and superior/inferior labial veins demand precise technique and aspiration protocols.
Forehead procedures hold installed capacity. Jawline applications are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA registration protocols and AHPRA practitioner standards are redistributing service capacity across Australian states, concentrating investment in compliant metropolitan networks while constraining regional expansion.
New South Wales
Sydney's dermatology corridor anchors the highest clinic density nationally, with AHPRA-registered cosmetic physicians clustering in eastern suburbs and North Shore medical precincts. TGA adverse event reporting obligations for longer-duration fillers have prompted Sydney networks to centralize complication documentation systems. The Sydney CBD and Bondi Junction medical hubs are absorbing displaced demand from non-compliant operators shuttered under tightened advertising enforcement.
Victoria
Melbourne's inner-suburban corridors exceed 15 injectable clinics per square kilometer, triggering price competition that compresses margin per syringe. The Medical Board of Australia's mandatory training thresholds have elevated credential quality among Melbourne practitioners, reducing liability premiums for compliant operators. South Yarra and Toorak aesthetic precincts are expanding service menus toward male-targeted jawline contouring applications.
Queensland
Brisbane exhibits clinic-per-capita deficits relative to southern capitals, presenting whitespace for AHPRA-compliant operators entering underdeveloped corridors. The state's health department has aligned with federal TGA surveillance protocols for biostimulatory filler adverse events. Gold Coast medical spas are expanding nurse injector-led models with physician oversight to capture price-sensitive segments.
Western Australia
Perth's professional services demographics are driving demand for male-targeted masseter reduction and mandibular angle definition protocols. AHPRA-registered cosmetic physician concentration lags eastern states, constraining service expansion into suburban and regional Western Australia. Subiaco and Perth CBD clinic clusters are targeting fly-in patients from mining sector employment centers.
Australia Facial Injectable Market Key Industry Players
Player mix skews toward multinational pharmaceutical manufacturers with established TGA registration pathways and dedicated practitioner education infrastructure. Market structure concentrates around three archetypes: legacy toxin specialists with dermatology network integration, hyaluronic acid formulators with reversible product positioning, and biostimulator innovators targeting collagen induction protocols. Competitive dynamics revolve around TGA product registration timelines and AHPRA-compliant training program sponsorship.
Within the multinational manufacturer tier, Allergan Aesthetics and Galderma exemplify divergent specialization strategies—toxin-centric versus filler-centric portfolios—while Merz Aesthetics occupies a position emphasizing calcium hydroxylapatite differentiation. These three anchors represent how TGA registration history and practitioner relationship depth determine competitive access in a regulatory environment that privileges incumbent compliance infrastructure over novel entrant speed.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Galderma |
| Merz Aesthetics |
| Teoxane Laboratories |
| Sinclair Pharma |
| AbbVie |
| Prollenium Medical Technologies |
| Medytox |
| LG Chem |
| Others |
Cost & Logistics Intelligence
TGA product registration tiers create simultaneous gates for supply qualification and price differentiation, with AHPRA-compliant practitioner training investments separating premium service delivery from commodity injection protocols. Manufacturers with established TGA pathways capture margin through certified product positioning while non-registered alternatives compete on acquisition cost alone.
Pricing Analysis
Certification level (TGA-registered versus unregistered imports) creates the primary spread between premium and economy tiers in the Australian market. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, reversal capability, and practitioner training bundling. Pricing pressure stems from AHPRA advertising restrictions that compress patient acquisition margins and force clinics toward lower-cost product alternatives. Medical spas exhibit highest price sensitivity due to nurse injector staffing models, while dermatology clinics with specialist physicians absorb premium positioning with lower volume elasticity.
Supply Chain Analysis
Switzerland and France anchor hyaluronic acid raw material fermentation and cross-linking technology for TGA-registered filler products entering Australian distribution. Botulinum toxin bulk drug substance concentrates in South Korean and Irish manufacturing facilities before fill-finish operations. Supply chain risk centers on single-source vulnerability for specialized cross-linking reagents and extended TGA approval timelines that delay product substitution. Distribution runs through manufacturer-direct sales forces to AHPRA-registered clinics, bypassing traditional pharmaceutical wholesale channels to maintain practitioner relationship control and training program integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AHPRA's tightening cosmetic medicine standards constitute a regulatory inflection that will consolidate market access around compliant operators while accelerating displacement of non-certified competitors. This disruption favors incumbents with established training infrastructure and threatens marginal players dependent on advertising-dependent patient acquisition.
For Market Incumbents: Secure TGA registration priority for next-generation biostimulatory formulations before reclassification deliberations finalize, and deepen practitioner training program sponsorship to lock in clinic loyalty against emerging Korean and Chinese manufacturers with faster regulatory pathways but weaker education infrastructure. Vertical integration into complication documentation software strengthens indemnity positioning as post-market surveillance obligations extend to clinic operators. For New Entrants and Emerging Players: Lead with direct-to-practitioner digital education platforms that bypass traditional medical college credentialing timelines, targeting regional Queensland and Western Australia where AHPRA-registered cosmetic physician density lags Sydney and Melbourne. The men's aesthetic segment—specifically jawline contouring and masseter reduction protocols—presents the most penetrable whitespace with underserved demand among professional services demographics in Perth and Brisbane. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents divesting aesthetic medicine divisions to refocus on core therapeutic portfolios, particularly filler-centric assets with TGA registration history but underexploited Australian distribution. Long-term viability hinges on regulatory compliance infrastructure rather than product innovation velocity, with acquisition premiums concentrating in targets with established AHPRA training partnerships. The signal to watch is TGA reclassification timing for collagen biostimulators, which would trigger safety data resubmission costs and consolidation pressure on smaller sponsors lacking regulatory affairs scale.| Strategic Initiative | Industry Significance |
|---|---|
| AHPRA-Compliant Training Program Expansion | Manufacturer-sponsored education accelerates regional GP credential acquisition outside Sydney-Melbourne corridor. |
| TGA Registration Priority for Biostimulators | Early submission before reclassification finalization preserves market access for longer-duration filler portfolios. |
| Complication Documentation Software Development | Centralized adverse event reporting satisfies TGA post-market surveillance expansion and reduces clinic indemnity premiums. |
| Male-Targeted Service Line Launch | Jawline contouring protocols capture underpenetrated professional services demographics in Perth and Brisbane. |
| Direct Distribution Channel Investment | Bypassing pharmaceutical wholesalers strengthens practitioner relationship control and training program integration. |
Research Approach
Desk research of TGA registration databases, AHPRA practitioner registers, and Medical Board of Australia guideline publications preceded structured interviews with cosmetic physicians, nurse injectors, clinic operations directors, and medical indemnity underwriters. Secondary validation drew from hospital procurement records, dermatology network service menus, and manufacturer training program disclosures. Bottom-up clinic capacity modeling and top-down product volume estimates were triangulated against TGA import data and practitioner registration growth trends.
Variance decomposition across product type, end-user setting, application indication, injection site, and state-level regulatory enforcement intensity shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and practitioner supply growth constraints. Forecast inputs included AHPRA registration trajectory projections, TGA approval pipeline status, and clinic density saturation thresholds in metropolitan versus regional markets.
The analysis sits within stated boundaries; outcomes outside sustained AHPRA enforcement intensity, stable TGA registration timelines, or continued metropolitan demand concentration would require recalibration. Forecasts reflect assumptions regarding regulatory compliance cost absorption and practitioner migration patterns from general practice into cosmetic medicine. Recalibration cycles align with material shifts in AHPRA advertising enforcement actions and TGA reclassification determinations for biostimulatory filler products.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Japan Facial Aesthetics Market