
 Europe Facial Injectable Market | 2026-2036
Europe Facial Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Facial Injectable Market Insights
Aftermarket service revenue from repeat injection scheduling and touch-up protocols is tilting margin pools away from one-time device sales toward recurring patient relationships. Galderma S.A. leverages its integrated training academy network to lock in clinic loyalty across Continental Europe. Allergan Aesthetics (AbbVie Inc.) anchors its position through exclusive loyalty programs that tie practitioner certification to product supply guarantees. Merz Pharma GmbH & Co. KGaA specializes in neurotoxin formulations that compete directly with established botulinum toxin platforms.
Europe facial injectables comprise sterile biocompatible formulations—hyaluronic acid cross-linked gels, botulinum toxin type A complexes, calcium hydroxylapatite microspheres, and poly-L-lactic acid suspensions—engineered for subcutaneous or intramuscular delivery to modify facial topography or muscular activity. These products function primarily as non-surgical alternatives to rhytidectomy, addressing glabellar lines, nasolabial folds, and mid-face volume depletion through minimally invasive office-based procedures. Hyaluronic acid products dominate current volume due to reversibility with hyaluronidase and immediate visual correction, while botulinum toxin generates the densest margin pools per treatment through high-frequency repeat cycles. Poly-L-lactic acid occupies a narrower position in collagen biostimulation for patients seeking gradual, longer-duration outcomes rather than instant volumization.
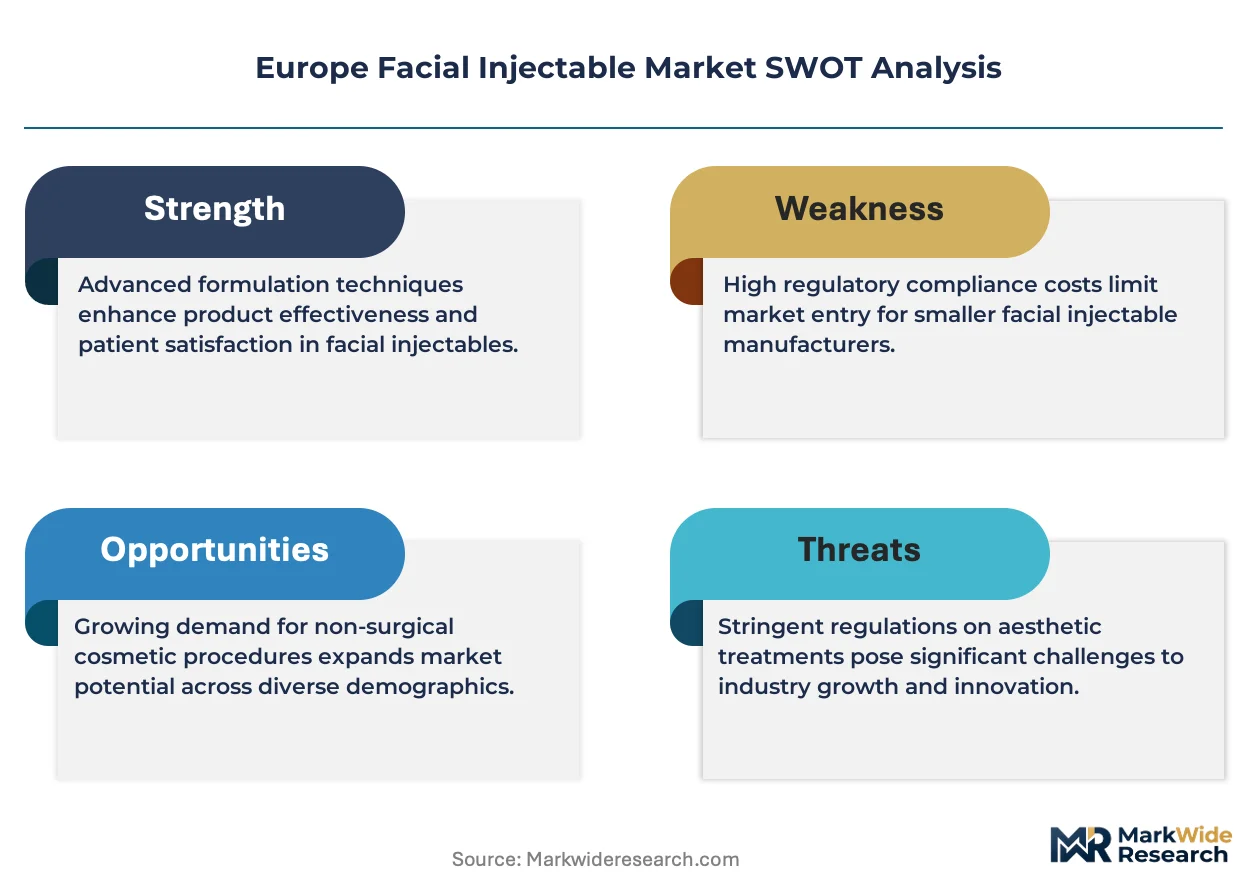
The EU Medical Device Regulation and CE marking framework administered by notified bodies in Germany, France, and the Netherlands shape product entry timelines and clinical evidence requirements for all non-toxin injectables. EMA oversight of botulinum toxin as a medicinal product creates a dual-track regulatory environment where manufacturers must navigate separate conformity pathways for toxin versus filler portfolios. Stakeholders must monitor how the EU AI Act intersects with emerging imaging-guided injection systems, as algorithmic facial analysis tools for treatment planning may trigger additional algorithmic risk classification requirements.
Market Dynamics
The EU Medical Device Regulation is compressing product entry timelines while metropolitan clinic chains concentrate purchasing power, fundamentally restructuring how manufacturers secure market access across Continental Europe.
Growth Catalysts
- MDR Clinical Evidence Requirements:The tightened pre-market clinical data mandates for hyaluronic acid formulations are elevating barriers that favor established portfolios with robust dossiers.
- Combination Protocol Adoption:Aesthetic clinics in Germany, France, and the United Kingdom are expanding service menus to include integrated toxin-filler treatment sequences.
- Paris Injectable Center Density:Dermatology chains in metropolitan France are constructing dedicated injectable facilities that concentrate trained practitioner pools.
Market Restraints
- Dual-Track Regulatory Friction:EMA oversight of botulinum toxin as a medicinal product alongside CE marking for fillers forces manufacturers to maintain separate conformity systems.
- Hyaluronidase Reversibility Dependency:The clinical expectation of immediate correction reversal for hyaluronic acid products constrains formulation innovation toward longer-duration alternatives.
- Notified Body Bottleneck:Concentration of MDR certification capacity in Germany, France, and the Netherlands creates submission queue delays extending product launch timelines.
Strategic Opportunities
- Eastern European Clinic Penetration:Poland, Czech Republic, and Romania exhibit underdeveloped aesthetic clinic density relative to Western European saturation levels.
- EU AI Act Imaging Integration:Algorithmic facial analysis tools for injection planning may trigger additional risk classification requirements that first-movers can shape.
- Collagen Biostimulation Positioning:Poly-L-lactic acid suspensions address patient segments seeking gradual volumization rather than immediate correction.
Industry Challenges
- Practitioner Certification Standardization:Divergent national training requirements across EU member states complicate pan-European rollout of manufacturer education programs.
- Supply Chain Reconfiguration:MDR economic operator obligations force restructuring of distributor relationships and post-market surveillance responsibilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Facial Injectable Market |
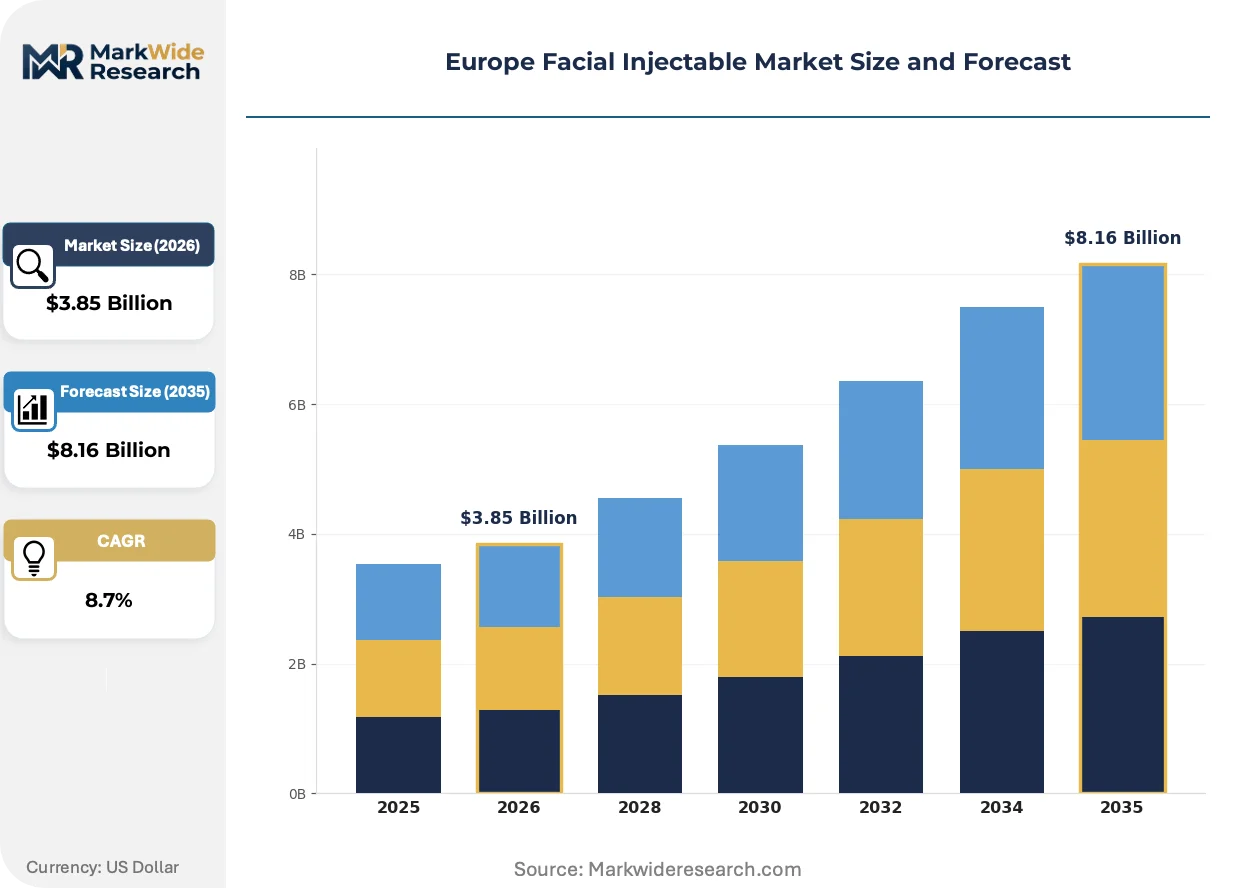
| Market Size in 2026 | $3.85 Billion |
| Market Size in 2035 | $8.16 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-Lactic Acid End User: Aesthetic Clinics, Dermatology Centers, Hospitals, Homecare Application: Facial Rejuvenation, Lip Augmentation, Wrinkle Treatment, Volume Restoration Delivery Mode: Injectable, Mini Needle, Cannula, Topical |
| Companies Covered | Galderma S.A., Allergan Aesthetics (AbbVie Inc.), Merz Pharma GmbH & Co. KGaA, Ipsen Pharma, Sinclair Pharma Ltd., Medytox Inc., Prollenium Medical Technologies Inc., Teoxane Laboratories, Revance Therapeutics, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Facial Injectable Market Trends and Innovations
Three intersecting developments are compressing traditional competitive advantages: imaging-guided injection systems, regulatory algorithm classification, and shifting clinic procurement consolidation.
High-resolution ultrasound and infrared mapping systems for real-time vascular avoidance during filler placement are rendering obsolete reliance on anatomical landmark knowledge alone. German and Swiss aesthetic clinics are deploying these systems at accelerating rates. The technology is rendering obsolete the historical premium commanded by practitioner experience in complication avoidance.
The EU AI Act intersects with emerging imaging-guided injection platforms as algorithmic facial analysis tools for treatment planning trigger additional risk classification requirements. Manufacturers must now navigate conformity assessment pathways for software-as-medical-device components alongside hardware. Paris-based dermatology chains are most affected, delaying rollout of AI-assisted planning modules pending notified body guidance.
Clinic procurement is consolidating toward multi-site chains that negotiate enterprise-level supply agreements replacing individual practitioner purchasing. Independent aesthetic clinics in the United Kingdom are losing price competitiveness to national chain networks. This concentration is most visible in London and Manchester, where three clinic groups now account for substantial neurotoxin volume.
Europe Facial Injectable Market Segmentation
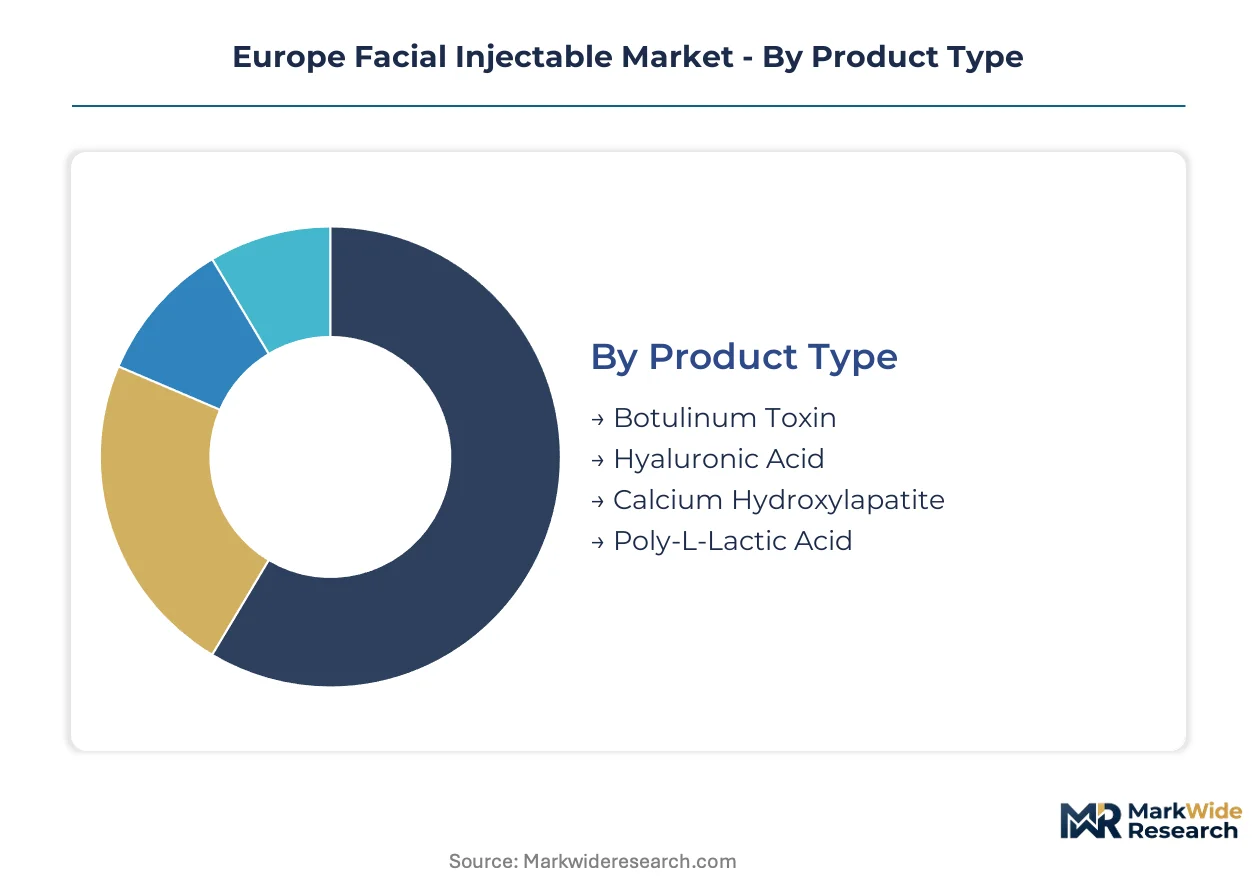
Segmentation in facial injectables reveals how formulation chemistry, clinical setting, and anatomical target interact to determine purchasing patterns across Continental Europe. Manufacturers configure product portfolios around these dimensions to align with MDR compliance pathways and clinic procurement consolidation.
Product Type:
Cost tier structures the competitive landscape, with reimbursement status and repeat purchase frequency creating divergent margin profiles across formulation categories.
- Hyaluronic Acid:Cross-linked bioresorbable gels deliver immediate volumetric correction with enzymatic reversibility via hyaluronidase. Paris-based dermatology chains prioritize these formulations for their liability profile and patient satisfaction metrics.
- Botulinum Toxin:Purified neurotoxin complexes interrupt neuromuscular signaling to reduce dynamic rhytides. German aesthetic clinics generate the densest per-patient revenue through quarterly injection cycles that lock in recurring appointments.
- Calcium Hydroxylapatite:Microsphere suspensions provide longer-duration correction through neocollagenesis stimulation. Demand concentrates in premium London clinics seeking differentiated outcomes.
- Poly-L-Lactic Acid:Biostimulatory colloids trigger gradual collagen deposition for patients accepting delayed gratification. French practitioners favor these for mid-face volumization in younger demographics.
Hyaluronic acid commands the established base. The steepest expansion runs through botulinum toxin protocols.
End User:
Customer type determines purchasing scale, with multi-site chains extracting volume discounts that independent operators cannot match.
- Aesthetic Clinics:Standalone and franchised facilities perform the majority of toxin and filler injections across Germany, France, and the United Kingdom. These operators negotiate enterprise supply agreements with manufacturers.
- Dermatology Centers:Physician-led practices in metropolitan France combine medical dermatology with cosmetic services, leveraging clinical credibility to justify premium pricing.
- Hospitals:Academic medical centers and private hospital groups handle complex reconstructive applications and complication management referrals.
- Homecare:Self-administered topical formulations occupy a marginal position, constrained by EMA safety oversight and practitioner liability concerns.
Dermatology centers anchor premium positioning. Aesthetic clinic chains are expanding most quickly through acquisition rollups.
Application:
Anatomical target shapes formulation selection, with perioral and mid-face zones requiring distinct rheological properties and injection techniques.
- Facial Rejuvenation:Comprehensive treatment protocols addressing multiple aesthetic units simultaneously. German clinics report strongest patient retention for these bundled service offerings.
- Wrinkle Treatment:Targeted glabellar and forehead line correction, historically the entry point for neurotoxin adoption across European markets.
- Lip Augmentation:Vermilion border and volume enhancement procedures, with hyaluronic acid dominating due to reversibility requirements.
- Volume Restoration:Mid-face and temple hollow correction, where poly-L-lactic acid competes against high-G' hyaluronic acid formulations.
Wrinkle treatment retains the largest procedure volume. Facial rejuvenation packages are gaining share fastest through combination protocol adoption.
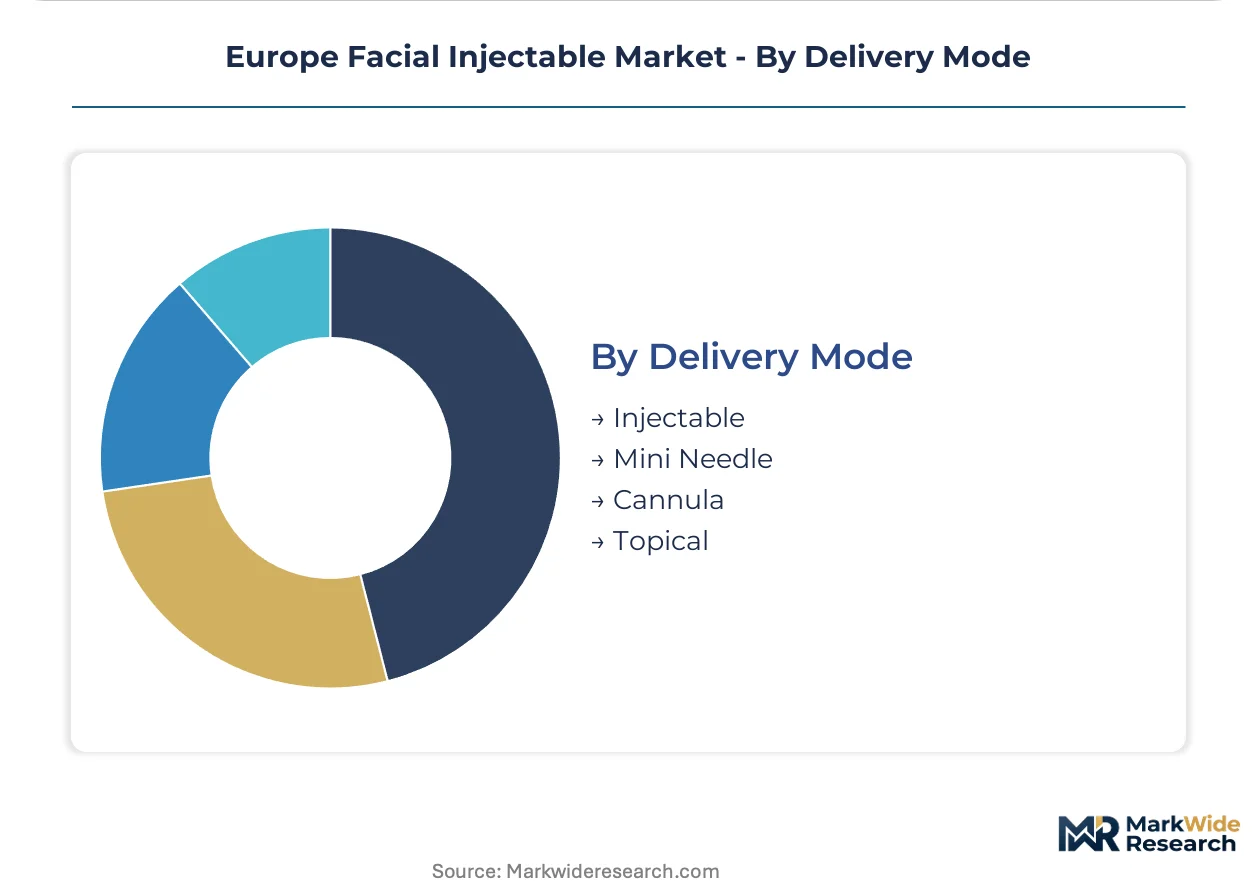
Delivery Mode:
Instrumentation sophistication influences practitioner training requirements and complication rates, with vascular avoidance technology reshaping competitive dynamics.
- Injectable:Standard syringe-based delivery with hypodermic needles, still dominant across Continental Europe due to cost accessibility.
- Cannula:Blunt-tipped instruments reducing vascular penetration risk. Swiss and German clinics lead adoption rates for filler placement safety.
- Mini Needle:Ultra-fine gauge systems for superficial dermal placement and reduced patient discomfort.
- Topical:Transdermal formulations with limited penetration, constrained by clinical efficacy expectations.
Standard injectable techniques command current practice patterns. Cannula adoption is climbing the fastest as imaging-guided systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing and clinical trial infrastructure for facial injectables concentrates in Germany, France, and Switzerland, with notified body capacity bottlenecks in these jurisdictions extending product launch timelines across Continental Europe.
Germany
Aesthetic clinic chains in Berlin, Munich, and Hamburg drive dense per-patient revenue through quarterly neurotoxin injection cycles. The German Federal Institute for Drugs and Medical Devices enforces stringent MDR clinical evidence requirements for hyaluronic acid formulations. The Rhine-Main cluster around Frankfurt anchors pharmaceutical manufacturing and notified body certification capacity for CE marking processes.
France
Paris-based dermatology chains are constructing dedicated injectable facilities that concentrate trained practitioner pools and premium pricing power. ANSM oversight of botulinum toxin as a medicinal product operates alongside CE marking frameworks for fillers. The Île-de-France region hosts the densest concentration of combination toxin-filler protocol adoption in Continental Europe.
United Kingdom
Independent aesthetic clinics in London and Manchester are losing price competitiveness to national chain networks negotiating enterprise-level supply agreements. The Medicines and Healthcare products Regulatory Agency maintains post-Brexit alignment with EMA standards for neurotoxin oversight. Greater London accounts for substantial neurotoxin volume through three dominant clinic groups.
Switzerland
Swiss aesthetic clinics lead Continental Europe in cannula adoption rates and imaging-guided injection system deployment for vascular avoidance. Swissmedic regulates both medicinal products and medical devices under unified frameworks that streamline conformity pathways. The Zurich-Geneva corridor concentrates high-resolution ultrasound system installation for real-time filler placement guidance.
Poland
Warsaw and Krakow exhibit underdeveloped aesthetic clinic density relative to Western European saturation levels, creating whitespace for manufacturer education program rollout. The Polish Office for Registration of Medicinal Products oversees botulinum toxin registration alongside EU MDR alignment for fillers. Polish clinic operators are expanding service menus to include integrated toxin-filler treatment sequences.
Europe Facial Injectable Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized aesthetic medicine firms split the market into distinct capability tiers. Consolidation pressures favor players with robust clinical dossiers navigating MDR evidence requirements. Three archetypes dominate: diversified dermatology portfolios with training academy networks, neurotoxin specialists competing on injection cycle frequency, and biostimulatory formulation developers targeting gradual volumization segments. Manufacturers defend position through exclusive loyalty programs tying practitioner certification to supply guarantees, while clinic procurement consolidation forces restructuring of distributor relationships.
Within the integrated pharmaceutical tier, Galderma S.A. and Allergan Aesthetics (AbbVie Inc.) exemplify archetypes combining product portfolios with captive education infrastructure. Merz Pharma GmbH & Co. KGaA occupies a position as a neurotoxin-focused developer competing against established botulinum platforms. These three entities represent the dominant competitive anchors across Continental Europe, with each sitting within distinct strategic postures around training network depth, loyalty program architecture, and formulation specialization.
| Leading Market Players |
|---|
| Galderma S.A. |
| Allergan Aesthetics (AbbVie Inc.) |
| Merz Pharma GmbH & Co. KGaA |
| Ipsen Pharma |
| Sinclair Pharma Ltd. |
| Medytox Inc. |
| Prollenium Medical Technologies Inc. |
| Teoxane Laboratories |
| Revance Therapeutics, Inc. |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main cluster around Frankfurt anchors pharmaceutical manufacturing and notified body certification capacity, concentrating upstream supply leverage that translates into tiered pricing power for hyaluronic acid and botulinum toxin formulations across downstream clinic networks.
Pricing Analysis
The EU Medical Device Regulation dictates the pricing tier structure across Continental Europe, separating CE-marked premium formulations from economy alternatives through clinical evidence dossier depth. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and practitioner training bundling. Cost compression in standard-tier hyaluronic acid intensifies because clinic procurement consolidation extracts volume discounts from distributors. Independent aesthetic clinics in the United Kingdom exhibit highest price sensitivity, while Paris-based dermatology chains command premium positioning through combination protocol bundling.
Supply Chain Analysis
Extended payment terms from German and Swiss manufacturers to clinic distributors compress working capital cycles and reshape procurement negotiation leverage. Manufacturing concentrates in Germany, France, and Switzerland, with sterile formulation filling drawing from pharmaceutical-grade hyaluronic acid feedstock, bacterial fermentation substrates for neurotoxin production, and medical-grade polymer resins. Single-source vulnerability runs through notified body certification queues in Germany, France, and the Netherlands. Distribution runs through manufacturer-direct sales forces serving multi-site clinic chains alongside specialized aesthetic distributors for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe facial injectables function as a service-attach market where repeat injection scheduling and touch-up protocols expand recurring revenue pools faster than one-time product sales.
For Market Incumbents: Entrench clinic loyalty through captive training academy networks that lock practitioner certification to product supply guarantees. Deepen backward integration into hyaluronic acid raw material production to offset feedstock cost volatility. Counter imaging-guided injection system vendors by embedding proprietary software modules within existing hardware partnerships. For New Entrants and Emerging Players: Pursue underdeveloped aesthetic clinic density in Poland, Czech Republic, and Romania where Western European saturation creates whitespace for education program rollout. Target dermatology center partnerships in metropolitan France as the most penetrable premium segment. Differentiate through poly-L-lactic acid biostimulation formulations addressing gradual volumization demand unmet by immediate-correction hyaluronic acid dominance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with robust MDR clinical dossiers navigating tightened evidence requirements. Long-term viability hinges on recurring revenue attachment rates rather than one-time device sales. Acquisition targets should demonstrate integrated training infrastructure and enterprise supply agreements with consolidating clinic chains. Watch imaging-guided injection system adoption curves as inflection indicator for commoditization risk in traditional formulation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Dossier Investment | CE marking pathways for hyaluronic acid formulations require expanded patient follow-up data under tightened notified body scrutiny. |
| Training Academy Network Expansion | Galderma's integrated education infrastructure locks clinic loyalty across Germany, France, and Switzerland through certification-tied supply guarantees. |
| Combination Protocol Development | Integrated toxin-filler treatment sequences in Paris dermatology chains drive higher per-patient revenue and appointment frequency. |
| Imaging-Guided System Partnership | Swiss and German clinic adoption of ultrasound-based vascular avoidance technology reshapes competitive dynamics away from practitioner experience premiums. |
| Eastern European Clinic Penetration | Polish and Czech Republic aesthetic clinic density lags Western European saturation, creating whitespace for manufacturer education program rollout. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA regulatory filings, notified body guidance documents, and clinic procurement databases across Germany, France, the United Kingdom, Switzerland, and Poland. Interviews with aesthetic clinic medical directors, dermatology chain procurement officers, pharmaceutical regulatory affairs leads, and distributor account managers inform demand-side dynamics. Bottom-up procedure volume estimates triangulate against top-down manufacturer shipment data and national pharmaceutical registry records.
Forecast inputs span formulation chemistry, clinical setting, anatomical application target, and delivery mode sophistication across the projection horizon. Modeled segmentation captures hyaluronic acid, botulinum toxin, calcium hydroxylapatite, and poly-L-lactic acid product categories alongside aesthetic clinic, dermatology center, and hospital end-user channels. CAGRs derive from procedure volume growth trajectories, pricing elasticity assumptions, and clinic penetration rate modeling. EU AI Act algorithmic risk classification timelines and MDR transition deadlines inform regulatory scenario inputs.
Sensitivities concentrate around notified body certification queue lengths, clinic procurement consolidation pace, and imaging-guided injection system adoption curves. Forecasts reflect documented assumptions regarding repeat injection frequency, practitioner training completion rates, and combination protocol uptake. Macroeconomic contraction affecting discretionary aesthetic spending, regulatory restriction on botulinum toxin advertising, or technological displacement by non-invasive alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market