
 Facial Injectables Market | 2026-2036
Facial Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Injectables Market Intelligence
Buyer concentration among dermatology clinics and medical spas is expanding as independent practices consolidate into multi-site aesthetic chains. AbbVie Inc. leverages its Allergan heritage to dominate the botulinum toxin segment with established clinician loyalty programs. Galderma SA anchors its position through dermal filler portfolios that span hyaluronic acid and calcium hydroxylapatite formulations. Merz Pharma differentiates via integrated training platforms that lock in provider preference across European and North American markets.
Facial injectables comprise sterile biologic and synthetic formulations delivered via needle or cannula to modify soft tissue structure, with botulinum toxin acting as a neuromodulator that blocks acetylcholine release at the neuromuscular junction to reduce dynamic rhytides. Dermal fillers restore volume through cross-linked hyaluronic acid or collagen-stimulating agents like poly-L-lactic acid, with gel particle size and cross-link density determining lift capacity and duration. Botulinum toxin commands the largest revenue pool due to repeat treatment cycles every three to four months, while poly-L-lactic acid represents the fastest-expanding category as collagen biostimulation gains traction among younger patients seeking preventive protocols. Wrinkle reduction remains the dominant application, though facial contouring using calcium hydroxylapatite is capturing margin-rich demand from patients seeking jawline definition without implant surgery.
The FDA enforces stringent biologics licensing requirements for botulinum toxin manufacturing that elevate compliance costs and deter commoditization. EMA's Medical Device Regulation reclassifies certain high-risk dermal fillers, imposing clinical evidence thresholds that reshape competitive access across European markets. South Korea's Ministry of Food and Drug Safety maintains accelerated approval pathways for domestic innovators, reinforcing Seoul's manufacturing cluster. Stakeholders must monitor how regulatory divergence between the FDA and EMA on biostimulator classification will fragment product registration strategies and reshape geographic prioritization for pipeline assets.
Market Dynamics
Clinician training platforms and certification ecosystems are locking in provider loyalty faster than product differentiation alone, concentrating purchasing power within multi-site aesthetic chains that negotiate consolidated supply contracts.
Growth Catalysts
- MFDS Accelerated Pathways:South Korea's streamlined biologics approvals for domestic manufacturers compress time-to-market for novel toxin formulations and reinforce Seoul's manufacturing cluster.
- Collagen Biostimulation Protocols:Poly-L-lactic acid demand among patients aged 25-35 seeking preventive treatments extends addressable patient lifetime value beyond traditional wrinkle correction.
- Medical Spa Channel Expansion:Non-physician supervised injection protocols in regulated jurisdictions broaden service accessibility and normalize maintenance treatment frequencies.
Market Restraints
- Botulinum Toxin Supply Concentration:Three manufacturers control bulk active pharmaceutical ingredient production, creating vulnerability to batch contamination or facility shutdown.
- EMA MDR Clinical Evidence Thresholds:Reclassification of high-risk dermal fillers mandates costly pre-market clinical trials that deter mid-tier competitors from European registration.
- Hyaluronic Acid Raw Material Volatility:Fermentation-based sodium hyaluronate supply fluctuates with pharmaceutical-grade glucose pricing and bioreactor capacity constraints.
Strategic Opportunities
- Men's Aesthetic Segment:Jawline contouring and masseter reduction protocols remain underpenetrated among male patients in North American and European metropolitan markets.
- Telehealth-Integrated Consultation Models:Remote pre-screening and treatment planning reduce clinic overhead while capturing patients in secondary and tertiary cities.
- Combination Therapy Protocols:Sequential neuromodulator and biostimulator administration creates service bundling opportunities with higher per-visit revenue capture.
Industry Challenges
- Injection Technique Standardization:Cannula versus needle approaches lack consensus guidelines, complicating training curriculum development and liability risk assessment.
- Adverse Event Documentation Burden:Mandatory biologics pharmacovigilance reporting for toxin products strains clinic administrative capacity and deters some providers from adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Injectables Market |
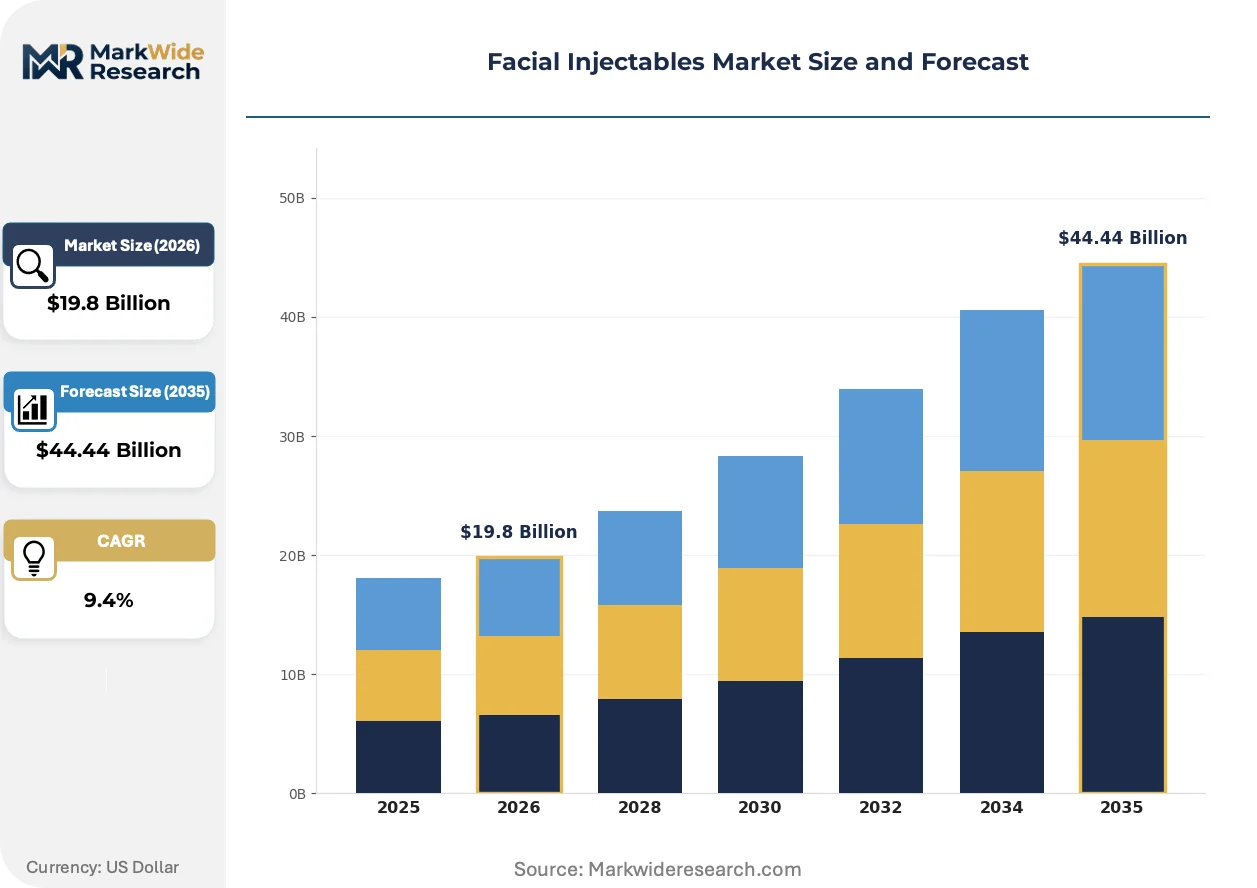
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $44.44 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Dermal Fillers, Calcium Hydroxylapatite, Poly-L-Lactic Acid Application: Wrinkle Reduction, Lip Augmentation, Facial Contouring, Scar Treatment End User: Medical Spas, Dermatology Clinics, Plastic Surgery Centers, Aesthetic Dentistry Clinics Distribution Channel: Direct Sales, Online Pharmacies, Specialist Distributors, Healthcare Retailers |
| Companies Covered | AbbVie Inc., Galderma SA, Merz Pharma, Ipsen SA, Revance Therapeutics Inc., Medytox Inc., Sinclair Pharma, Evolus Inc., Daewoong Pharmaceutical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Injectables Market Strategic Shifts & Innovations
Product development pipelines are pivoting toward longer-duration formulations and precision delivery systems that reduce treatment frequency while improving anatomical targeting accuracy.
Micro-dosing protocols for botulinum toxin are rewriting treatment paradigms across forehead and periorbital applications. Aesthetic practitioners in high-volume metropolitan clinics are adopting these lower-unit approaches to preserve natural facial expression. The technique is compressing average units per patient while expanding total patient throughput and reducing adverse event rates.
EMA's Medical Device Regulation implementation continues reshaping competitive access across European markets. High-risk dermal filler reclassification imposes clinical evidence thresholds that legacy products struggle to satisfy. Smaller manufacturers are withdrawing from the CE-marking process rather than absorbing trial costs, consolidating shelf presence among established portfolios.
Subscription-based maintenance programs are displacing episodic fee-for-service models in premium clinic segments. Patients in Seoul, Los Angeles, and London lock in quarterly treatment schedules through prepaid annual plans. The shift reduces appointment attrition and smooths revenue predictability for multi-site operators.
Facial Injectables Market Segmentation
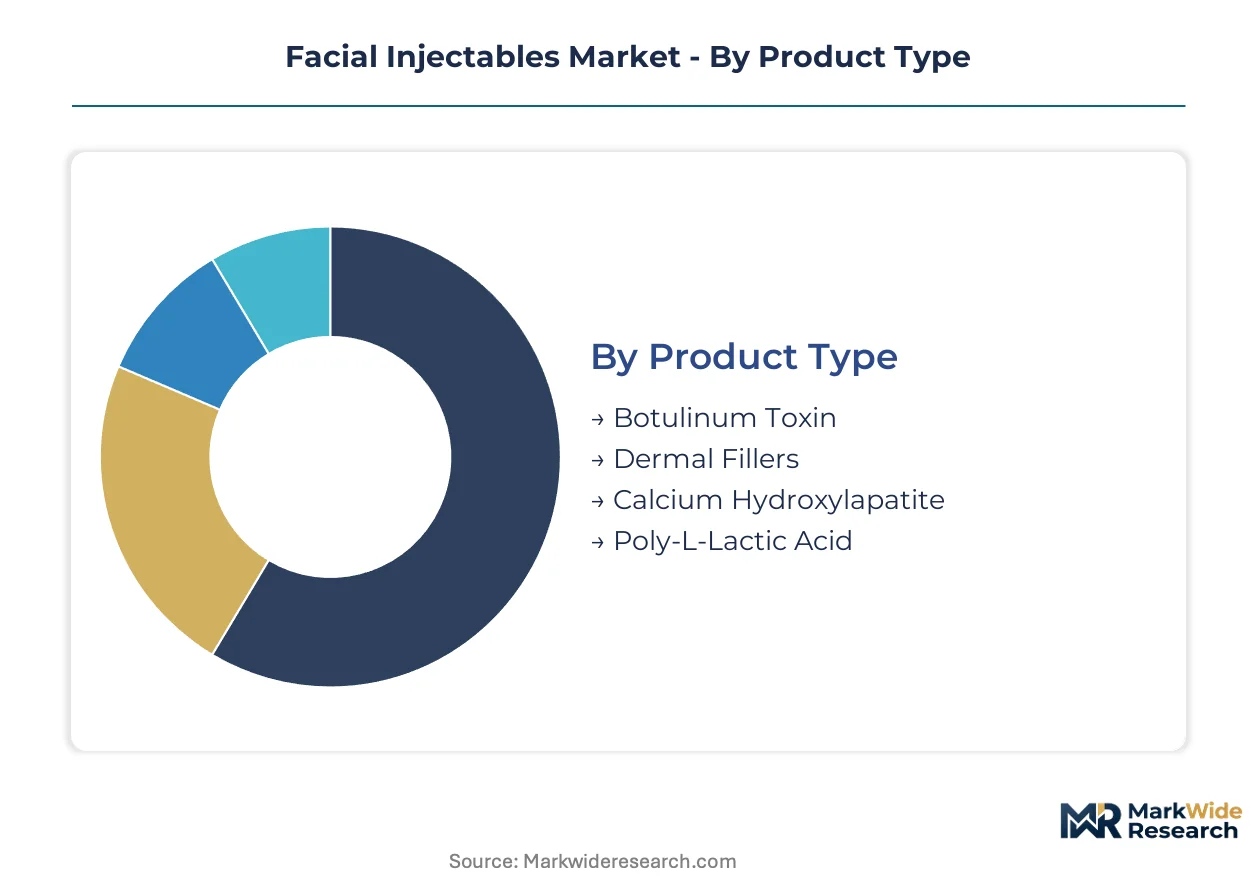
Facial injectables demand fragments across distinct product chemistries, anatomical applications, and clinical settings. Each segmentation axis reveals divergent margin structures, regulatory burdens, and purchasing behaviors that reshape competitive priorities.
Product Type:
Botulinum toxin captures volume leadership through repeat treatment cycles, while biostimulators command premium positioning per procedure.
- Botulinum Toxin:Purified neurotoxin formulations block acetylcholine release at neuromuscular junctions to soften dynamic rhytides. Demand concentrates in Seoul and Los Angeles metropolitan corridors where medical tourism infrastructure and celebrity influence normalize quarterly maintenance protocols.
- Dermal Fillers:Cross-linked hyaluronic acid gels restore subcutaneous volume through physical displacement and hydrophilic expansion. Dermatology clinics in Germany and France prioritize these formulations for perioral rejuvenation, though EMA MDR reclassification elevates clinical evidence costs for new entrants.
- Calcium Hydroxylapatite:Synthetic bone mineral microspheres suspended in carboxymethylcellulose gel provide structural scaffolding for jawline definition.
- Poly-L-Lactic Acid:Bioresorbable polymer microparticles stimulate neocollagenesis through foreign body response mechanisms.
Today's leader: Botulinum Toxin. Tomorrow's challenger: Poly-L-Lactic Acid.
Application:
Wrinkle correction anchors reimbursement familiarity, yet contouring applications unlock out-of-pocket spending elasticity.
- Wrinkle Reduction:Forehead glabellar lines and crow's feet represent the most codified injection protocols with established CPT coding. Medical spas in Miami and Dallas leverage these familiar procedures to acquire first-time aesthetic patients before upselling combination therapies.
- Facial Contouring:Mandibular angle augmentation and cheek volumization require advanced cannula techniques and anatomical precision. Plastic surgery centers in São Paulo and Mexico City capture premium pricing for these technically demanding procedures that bridge injectable and surgical aesthetics.
- Lip Augmentation:Vermillion border definition and philtral column enhancement using hyaluronic acid fillers.
- Scar Treatment:Subcision combined with filler deposition for acne and traumatic scar revision.
Wrinkle reduction generates procedure volume; facial contouring captures margin expansion.
End User:
Channel consolidation favors multi-site operators with centralized procurement leverage over independent single-location practices.
- Dermatology Clinics:Board-certified dermatologists command patient trust for complex periorbital and forehead applications requiring adverse event management capability. Chains like those expanding across Texas and Florida negotiate consolidated supply contracts that compress per-unit acquisition costs below independent practice benchmarks.
- Medical Spas:Non-physician supervised injection protocols in regulated states broaden service accessibility. California and New York jurisdictions with expanded scope-of-practice rules for nurse practitioners and physician assistants drive treatment frequency normalization through membership models.
- Plastic Surgery Centers:Hybrid surgical-injectable practices capture pre- and post-operative aesthetic maintenance.
- Aesthetic Dentistry Clinics:Oral and maxillofacial specialists leverage existing patient relationships for perioral rejuvenation.
Dermatology clinics hold purchasing power concentration; medical spas represent the steepest expansion trajectory.
Distribution Channel:
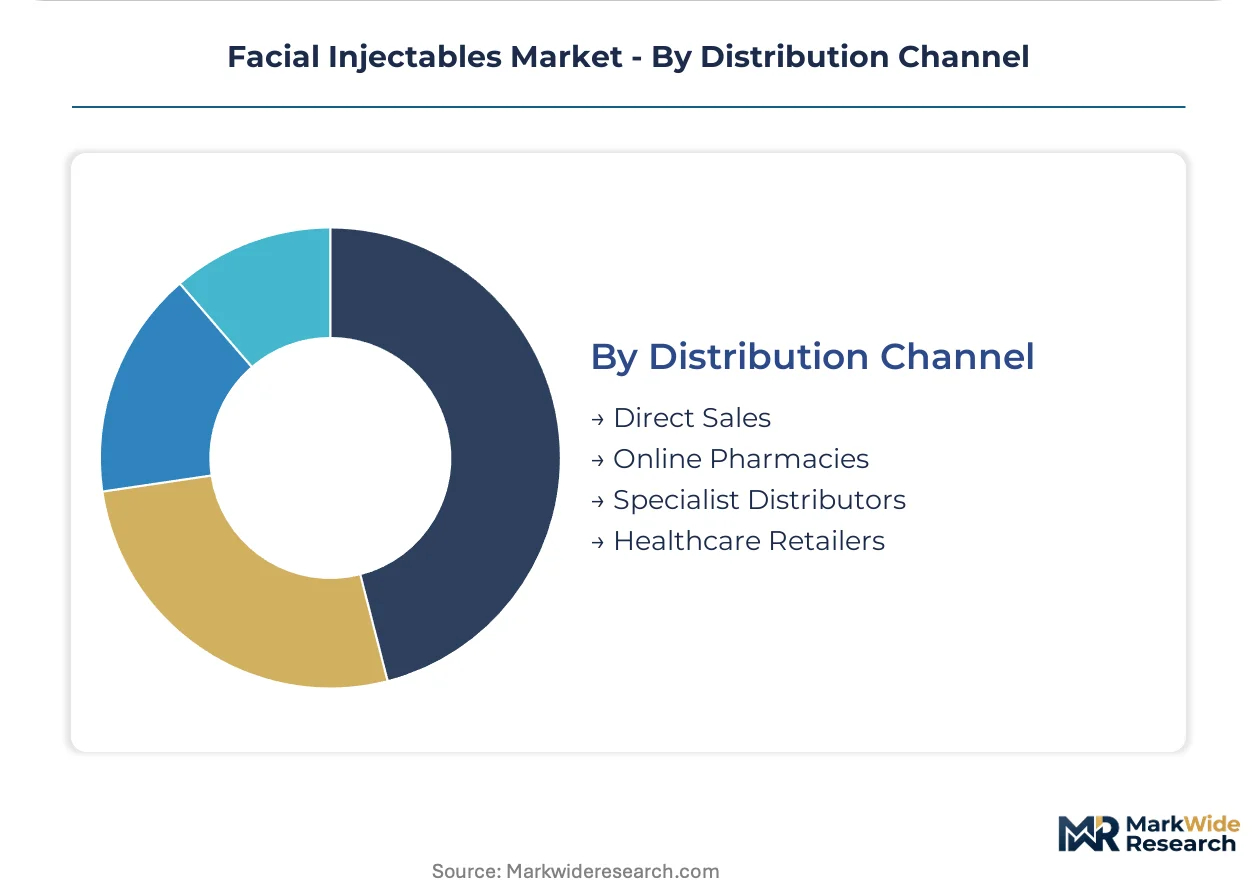
Direct relationships dominate high-value toxin procurement, while digital channels fragment filler purchasing.
- Direct Sales:Manufacturer field forces cultivate clinician loyalty through training certification and volume rebate structures. AbbVie and Galderma deploy dedicated aesthetic specialists to high-volume accounts in Chicago, London, and Sydney who control formulary decisions across 15-plus location networks.
- Specialist Distributors:Regional medical aesthetics wholesalers buffer inventory for mid-tier clinics lacking cold-chain logistics infrastructure. These intermediaries concentrate in secondary US markets and Southern European regions where fragmented provider landscapes resist direct manufacturer engagement economics.
- Online Pharmacies:E-commerce platforms facilitate filler procurement for established accounts with credit terms.
- Healthcare Retailers:Pharmacy chains with clinical service extensions capture consumer-directed skin booster demand.
Direct sales lock in the toxin segment; specialist distributors defend filler access in fragmented markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified dermatologists and aesthetic nurse practitioners cluster in metropolitan corridors where disposable income density supports premium service pricing. Seoul, Los Angeles, and London anchor the highest treatment frequencies per capita. Regulatory divergence between the FDA, EMA, and MFDS fragments product registration strategies across these talent hubs.
United States
Medical spa chains in Texas and Florida normalize quarterly maintenance protocols through membership models. The FDA enforces stringent biologics licensing requirements for botulinum toxin manufacturing that elevate compliance costs. Chicago and Dallas host concentrated purchasing power among 15-plus location networks negotiating consolidated supply contracts.
South Korea
Domestic manufacturers leverage Seoul's medical tourism infrastructure to capture inbound aesthetic patients from across Asia. The MFDS maintains accelerated approval pathways for novel toxin formulations that compress time-to-market. Busan-Ulsan anchors manufacturing clusters where fermentation-based sodium hyaluronate production faces bioreactor capacity constraints.
Germany
Dermatology clinics in Munich and Frankfurt prioritize hyaluronic acid formulations for perioral rejuvenation among aging demographics. The EMA's Medical Device Regulation reclassifies high-risk dermal fillers, imposing clinical evidence thresholds that reshape competitive access. Baden-Württemberg hosts specialist distributors buffering inventory for mid-tier practices lacking cold-chain logistics.
Brazil
Plastic surgery centers in São Paulo capture premium pricing for mandibular angle augmentation using technically demanding cannula techniques. ANVISA registration timelines lag European and North American approvals, creating parallel market dynamics. Rio de Janeiro's hybrid surgical-injectable practices lock in pre- and post-operative aesthetic maintenance revenue streams.
United Kingdom
London aesthetic chains displace episodic fee-for-service models with prepaid annual subscription plans. The MHRA post-Brexit regulatory divergence from EMA MDR creates distinct registration pathways for biostimulator products. Harley Street concentration of board-certified practitioners commands patient trust for complex periorbital applications.
Facial Injectables Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across product chemistry boundaries. The vendor base stratifies into three tiers: legacy pharmaceutical conglomerates with aesthetic divisions, mid-cap dermal filler specialists, and emerging toxin innovators from Asian manufacturing clusters. Consolidation pressure intensifies as multi-site clinic chains demand volume rebate structures that favor scaled suppliers. Dominant competitive moves include clinician training platform investments and direct sales force expansion into secondary metropolitan markets.
Within the legacy pharmaceutical tier, AbbVie Inc. exemplifies conglomerate diversification into aesthetic medicine through its Allergan heritage. Galderma SA anchors the mid-cap specialist position with cross-linked formulation portfolios spanning multiple chemistries. Merz Pharma occupies the integrated training platform vector, locking in provider preference through certification ecosystems. These three entities represent divergent strategic archetypes: conglomerate leverage, formulation breadth, and service lock-in respectively.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Galderma SA |
| Merz Pharma |
| Ipsen SA |
| Revance Therapeutics Inc. |
| Medytox Inc. |
| Sinclair Pharma |
| Evolus Inc. |
| Daewoong Pharmaceutical Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up aesthetic clinic chains in Texas and Florida anchor purchasing power concentration, compressing per-unit acquisition costs through consolidated supply contracts while forcing manufacturers to absorb cold-chain logistics expenses rather than pass through to high-volume accounts.
Pricing Analysis
Bundled subscription models for quarterly toxin maintenance now compete against unbundled per-procedure pricing across metropolitan markets. Three-tier pricing structure across premium, standard, and economy levels separates board-certified dermatologist protocols from medical spa nurse practitioner services and telehealth-integrated consultation tiers. Pricing pressure stems from multi-site chains demanding volume rebates that erode list-price realization. Medical spas exhibit highest price sensitivity due to non-physician supervision constraints and membership-model cash flow pressures.
Supply Chain Analysis
Workforce availability constraints in South Korea's Busan-Ulsan corridor and Germany's Baden-Württemberg region limit fermentation-based sodium hyaluronate batch expansion despite bioreactor capacity investments. Active pharmaceutical ingredient production concentrates in South Korea, Ireland, and the United States, drawing from pharmaceutical-grade glucose and specialized bacterial strain repositories. Single-source vulnerability for bulk botulinum toxin fermentation creates exposure to facility contamination events. Distribution runs through direct manufacturer field forces for toxin procurement, with specialist distributors buffering filler inventory for mid-tier clinics lacking cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facial injectables market operates as a regulatory compounder where EMA MDR reclassification of high-risk dermal fillers has elevated clinical evidence thresholds, accelerating competitive consolidation and favoring scaled incumbents with trial-absorption capacity.
For Market Incumbents: Hedge against biosimilar toxin erosion by deepening clinician training platform investments that lock in provider preference through certification ecosystems. Anchor formulation pipelines in Seoul's MFDS accelerated pathway to compress time-to-market for novel neuromodulator variants. Absorb EMA-mandated clinical trial costs for high-risk filler reclassification to consolidate shelf presence as mid-tier competitors withdraw.
For New Entrants and Emerging Players: Telehealth-integrated consultation models offer the lowest-friction entry vector into secondary and tertiary metropolitan markets where dermatologist density lags patient demand. Target men's aesthetic segments in North American metropolitan corridors for jawline contouring protocols that remain underpenetrated relative to female patient bases. Pursue direct-to-clinic digital distribution partnerships that bypass established field-force relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap dermal filler specialists facing EMA MDR compliance cost absorption without the volume scale to negotiate consolidated supply contracts. Long-term viability favors integrated training platform operators with recurring revenue streams from certification ecosystems rather than pure-play formulation houses. Watch MFDS approval velocity for domestic Korean innovators as the inflection signal for manufacturing cluster competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinician Training Platform Expansion | AbbVie's Allergan heritage and Merz Pharma's certification ecosystems lock in provider preference across high-volume accounts. |
| MFDS Accelerated Pathway Utilization | Domestic Korean manufacturers compress novel toxin formulation time-to-market versus FDA or EMA submission timelines. |
| Subscription-Based Maintenance Programs | Prepaid annual plans in Seoul, Los Angeles, and London reduce appointment attrition and smooth revenue predictability. |
| Men's Aesthetic Segment Development | Jawline contouring and masseter reduction protocols capture underpenetrated male patient demand in metropolitan markets. |
| Combination Therapy Protocol Formulation | Sequential neuromodulator and biostimulator administration creates service bundling with higher per-visit revenue capture. |
Research Approach
Direct dialogue with board-certified dermatologists, aesthetic nurse practitioners, medical spa operators, pharmaceutical regulatory affairs leads, and GPO contracts managers grounded qualitative insights in operational reality. Secondary validation drew from FDA biologics licensing filings, EMA MDR submission databases, MFDS approval registries, hospital procurement contract repositories, and clinical trial disclosure records. Bottom-up patient volume estimates across metropolitan treatment corridors triangulated against top-down manufacturer revenue disclosures.
Bottom-up modeling anchored forecasts in procedure frequency data across Seoul, Los Angeles, London, São Paulo, and Dallas metropolitan clusters, while top-down approaches validated against disclosed manufacturer sales in toxin and filler categories. Segmentation dimensions spanned product chemistry, anatomical application, end-user channel, and regional regulatory cluster. CAGRs derived from patient cohort expansion rates and treatment frequency normalization trends, incorporating poly-L-lactic acid adoption velocity among preventive protocol seekers and medical spa channel penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for longer-duration toxin formulations or precision delivery systems would alter the outlook. Forecasts reflect assumptions regarding regulatory divergence stability, bioreactor capacity expansion timelines, and clinician workforce growth in key metropolitan corridors. Material deviation in MFDS approval velocity, EMA MDR enforcement intensity, or bulk API supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Scar Revision Market