
 Medical Aesthetic Dermal Filler Market | 2026-2036
Medical Aesthetic Dermal Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Aesthetic Dermal Filler Market Insights
EU MDR compliance is consolidating the competitive landscape for injectable aesthetic products. Allergan Aesthetics leverages its vertically integrated manufacturing network to sustain cost advantages across hyaluronic acid portfolios. Galderma anchors its position through dermatology channel control and physician education infrastructure. Merz Pharma differentiates via specialized focus on minimally invasive facial rejuvenation technologies.
Medical aesthetic dermal fillers comprise biocompatible gel or particulate formulations—predominantly cross-linked hyaluronic acid, calcium hydroxylapatite microspheres, poly-L-lactic acid, or polymethylmethacrylate—designed for subcutaneous or intradermal injection to restore facial volume, contour soft tissue, or correct age-related morphological changes. Hyaluronic acid dominates current volume due to reversibility with hyaluronidase and established safety profiles, while poly-L-lactic acid occupies a premium niche for gradual collagen biostimulation with extended duration. Pre-filled syringe delivery controls the professional channel, though autologous approaches are gaining traction among safety-conscious patient segments seeking reduced immunogenic risk.
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence standards for dermal filler manufacturers. Health Canada and Australia's TGA impose parallel but non-identical biocompatibility testing mandates that fragment regulatory strategy for multinational portfolios. Stakeholders must monitor evolving combination-product classifications where fillers incorporate lidocaine or linked device components, as these determinations will dictate which approval pathways govern next-generation launches and which competitors can afford the associated regulatory investment.
Market Dynamics
Cross-linked hyaluronic acid formulation patents are concentrating manufacturing capabilities among three dominant suppliers, while FDA's evolving combination-product framework is extending development timelines for lidocaine-incorporated fillers and reshaping competitive entry economics.
Growth Catalysts
- EU MDR streamlined pathways:The European Medical Device Regulation's consolidated technical documentation requirements for established filler classes is reducing redundant biocompatibility testing costs for manufacturers with existing CE-marked portfolios.
- Medical spa channel expansion:Non-surgical aesthetic clinics in the United States are broadening service menus to include advanced injection protocols, creating dedicated demand for premium hyaluronic acid formulations with extended duration profiles.
- Hyaluronidase reversibility:The enzymatic dissolution capability unique to hyaluronic acid-based products is reducing physician liability exposure and accelerating first-time patient conversion rates across all demographic segments.
Market Restraints
- Fermentation-derived sodium hyaluronate supply:Pharmaceutical-grade raw material production concentrates in Chinese bioreactor facilities, exposing formulation costs to geopolitical trade friction and biosafety inspection disruptions.
- Calcium hydroxylapatite irreversibility:The non-dissolvable nature of Radiesse-class products creates permanent complication risk that limits adoption among early-career injectors and risk-averse patient cohorts.
- EU MDR notified body capacity:The limited number of designated conformity assessment organizations for class III implantable devices is extending recertification queues and freezing portfolio updates for mid-tier manufacturers.
Strategic Opportunities
- Autologous fat grafting integration:Hybrid protocols combining micronized adipose tissue with synthetic fillers are opening procedural revenue streams in Brazil's premium aesthetic surgery centers.
- Health Canada parallel review:The regulator's pilot program for leveraging FDA premarket notification data is compressing entry timelines for US-approved products into Canadian dermatology channels.
- Poly-L-lactic acid body applications:Off-label utilization for décolletage and hand rejuvenation is creating incremental volume in the premium biostimulator segment ahead of formal indication expansion.
Industry Challenges
- Vascular occlusion management training:The specialized skill set required for hyaluronidase emergency protocol execution remains inconsistently distributed across medical spa nursing staff, elevating malpractice exposure.
- Pre-filled syringe sterilization validation:Terminal steam sterilization of complex delivery systems requires capital-intensive isolator technology that fragments production economics for smaller formulation specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Aesthetic Dermal Filler Market |
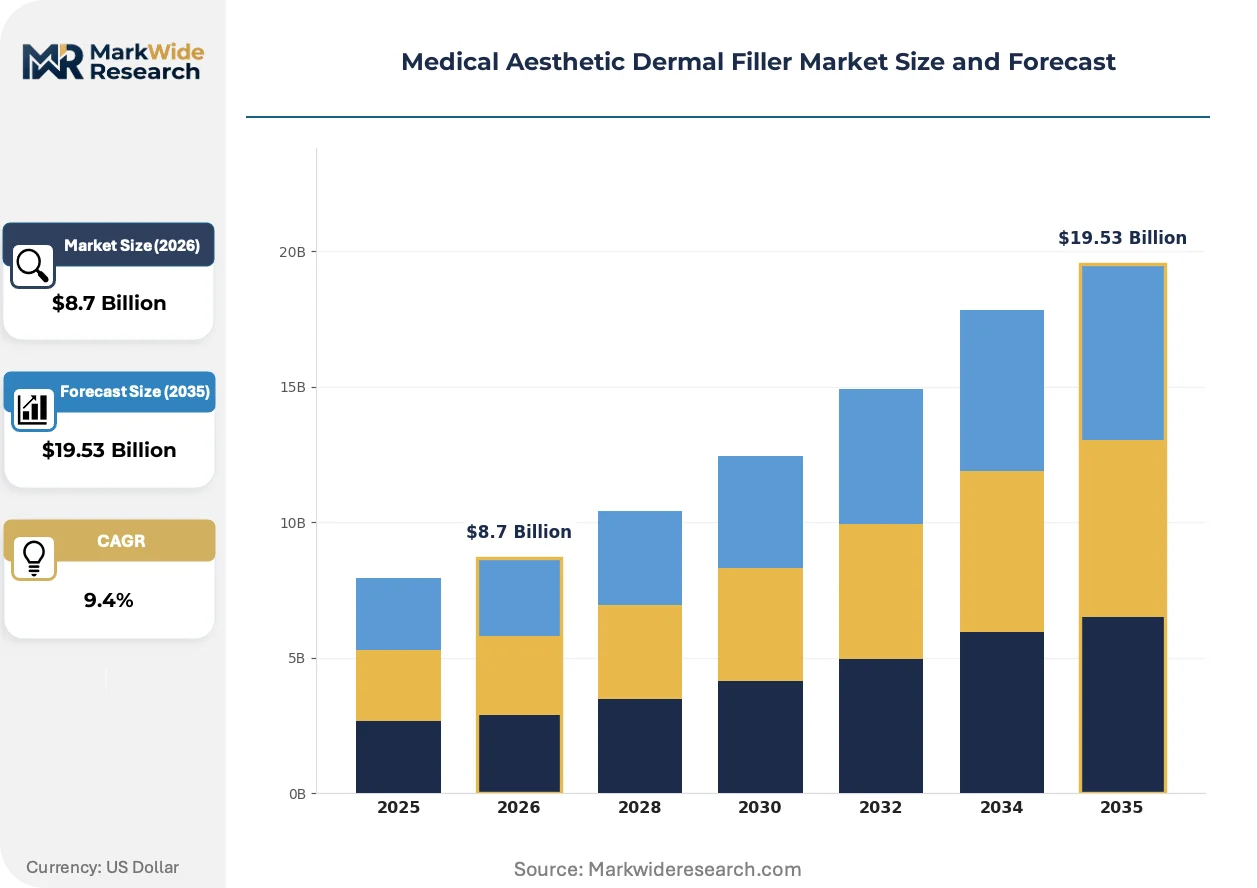
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-Lactic Acid, PMMA Application: Facial Contouring, Lip Augmentation, Wrinkle Reduction, Volume Loss Correction End User: Your Average Consumer, Medical Spa, Dermatology Clinic, Plastic Surgery Center Delivery Mode: Injectable, Pre-filled Syringe, Autologous, Other |
| Companies Covered | Allergan Aesthetics, Galderma, Merz Pharma, Sinclair Pharma, Bioxis Pharmaceuticals, Suneva Medical, Prollenium Medical Technologies, Revance Therapeutics, Teoxane Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Aesthetic Dermal Filler Market Trends and Innovations
Injection robotics and real-time tissue imaging are converging to standardize placement precision, while regulatory pressure on combination-product classifications is forcing R&D pipeline restructuring across the formulation landscape.
Ultrasound-guided cannula placement is automating depth verification during subdermal injection procedures. High-volume aesthetic chains in South Korea are deploying handheld imaging devices at scale, compressing complication rates and reducing revision visit frequency. The technology is automating physician training curves and enabling consistent outcomes across practitioner experience levels.
EU MDR Article 117 combination-product determinations are reclassifying lidocaine-incorporated fillers as drug-device combinations rather than pure devices. This regulatory friction is extending clinical evidence requirements and forcing manufacturers to establish pharmaceutical-quality pharmacovigilance systems. German and French notified bodies are applying divergent interpretation standards, fragmenting approval strategy for pan-European launches.
Direct-to-consumer teleconsultation platforms are displacing traditional physician referral pathways for initial aesthetic assessments. Millennial and Gen-Z patient cohorts in the United States are booking injection appointments through Instagram-integrated booking systems, bypassing dermatology practice gatekeepers. This channel disintermediation is compressing brand loyalty cycles and elevating price transparency pressure on premium formulation tiers.
Medical Aesthetic Dermal Filler Market Segmentation
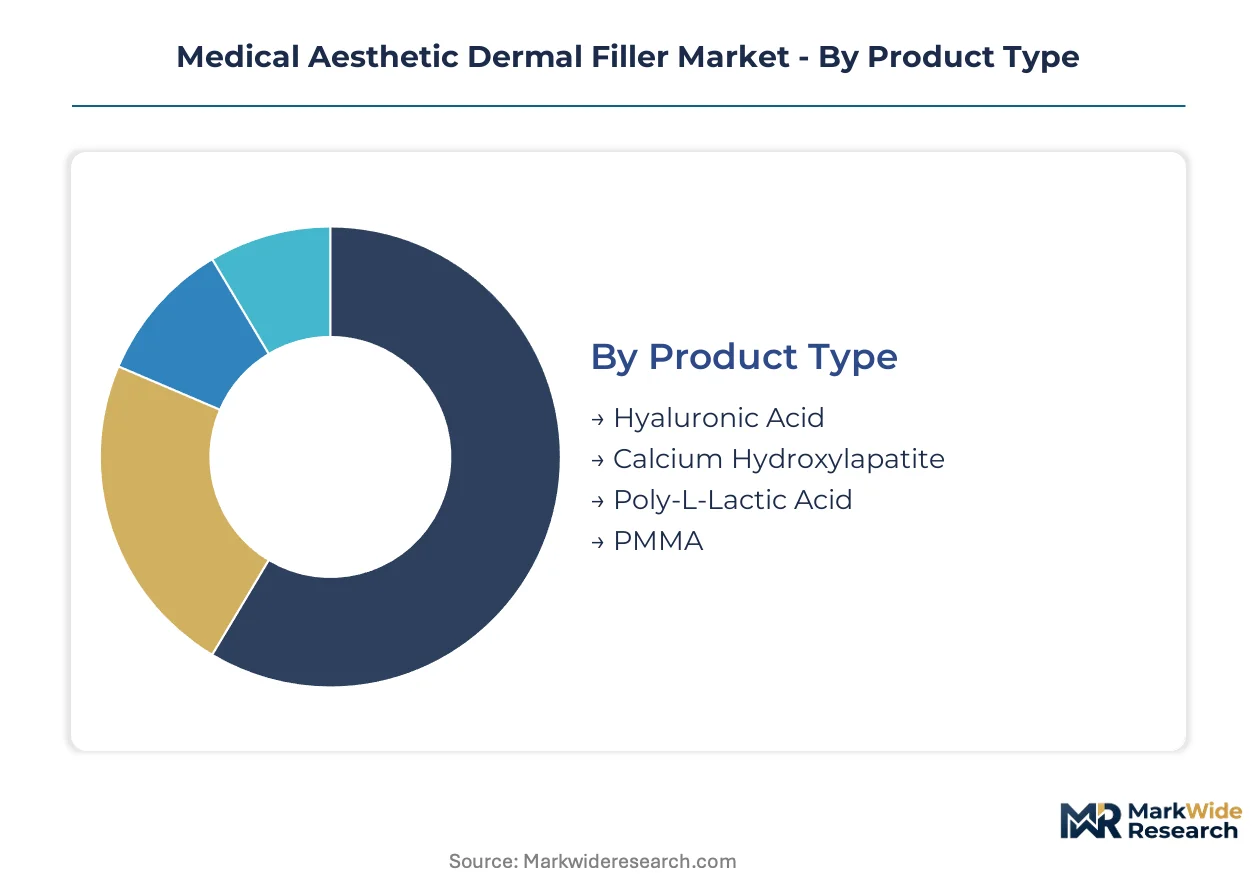
Formulation chemistry dictates reimbursement pathways and liability exposure for practitioners, while delivery modality shapes capital requirements and sterility validation burdens across manufacturing tiers. Understanding segment boundaries clarifies where premium pricing sustains margins versus where commoditization pressures concentrate.
Product Type:
Practitioner risk tolerance and reversibility requirements drive material selection more than unit economics.
- Hyaluronic Acid:Cross-linked biocompatible gels dissolve via hyaluronidase enzyme, enabling immediate complication reversal. Demand clusters in United States medical spa channels where first-time patient conversion depends on perceived safety backstops. FDA 510(k) pathways favor established cross-linking chemistries, entrenching incumbent formulation advantages.
- Calcium Hydroxylapatite:Microsphere suspensions in aqueous gel carrier provide structural scaffolding with 12-18 month longevity. Adoption concentrates among experienced injectors in Brazil and South Korea where patients prioritize duration over reversibility. Radiesse-class products face liability constraints in litigation-prone jurisdictions.
- Poly-L-Lactic Acid:Biostimulatory microparticles trigger gradual collagen neogenesis over 3-6 months. Sculptra protocols command premium positioning in European dermatology clinics for pan-facial volume restoration.
- PMMA:Permanent polymethylmethacrylate microspheres in collagen carrier deliver irreversible augmentation. Bellafill maintains niche presence for acne scar correction among patients with established aesthetic commitment.
Volume sits with hyaluronic acid formulations; growth tilts toward poly-L-lactic acid biostimulators as extended-duration protocols gain clinical validation.
Application:
Anatomical treatment zones fragment reimbursement coding and dictate cannula versus needle selection in protocol design.
- Facial Contouring:Mid-face volumization and jawline definition require deep dermal or supraperiosteal placement. South Korean high-volume chains standardize ultrasound-guided cannula techniques for zygomatic arch enhancement, compressing complication rates.
- Wrinkle Reduction:Superficial rhytid correction in nasolabial folds and marionette lines demands precise rheological matching of filler G-prime to tissue mobility. German dermatology practices emphasize rheological characterization in patient consultations.
- Lip Augmentation:Vermilion border definition and volume expansion attract younger demographic entry into aesthetic services. Instagram-integrated booking platforms in United States urban centers drive appointment velocity for this indication.
- Volume Loss Correction:Pan-facial lipoatrophy addressing addresses HIV-associated or age-related fat pad depletion. French and Italian clinics lead off-label temple and lateral cheek protocols.
Procedure frequency favors wrinkle reduction; margin expansion concentrates in facial contouring as premium product volumes scale.
End User:
Credentialing requirements and supervision models determine which delivery settings can access specific product tiers.
- Medical Spa:Non-surgical aesthetic clinics operating under physician medical directorship dominate United States hyaluronic acid volume. State-level scope-of-practice variations fragment nursing injector autonomy.
- Dermatology Clinic:Board-certified dermatologists control poly-L-lactic acid and calcium hydroxylapatite distribution through specialized training networks. Galderma's physician education infrastructure anchors channel loyalty.
- Plastic Surgery Center:Hybrid surgical-non-surgical practices capture premium pricing for combination protocols. Brazilian centers integrate autologous fat grafting with synthetic fillers.
- Your Average Consumer:Direct-to-patient teleconsultation platforms are emerging in United States millennial segments, though product access remains prescription-gated.
Patient acquisition costs favor dermatology clinics; procedure volume concentrates in medical spa channels.
Delivery Mode:
Sterilization validation requirements and cold chain logistics fragment manufacturing economics across format types.
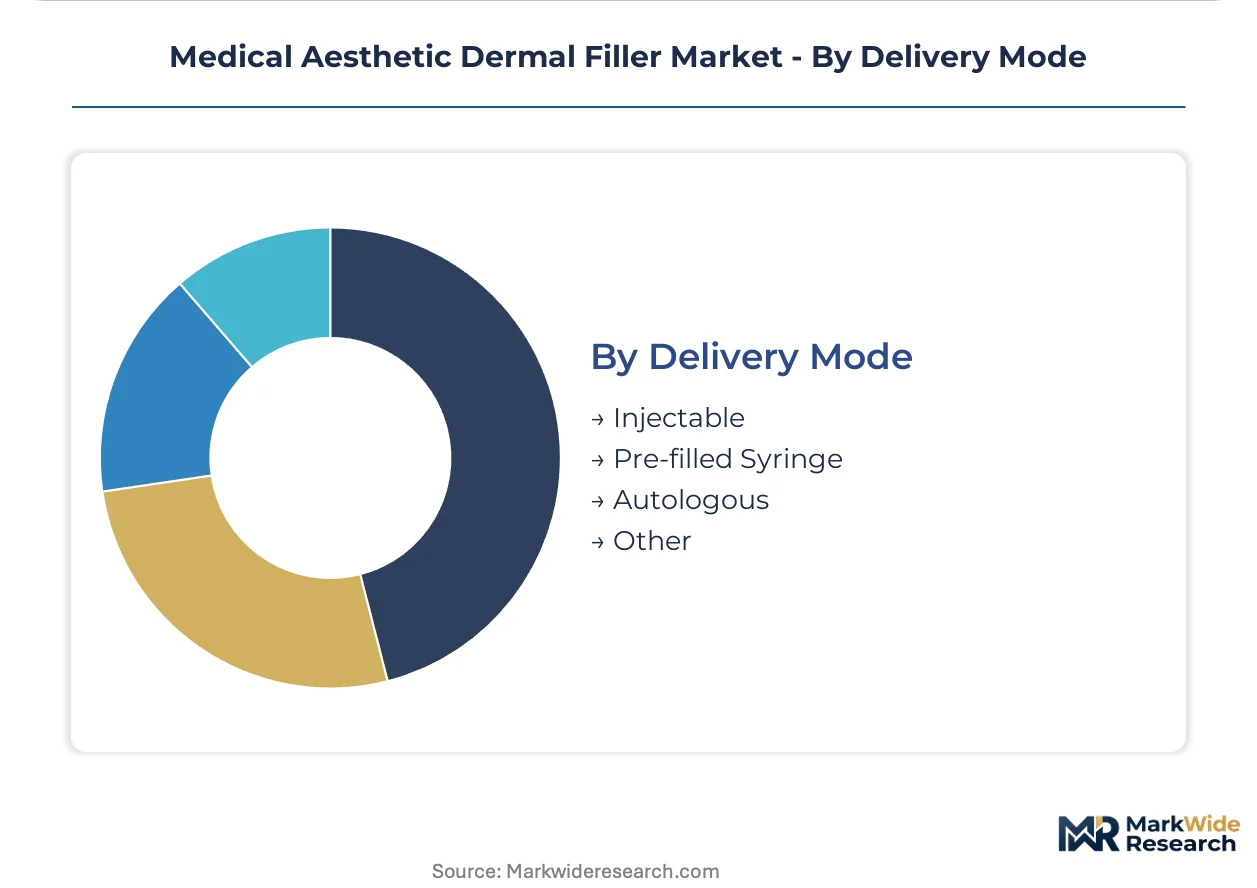
- Pre-filled Syringe:Terminal steam sterilization of complex delivery systems requires capital-intensive isolator technology. Three dominant suppliers control pharmaceutical-grade hyaluronic acid raw material access.
- Injectable:Bulk vial formats persist in research and compounding pharmacy segments outside major brand portfolios.
- Autologous:Adipose-derived stromal vascular fraction and micronized fat grafting reduce immunogenic risk. Brazilian premium surgery centers pioneer hybrid protocols.
- Other:Emerging mechanical delivery devices and needle-free systems occupy pre-commercial development phases.
Commercial scale sits with pre-filled syringes; clinical interest tilts toward autologous approaches as safety documentation accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in South Korea's Incheon cluster concentrate hyaluronic acid fermentation capacity, drawing contract manufacturing investment from multinational formulation houses seeking proximity to raw material suppliers.
United States
Medical spa chains in Florida and Texas drive hyaluronic acid syringe volume through Instagram-integrated booking platforms. FDA's evolving combination-product framework for lidocaine-incorporated fillers extends clinical trial timelines. Los Angeles and Miami aesthetic surgery centers pioneer ultrasound-guided cannula protocols for facial contouring procedures.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia anchor European demand for poly-L-lactic acid biostimulators. EU MDR notified body capacity constraints freeze portfolio updates for mid-tier manufacturers. Berlin-Brandenburg medical device clusters concentrate sterilization validation expertise for pre-filled syringe systems.
South Korea
High-volume aesthetic chains in Seoul deploy handheld ultrasound imaging devices at scale, compressing complication rates. MFDS maintains parallel but non-identical biocompatibility testing mandates that fragment regulatory strategy. Busan-Ulsan bioreactor facilities supply pharmaceutical-grade sodium hyaluronate to global formulation networks.
Brazil
Premium surgery centers in São Paulo integrate autologous fat grafting with synthetic fillers for hybrid protocols. ANVISA imposes import licensing requirements that delay product registration for non-ASEAN manufacturers. Rio de Janeiro aesthetic clinics lead off-label temple and lateral cheek volume restoration techniques.
Australia
Dermatology practices in New South Wales and Victoria absorb TGA-approved calcium hydroxylapatite microspheres for jawline definition. Health Canada's pilot program for leveraging FDA premarket data creates precedent pressure on Australian parallel review pathways. Sydney medical spa networks standardize hyaluronidase emergency protocol training across nursing staff.
Medical Aesthetic Dermal Filler Market Competitive Landscape
United States and Swiss producers anchor one tier; South Korean and French specialists hold differentiated positions through device-integrated delivery systems. Three dominant suppliers control pharmaceutical-grade hyaluronic acid raw material access, consolidating manufacturing capabilities around cross-linked formulation patents. Strategic archetypes span vertically integrated dermatology channel controllers, fermentation-derived raw material specialists, and minimally invasive facial rejuvenation technology purists. Competitive moves concentrate on EU MDR compliance infrastructure investment and medical spa channel education partnerships.
Within the vertically integrated tier, Allergan Aesthetics and Galderma exemplify archetypes of dermatology channel control and physician education infrastructure anchoring. Merz Pharma occupies a position representing specialized focus on minimally invasive facial rejuvenation technologies. These three entities sit within distinct strategic postures: one emphasizing captive supply networks, another leveraging clinical training ecosystems, the third differentiating through narrow technology specialization.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Galderma |
| Merz Pharma |
| Sinclair Pharma |
| Bioxis Pharmaceuticals |
| Suneva Medical |
| Prollenium Medical Technologies |
| Revance Therapeutics |
| Teoxane Laboratories |
| Others |
Pricing and Supply Chain Analysis
Captive control over fermentation-derived sodium hyaluronate anchors both supply security and pricing power for incumbent dermal filler manufacturers. Chinese bioreactor facilities supply pharmaceutical-grade raw material to three dominant formulation houses, concentrating upstream leverage while downstream medical spa channels compete on appointment velocity rather than product cost.
Pricing Analysis
Short lead times for EU MDR-certified hyaluronic acid syringes command premium positioning in German dermatology clinics, while spot inventory of non-certified alternatives trades at discounted rates in price-sensitive Brazilian channels. Three-tier pricing structure across premium, standard, and economy levels reflects rheological sophistication and reversibility assurance. Cost compression in standard-grade hyaluronic acid intensifies because South Korean high-volume chains negotiate consolidated procurement contracts. Medical spa networks in Florida and Texas exhibit highest price sensitivity; board-certified dermatology practices in Bavaria show least.
Supply Chain Analysis
Dual-sourcing requirements from multinational formulation houses mandate qualification of both Chinese and South Korean sodium hyaluronate suppliers to mitigate single-source vulnerability. Pharmaceutical-grade raw material production concentrates in China, South Korea, and select Swiss fermentation facilities. Cross-linked hyaluronic acid formulation patents, pre-filled syringe sterilization validation equipment, and terminal isolator technology constitute critical input dependencies. Tariff exposure on Chinese bioreactor output fragments production economics for mid-tier manufacturers. Distribution runs through physician-dispensed professional channels with cold chain logistics controlled by vertically integrated dermatology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR compliance infrastructure costs force weaker formulation specialists toward acquisition or exit. Regulatory burden concentration favors incumbents with existing notified body relationships.
For Market Incumbents: Cement channel loyalty through exclusive physician education partnerships in poly-L-lactic acid injection protocols. Expand backward integration into pharmaceutical-grade sodium hyaluronate fermentation capacity in South Korea's Busan-Ulsan corridor to secure raw material autonomy against Chinese supply disruption. Autologous fat grafting substitution technology threatens synthetic filler volume in Brazilian premium surgery centers.
For New Entrants and Emerging Players: Instagram-integrated teleconsultation booking platforms offer direct patient acquisition routes bypassing dermatology practice gatekeepers. Target millennial lip augmentation demand in United States urban centers where brand loyalty cycles compress and price transparency pressure elevates. Pursue Health Canada parallel review pathway for accelerated entry leveraging existing FDA 510(k) data packages.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier manufacturers with EU MDR technical documentation already filed but lacking capital to complete notified body recertification queues. Long-term viability hinges on combination-product classification expertise as lidocaine-incorporated fillers shift toward drug-device regulatory pathways. Watch ANVISA import licensing delays in Brazil as inflection indicator for Latin American market access friction.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body recertification queues freeze portfolio updates for competitors lacking capital reserves. |
| Physician Education Infrastructure Expansion | Galderma's dermatology channel control demonstrates anchoring power through specialized training networks. |
| Ultrasound-Guided Cannula Protocol Development | Seoul high-volume chains standardize imaging automation to compress complication rates and revision frequency. |
| Autologous Fat Grafting Hybrid Integration | São Paulo premium surgery centers pioneer micronized adipose protocols reducing immunogenic risk profiles. |
| Health Canada Parallel Review Participation | Leveraging FDA premarket data compresses entry timelines for US-approved products into Canadian channels. |
Research Methodology
Independent corroboration across regulatory filings, procurement databases, and clinical protocol documentation underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, medical spa medical directors, dermatology clinic procurement managers, and GPO contracts specialists combined with secondary validation from FDA 510(k) databases, EMA CE marking registries, MFDS submission records, and hospital procurement databases. Bottom-up demand modeling across formulation chemistry segments triangulated against top-down market sizing from raw material fermentation capacity.
Comparable-period anchoring to historical CE marking and FDA approval trajectories established baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include formulation chemistry, anatomical application zone, end-user credentialing tier, and delivery modality sterility requirements. CAGRs derived from elasticity-adjusted demand curves incorporating hyaluronidase reversibility preference shifts and medical spa channel expansion rates. Forecast inputs incorporated EU MDR notified body capacity constraints and Chinese biosafety inspection disruption probabilities.
Inputs from regulatory submission databases and medical spa appointment booking platforms were available through the study window; gaps in real-time pricing transparency for autologous fat grafting protocols introduce uncertainty bands around premium segment estimates. Forecasts reflect documented assumptions regarding physician training curve compression and ultrasound imaging device deployment rates. Deviation in EU MDR combination-product classification determinations for lidocaine-incorporated fillers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Carboxy Therapy Market