
 North America Aesthetic Dermatology Market | 2026-2036
North America Aesthetic Dermatology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aesthetic Dermatology Market Analytics
Combination therapy bundling is restructuring how aesthetic practices package injectables with energy-based procedures for premium patient outcomes. Allergan Aesthetics leverages its portfolio breadth to anchor bundled service protocols across dermatology practices. Galderma competes through specialized filler and toxin formulations that target specific facial anatomies. Candela Medical controls laser and light-based platform development, sustaining technology leadership in vascular and pigmentation applications.
Aesthetic dermatology encompasses minimally invasive and non-invasive procedures that modify skin appearance through energy delivery, pharmaceutical injection, or chemical resurfacing, typically operating at wavelengths between 532 nm and 10,600 nm or utilizing biocompatible fillers such as hyaluronic acid and calcium hydroxylapatite. These interventions serve commercial purposes by addressing photodamage, rhytides, adiposity, and dyschromia in outpatient settings with minimal recovery intervals. Injectables occupy the largest margin pool due to recurring treatment cycles and direct-to-consumer brand recognition, while radiofrequency and ultrasound technologies represent the fastest-expanding technology segment as practitioners seek alternatives to surgical lifting. Laser treatments remain mature in hair removal and vascular indications but face margin compression from device commoditization.
FDA 510(k) clearance requirements and HIPAA privacy obligations shape product development timelines and clinic operational compliance across the United States, while Health Canada and PMRA oversight in Canada establishes parallel but distinct approval pathways for cross-border manufacturers. The FTC monitors advertising claims for aesthetic outcomes, constraining how practices and manufacturers communicate efficacy. Stakeholders must monitor evolving FDA guidance on energy-based device indications and state-level scope-of-practice regulations that determine whether non-physician providers may operate aesthetic equipment.
Market Dynamics
Med spa chains and dermatology practices are consolidating service delivery around combination therapy protocols that bundle energy-based devices with injectables, compressing standalone procedure margins while elevating patient retention economics. FDA 510(k) clearance pathways are shortening time-to-market for novel laser and radiofrequency platforms, accelerating competitive substitution cycles across California, Texas, and Florida where clinic density and disposable income concentrate demand.
Growth Catalysts
- Energy-based device innovation:Radiofrequency and ultrasound technologies are expanding indication sets beyond traditional resurfacing into non-surgical lifting, attracting younger patient cohorts seeking preventive interventions. Practitioners in high-density metropolitan markets are prioritizing these platforms for their recurring revenue potential.
- FDA regulatory efficiency:Streamlined 510(k) clearance mechanisms for predicate-based energy devices are reducing commercialization timelines from 18-24 months to 12-15 months, enabling faster platform turnover and technology refresh cycles.
- Disposable income concentration:California, Texas, and Florida maintain disproportionate shares of aesthetic procedure volume due to aligned demographics, climate-driven skin concern prevalence, and medical tourism inflows from neighboring states and Canadian provinces.
Market Restraints
- Device commoditization pressure:Laser hair removal and vascular treatment platforms face margin compression as Chinese and Korean manufacturers flood mid-market segments with functionally equivalent systems at 40-60% price discounts.
- Input cost volatility:Hyaluronic acid raw material supply concentrates among three European fermentation producers, exposing filler manufacturers to batch consistency risks and periodic shortage-driven price spikes.
- Scope-of-practice fragmentation:State-level regulations governing non-physician operation of energy-based devices vary across Texas, Florida, and California, creating operational complexity for multi-state clinic chains and limiting workforce flexibility.
Strategic Opportunities
- Men's aesthetic penetration:Underdeveloped male patient segments across Texas and Florida represent expansion white space as social stigma erosion and targeted marketing protocols normalize injectable and energy-based treatments for jawline contouring and hair restoration.
- Combination protocol standardization:Bundling neuromodulators with fractional laser resurfacing in single-visit protocols is elevating average transaction values while reducing patient acquisition costs through improved outcome differentiation.
- Telehealth consultation integration:Virtual pre-screening and post-procedure follow-up channels are extending geographic catchment areas for established California practices, capturing patients from secondary markets without physical expansion.
Industry Challenges
- Injection technique specialization:Advanced filler placement for periorbital and temple regions demands anatomical expertise that outpaces current training pipeline capacity, creating service quality variance across expanding non-physician injector workforces.
- Device depreciation cycles:Accelerated FDA clearance timelines compress effective equipment lifespans from 7-10 years to 4-6 years, straining capital allocation for independent practices without corporate backing.
- HIPAA-compliant marketing analytics:FTC oversight of before-and-after outcome claims intersects with patient privacy obligations, constraining digital advertising personalization and attribution modeling for direct-to-consumer campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aesthetic Dermatology Market |
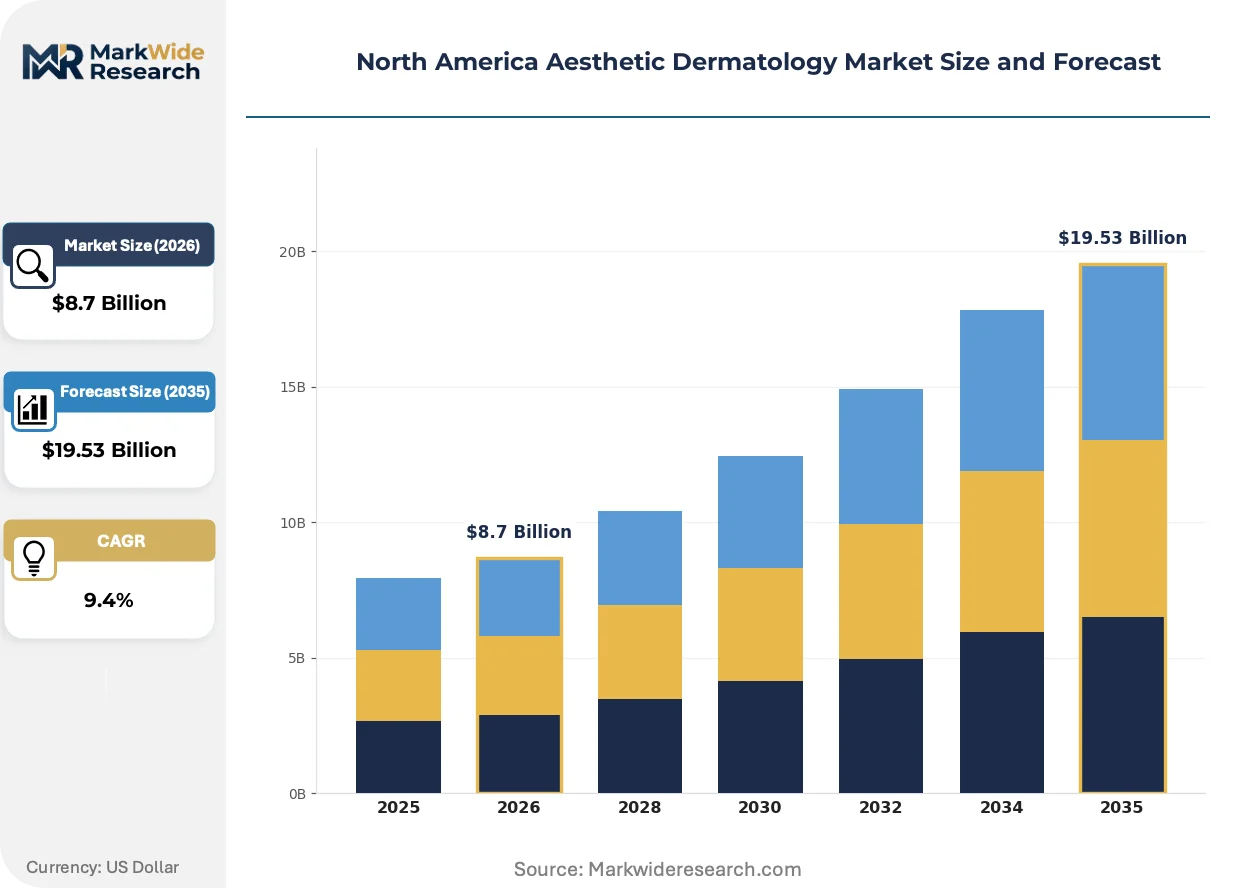
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Treatments, Skin Rejuvenation Devices, Chemical Peels Customer Type: Individuals, Clinics, Hospitals, Dermatology Practices Technology: Microneedling, Radiofrequency, Cryotherapy, Ultrasound Application: Wrinkle Reduction, Skin Tightening, Acne Treatment, Pigmentation Removal |
| Companies Covered | Allergan Aesthetics, Galderma, Cutera, Cynosure, Candela Medical, Alma Lasers, Bausch Health Companies, Merz Pharma, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aesthetic Dermatology Market Evolving Landscape
Radiofrequency microneedling platforms are converging with ultrasound-based fat reduction systems to create multi-modality treatment rooms that maximize per-square-foot revenue while reducing patient throughput bottlenecks. This technological layering is restructuring capital deployment patterns and staff training priorities across outpatient aesthetic settings.
Microfocused ultrasound with visualization is overtaking traditional surgical lifting consultations among patients aged 35-50 seeking brow and submental contouring without operative recovery. Dermatology practices in California and Texas are allocating 60-70% of new capital expenditure toward these platforms, compressing demand for thread lift procedures and mini-lift surgeries that previously captured this demographic.
FDA draft guidance on energy-based device indications for skin laxity is clarifying predicate pathways for novel radiofrequency and laser platforms, reducing regulatory uncertainty for manufacturers pursuing expanded label claims. The draft prioritizes objective endpoint validation through standardized photography protocols, disproportionately affecting smaller device developers lacking established clinical affairs infrastructure relative to established platform holders.
Subscription membership models for maintenance toxin and filler schedules are displacing transactional per-procedure pricing in high-competition metropolitan markets. Med spa chains across Florida and Texas are piloting annual commitment programs with priority booking guarantees, capturing predictable cash flows while locking in patient loyalty against competing practices within 15-mile radii.
North America Aesthetic Dermatology Market Segmentation
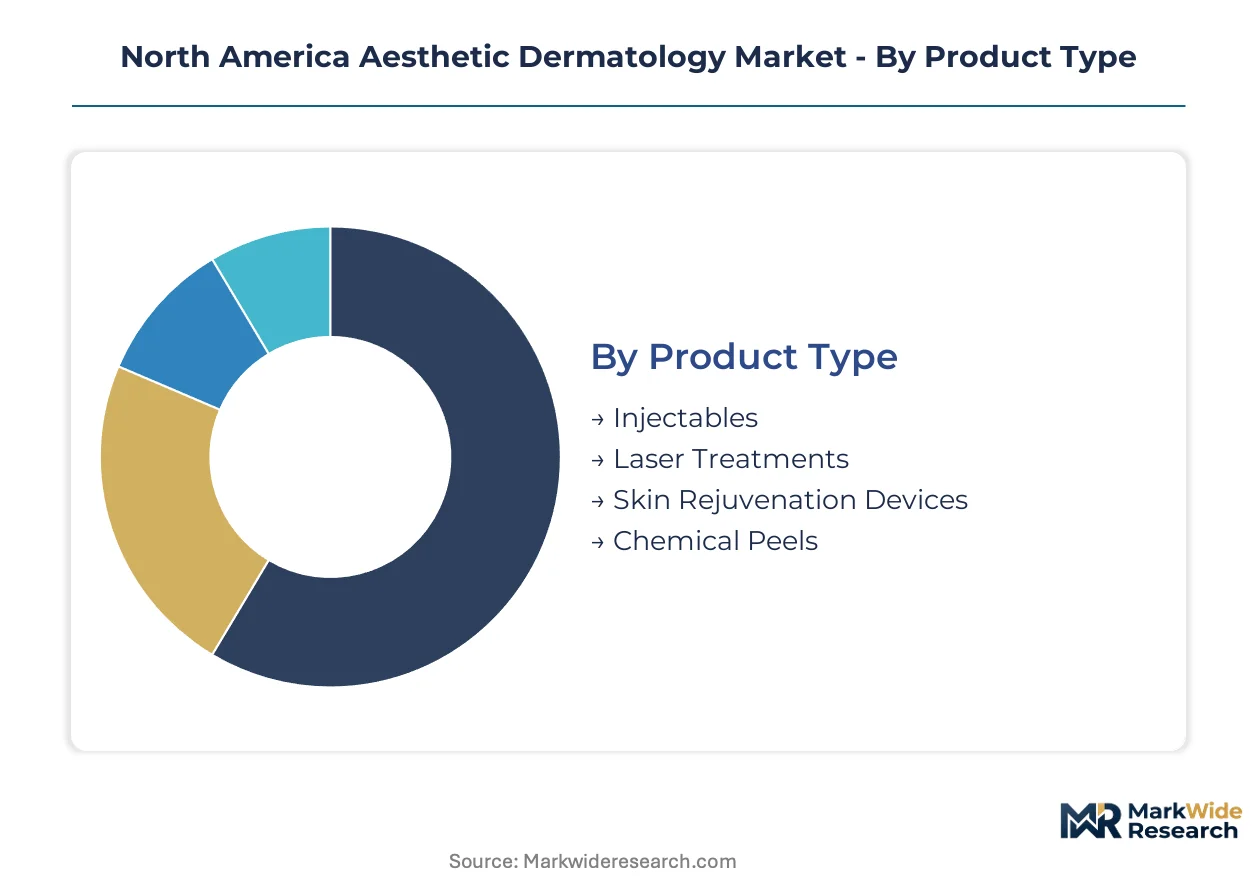
Segmentation in aesthetic dermatology reveals divergent capital requirements and margin profiles across product categories. Understanding these structural differences enables targeted resource allocation for manufacturers and service providers competing across North American metropolitan markets.
Product Type:
Capital intensity varies dramatically across product categories, with energy-based platforms demanding 5-10x the upfront investment of consumable injectables.
- Injectables:Hyaluronic acid and neuromodulator formulations require minimal capital equipment but command recurring revenue through treatment cycles. Demand concentrates in California and Texas dermatology practices where patient retention economics favor subscription-based maintenance schedules.
- Laser Treatments:Platforms operating across 532 nm to 10,600 nm wavelengths demand substantial capital deployment and specialized facility infrastructure. Clinics in Florida prioritize these systems for photodamage correction driven by climate-induced skin concern prevalence.
- Skin Rejuvenation Devices:Radiofrequency and light-based systems occupy mid-tier capital intensity with shorter depreciation cycles than surgical lasers.
- Chemical Peels:Lowest equipment barrier to entry with formulation-dependent efficacy profiles and minimal regulatory clearance requirements.
Most installed capacity flows through Injectables. Expansion is steepest in Skin Rejuvenation Devices.
Customer Type:
Customer archetypes determine purchasing behavior, with institutional buyers negotiating volume contracts while individual patients drive brand-level demand recognition.
- Individuals:Direct consumers selecting providers based on outcome reputation and convenience proximity. California residents demonstrate highest per-capita procedure frequency among North American patient populations.
- Clinics:Med spa chains and independent aesthetic practices consolidating multi-modality service menus. Texas-based chains are expanding fastest through acquisition-driven consolidation strategies.
- Hospitals:Academic medical centers and health system outpatient divisions integrating aesthetic services into dermatology departments.
- Dermatology Practices:Physician-owned specialty practices maintaining clinical credibility advantages for complex indications.
Revenue concentration sits with Dermatology Practices. Patient volume growth is climbing fastest in Clinics.
Technology:
Technology selection dictates reimbursement positioning, regulatory pathway complexity, and practitioner training requirements across North American jurisdictions.
- Microneedling:Percutaneous collagen induction systems combining mechanical penetration with topical delivery. Florida practices favor these platforms for minimal downtime protocols attracting working-age professional demographics.
- Radiofrequency:Thermal energy delivery for non-surgical tissue tightening with expanding indication sets. FDA 510(k) predicate pathways are shortening clearance timelines for next-generation fractional and microneedling-integrated systems.
- Cryotherapy:Controlled cold application for lesion removal and adipocyte disruption with established safety profiles.
- Ultrasound:Microfocused visualization-guided systems capturing surgical lift alternatives among patients aged 35-50.
Platform deployment concentrates in Radiofrequency. Technology refresh rates are accelerating most quickly in Ultrasound.
Application:
Application focus shapes marketing compliance boundaries under FTC oversight and determines competitive intensity within metropolitan catchment areas.
- Wrinkle Reduction:Neuromodulator and filler interventions for rhytide correction represent the most mature application with established direct-to-consumer brand recognition. Texas and Florida markets show particular concentration of toxin maintenance schedules.
- Skin Tightening:Energy-based lifting alternatives to surgical procedures attracting younger preventive treatment cohorts. California practices lead adoption of combination protocols bundling radiofrequency with ultrasound platforms.
- Acne Treatment:Light-based and pharmaceutical interventions addressing inflammatory and scarring indications.
- Pigmentation Removal:Laser and intense pulsed light systems targeting dyschromia with wavelength-specific selectivity requirements.
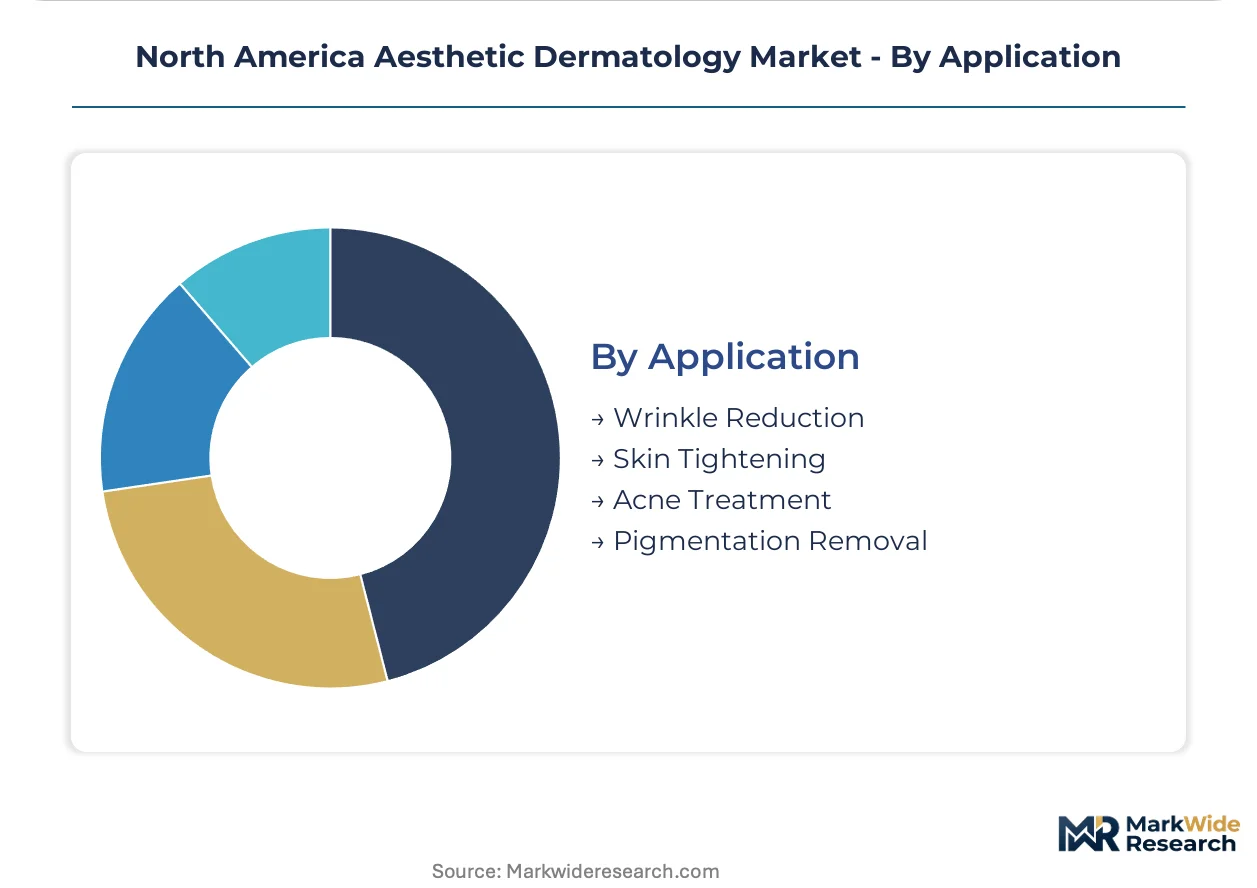
Procedure volume flows predominantly through Wrinkle Reduction. Indication expansion is gaining share fastest in Skin Tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aesthetic dermatology industry traces its commercial scaling to the United States, where FDA regulatory frameworks first enabled mass-market energy-based devices and injectable formulations in the 1990s and 2000s. This foundational infrastructure established protocols that Canadian and Mexican markets subsequently adapted.
United States
California, Texas, and Florida concentrate procedure volume through aligned demographics and climate-driven skin concerns. FDA 510(k) clearance pathways for predicate-based energy devices compress commercialization timelines to 12-15 months. Los Angeles and Miami serve as innovation hubs where med spa chains pilot subscription membership models for maintenance toxin schedules.
Canada
Toronto and Vancouver anchor demand through high disposable income concentrations and medical tourism inflows from neighboring provinces. Health Canada and PMRA oversight establishes parallel approval pathways distinct from FDA mechanisms, creating regulatory complexity for cross-border manufacturers. Ontario-based dermatology practices are consolidating multi-modality service menus through acquisition-driven expansion.
Mexico
Mexico City and Monterrey attract price-sensitive patients from the southwestern United States seeking cost-advantaged procedures. COFEPRIS regulatory oversight governs device and pharmaceutical approvals with timelines that lag FDA processes by 6-12 months. Tijuana medical corridors specialize in combination therapy bundling for cross-border aesthetic tourism.
North America Aesthetic Dermatology Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and brand recognition dimensions. The vendor base concentrates around established platform holders with FDA clearance portfolios and direct-to-consumer marketing capabilities. Three strategic archetypes dominate: diversified pharmaceutical-aesthetic conglomerates, specialized energy-device manufacturers, and emerging Asian challengers with cost-disrupted mid-market offerings. Competitive moves center on M&A-driven portfolio consolidation and accelerated technology licensing to compress R&D cycles.
Within the diversified pharmaceutical-aesthetic tier, Allergan Aesthetics and Galderma occupy positions anchored by injectable formulation breadth and recurring revenue economics. Candela Medical exemplifies the specialized energy-device archetype with concentrated expertise in laser and light-based platforms. These three entities represent distinct competitive vectors: toxin and filler dominance, integrated device-injectable bundling, and wavelength-specific technology leadership.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Galderma |
| Cutera |
| Cynosure |
| Candela Medical |
| Alma Lasers |
| Bausch Health Companies |
| Merz Pharma |
| Lumenis |
| Others |
Value Network & Pricing Analysis
Premium-device and commodity-device divergence across energy-based platforms manifests in starkly different pricing architectures and sourcing configurations. Allergan Aesthetics and Galderma command subscription-based recurring revenue through toxin and filler portfolios, while Chinese and Korean manufacturers compress margins on laser hair removal systems through direct-to-clinic distribution that bypasses traditional device leasing structures.
Pricing Analysis
Subscription membership models for maintenance toxin schedules now dominate high-competition metropolitan markets, displacing transactional per-procedure pricing. Price differentiation rests on brand recognition and injector certification tier, with Allergan Aesthetics and Galderma capturing premium positioning against emerging toxin biosimilars. Cost compression in mid-market laser platforms intensifies as Asian manufacturers flood Texas and Florida with functionally equivalent systems at steep discounts. Independent dermatology practices demonstrate highest price sensitivity due to capital constraint, while med spa chains absorb premium pricing for exclusive territory rights.
Supply Chain Analysis
Trade-in and refurbishment flows for energy-based devices create secondary market liquidity that extends effective equipment lifespans for budget-constrained practices. Manufacturing concentrates in the United States, Israel, and South Korea for laser and radiofrequency platforms, while hyaluronic acid raw material fermentation anchors in three European producers. Supply chain risk centers on single-source vulnerability for HA precursor batches, with periodic shortage-driven price spikes disrupting filler production schedules. Distribution runs through manufacturer-direct sales forces and specialized medical device distributors serving multi-state clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American aesthetic dermatology has entered late-cycle quality concentration, with patient demand shifting toward combination protocols that demand premium injector expertise and multi-modality platform ownership.
For Market Incumbents: Anchor service differentiation through exclusive combination therapy bundling that locks patient loyalty against competing practices within 15-mile radii. Defend against emerging Asian device manufacturers by deepening backward integration into proprietary training academies that certify injector technique. Prioritize FDA 510(k) predicate pathway investments for next-generation radiofrequency platforms with expanded skin laxity indications. For New Entrants and Emerging Players: The mid-market price-point gap between premium Allergan Aesthetics toxin subscriptions and economy Korean device offerings presents serviceable white space for specialized ultrasound platforms targeting jawline contouring. Men's aesthetic segments across Texas and Florida remain underpenetrated, with social stigma erosion creating first-mover advantage for targeted marketing protocols. Pursue telehealth-integrated pre-screening channels to extend geographic catchment without physical clinic expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where independent dermatology practices face compressed equipment depreciation cycles and capital allocation strain from accelerated FDA clearance timelines. Five-to-ten year viability favors platforms with recurring consumable revenue and direct-to-consumer brand recognition. Monitor FDA draft guidance finalization on energy-based device indications as inflection signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Therapy Protocol Standardization | Bundling neuromodulators with fractional laser resurfacing elevates average transaction values for California practices. |
| Subscription Membership Model Deployment | Annual commitment programs with priority booking guarantees capture predictable cash flows for Florida med spa chains. |
| Men's Aesthetic Service Line Expansion | Jawline contouring and hair restoration protocols normalize injectable treatments across Texas male demographics. |
| Telehealth Consultation Integration | Virtual pre-screening extends geographic catchment areas for established practices without physical expansion. |
| FDA 510(k) Predicate Pathway Investment | Streamlined clearance mechanisms compress commercialization timelines for next-generation radiofrequency platforms. |
Research Methodology
Multiple input streams — clinician interviews, device manufacturer regulatory affairs consultations, and med spa chain operational assessments — were reconciled against secondary validation from FDA 510(k) filings, Health Canada device licensing records, and state-level scope-of-practice regulatory databases. Bottom-up procedure volume estimates from California, Texas, and Florida dermatology practices were triangulated with top-down market sizing derived from Allergan Aesthetics and Galderma revenue disclosures.
Data-stream reconciliation across product type, customer archetype, technology platform, and application indication dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates, treatment cycle frequency assumptions, and capital expenditure patterns across metropolitan markets. Industry-specific forecast inputs incorporated FDA clearance timeline compression effects and hyaluronic acid raw material supply concentration risks.
Caveats apply where FDA guidance finalization on energy-based device indications or state-level scope-of-practice liberalization could materially shift the outlook for non-physician injector workforce expansion. Practitioners should monitor COFEPRIS regulatory alignment in Mexico and emerging Asian manufacturer entry into mid-market laser segments for early signals of competitive intensity acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Asia-Pacific Dermal Fillers Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market