
 Collagen Fillers Market | 2026-2036
Collagen Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Collagen Fillers Market Analysis
Multi-source procurement of raw collagen materials is expanding as manufacturers seek supply resilience against bovine and porcine origin constraints. Allergan (AbbVie) leverages its vertically integrated biologics infrastructure to secure consistent Type I collagen feedstock. Johnson & Johnson anchors its competitive stance through broad dermatology channel relationships that sustain high-volume filler distribution. Merz Pharma GmbH & Co. KGaA differentiates via specialized R&D focus on cross-linking technologies that extend product longevity in vivo.
Collagen fillers comprise purified extracellular matrix proteins, primarily Type I and Type III collagen, formulated as injectable gels or solid implants for soft tissue augmentation and dermal volume restoration. These products function through immediate mechanical support and gradual biodegradation that stimulates host fibroblast activity and neocollagenesis. Injectable fillers dominate current revenue pools due to lower procedural barriers and reversibility, while biologic products represent the fastest-expanding category as recombinant and human-biosynthetic sources reduce immunogenicity risks. Facial contouring applications command premium positioning relative to wrinkle reduction, reflecting higher per-procedure product volumes and specialized injector training requirements.
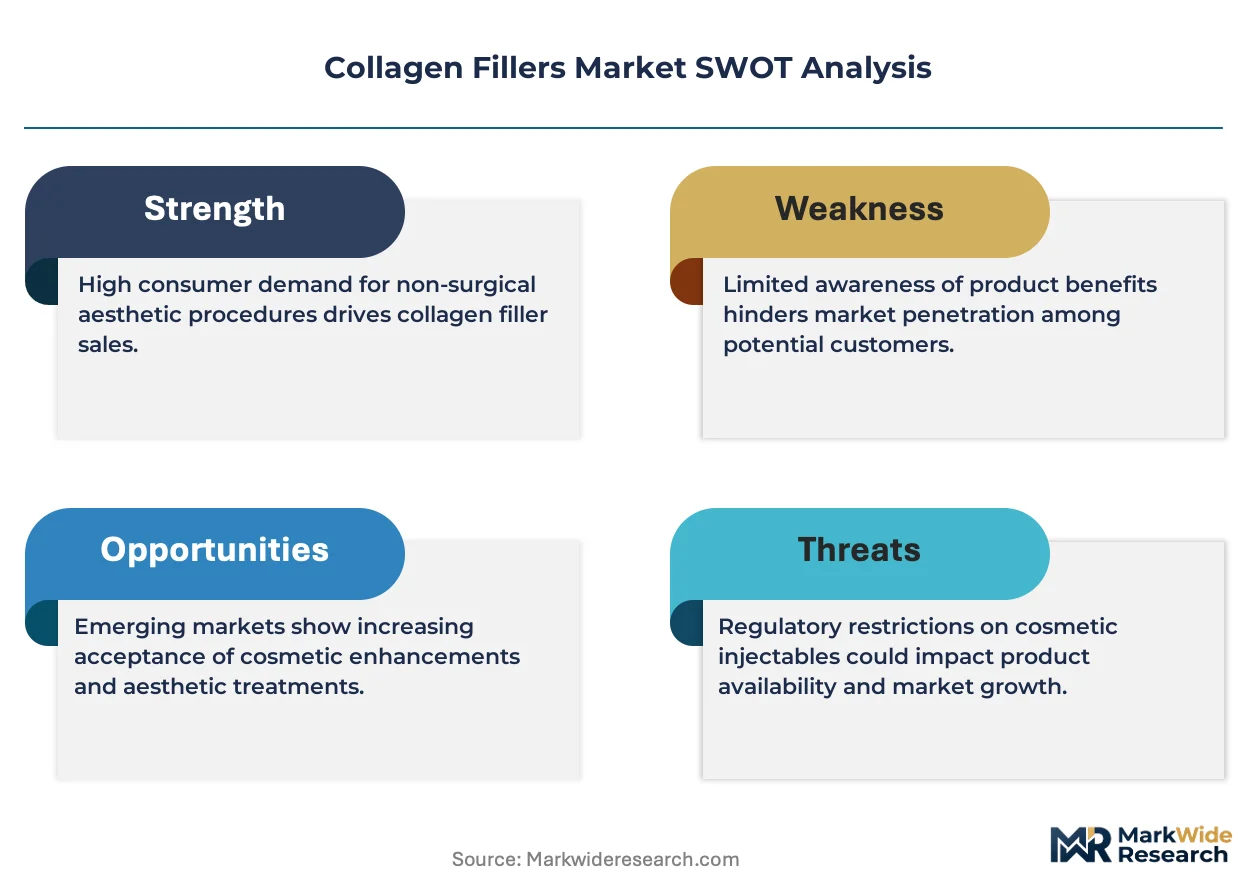
The FDA maintains stringent premarket notification pathways for collagen-based devices under its biologics and 510(k) frameworks, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for implantable aesthetic products. Health Canada and Australia's TGA enforce comparable safety surveillance protocols that delay market entry for novel formulations but elevate practitioner and patient confidence. Stakeholders must monitor evolving reimbursement classifications for aesthetic versus reconstructive indications, as these determinations fundamentally reshape addressable patient populations and pricing authority across clinical settings.
Market Dynamics
Cross-linking chemistry advances are compressing product degradation timelines and extending clinical efficacy windows, forcing manufacturers to recalibrate formulation pipelines around longer-acting molecular architectures rather than incremental concentration adjustments.
Growth Catalysts
- MFDS fast-track pathways:South Korea's streamlined biologics approval framework accelerates novel collagen construct market entry, incentivizing manufacturers to prioritize Seoul-based clinical trial sites for first-in-human data generation.
- Recombinant human collagen platforms:Biosynthetic production methods eliminate bovine spongiform encephalopathy screening burdens and porcine religious restriction barriers, opening addressable patient pools in Middle Eastern and South Asian markets.
- Combination therapy protocols:Aesthetic practices increasingly sequence collagen fillers with energy-based devices, creating bundled procedure economics that lift per-visit revenue and patient retention metrics.
Market Restraints
- Type I collagen feedstock concentration:Three specialized abattoir networks in the United States and Brazil supply pharmaceutical-grade dermal matrix, creating single-source vulnerability for non-vertically integrated formulators.
- EU MDR clinical evidence burdens:Enhanced post-market surveillance requirements for implantable aesthetic devices extend recertification timelines and inflate regulatory affairs headcount by forty percent for mid-tier manufacturers.
- Hyaluronic acid substitution:Reversible HA fillers with lidocaine integration capture price-sensitive segments and first-time injectable patients, compressing collagen trial rates among demographic cohorts under forty-five.
Strategic Opportunities
- Vietnam and Indonesia clinic expansion:Aesthetic medicine infrastructure investment in Ho Chi Minh City and Jakarta outpaces trained injector supply, creating first-mover advantage for collagen brands establishing training academy partnerships.
- Hand and décolletage applications:Off-face volumizing procedures remain underdeveloped relative to facial contouring, offering premium positioning for collagen constructs with demonstrated dermal thickness restoration in extremity skin.
- ISO 13485 certification as procurement filter:Hospital-based dermatology departments increasingly mandate quality management system certification for vendor qualification, advantaging compliant manufacturers in institutional tender processes.
Industry Challenges
- Cross-linking specialist scarcity:Polymer chemistry expertise for optimizing carbodiimide and glutaraldehyde reaction kinetics concentrates among aging academic cohorts, constraining R&D throughput for second-generation product lines.
- Cold chain integrity at last-mile:Temperature excursions during clinic receiving compromise collagen fibril structure, requiring manufacturers to absorb replacement costs or deploy IoT-enabled shipment monitoring that inflates logistics spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagen Fillers Market |
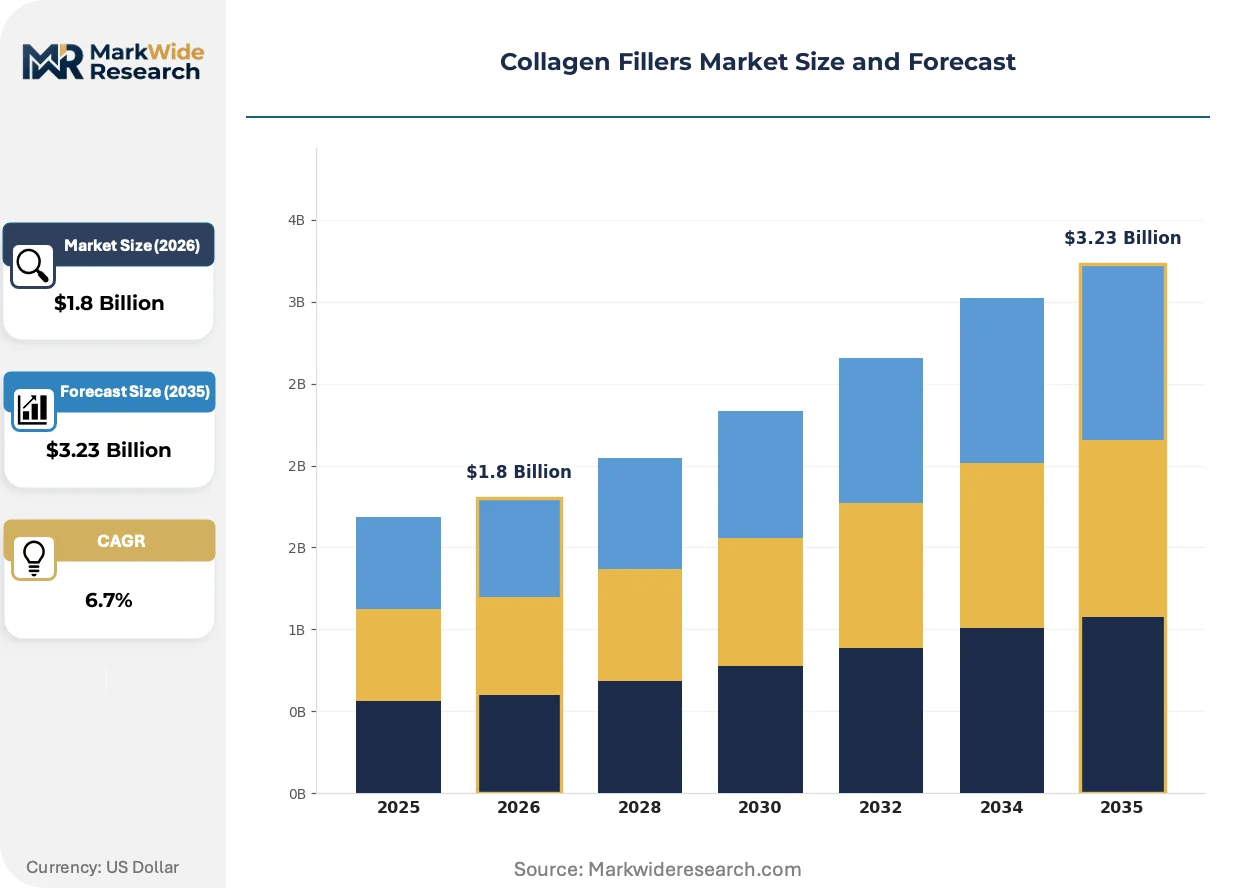
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Fillers, Surgical Implants, Biologic Products, Semi-Permanent Fillers Application: Wrinkle Reduction, Facial Contouring, Lip Enhancement, Scar Treatment End User: Cosmetic Clinics, Dermatology Practices, Hospitals, Medical Spas Distribution Channel: Direct Sales, Online Retail, Wholesalers, Beauty Supply Stores |
| Companies Covered | Allergan (AbbVie), Johnson & Johnson, Merz Pharma GmbH & Co. KGaA, Collplant Holdings Ltd, Suneva Medical, Sinclair Pharma, Ortho Dermatologics, Sunmax Biotechnology Co., Ltd., EURORESEARCH s.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagen Fillers Market Emerging Trajectories
Bifunctional filler architectures that merge immediate mechanical support with sustained bio-stimulation are displacing single-mechanism products across premium procedure tiers, compelling manufacturers to reframe clinical trial endpoints around neocollagenesis biomarkers rather than wrinkle depth alone.
Telopeptide-stripped atelocollagen formulations are unifying immunogenicity reduction with native fibril assembly properties, enabling adoption by academic medical centers previously restricted to synthetic alternatives. University-affiliated dermatology departments in Germany and Japan now specify atelo-derived constructs for reconstructive applications. This unification of safety and performance profiles is compressing market segmentation between aesthetic and medical-grade product categories.
The FDA's 2023 updated guidance on biologic injectables mandates enhanced pharmacovigilance for novel collagen sources, extending premarket notification review cycles but elevating post-approval competitive moats for compliant entrants. Manufacturers must now submit real-world evidence protocols alongside 510(k) submissions. High-volume aesthetic chains are responding by consolidating supplier relationships around established FDA-cleared portfolios rather than experimental constructs.
Patient preference is migrating toward gradual, serial micro-dosing regimens over single high-volume injections, disrupting traditional per-syringe pricing models and favoring subscription-based loyalty programs. Med-spa chains in California and Florida now package annual filler maintenance into membership tiers. This behavioral shift compresses average transaction values while extending lifetime patient revenue capture for practices with robust retention infrastructure.
Collagen Fillers Market Segmentation
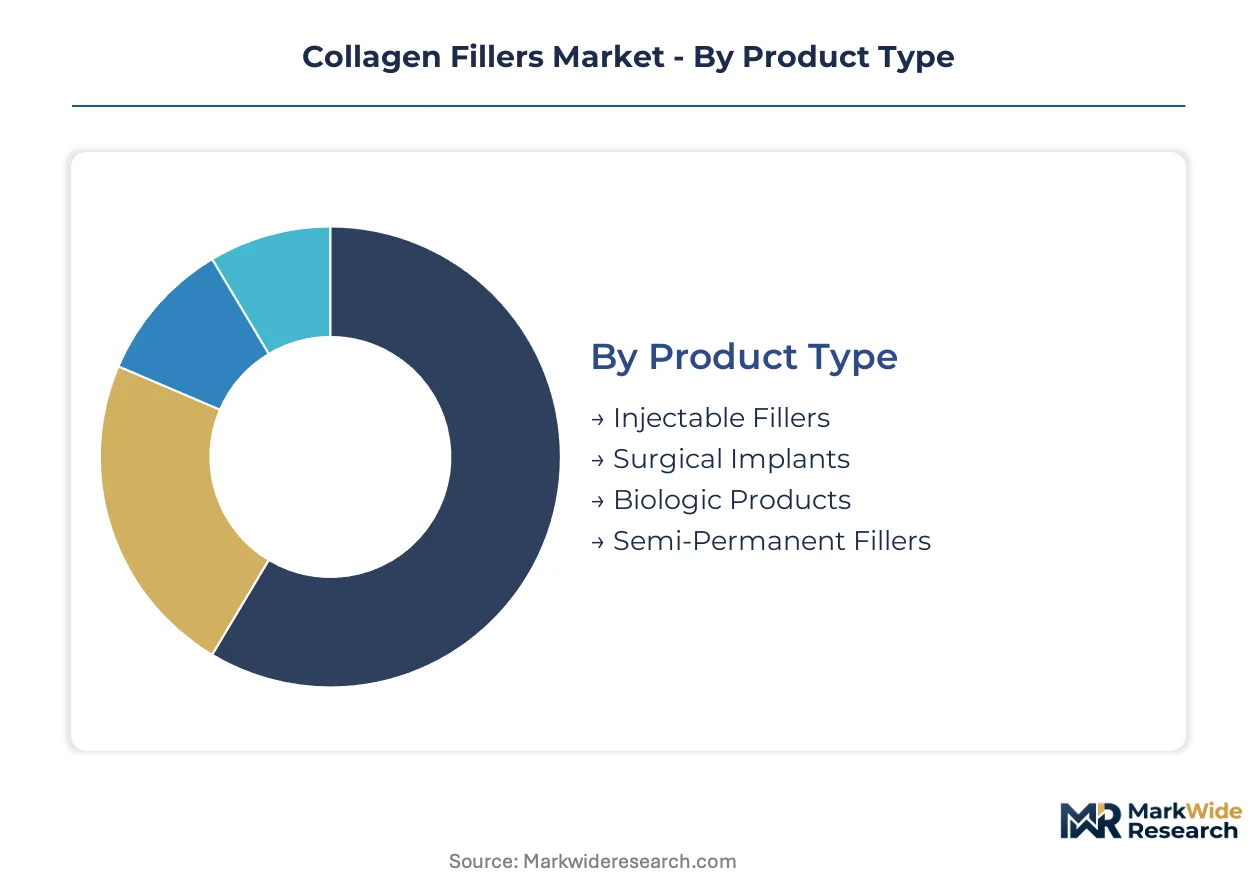
Collagen filler purchasing patterns diverge sharply across clinical settings and patient demographics, with procedure type dictating product viscosity, cross-linking density, and volume requirements. Manufacturers calibrate formulation portfolios around these distinct usage profiles rather than pursuing universal platform strategies.
Product Type:
Replacement cycles and upgrade trajectories vary dramatically across collagen delivery formats, with reversibility concerns and longevity expectations driving portfolio migration patterns.
- Injectable Fillers:Cross-linked aqueous gels formulated for dermal or subdermal injection via fine-gauge needles dominate current revenue pools. Demand concentrates in South Korea's Gangnam clinic corridor, where high procedure density and injector specialization sustain premium pricing for immediate-result formulations.
- Biologic Products:Recombinant human collagen and human-biosynthetic constructs eliminate bovine and porcine immunogenicity risks through cell-culture production methods. Adoption is accelerating fastest in Middle Eastern markets where religious dietary restrictions previously blocked animal-derived alternatives.
- Surgical Implants:Solid collagen matrices for subcutaneous placement during operative procedures.
- Semi-Permanent Fillers:Moderately cross-linked formulations engineered for extended residence time.
Volume placements concentrate in Injectable Fillers; the faster expansion belongs to Biologic Products.
Application:
Cost-tier stratification across aesthetic procedures creates distinct margin profiles, with facial contouring commanding premium positioning relative to maintenance-oriented treatments.
- Facial Contouring:Cheek, jawline, and temple volumizing procedures require higher per-treatment product volumes and specialized injector training in deep-plane placement techniques. Demand clusters in California and Florida med-spa chains, where bundled membership pricing lifts annual per-patient spend.
- Wrinkle Reduction:Nasolabial fold and perioral line treatments represent the entry-level application segment. South Korean dermatology practices report compressed margins here as hyaluronic acid alternatives capture price-sensitive first-time patients.
- Lip Enhancement:Vermilion border and philtral column augmentation procedures.
- Scar Treatment:Atrophic acne and surgical scar revision applications.
Facial Contouring generates the highest per-procedure revenue; Lip Enhancement shows the steepest expansion trajectory among younger demographic cohorts.
End User:
Customer-type segmentation reveals divergent procurement authority structures, with institutional buyers prioritizing quality certification over brand recognition.
- Dermatology Practices:Board-certified specialists with procedural autonomy drive adoption of advanced cross-linking technologies. Germany's university-affiliated dermatology departments now specify atelocollagen constructs for reconstructive protocols.
- Cosmetic Clinics:Independent aesthetic medicine facilities concentrate volume in high-turnover facial applications.
- Medical Spas:Hybrid retail-clinical settings with subscription-based patient retention models.
- Hospitals:Institutional procurement departments increasingly mandate ISO 13485 certification for vendor qualification.
Dermatology Practices anchor premium product adoption; Medical Spas are gaining share fastest through membership-based volume commitments.
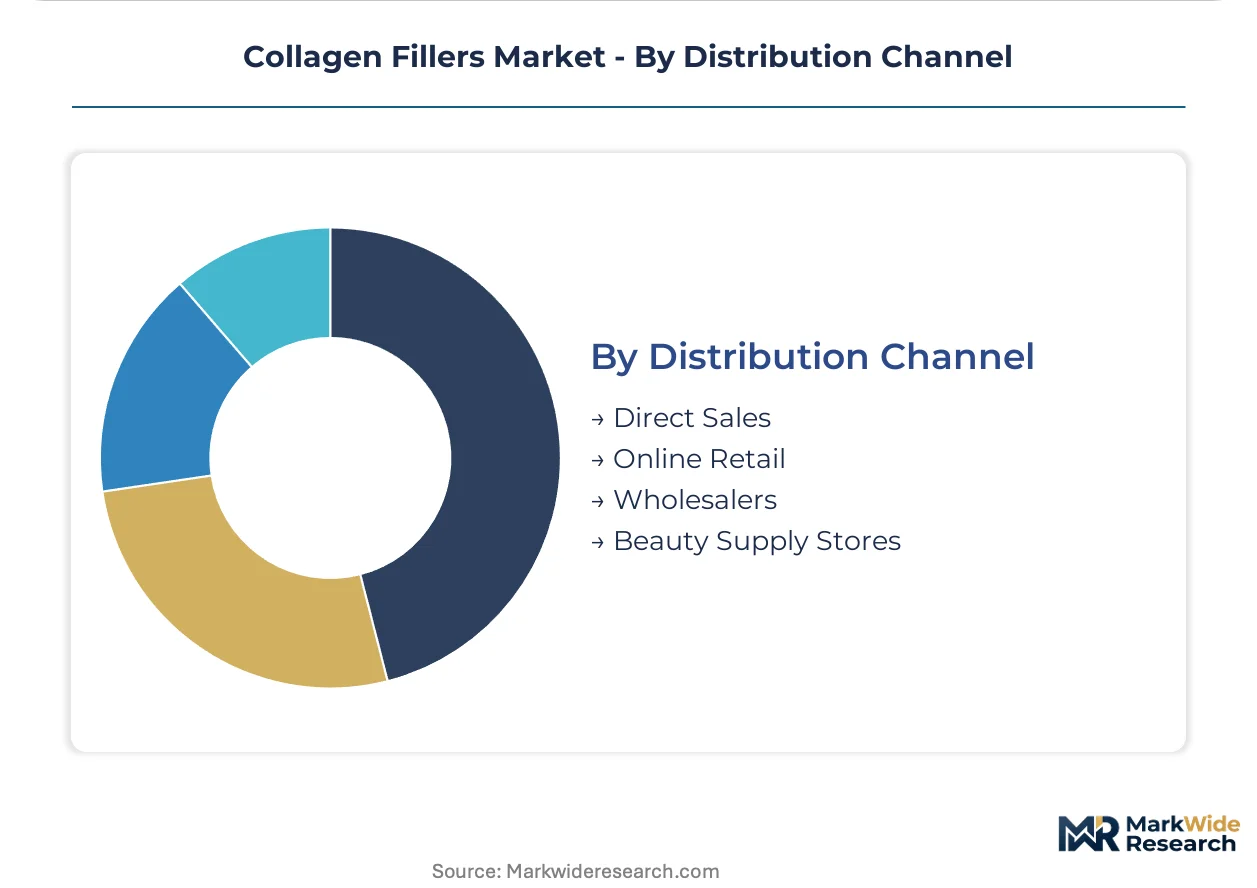
Distribution Channel:
Supply concentration in direct sales relationships reflects the specialized handling requirements and cold-chain sensitivity of collagen formulations.
- Direct Sales:Manufacturer-to-clinic relationships dominate pharmaceutical-grade collagen distribution. Brazil's ANVISA-registered products move exclusively through this channel to ensure temperature integrity.
- Wholesalers:Regional medical supply distributors serve secondary markets.
- Online Retail:E-commerce penetration remains limited by storage temperature requirements.
- Beauty Supply Stores:Non-clinical retail channels for cosmetic-grade topical preparations.
Direct Sales captures the majority of volume placements; Online Retail is expanding fastest among established patients with predictable reorder patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade collagen feedstock concentrates in specialized abattoir networks across the United States and Brazil, anchoring regional manufacturing capacity and shaping procurement patterns for formulators worldwide.
United States
Board-certified dermatology practices in California and Florida drive procedural volume through bundled membership pricing models. The FDA maintains stringent premarket notification pathways under its biologics and 510(k) frameworks for collagen-based devices. Boston's academic medical centers now specify atelocollagen constructs for reconstructive protocols, compressing segmentation between aesthetic and medical-grade categories.
South Korea
Gangnam's clinic corridor sustains premium pricing for immediate-result formulations through high procedure density and injector specialization. The MFDS operates streamlined biologics approval frameworks that accelerate novel construct market entry. Seoul-based clinical trial sites generate first-in-human data that manufacturers leverage for subsequent regulatory submissions in other jurisdictions.
Germany
University-affiliated dermatology departments prioritize atelocollagen formulations with demonstrated immunogenicity reduction profiles. The EU Medical Device Regulation imposes enhanced clinical evidence requirements that extend recertification timelines for implantable aesthetic products. Frankfurt's hospital procurement departments increasingly mandate ISO 13485 certification for vendor qualification in institutional tender processes.
Brazil
ANVISA-registered products move exclusively through direct manufacturer-to-clinic channels to ensure cold-chain integrity. The country's specialized abattoir networks supply pharmaceutical-grade dermal matrix to non-vertically integrated formulators, creating single-source vulnerability. São Paulo's aesthetic medicine infrastructure attracts training academy partnerships from collagen brands seeking first-mover positioning.
Japan
PMDA oversight maintains rigorous safety surveillance protocols that delay market entry for novel formulations but elevate practitioner confidence. METI initiatives support recombinant human collagen platform development to reduce import dependence on animal-derived feedstocks. Tokyo's dermatology practices report accelerating adoption of biosynthetic constructs for patients with bovine and porcine sensitivities.
Collagen Fillers Market Vendor Landscape
Backward integration into raw material supply dominates the current landscape as manufacturers seek resilience against feedstock concentration risks. The vendor base structures around three tiers: diversified pharmaceutical conglomerates with dermatology channel control, specialized aesthetics companies with focused R&D operations, and emerging biosynthetic platform developers. Strategic archetypes include vertically integrated biologics specialists, cross-linking technology innovators, and recombinant production platform builders. M&A activity and capacity expansion represent the dominant competitive moves, with mid-tier manufacturers acquiring ISO 13485-certified facilities to qualify for hospital procurement tenders.
Within the diversified pharmaceutical tier, Allergan (AbbVie) and Johnson & Johnson occupy positions anchored by established dermatology distribution infrastructure and broad channel relationships. Merz Pharma GmbH & Co. KGaA exemplifies the specialized R&D archetype through its concentrated focus on cross-linking technologies. These three entities represent distinct strategic postures: captive supply chain control, high-volume filler distribution, and formulation longevity optimization respectively.
| Leading Market Players |
|---|
| Allergan (AbbVie) |
| Johnson & Johnson |
| Merz Pharma GmbH & Co. KGaA |
| Collplant Holdings Ltd |
| Suneva Medical |
| Sinclair Pharma |
| Ortho Dermatologics |
| Sunmax Biotechnology Co., Ltd. |
| EURORESEARCH s.r.l. |
| Others |
Supply Flow & Price Mechanics
Captive supply of Type I collagen feedstock anchors both manufacturing resilience and pricing authority for vertically integrated manufacturers, while non-integrated formulators absorb volatility from the three specialized abattoir networks in the United States and Brazil. This structural asymmetry compresses margins for mid-tier players unable to secure long-term offtake agreements or biosynthetic alternatives.
Pricing Analysis
Warranty-backed cold-chain guarantees now separate premium collagen constructs from unbundled commodity offerings, with temperature excursion liability shifting to manufacturers in direct sales relationships. Three-tier pricing structure across premium, standard, and economy levels stratifies by cross-linking density and ISO 13485 certification status, with hospital procurement departments least sensitive to price and cosmetic clinics most responsive to volume discounts. Pricing pressure stems from hyaluronic acid substitution in wrinkle reduction segments, compressing trial rates among patients under forty-five.
Supply Chain Analysis
Polymer chemistry expertise scarcity in Boston and Frankfurt constrains R&D throughput for second-generation cross-linking technologies, forcing manufacturers to compete for aging academic specialists. Pharmaceutical-grade dermal matrix concentrates in United States and Brazilian abattoir networks, with recombinant human collagen platforms drawing from Japanese and South Korean cell-culture facilities. Single-source vulnerability in animal-derived feedstocks elevates biosynthetic investment priorities. Distribution runs through direct manufacturer-to-clinic channels to preserve cold-chain integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collagen fillers market operates as a cost-of-compliance story where the FDA's enhanced pharmacovigilance mandates for novel biologic sources erect formidable barrier-to-entry moats for established players with cleared portfolios.
For Market Incumbents: Hedge against hyaluronic acid substitution by deepening cross-linking R&D partnerships with German and Japanese university departments, while securing captive supply agreements with ANVISA-registered Brazilian abattoirs to neutralize feedstock concentration risks. ISO 13485 certification investment unlocks hospital procurement tenders that competitors forfeit. For New Entrants and Emerging Players: Hospital-based dermatology departments represent the most penetrable buyer archetype for atelocollagen constructs with demonstrated immunogenicity reduction, particularly in Germany where EU MDR compliance has thinned the vendor pool. Recombinant human collagen platforms bypass religious restriction barriers in Middle Eastern markets where animal-derived alternatives face exclusion. Prioritize training academy partnerships in Ho Chi Minh City and Jakarta to capture clinic expansion outpacing trained injector supply. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking dermatology channel control, with mid-tier manufacturers holding ISO 13485-certified facilities commanding strategic premiums. Long-term viability hinges on biosynthetic platform scalability rather than animal-derived feedstock dependence. Watch for MFDS fast-track approvals as inflection indicators for platform validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive dermal matrix sourcing from Brazilian ANVISA-registered abattoirs neutralizes single-source vulnerability for non-vertically integrated formulators. |
| Cross-Linking Technology Licensing | Carbodiimide and glutaraldehyde reaction kinetics expertise from German academic partnerships extends product longevity in vivo. |
| ISO 13485 Certification Acquisition | Quality management system credentials qualify manufacturers for Frankfurt hospital procurement tenders and institutional vendor lists. |
| Recombinant Platform Development | Cell-culture production methods eliminate bovine spongiform encephalopathy screening burdens and porcine religious restrictions in Middle Eastern markets. |
| Training Academy Partnership Expansion | Injector education infrastructure in Ho Chi Minh City and Jakarta captures first-mover advantage where clinic density outpaces skilled practitioner supply. |
Methodological Framework
Independent corroboration across dermatology practice administrators, biomedical engineers at university-affiliated departments, GPO contracts managers, and regulatory affairs specialists at collagen manufacturers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA 510(k) filings, MFDS biologics approval databases, EU MDR recertification records, and ANVISA registration documents anchors the analysis. Bottom-up procedure volume estimates from clinic billing systems triangulate against top-down manufacturer shipment data across the analysis window.
Comparable historical reference periods anchored the projection horizon to observed replacement cycles and upgrade trajectories across injectable, biologic, and surgical implant formats. The analytical framework modeled segmentation across product viscosity tiers, application types from facial contouring to scar treatment, end-user procurement authority structures, and regional regulatory clusters. CAGRs derived from fitted growth curves incorporate cross-linking chemistry advancement rates and biosynthetic platform adoption curves as industry-specific inputs.
Revisions become necessary when FDA guidance shifts on biologic injectable pharmacovigilance protocols, when MFDS fast-track pathways expand or contract, or when recombinant human collagen production achieves cost parity with animal-derived alternatives. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
India Hair Transplant Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
South Korea Hair Transplant Market