
 Asia-Pacific Aesthetic Dermatology Market | 2026-2036
Asia-Pacific Aesthetic Dermatology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aesthetic Dermatology Market Outlook
Younger millennial and Gen-Z consumers is bifurcating demand away from traditional anti-aging patients toward preventive aesthetic maintenance. AbbVie Inc. leverages its Allergan Aesthetics portfolio to dominate injectable neurotoxin segments across Japan and Australia. Galderma anchors its position through R&D intensity in biostimulatory fillers and integrated skincare protocols. Hugel Inc. competes aggressively on manufacturing scale, supplying botulinum toxin at price points that undercut Western rivals in Southeast Asian markets.
Asia-Pacific aesthetic dermatology encompasses energy-based devices, injectable biologics, and topical resurfacing agents designed to modify skin appearance through collagen remodeling, neuromuscular modulation, or selective photothermolysis. Laser devices and radiofrequency platforms operate at wavelengths between 532 nm and 10,600 nm to target chromophores in epidermal and dermal tissues. Botulinum toxin and dermal fillers command the largest revenue pools due to repeat purchase cycles and low switching costs among clinic buyers. Non-invasive technology segments are capturing disproportionate growth as recovery-time sensitivity rises among working professionals in dense metropolitan markets.
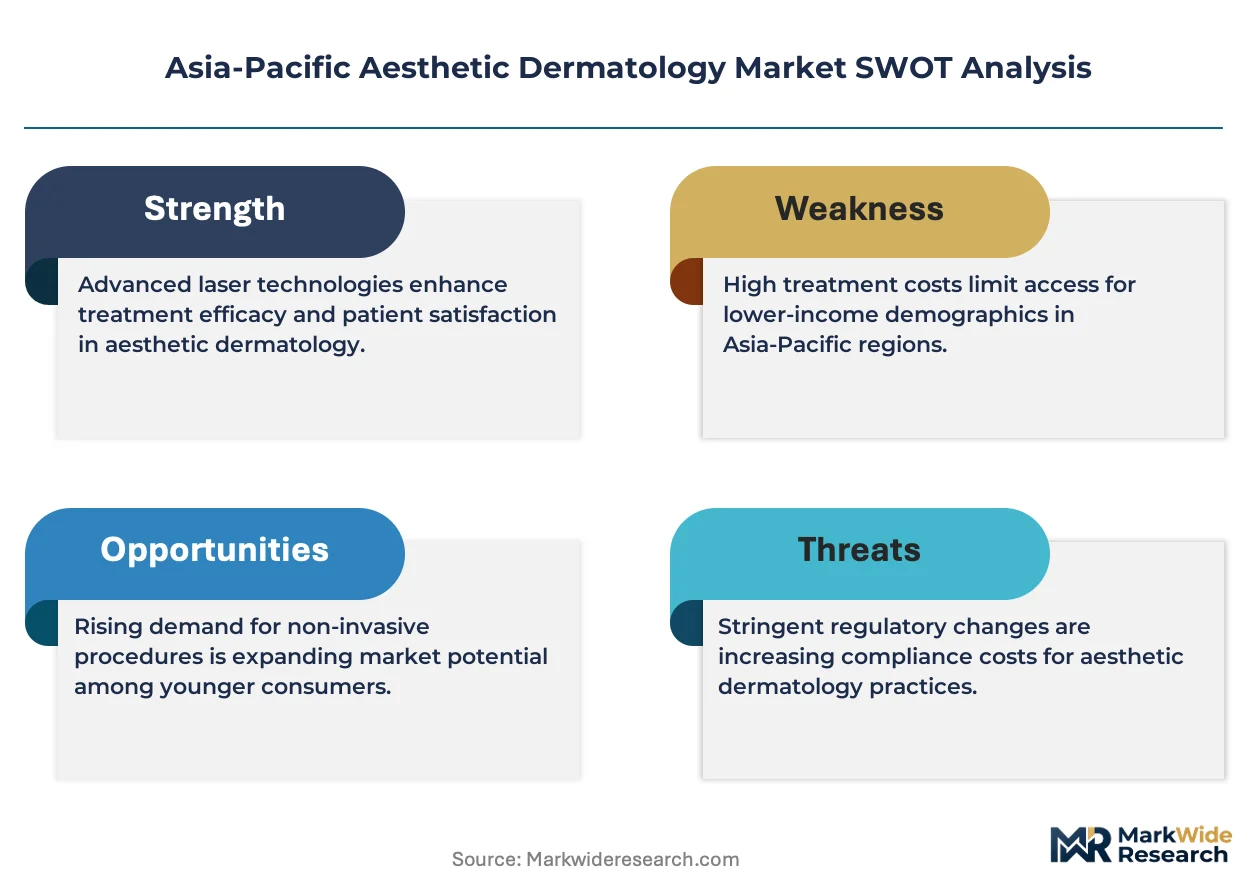
MFDS in South Korea, NMPA in China, and TGA in Australia enforce divergent clinical evidence standards that fragment product registration strategies and delay cross-border launches. China's SAMR recently tightened advertising rules for aesthetic procedures, forcing clinics to revise patient acquisition channels toward physician-led education. Japan's PMDA maintains stringent stability testing for hyaluronic acid fillers that elevates compliance costs for new entrants. Stakeholders must monitor regulatory harmonization talks between ASEAN member states, as mutual recognition agreements could reshape competitive access across Southeast Asian clinic networks.
Market Dynamics
Preventive aesthetic protocols among millennial and Gen-Z cohorts are compressing treatment intervals and expanding addressable patient pools beyond traditional anti-aging demographics. This generational pivot is restructuring clinic revenue models and device utilization patterns across metropolitan centers.
Growth Catalysts
- MFDS Accelerated Pathways:South Korea's streamlined device approval routes reduce registration timelines for energy-based platforms, enabling faster commercialization of radiofrequency and laser systems in Seoul's premium clinic networks.
- Urban Middle-Class Expansion:Disposable income concentration in Shanghai, Tokyo, and Singapore is driving recurring expenditure on neuromodulator maintenance and collagen-stimulating injectables.
- Non-Invasive Technology Maturation:Fractional laser and high-intensity focused ultrasound platforms now deliver comparable outcomes to ablative procedures with minimal downtime, capturing working professional segments.
Market Restraints
- Hyaluronic Acid Raw Material Concentration:Pharmaceutical-grade HA feedstock supply concentrates among three dominant biotech suppliers, exposing filler manufacturers to input cost volatility and allocation constraints.
- PMDA Stability Testing Burden:Japan's stringent three-year shelf-life validation requirements for cross-linked gel formulations elevate compliance expenditures and delay market entry for novel rheology profiles.
- Intense Pulsed Light Substitution:Lower-cost IPL platforms in tier-two Chinese cities capture price-sensitive patients seeking photorejuvenation, compressing margins for premium laser device placements.
Strategic Opportunities
- Vietnam and Indonesia Penetration:Ho Chi Minh City and Jakarta exhibit sub-15% clinic density relative to Bangkok, presenting first-mover expansion potential for standardized franchise protocols.
- SAMR Advertising Reform Arbitrage:China's tightened aesthetic marketing rules force patient acquisition toward physician education platforms, rewarding clinics with established KOL networks and proprietary content channels.
- Biostimulator-Skincare Convergence:Integrated treatment protocols combining injectable poly-L-lactic acid with physician-dispensed topicals are capturing premium pricing in Sydney and Melbourne dermatology practices.
Industry Challenges
- Injector Certification Bottlenecks:Qualified practitioner scarcity in Manila and Kuala Lumpur limits procedural volume expansion despite installed device capacity, constraining clinic network scalability.
- Cross-Border Device Registration Complexity:Divergent clinical evidence requirements between MFDS, NMPA, and TGA force manufacturers to duplicate trials, extending product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aesthetic Dermatology Market |
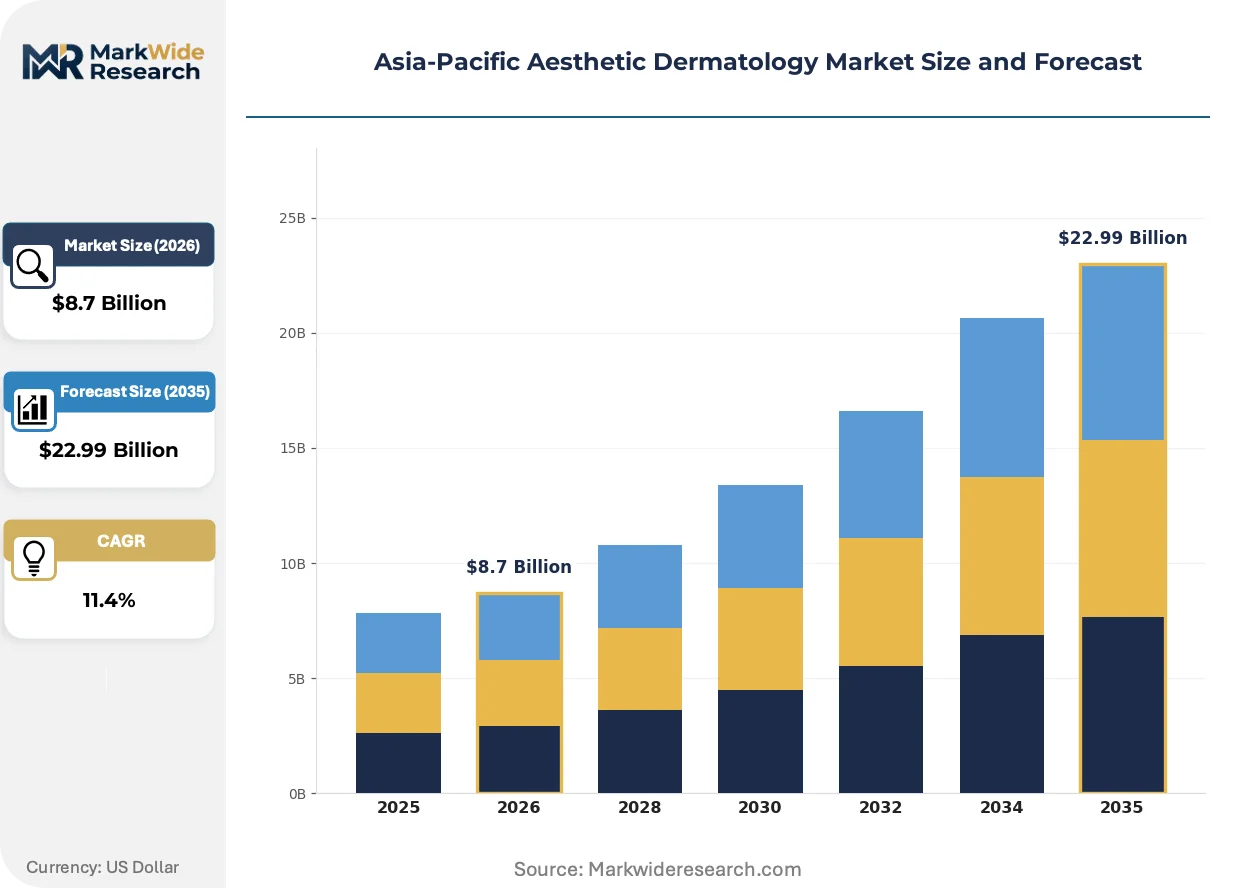
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Dermal Fillers, Peels, Laser Devices Application: Anti-Aging, Skin Rejuvenation, Hair Removal, Acne Treatment End User: Clinics, Hospitals, Home Users, Med Spas Technology: Non-Invasive, Minimally Invasive, Surgical, Radiofrequency |
| Companies Covered | AbbVie Inc., Merz Pharma, Galderma, Medytox, Hugel Inc., Candela Medical, Cutera Inc., Lumenis Ltd., Bausch Health Companies Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aesthetic Dermatology Market Strategic Shifts
Technology convergence and regulatory recalibration are reshaping competitive positioning across the Asia-Pacific aesthetic dermatology landscape. Device manufacturers and clinic operators are restructuring around shortened innovation cycles and intensified compliance requirements.
Microfocused ultrasound with visualization is fragmenting the non-surgical lifting segment by enabling precise energy delivery at customizable depths. Premium clinics in Osaka and Hong Kong are adopting the technology at replacement pace for older mono-frequency platforms. This capability expansion is fragmenting patient flows between dermatologists and plastic surgeons who previously controlled surgical alternatives.
NMPA's 2023 medical device classification reforms are elevating clinical evidence standards for radiofrequency microneedling systems. Domestic Chinese manufacturers face expanded trial obligations that favor multinational sponsors with established biocompatibility dossiers. Imported energy-based platforms with prior FDA or CE documentation are capturing accelerated review slots in Shanghai and Beijing regulatory submissions.
Subscription-based maintenance programs are displacing episodic treatment purchasing in Seoul's Gangnam district clinic clusters. Younger patients lock in quarterly neurotoxin intervals through prepaid annual contracts, shifting revenue recognition patterns for injectable suppliers. This behavioral pivot is most visible in South Korea's saturated aesthetic market where patient lifetime value competition has intensified among med spa chains.
Asia-Pacific Aesthetic Dermatology Market Segmentation
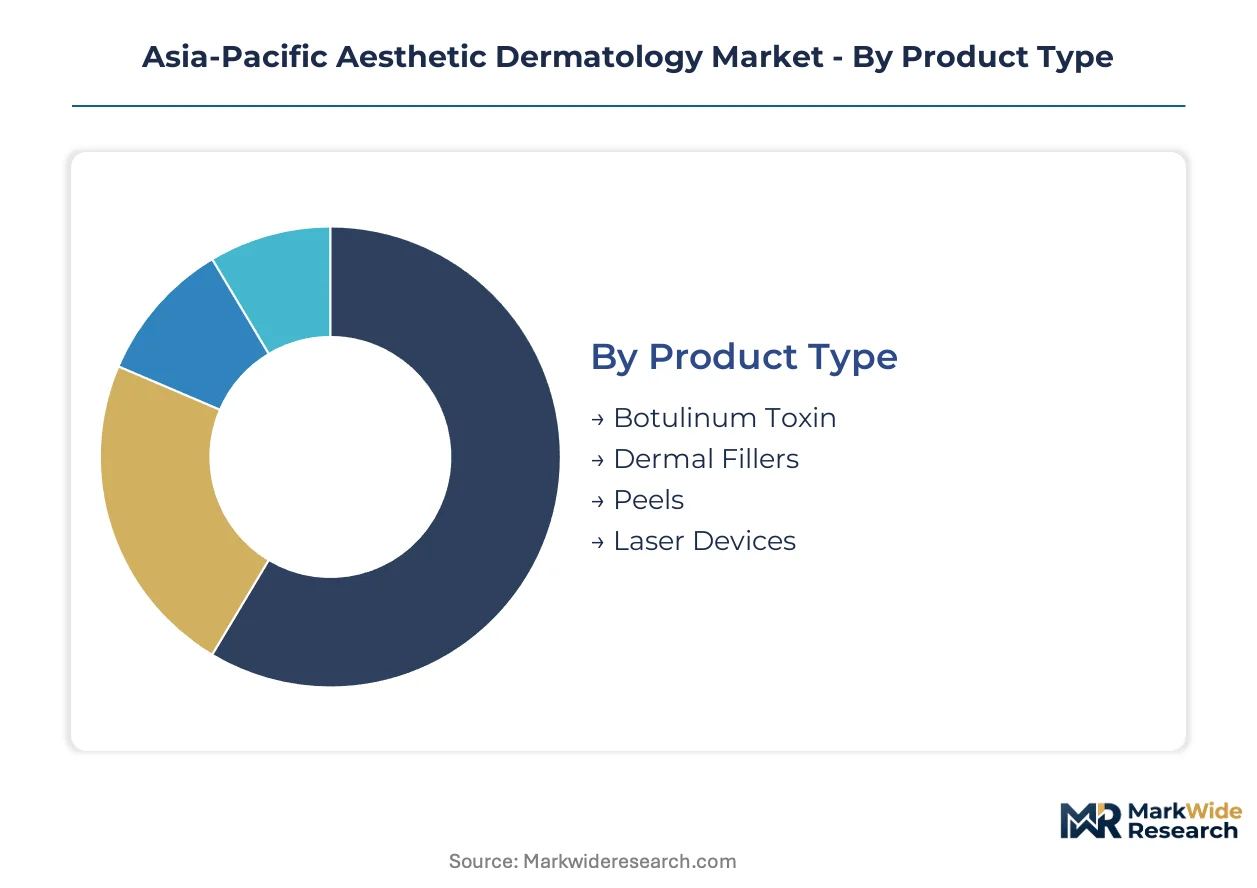
Segmentation in Asia-Pacific aesthetic dermatology reveals how regulatory pathways, procedural settings, and technology interfaces reshape commercial strategy. Each dimension carries distinct margin profiles and compliance burdens across South Korea, China, and Japan.
Product Type:
MFDS, NMPA, and PMDA impose divergent stability and biocompatibility standards that fragment registration economics across injectable and device categories.
- Botulinum Toxin:Purified neuroprotein formulations require cold-chain distribution and repeat injection cycles. Demand clusters in Seoul's Gangnam district and Shanghai's Jing'an district where subscription maintenance programs now dominate clinic revenue.
- Dermal Fillers:Cross-linked hyaluronic acid and biostimulatory gels command premium pricing in Tokyo's Aoyama clinic corridor. PMDA's three-year shelf-life validation elevates compliance costs for novel rheology profiles entering Japan.
- Peels:Chemical resurfacing agents with glycolic, salicylic, and trichloroacetic acid concentrations suit price-sensitive segments in Bangkok and Kuala Lumpur.
- Laser Devices:Fractional and ablative platforms operating at 532 nm to 10,600 nm wavelengths target chromophores in epidermal and dermal tissues.
Botulinum toxin handles the majority of throughput; dermal fillers are the fastest mover on share.
Application:
Generational demand bifurcation is restructuring treatment intervals and patient acquisition costs across metropolitan clinic networks.
- Anti-Aging:Traditional wrinkle reduction and volume restoration protocols target patients aged 45-65. China's SAMR advertising reforms have forced clinics toward physician-led education channels for this demographic.
- Skin Rejuvenation:Photodamage correction and texture improvement procedures now capture millennial and Gen-Z cohorts seeking preventive maintenance in Singapore and Sydney.
- Hair Removal:Laser and IPL-based permanent reduction treatments concentrate in Vietnam's emerging Ho Chi Minh City clinic clusters.
- Acne Treatment:Energy-based sebaceous gland modulation and topical-isotretinoin protocols address persistent inflammatory conditions in Jakarta's young professional segments.
Anti-aging retains the largest installed procedure base; skin rejuvenation is expanding most quickly among younger patient cohorts.
End User:
Facility type determines reimbursement pathways, practitioner certification requirements, and capital equipment depreciation schedules.
- Clinics:Dermatology and plastic surgery practices with dedicated aesthetic units dominate procedural volume in Osaka and Hong Kong.
- Hospitals:Academic medical centers with aesthetic surgery departments handle complex reconstructive cases and complication management in Beijing and Tokyo.
- Home Users:Consumer-grade LED masks and microcurrent devices capture preventive maintenance demand among cost-conscious segments in Manila.
- Med Spas:Hybrid retail-clinical environments with standardized franchise protocols are penetrating underserved Indonesian and Vietnamese markets.
Clinics process the highest procedure density; med spas are gaining share fastest through franchise expansion.
Technology:
Invasiveness tier directly correlates with recovery time, practitioner credentialing requirements, and pricing power in dense metropolitan markets.
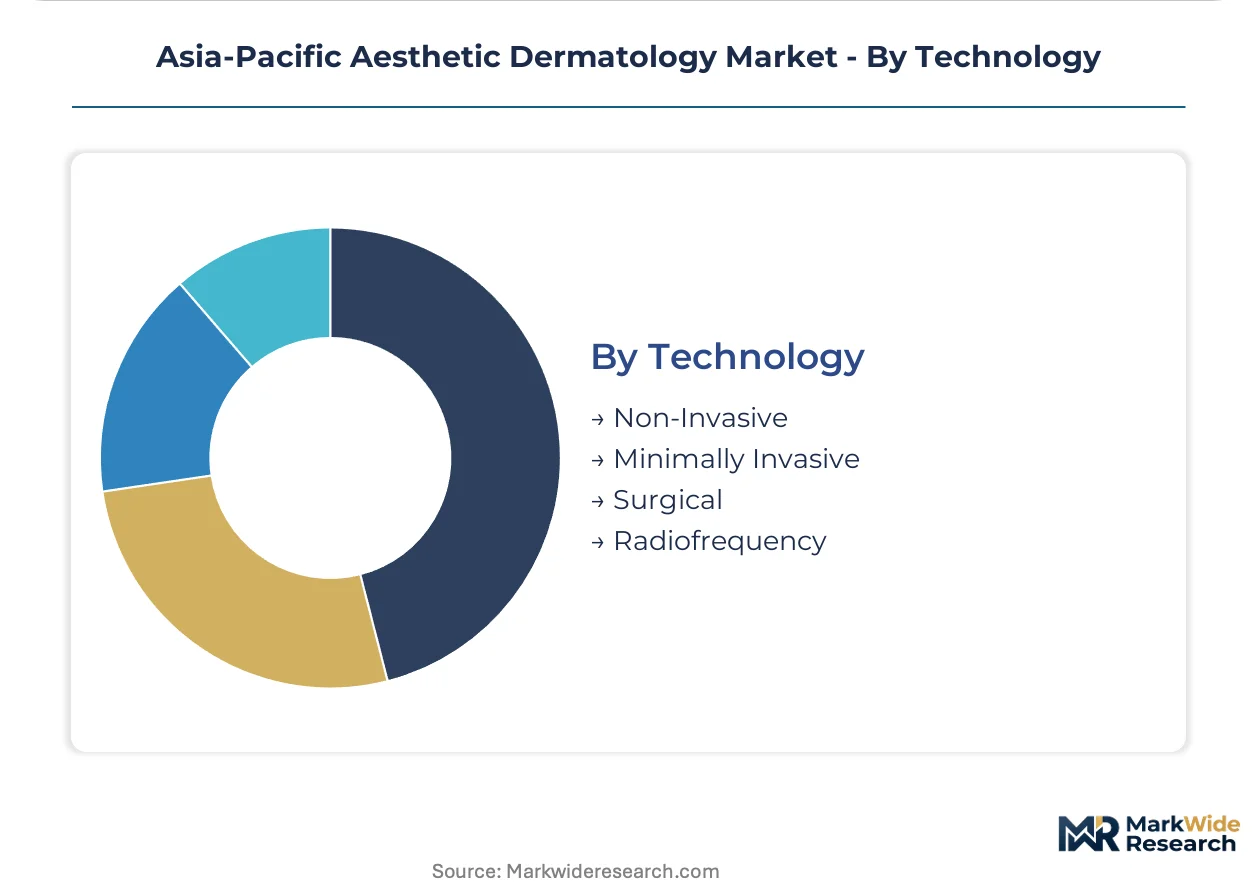
- Non-Invasive:Topical agents, LED therapy, and superficial chemical peels require no anesthesia and minimal downtime. Working professionals in Shanghai and Singapore prioritize these modalities for lunch-hour scheduling.
- Minimally Invasive:Injectable neurotoxins, fillers, and microneedling procedures capture the largest revenue pool across Asia-Pacific due to repeat purchase cycles and low switching costs.
- Surgical:Blepharoplasty, rhytidectomy, and liposuction procedures concentrate in Seoul's premium hospital networks with JCI accreditation.
- Radiofrequency:Monopolar and bipolar energy delivery systems for skin tightening and fat reduction are displacing older mono-frequency platforms in Melbourne and Sydney.
Minimally invasive technology commands the dominant revenue share; non-invasive modalities are climbing the fastest as recovery-time sensitivity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean device manufacturers export radiofrequency and laser platforms to premium clinic networks across Shanghai, Tokyo, and Singapore. This trade corridor channels Seoul's manufacturing scale toward Asia-Pacific's densest metropolitan aesthetic markets.
China
NMPA's 2023 medical device classification reforms elevated clinical evidence standards for radiofrequency microneedling systems. SAMR tightened aesthetic advertising rules, forcing clinics toward physician-led education channels. Shanghai and Beijing regulatory submissions now prioritize imported energy-based platforms with prior FDA or CE documentation.
South Korea
MFDS accelerated approval pathways compress registration timelines for energy-based platforms. Subscription-based maintenance programs now dominate Gangnam district clinic clusters, locking younger patients into quarterly neurotoxin intervals. Seoul's premium clinic networks drive procedural volume through prepaid annual contracts.
Japan
PMDA enforces stringent three-year shelf-life validation requirements for cross-linked hyaluronic acid gel formulations. Tokyo's Aoyama clinic corridor commands premium pricing for dermal fillers and biostimulatory injectables. Compliance costs for novel rheology profiles elevate barriers for new market entrants.
Australia
TGA clinical evidence standards diverge from MFDS and NMPA requirements, fragmenting product registration strategies. Sydney and Melbourne dermatology practices capture premium pricing through integrated protocols combining injectable poly-L-lactic acid with physician-dispensed topicals. Working professionals prioritize non-invasive modalities for minimal downtime.
Vietnam
Ho Chi Minh City exhibits sub-15% clinic density relative to Bangkok, presenting first-mover expansion potential for standardized franchise protocols. Hair removal treatments concentrate in emerging clinic clusters serving young professional segments. Med spa chains target underserved markets through hybrid retail-clinical environments.
Asia-Pacific Aesthetic Dermatology Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and geographic expansion dimensions. The vendor base fragments across three tiers: multinational pharmaceutical conglomerates with aesthetics divisions, dedicated dermatology device manufacturers, and regional toxin suppliers competing on manufacturing scale. Strategic archetypes include portfolio diversifiers expanding through acquisition, technology licensors monetizing platform patents, and price competitors leveraging captive manufacturing. M&A activity concentrates on biostimulatory filler capabilities, while capacity expansion targets Southeast Asian distribution infrastructure.
Within the pharmaceutical conglomerate tier, AbbVie Inc. and Galderma exemplify portfolio-heavy positioning anchored by injectable biologics. Hugel Inc. occupies a distinct archetype as a Korea-based manufacturer supplying botulinum toxin at price points that undercut Western rivals across Southeast Asian markets. These three entities represent the dominant competitive anchors shaping procurement patterns for clinic buyers from Seoul to Jakarta.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Merz Pharma |
| Galderma |
| Medytox |
| Hugel Inc. |
| Candela Medical |
| Cutera Inc. |
| Lumenis Ltd. |
| Bausch Health Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
MFDS accelerated approval pathways in South Korea gate both supply qualification and price differentiation simultaneously, as faster registration timelines for Seoul-manufactured energy devices compress price premiums for competing imports while elevating compliance costs that filter out low-tier entrants. This regulatory arbitrage concentrates pricing power among manufacturers with established biocompatibility dossiers and cold-chain infrastructure.
Pricing Analysis
Current-generation radiofrequency microneedling platforms command 40-60% price premiums over prior-generation mono-frequency systems in Gangnam district clinic clusters, while next-generation microfocused ultrasound with visualization is capturing additional uplift through prepaid annual subscription contracts. Pricing stratifies across premium, standard, and economy tiers based on FDA or CE documentation status and practitioner certification level. Cost compression in economy-tier IPL platforms is intensifying because lower-cost domestic Chinese manufacturers are flooding tier-two city markets. Price sensitivity concentrates among first-time patients in Ho Chi Minh City and Jakarta, while Seoul's saturated aesthetic market exhibits inelastic demand for premium-tier biostimulatory fillers.
Supply Chain Analysis
South Korea and China anchor pharmaceutical-grade hyaluronic acid feedstock production, with Seoul-based biotech suppliers commanding allocation priority for cross-linked gel formulations used in Tokyo's Aoyama clinic corridor. Raw material dependencies center on bacterial fermentation-derived HA, medical-grade stainless steel for microneedling cartridges, and precision optical components for fractional laser systems. Single-source vulnerability concentrates in HA feedstock supply, where three dominant biotech suppliers expose filler manufacturers to input cost volatility. Distribution runs through specialized medical device distributors with cold-chain capabilities, feeding directly into premium clinic networks and med spa franchise operations across metropolitan Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific aesthetic dermatology represents a high-growth disruption as NMPA's 2023 medical device classification reforms elevate clinical evidence standards, forcing competitive restructuring around biocompatibility dossiers and physician-led patient acquisition channels.
For Market Incumbents: Fortify procurement relationships with Seoul-based HA feedstock suppliers through long-term offtake agreements, locking in allocation priority before capacity constraints tighten. Expand backward integration into bacterial fermentation capacity to neutralize input cost volatility from the three-dominant-supplier concentration. Invest in MFDS pre-submission consultations to compress registration timelines for next-generation radiofrequency platforms, defending against emerging entrants with prior FDA documentation.
For New Entrants and Emerging Players: Subscription-based maintenance program penetration in South Korea's saturated Gangnam district reveals a service-layer gap where incumbents under-serve patient lifetime value optimization through prepaid annual contracts. Target Ho Chi Minh City and Jakarta's sub-15% clinic density relative to Bangkok, where standardized franchise protocols can capture first-mover positioning before multinational chains establish footprint. Deploy physician education platforms as the primary go-to-market angle, arbitraging China's SAMR advertising reforms that force patient acquisition away from direct-to-consumer marketing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biostimulatory filler manufacturing as PMDA stability testing requirements and three-year shelf-life validation protocols elevate compliance expenditures. Long-term viability over the next decade hinges on capturing integrated treatment protocol capabilities combining injectable poly-L-lactic acid with physician-dispensed topicals. Acquisition targets should prioritize regional toxin suppliers with captive manufacturing scale and established Southeast Asian distribution infrastructure. The signal to watch is NMPA regulatory harmonization progress with ASEAN member states, as mutual recognition agreements would reshape competitive access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Pre-Submission Consultation | Compresses registration timelines for Seoul-manufactured radiofrequency platforms entering premium clinic networks. |
| Backward Integration into HA Fermentation | Neutralizes input cost volatility from concentrated pharmaceutical-grade feedstock suppliers. |
| Physician Education Platform Development | Arbitrages China's SAMR advertising reforms by shifting patient acquisition to KOL-led channels. |
| Subscription Maintenance Program Launch | Captures patient lifetime value through prepaid annual neurotoxin contracts in saturated metropolitan markets. |
| ASEAN Franchise Protocol Standardization | Enables rapid replication across Ho Chi Minh City and Jakarta's underserved clinic density markets. |
Study Parameters
Initial hypotheses were tested against primary input from aesthetic clinic operators, biomedical device regulatory consultants, pharmaceutical-grade HA procurement managers, and dermatology practice owners, and refined through secondary validation against MFDS registration databases, NMPA medical device classification filings, PMDA stability testing guidelines, and hospital procurement contract repositories. Bottom-up procedure volume estimates from Seoul, Shanghai, and Tokyo clinic clusters were triangulated with top-down market sizing derived from import-export customs data and distributor shipment records.
Variance decomposition across the projection horizon isolates volume drivers by technology invasiveness tier, regulatory pathway complexity, and metropolitan market saturation level. Segmentation dimensions modeled include product type, application indication, end-user facility category, and technology platform generation. CAGRs were derived from fitted growth curves anchored to procedural volume trajectories and pricing trend analysis. Industry-specific forecast inputs incorporate MFDS accelerated pathway utilization rates and NMPA reform implementation timelines.
Material uncertainties — regulatory harmonization delays, HA feedstock supply disruptions, and PMDA stability testing requirement expansions — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued urban middle-class disposable income expansion and working professional recovery-time sensitivity intensification. Recalibration cycles align with material shifts in NMPA classification reforms and ASEAN mutual recognition agreement negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Photorejuvenation Market