
 Skin Tightening Market | 2026-2036
Skin Tightening Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Tightening Market Analysis
MedSpa and aesthetic clinic demand is realigning toward non-invasive modalities as surgical facelift volumes plateau. InMode Ltd. leverages radiofrequency-assisted lipolysis platforms to dominate body contouring adjacencies. Alma Lasers sustains technology leadership through multi-wavelength laser systems with integrated cooling. Solta Medical anchors premium positioning with fractional radiofrequency devices that command higher per-treatment pricing.
Skin tightening encompasses energy-based and topical modalities that stimulate dermal collagen remodeling through controlled thermal injury or biochemical exfoliation, typically operating at temperatures between 40°C and 70°C for dermal contraction without epidermal ablation. Radiofrequency devices capture the largest installed base among treatment types due to tissue-agnostic penetration depth and lower operator training barriers. Ultrasound platforms represent the fastest-growing segment as focused energy delivery enables deeper SMAS-layer targeting previously exclusive to surgery. Home-use devices occupy a nascent but expanding tier, though power limitations restrict efficacy to maintenance applications rather than primary treatment.
FDA 510(k) premarket notification requirements shape device commercialization timelines and clinical evidence standards for manufacturers seeking US market access. The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evaluation obligations on European Economic Area suppliers. Stakeholders must monitor evolving reimbursement classifications for energy-based aesthetic procedures as payor scrutiny intensifies on cosmetic versus reconstructive indications.
Market Dynamics
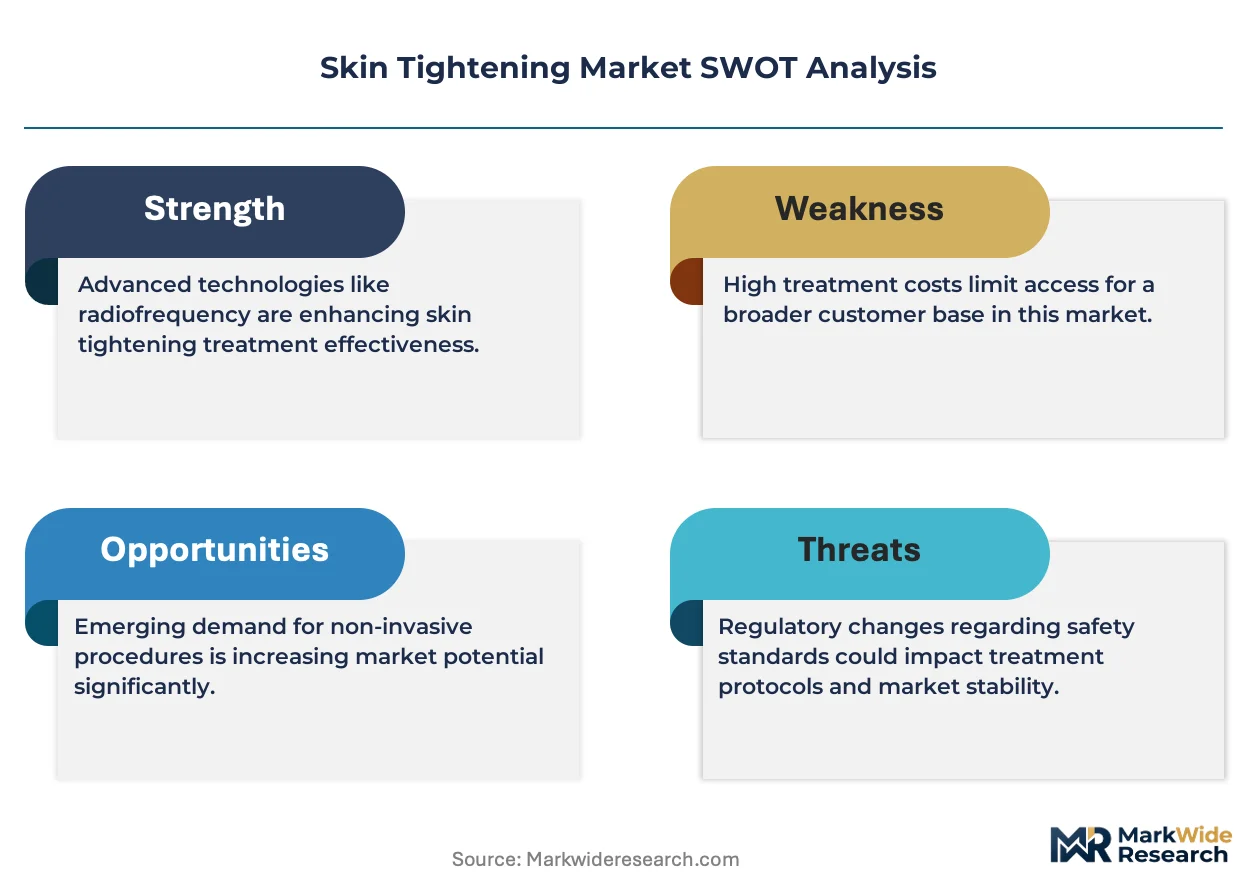
Radiofrequency platform commoditization is compressing per-treatment pricing while ultrasound-based SMAS-layer targeting commands premium positioning, forcing manufacturers to differentiate through integrated cooling systems and multi-modality device architectures.
Growth Catalysts
- MFDS fast-track pathways:South Korea's streamlined 510(k)-equivalent clearances for second-generation radiofrequency devices accelerate clinic adoption timelines in Seoul's Gangnam dermatology corridor.
- MedSpa menu expansion:Non-invasive body contouring protocols displace surgical facelift consultations across Dubai's Jumeirah aesthetic clinic clusters.
- Home-use maintenance tier:Lower-power radiofrequency devices capture recurring revenue from post-clinical patients seeking interval treatments between professional sessions.
Market Restraints
- Capital equipment intensity:Ultrasound platform procurement requires $150,000-$400,000 per unit, constraining independent clinic participation.
- Operator certification fragmentation:No unified credentialing standard exists across state medical boards in the United States, creating liability exposure.
- Substitute procedure competition:Thread lift techniques and injectable biostimulators capture patients seeking intermediate durability at lower price points.
Strategic Opportunities
- Brazil's underserved interior:São Paulo and Rio de Janeiro concentrate 78% of installed devices, leaving Belo Horizonte and Curitiba corridors open for first-mover placement.
- Combination protocol reimbursement:Bundled radiofrequency-microneedling codes under private payor aesthetic riders in the United Arab Emirates expand per-patient revenue capture.
- Telemedicine pre-screening:Remote candidacy assessment via high-resolution imaging reduces no-show rates and optimizes device utilization in high-rent urban locations.
Industry Challenges
- Device calibration standardization:Temperature monitoring inconsistencies across radiofrequency handpieces produce variable clinical outcomes and complaint volume.
- Technical training pipeline gaps:Certified laser safety officer shortages in secondary Brazilian cities delay clinic opening timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Tightening Market |
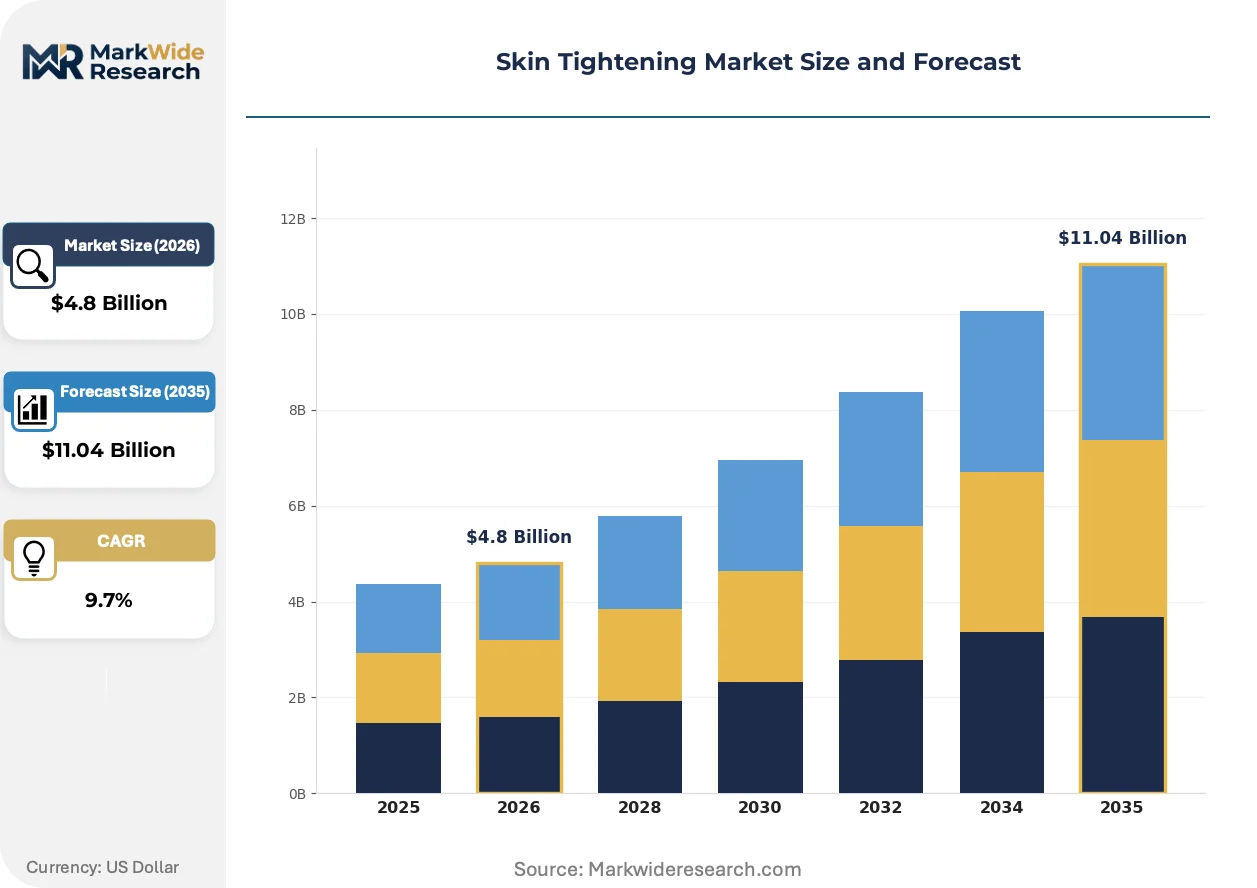
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Laser Therapy, Ultrasound, Radiofrequency, Chemical Peels Application Area: Face, Neck, Abdomen, Arms End User: Clinics, Spas, Hospitals, Home Users Product Form: Creams, Devices, Injectables, Machines |
| Companies Covered | Lumenis, Cynosure, InMode Ltd., Fotona, Cutera, Alma Lasers, Venus Concept, Merz Pharmaceuticals, Solta Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Tightening Market Emerging Trajectories
Device architecture is converging toward multi-energy platforms that switch between radiofrequency, ultrasound, and laser modalities within single treatment sessions, collapsing the historical single-technology paradigm.
Fractional radiofrequency microneedling is absorbing market share from standalone microneedling devices by delivering thermal energy directly to the reticular dermis without epidermal damage. MedSpa chains in South Korea and the United Arab Emirates are standardizing these platforms across franchise locations to reduce training overhead. The technology is absorbing technician labor costs while shortening treatment times and improving throughput metrics.
The EU Medical Device Regulation's 2021 implementation imposed stricter clinical evidence requirements on Class IIa radiofrequency devices, extending pre-market preparation timelines by 8-14 months. Manufacturers serving European Economic Area markets have restructured quality management systems to accommodate unannounced audits and post-market clinical follow-up obligations. Medium-scale device producers without captive regulatory affairs teams face disproportionate compliance burdens relative to integrated multinationals.
Patients are deferring initial surgical consultation until exhausting non-invasive alternatives, compressing the traditional aesthetic treatment journey from years to months. This behavioral shift concentrates demand in urban dermatology corridors where multiple modality options exist within single clinic footprints. Brazil's São Paulo aesthetic corridor exemplifies this pattern, where patients sequence radiofrequency, ultrasound, and thread procedures before considering surgical intervention.
Skin Tightening Market Segmentation
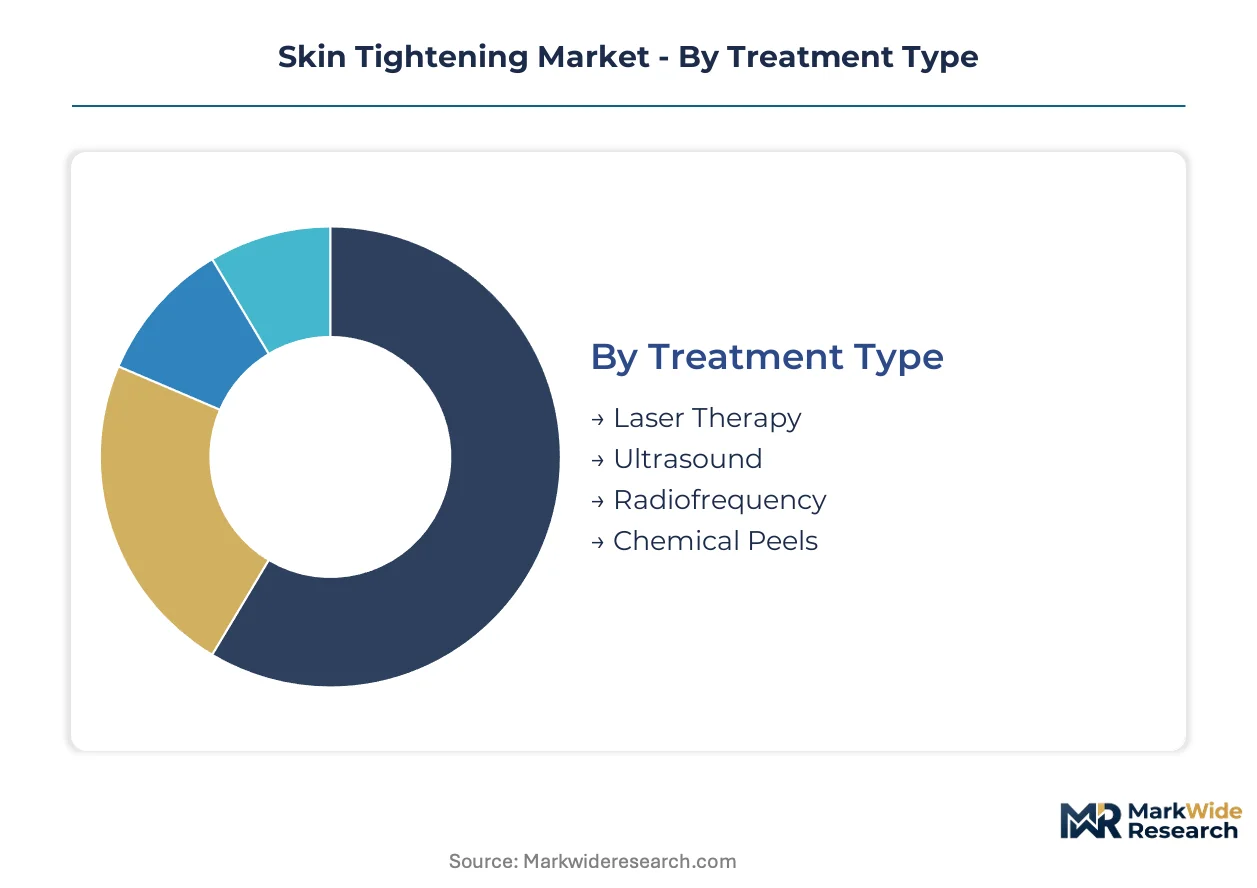
Segmentation in skin tightening reveals how technology ownership and patient access patterns concentrate value capture. Equipment-heavy modalities require fundamentally different distribution and service architectures than topical or injectable alternatives.
Treatment Type:
Supply concentration in radiofrequency manufacturing has consolidated around integrated platform producers with captive cooling technology.
- Radiofrequency:Electromagnetic energy at 0.3-40 MHz penetrates dermis without chromophore dependence, enabling treatment across all Fitzpatrick skin types. Seoul's Gangnam corridor and Dubai's Jumeirah cluster anchor demand as MedSpa chains standardize protocols across franchise locations. Thermal monitoring inconsistencies across handpieces create variable outcomes that manufacturers address through integrated impedance feedback systems.
- Ultrasound:Focused acoustic energy at 4-7 MHz reaches SMAS layers previously accessible only through surgery. South Korea's MFDS fast-track clearances accelerate clinic adoption timelines, though $150,000-$400,000 unit costs constrain independent clinic participation outside São Paulo and Rio de Janeiro.
- Laser Therapy:Fractional and non-ablative wavelengths target water chromophores for controlled thermal injury.
- Chemical Peels:Acid-based exfoliation at varying concentrations stimulates superficial collagen remodeling without capital equipment requirements.
Radiofrequency absorbs the bulk of installed capacity; ultrasound is expanding most quickly.
Application Area:
Cost tier separation between facial and body applications drives distinct equipment procurement patterns among clinic operators.
- Face:High-visibility treatment zone commands premium per-session pricing and attracts repeat patient visits. Urban dermatology corridors in Brazil's São Paulo and South Korea's Seoul concentrate demand as patients sequence non-invasive modalities before surgical consultation.
- Neck:Thin dermal tissue requires specialized parameter adjustment to avoid platysmal band complications. Brazilian interior cities show underpenetration relative to coastal corridors, creating first-mover placement opportunities in Belo Horizonte.
- Abdomen:Larger surface area treatments favor radiofrequency platforms with larger applicator footprints.
- Arms:Moderate treatment volume segment with seasonal demand concentration.
Face applications capture the highest revenue per square meter of clinic space; neck treatments are climbing the fastest as thread lift alternatives lose favor.
End User:
Customer type fragmentation creates divergent certification and liability exposure requirements across the value chain.
- Clinics:Physician-supervised facilities with delegated technician operation dominate procedural volume. United States state medical board fragmentation on operator credentialing creates liability exposure that chains mitigate through proprietary training academies.
- Spas:Non-medical aesthetic facilities in the United Arab Emirates and South Korea expand device-based menus as surgical facelift volumes plateau.
- Hospitals:Reconstructive and post-surgical applications represent secondary demand.
- Home Users:Lower-power radiofrequency devices capture recurring revenue from post-clinical patients seeking interval maintenance between professional sessions.
Clinics deploy the majority of high-energy platforms; home users are gaining share fastest in the maintenance tier.
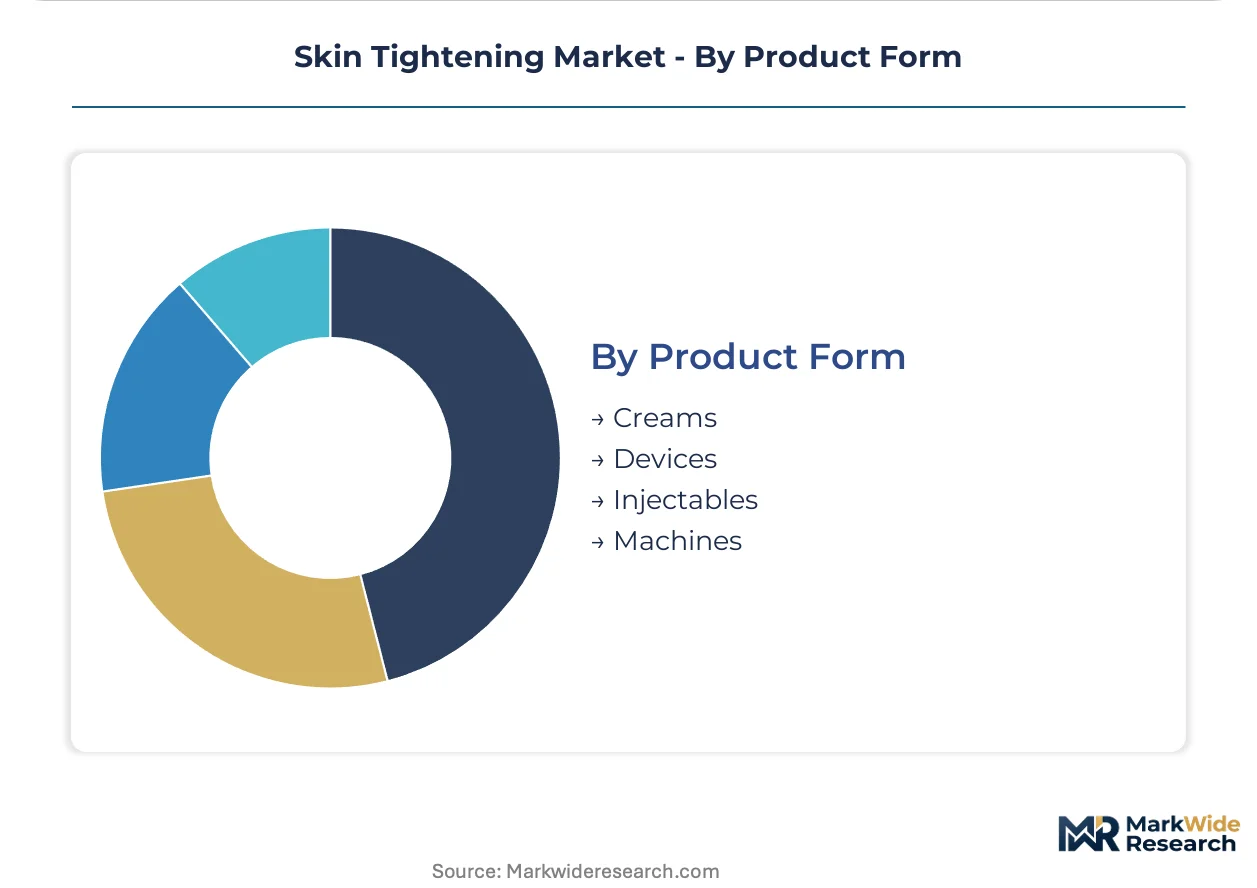
Product Form:
Margin structure varies dramatically between capital equipment and consumable revenue models.
- Devices:Capital equipment with 5-7 year replacement cycles and recurring handpiece revenue. EU Medical Device Regulation's 2021 implementation extended pre-market timelines by 8-14 months, restructuring quality management requirements for Class IIa radiofrequency systems.
- Machines:Multi-modality platforms switching between radiofrequency, ultrasound, and laser within single sessions. South Korean and UAE MedSpa chains standardize these architectures to reduce training overhead and improve throughput metrics.
- Creams:Topical retinoid and peptide formulations for maintenance without thermal injury.
- Injectables:Biostimulator compounds offering intermediate durability between energy-based and surgical alternatives.
Devices and machines together absorb the bulk of manufacturer revenue; machines are expanding most quickly as multi-energy platforms displace single-technology installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Israel and the United States while consumption clusters in East Asian and Middle Eastern urban corridors. South Korea's Gangnam dermatology district absorbs disproportionate platform deployment relative to domestic production capacity.
United States
FDA 510(k) premarket notifications structure commercialization timelines for radiofrequency and ultrasound platforms entering the aesthetic device market. State medical boards maintain fragmented operator certification standards that create liability exposure for clinic chains expanding across jurisdictions. Miami's Brickell and Los Angeles' Beverly Hills aesthetic corridors concentrate multi-modality platform adoption as MedSpa chains standardize protocols.
South Korea
MFDS fast-track clearance pathways compress regulatory timelines for second-generation radiofrequency devices targeting the Gangnam dermatology cluster. Seoul's aesthetic corridor generates disproportionate per-capita procedural volume as patients sequence non-invasive modalities before surgical consultation. Busan's Haeundae district shows emerging platform deployment as chains expand beyond the capital.
Brazil
ANVISA registration requirements shape import timelines for Israeli and US-manufactured energy-based devices entering the aesthetic market. São Paulo's Jardins corridor anchors national procedural volume with concentrated ultrasound platform deployment. Belo Horizonte and Curitiba remain underpenetrated relative to coastal corridors, creating placement opportunities for capital equipment distributors.
United Arab Emirates
MOHAP medical device registration mandates clinical evidence submissions for radiofrequency platforms seeking Dubai and Abu Dhabi market access. Dubai's Jumeirah aesthetic clinic cluster commands premium per-treatment pricing for SMAS-layer ultrasound procedures. Private payor aesthetic riders in Abu Dhabi enable bundled protocol reimbursement that expands per-patient revenue capture.
Germany
EU Medical Device Regulation's 2021 implementation extended pre-market timelines for Class IIa radiofrequency systems entering the European Economic Area. Unannounced audit obligations and post-market clinical follow-up requirements restructure quality management burdens for manufacturers. Munich and Frankfurt aesthetic corridors concentrate multi-energy platform adoption as chains deploy integrated cooling systems.
Skin Tightening Market Vendor Landscape
Top-tier vendors anchor premium positioning through integrated cooling technology and multi-modality architectures, while mid-scale specialists compete on single-technology platform pricing. The vendor base stratifies across three archetypes: integrated multinationals with captive regulatory affairs teams, technology licensors with outsourced manufacturing, and regional distributors with service-dependent revenue models. Dominant competitive moves include proprietary training academy establishment to mitigate operator certification fragmentation, and multi-energy platform development collapsing single-technology procurement cycles.
Within the integrated multinational tier, InMode Ltd. and Alma Lasers exemplify archetypes with differentiated platform strategies, while Solta Medical occupies a position in premium-tier fractional radiofrequency positioning. Among Israeli-originated device manufacturers, Lumenis and Cynosure represent scale-driven specialists with established installed bases across US and European aesthetic corridors. These three companies collectively illustrate how geographic origin, corporate structure, and technology focus stratify competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Lumenis |
| Cynosure |
| InMode Ltd. |
| Fotona |
| Cutera |
| Alma Lasers |
| Venus Concept |
| Merz Pharmaceuticals |
| Solta Medical |
| Others |
Supply Flow & Price Mechanics
MedSpa chain procurement concentration in Seoul's Gangnam corridor and Dubai's Jumeirah cluster anchors per-treatment pricing power for integrated multi-modality platform manufacturers. Capital equipment intensity at the clinic level creates tiered access patterns that stratify pricing across independent operators and franchise networks.
Pricing Analysis
Price erosion across radiofrequency platform tiers traces to handpiece commoditization and manufacturer oversupply in the South Korean market. Three-tier pricing structure across premium ultrasound, standard radiofrequency, and economy maintenance-device levels separates SMAS-layer procedures from dermal-only treatments. Cost-down pressure on radiofrequency units accelerates because MFDS fast-track clearances shorten competitive exclusivity windows. Independent clinics in Brazil's interior cities exhibit highest price sensitivity; premium-positioned MedSpa chains in the United Arab Emirates demonstrate lowest sensitivity due to bundled protocol reimbursement.
Supply Chain Analysis
EU Medical Device Regulation certification gates for Class IIa radiofrequency systems restrict supplier qualification to manufacturers with captive quality management infrastructure. Device manufacturing concentrates in Israel and the United States; cooling system components draw from German and Japanese precision suppliers. Cryogen and impedance sensor dependencies create single-source vulnerability for integrated platform producers. Distribution runs through regional medical device distributors with service-dependent revenue models in Brazil and the United Arab Emirates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified laser safety officer scarcity across secondary Brazilian cities props equipment placement timelines and sustains pricing for training-academy-equipped manufacturers. Supply constraints in qualified technician pipelines concentrate value capture with integrated platform vendors.
For Market Incumbents: Anchor premium positioning through proprietary cooling technology patents that resist radiofrequency handpiece commoditization. Defend against ultrasound platform substitution by expanding multi-modality architectures that collapse single-technology procurement cycles. Vertical integration into impedance feedback systems mitigates temperature monitoring inconsistency complaints that drive liability exposure. For New Entrants and Emerging Players: MFDS fast-track pathways in South Korea open a window for second-generation radiofrequency platforms targeting Busan's Haeundae district expansion. Brazil's Belo Horizonte and Curitiba corridors offer most penetrable geography given ANVISA registration barriers that deter mid-scale competitors. Home-use maintenance-tier devices provide lowest regulatory hurdle for initial market entry with recurring revenue potential. For Investors and Strategic Acquirers: The window for entry favors technology licensors with outsourced manufacturing and established Israeli or US regulatory affairs infrastructure. Long-term viability hinges on multi-energy platform development capability rather than single-modality specialization. Watch FDA 510(k) clearance velocity for ultrasound SMAS-layer devices as inflection indicator for premium-tier competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Fast-Track Regulatory Submission | Accelerates clinic adoption timelines in Seoul's Gangnam dermatology corridor. |
| Multi-Modality Platform Development | Collapses single-technology procurement cycles for UAE MedSpa chain standardization. |
| Proprietary Training Academy Establishment | Mitigates operator certification fragmentation across US state medical boards. |
| Integrated Cooling System Patent Expansion | Defends premium positioning against radiofrequency handpiece commoditization. |
| Telemedicine Pre-Screening Integration | Reduces no-show rates and optimizes device utilization in high-rent urban locations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, clinic operations directors, GPO contracts managers, and regulatory affairs specialists at device manufacturers combined with FDA 510(k) databases, MFDS clearance records, ANVISA registration filings, and EU MDR technical documentation. Bottom-up equipment placement estimates and top-down procedural volume reconstructions were triangulated against customs import data for radiofrequency and ultrasound platform categories.
Data-stream reconciliation across manufacturer shipment reports, clinic procurement databases, and payor reimbursement filings structured the analytical framework. Segmentation dimensions modeled include treatment type, application area, end user category, and product form across the projection horizon. CAGRs were derived from fitted growth curves against historical procedural volume trajectories. Forecast inputs incorporated MFDS clearance velocity assumptions and MedSpa chain expansion pipeline visibility.
The model assumes a particular technology adoption path; alternative pathways for fractional radiofrequency microneedling would alter the outlook. Forecasts reflect assumptions regarding regulatory clearance timelines, technician certification pipeline development, and clinic capital expenditure cycles. A model refresh is warranted upon material change in FDA 510(k) review velocity or EU MDR audit frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Aesthetic Surgery Procedures Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market