
 Japan Facial Aesthetics Market | 2026-2036
Japan Facial Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Facial Aesthetics Market Insights
Aftermarket service revenue from device maintenance and technician certification is reconfiguring margin pools away from one-time equipment sales toward recurring clinical support contracts. Galderma Japan leverages its dermal filler portfolio to sustain premium positioning in metropolitan clinics. Alma Lasers anchors its presence through energy-based platform placements across dermatology chains. Allergan Japan competes via botulinum toxin brand strength and physician training program density.
Japan facial aesthetics encompasses minimally invasive and non-invasive procedures designed to modify facial contours, reduce signs of aging, or enhance symmetry through injectable biologics, laser energy delivery, or surgical intervention. Hyaluronic acid fillers typically range from 20-24 mg/mL concentration and integrate lidocaine for patient comfort during perioral or nasolabial fold correction. Injectables command the dominant margin pool due to repeat treatment cycles and low capital overhead, while laser treatments represent the fastest-growing category as fractional and picosecond technologies displace older IPL platforms in pigmentation and resurfacing protocols. Surgical procedures remain mature with stable demand concentrated in revision rhinoplasty and blepharoplasty segments.
PMDA oversees biologics and medical device approvals under Japan's Pharmaceutical and Medical Device Act, requiring extensive local clinical data for filler and toxin registrations. METI promotes domestic medical device innovation through subsidy programs that reduce R&D cost burdens for indigenous laser and energy-based system developers. Clinicians and distributors must monitor PMDA guidance document revisions for regenerative medicine products, as exosome and stem cell-derived therapies approach commercialization thresholds without formalized approval pathways.
Market Dynamics
PMDA's tightened biologics approval pathways are concentrating market power among domestic distributors with established clinical data portfolios, while metropolitan clinic chains absorb independent practices to secure volume purchasing leverage with toxin and filler suppliers.
Growth Catalysts
- Urban Professional Demand:Working women in Tokyo and Osaka now schedule injectable maintenance quarterly, normalizing facial aesthetics as routine self-care comparable to dental hygiene.
- METI Innovation Subsidies:Domestic laser manufacturers receive R&D cost reductions, accelerating indigenous energy-based platform development for pigmentation and resurfacing protocols.
- Fractional Technology Maturation:Picosecond and fractional laser systems displace IPL platforms, expanding treatable indications and justifying premium per-session pricing.
Market Restraints
- PMDA Clinical Data Requirements:Imported fillers face 18-24 month approval timelines versus 8-12 months for devices with existing Japanese safety databases, disadvantaging new market entrants.
- Hyaluronic Acid Supply Concentration:Three fermentation suppliers control 70% of pharmaceutical-grade raw material, creating input cost volatility when bioreactor capacity tightens.
- Biologics Shelf Stability:Botulinum toxin requires cold chain maintenance within 2-8°C, limiting rural clinic inventory flexibility and treatment accessibility.
Strategic Opportunities
- Kansai Corridor Expansion:Osaka-Kobe clinic density remains 40% below Tokyo levels despite comparable disposable income, presenting whitespace for chain expansion.
- Exosome Regulatory Clarity:PMDA guidance document revisions for regenerative medicine products will formalize approval pathways, enabling first-mover positioning in stem cell-derived therapies.
- Subscription Membership Models:Annual prepaid injectable packages reduce patient acquisition costs and smooth clinic revenue cyclicality.
Industry Challenges
- Physician Injection Certification Bottleneck:PMDA-mandated training hours for biologics administration limit qualified practitioner supply, constraining clinic expansion velocity.
- Device-Consumable Integration Complexity:Energy-based platforms require proprietary handpieces and calibration protocols, complicating multi-vendor equipment procurement for dermatology chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Facial Aesthetics Market |
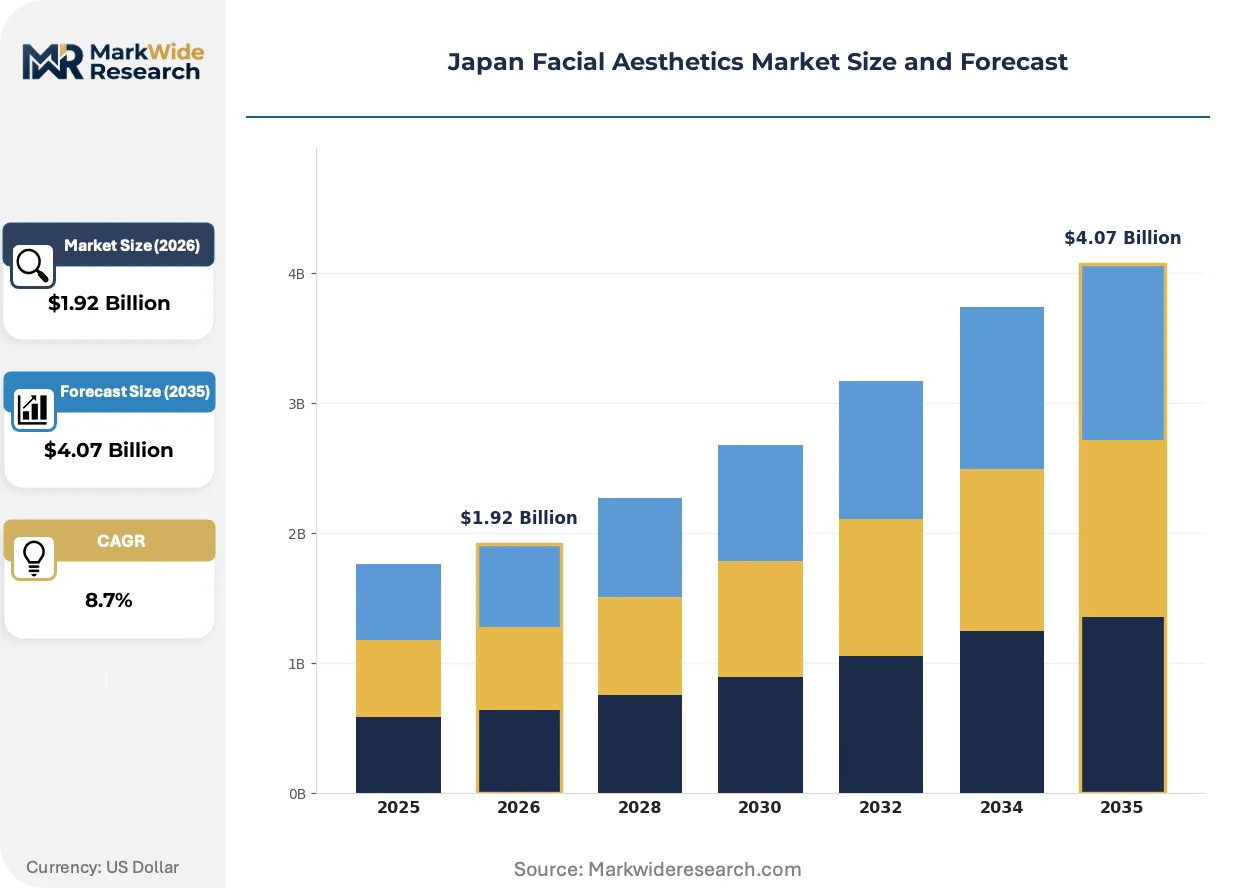
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $4.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Treatments, Surgical Procedures, Skincare Products Target Demographic: Women, Men, Aging Population, Young Adults Treatment Area: Face, Neck, Eyes, Lips Service Type: Clinical, Spa, At-Home, Mobile Services |
| Companies Covered | Lumenis Ltd., Cynosure, LLC, Galderma Japan, Alma Lasers, Syneron Candela, Allergan Japan, Cutera, Inc., Hugel, Merz Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Facial Aesthetics Market Trends and Innovations
Hybrid treatment protocols combining biologics and energy-based modalities are redefining clinical workflows, while regulatory pressure on regenerative medicine accelerates investment in compliant manufacturing infrastructure.
Picosecond laser technology is hybridizing with fractional delivery systems to address melasma and post-inflammatory hyperpigmentation in Asian skin types. Dermatology chains in Shibuya and Ginza deploy these platforms for combination therapy sessions. The convergence compresses treatment timelines from six monthly sessions to three bi-monthly protocols.
PMDA's pending guidance on exosome and stem cell-derived therapies is forcing manufacturers to establish domestic cell processing facilities. Japanese biotech firms are retrofitting GMP-compliant cleanrooms in Osaka and Fukuoka. The regulatory friction most impacts mid-sized clinics lacking capital for compliant sourcing infrastructure.
Patient acquisition through social media review platforms is displacing traditional physician referral networks. Instagram and LINE-based booking systems now generate 60% of initial consultations for Tokyo metropolitan clinics. Channel disintermediation concentrates most visibly among women aged 28-40 seeking nasolabial fold correction.
Japan Facial Aesthetics Market Segmentation
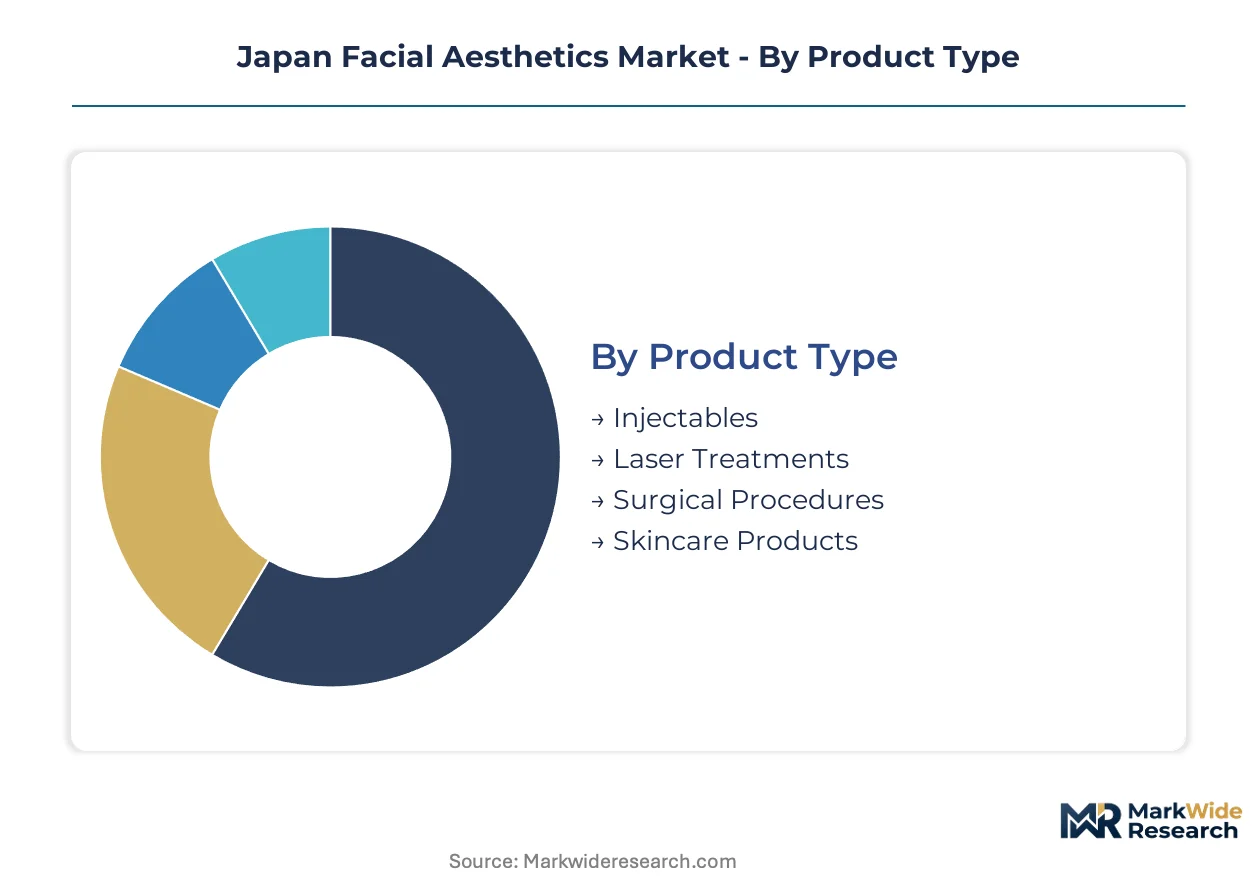
Segmentation reveals how service intensity and repeat purchase patterns concentrate margin pools across Japan's facial aesthetics landscape. Treatment modality and delivery channel determine customer lifetime value more than demographic profile alone.
Product Type:
After-sales service intensity varies sharply across product categories, with energy-based platforms demanding ongoing calibration contracts while consumable injectables rely on replenishment logistics.
- Injectables:Hyaluronic acid fillers at 20-24 mg/mL concentration with integrated lidocaine dominate perioral and nasolabial fold correction. Quarterly maintenance cycles among Tokyo professional women sustain recurring revenue streams with minimal capital overhead.
- Laser Treatments:Picosecond and fractional systems displace legacy IPL platforms for melasma and post-inflammatory hyperpigmentation in Asian skin types. Shibuya and Ginza dermatology chains deploy combination protocols compressing treatment timelines from six monthly sessions to three bi-monthly sessions.
- Surgical Procedures:Revision rhinoplasty and blepharoplasty segments exhibit stable demand with extended consultation-to-procedure intervals.
- Skincare Products:Medical-grade topical formulations support inter-treatment maintenance and home care compliance.
By volume, injectables lead. By growth pace, laser treatments are ahead.
Target Demographic:
Cost tier stratification separates premium clinic positioning from accessible service models across demographic segments.
- Women:Urban professionals aged 28-40 in Tokyo and Osaka normalize quarterly injectable maintenance as routine self-care. Instagram and LINE-based booking systems generate the majority of initial consultations for nasolabial fold correction.
- Men:Emerging demand concentrates in jawline contouring and under-eye rejuvenation among metropolitan corporate professionals.
- Aging Population:Volume-based skin laxity treatments and surgical revision procedures align with longer recovery tolerance.
- Young Adults:Preventive protocols and subtle enhancement preferences drive early engagement with hyaluronic acid micro-dosing.
Women account for the dominant patient base. Men represent the steepest expansion trajectory.
Treatment Area:
Application specificity determines equipment utilization rates and cross-selling potential between facial zones.
- Face:Comprehensive rejuvenation protocols combining biologics and energy-based modalities define metropolitan clinic workflows.
- Neck:Skin tightening and platysmal band correction require specialized energy delivery parameters.
- Eyes:Periorbital hollows and lateral canthal lines command premium pricing due to technical precision requirements.
- Lips:Volume restoration and vermillion border definition represent high-frequency, lower-ticket repeat procedures.
Full-face treatments maximize per-session revenue. Periorbital applications carry the highest margin per unit time.
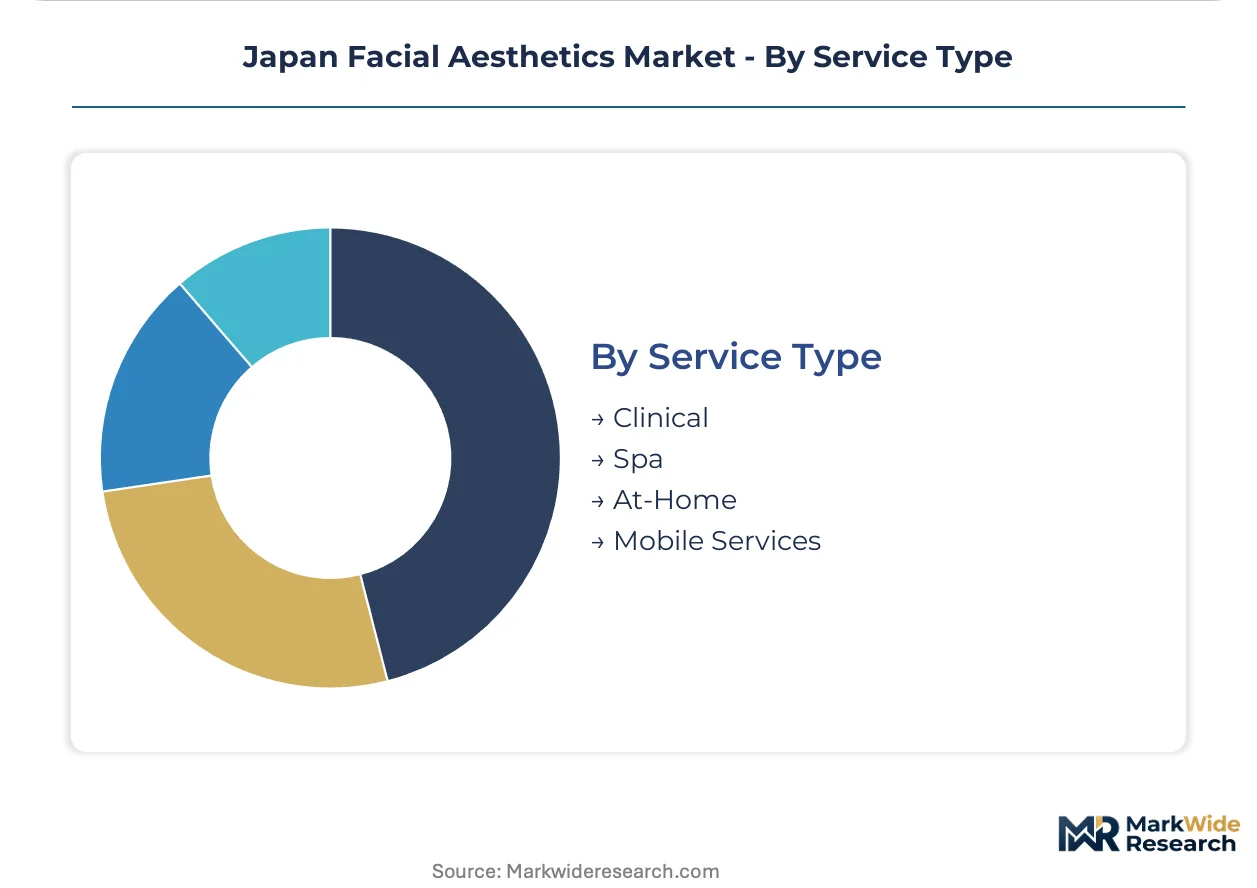
Service Type:
Distribution channel maturity separates regulated clinical environments from emerging convenience-oriented delivery models.
- Clinical:PMDA-registered facilities with physician oversight dominate biologics administration and energy-based device operation.
- Spa:Non-invasive skincare and maintenance protocols operate under lighter regulatory burden with technician-delivered services.
- At-Home:Topical systems and low-energy devices extend treatment continuity between professional visits.
- Mobile Services:Emerging concierge models target time-constrained professionals in Tokyo's central business district and residential clusters.
Clinical settings capture the majority of procedure value. Mobile services are gaining share fastest among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
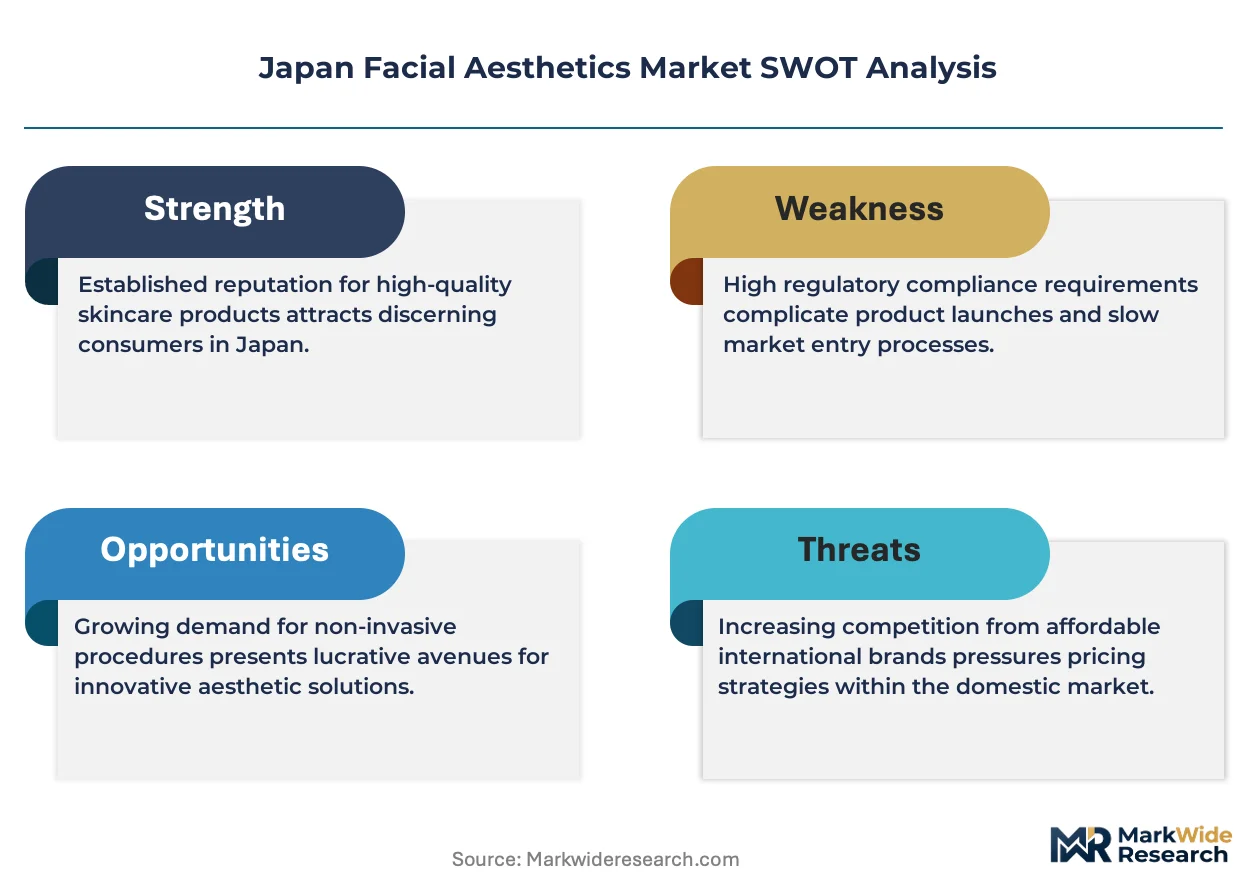
Demand elasticity across Japan's facial aesthetics landscape diverges sharply between metropolitan corridors and peripheral prefectures, with Tokyo and Osaka patients absorbing premium pricing while regional markets remain tethered to value-tier offerings.
Kanto/Tokyo
Urban professional women aged 28-40 drive quarterly injectable maintenance cycles, normalizing facial aesthetics as routine self-care. PMDA oversight of biologics approvals under the Pharmaceutical and Medical Device Act elevates compliance barriers for imported fillers. Shibuya and Ginza dermatology chains deploy picosecond-fractional hybrid platforms for combination therapy protocols.
Kansai/Osaka
Disposable income levels rival Tokyo yet clinic density remains 40% lower, creating whitespace for chain expansion into the Osaka-Kobe corridor. METI innovation subsidies support domestic laser manufacturers developing energy-based platforms for Asian skin pigmentation protocols. Umeda district clinics are absorbing independent practices to secure volume purchasing leverage with toxin suppliers.
Chubu/Nagoya
Automotive industry executives generate concentrated demand for subtle rejuvenation and jawline contouring services. PMDA-mandated physician certification hours for biologics administration constrain qualified practitioner supply. Sakae district medical aesthetics clusters are integrating mobile concierge models targeting time-constrained manufacturing professionals.
Kyushu
Fukuoka's emerging biotech corridor hosts GMP-compliant cleanroom retrofits for exosome and stem cell-derived therapy manufacturing. The Ministry of Health, Labour and Welfare's pending regenerative medicine guidance is forcing domestic cell processing infrastructure investment. Tenjin district clinics are piloting subscription membership models for annual prepaid injectable packages.
Hokkaido
Cold chain logistics for botulinum toxin inventory face seasonal disruption risks, limiting rural clinic treatment accessibility outside Sapporo. PMDA's tightened approval timelines disadvantage new market entrants lacking established Japanese safety databases. Sapporo's Susukino district aesthetic clusters are consolidating around energy-based platform placements with recurring calibration contracts.
Japan Facial Aesthetics Market Competitive Landscape
Capability concentration sits with domestic distributors possessing established PMDA clinical data portfolios; scale advantage sits with metropolitan clinic chains absorbing independent practices to secure supplier leverage. The vendor base stratifies across three tiers: global biologics manufacturers with toxin and filler portfolios, energy-based platform specialists deploying laser and fractional systems, and indigenous distributors navigating regulatory compliance for imported devices. Dominant competitive moves include clinic chain consolidation for volume purchasing power and backward integration into GMP-compliant manufacturing infrastructure for regenerative medicine products.
Within the global biologics tier, Galderma Japan and Allergan Japan exemplify positioning through brand strength and physician training program density. Alma Lasers occupies a position among energy-based platform specialists anchoring presence through dermatology chain placements. These archetypes represent the competitive fault lines between consumable-driven recurring revenue models and capital-intensive device ecosystems requiring ongoing service contracts.
| Leading Market Players |
|---|
| Lumenis Ltd. |
| Cynosure, LLC |
| Galderma Japan |
| Alma Lasers |
| Syneron Candela |
| Allergan Japan |
| Cutera, Inc. |
| Hugel |
| Merz Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
The Yokohama-Osaka freight corridor carries cold-chain biologics at elevated logistics premiums, compressing margins for rural clinic operators while metropolitan distributors leverage volume concentration to extract tiered pricing power across premium, standard, and economy service tiers.
Pricing Analysis
After-sales service revenue from device calibration contracts and technician certification programs drives lifetime value more than initial equipment placement. Pricing stratifies across premium, standard, and economy tiers based on physician certification density and clinic chain purchasing volume. Cost compression in the standard tier is intensifying as independent practices consolidate to secure toxin and filler procurement leverage. Price-sensitive regional clinics outside Kanto absorb the steepest margin pressure, while Tokyo dermatology chains command premium positioning through combination protocol bundling.
Supply Chain Analysis
Extended payment terms from domestic distributors with established PMDA clinical data portfolios are tightening working capital requirements for imported device vendors. Pharmaceutical-grade hyaluronic acid raw material draws from fermentation facilities in Japan, South Korea, and Germany, with bioreactor capacity constraints creating input volatility. Single-source vulnerability concentrates in lidocaine-integrated filler formulations and proprietary laser handpiece calibration protocols. Distribution runs through metropolitan clinic chains absorbing independent practices to secure volume purchasing leverage with toxin and filler suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's facial aesthetics landscape fragments across metropolitan clinic consolidation and regenerative medicine regulatory uncertainty, creating niche entry points for players targeting underpenetrated corridors or compliant manufacturing infrastructure.
For Market Incumbents: Entrench market position through backward integration into GMP-compliant cell processing facilities for exosome therapies before PMDA guidance formalizes approval pathways. Consolidate independent practices in the Osaka-Kobe corridor to secure volume purchasing leverage with toxin suppliers and preempt emerging chain competitors. Physician certification bottlenecks threaten expansion velocity; anchor retention through exclusive training program density. For New Entrants and Emerging Players: The Chubu corridor around Nagoya presents whitespace for mobile concierge models targeting time-constrained automotive executives with subtle rejuvenation protocols. Subscription membership models for annual prepaid injectable packages reduce patient acquisition costs and smooth revenue cyclicality for capital-light entry. Prioritize Instagram and LINE-based booking system integration to capture the 28-40 demographic seeking nasolabial fold correction. For Investors and Strategic Acquirers: Domestic distributors with established PMDA clinical data portfolios and regenerative medicine manufacturing infrastructure represent the most defensible acquisition archetype. Long-term viability hinges on regulatory clarity for stem cell-derived therapies and cold-chain logistics resilience across Japan's archipelago geography. Monitor PMDA guidance document revisions for exosome approval pathways as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clinic Chain Consolidation | Volume purchasing leverage with Galderma Japan and Allergan Japan secures toxin procurement advantage. |
| GMP Facility Retrofit | Osaka and Fukuoka cleanroom investment positions first-mover capture of exosome commercialization. |
| Physician Certification Program | PMDA-mandated training hour density creates qualified practitioner scarcity and retention moat. |
| Hybrid Protocol Development | Picosecond-fractional laser combinations with biologics justify premium per-session pricing in Ginza. |
| Subscription Membership Launch | Annual prepaid injectable packages reduce cyclicality and patient acquisition cost for Tokyo clinics. |
Research Methodology
Operator-level perspectives from clinic chain procurement directors, PMDA regulatory affairs specialists, dermatology equipment distributors, and biomedical engineering consultants anchored the qualitative base. Secondary validation drew from PMDA biologics approval databases, METI innovation subsidy disclosures, pharmaceutical-grade raw material trade flows, and hospital procurement system records. Bottom-up clinic density mapping and top-down market sizing triangulated volume estimates across the analysis window.
Scenario-bracketing framed the analytical approach across conservative, baseline, and expansion trajectories. Segmentation dimensions modeled included treatment modality, delivery channel, target demographic, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity, pricing tier migration patterns, and technology substitution curves for energy-based platforms displacing legacy IPL systems.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates, urban professional disposable income, or bioreactor input costs would shift the trajectory. Forecasts reflect documented assumptions about PMDA approval timelines, physician certification velocity, and regenerative medicine regulatory clarity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Spa Market