
 Global Anxiety Disorder Treatment Market | 2026-2036
Global Anxiety Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anxiety Disorder Treatment Market Foresight
Subscription-based patient financing and outcome-linked reimbursement contracts is tilting competitive access toward firms with capital reserves and payer relationships. Eli Lilly and Company leverages its metabolic-psychiatry pipeline to anchor positions in comorbid anxiety-depression indications. Pfizer Inc. sustains volume leadership through manufacturing scale across oral and injectable serotonin-modulating platforms. H. Lundbeck A/S specializes in CNS-focused R&D intensity, competing on mechanism novelty rather than portfolio breadth.
Anxiety disorder treatment encompasses pharmacological and psychotherapeutic interventions targeting pathological fear circuitry dysregulation, with selective serotonin reuptake inhibitors functioning as first-line agents through 5-HT transporter blockade and downstream receptor adaptation. The primary purpose is restoration of functional capacity in occupational, social, and daily living domains through symptom remission and relapse prevention. Selective serotonin reuptake inhibitors occupy the largest revenue pool due to established efficacy profiles and generic availability, while serotonin-norepinephrine reuptake inhibitors represent the fastest-expanding category driven by dual-mechanism efficacy in comorbid pain-anxiety presentations. Intravenous and injectable delivery modes are gaining structural share in acute crisis and treatment-resistant settings where rapid onset supersedes convenience preferences.
The FDA's breakthrough therapy and accelerated approval designations are reshaping development economics for novel anxiolytic mechanisms, compressing timelines from Phase II to commercialization. EMA's evolving digital health framework and WHO's inclusion of anxiety disorders in essential medicine lists are converging to expand reimbursed access across European and low-income health systems. Stakeholders must monitor how pharmacogenomic stratification and real-world evidence requirements reconfigure prescribing authority between psychiatrists, primary care providers, and emerging digital therapeutic platforms.
Market Dynamics
Accelerated FDA approval pathways for novel anxiolytic mechanisms are compressing development timelines from Phase II to commercialization, forcing established serotonin-modulator portfolios to defend against rapid-entry competitors with differentiated receptor targets.
Growth Catalysts
- Breakthrough Therapy Designations:FDA's expedited review programs compress regulatory timelines for novel mechanism antidepressants-anxiolytics, rewarding sponsors with real-world evidence infrastructure.
- Primary Care Integration:United States health systems embed standardized anxiety screening into routine wellness visits, expanding addressable patient pools beyond psychiatric specialty channels.
- Pharmacogenomic Stratification:CYP450 metabolic profiling guides SSRI selection, reducing trial-and-error prescribing and improving remission rates in treatment-naive populations.
Market Restraints
- API Supply Concentration:Sertraline and escitalopram active pharmaceutical ingredients concentrate among Indian and Chinese contract manufacturers, exposing formulators to geopolitical trade friction.
- Generic Erosion Dynamics:Patent cliffs for duloxetine and venlafaxine XR have collapsed branded pricing power in oral serotonin-norepinephrine reuptake inhibitor segments.
- Reimbursement Compression:Medicare Part D and commercial payers impose step-therapy protocols requiring failed generic SSRI trials before covering branded novel mechanisms.
Strategic Opportunities
- Digital Therapeutic Adjuncts:FDA-cleared prescription digital therapeutics for generalized anxiety disorder create combination reimbursement pathways alongside pharmacotherapy.
- Injectable Acute Crisis Formats:Intramuscular brexanolone and intravenous ketamine derivatives address emergency department and inpatient psychiatric settings where rapid onset overrides convenience preferences.
- Metabolic-Psychiatry Convergence:GLP-1 receptor agonist trials in comorbid obesity-anxiety populations open mechanism expansion beyond monoamine targets.
Industry Challenges
- Psychiatric Trial Recruitment:Placebo response rates in anxiety disorder trials have climbed to 40-50%, requiring larger enrollment to demonstrate statistical separation and inflating study costs.
- Real-World Evidence Infrastructure:Payers demand post-market outcome data linking prescribing to functional recovery metrics, forcing sponsors to build patient registries and health economics capabilities.
- Cross-Border Data Fragmentation:EMA's evolving digital health framework and FDA's decentralized trial guidance create divergent evidence standards for multinational submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anxiety Disorder Treatment Market |
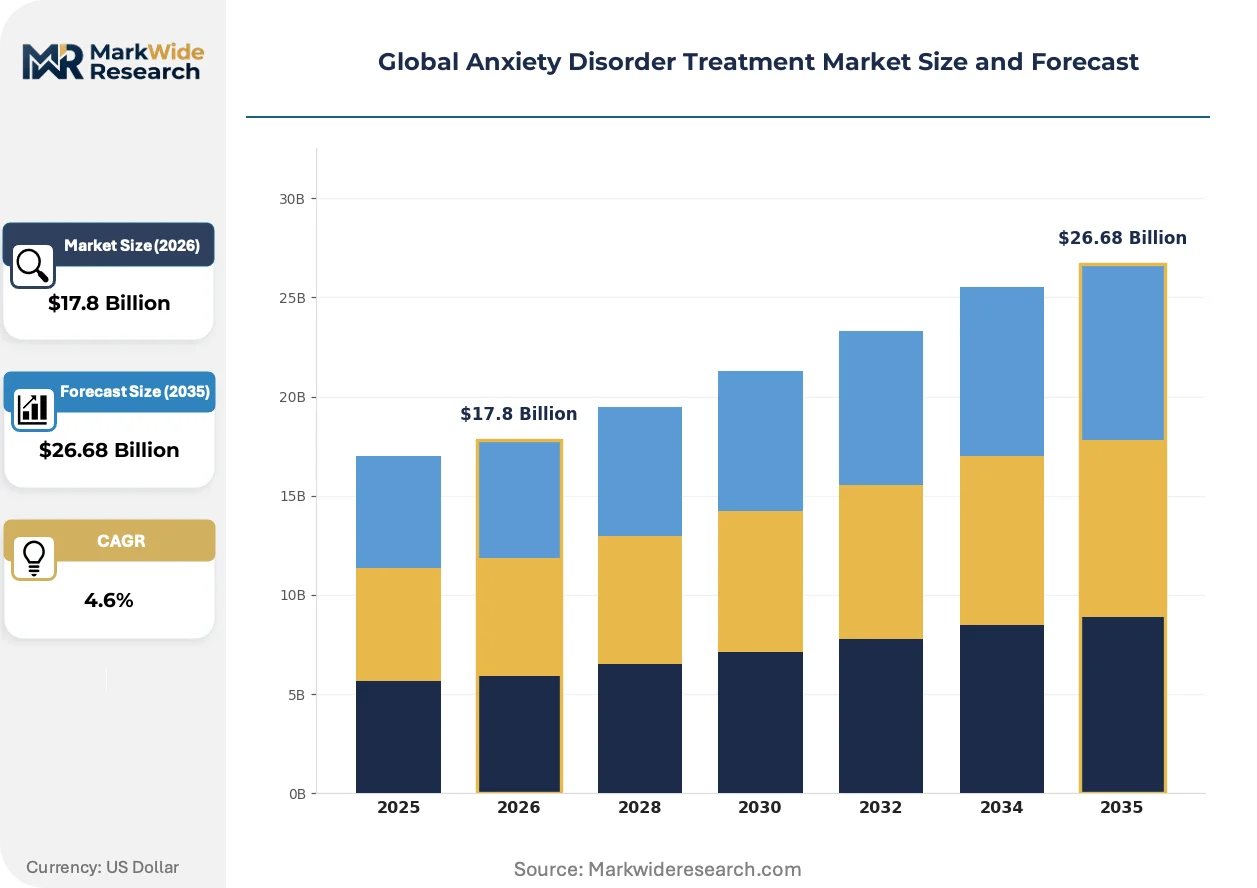
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Serotonin Reuptake Inhibitors, Benzodiazepines, Serotonin-Norepinephrine Reuptake Inhibitors, Beta Blockers, Buspirone Therapy Area: Generalized Anxiety Disorder, Panic Disorder, Social Anxiety, Phobias, Post-Traumatic Stress Delivery Mode: Oral, Intravenous, Transdermal, Sublingual, Injectable End User: Psychiatric Clinics, Primary Care Providers, Outpatient Centers, Community Health Facilities |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Eli Lilly and Company, GlaxoSmithKline plc, Merck & Co., Inc., AstraZeneca plc, AbbVie Inc., Novartis AG, H. Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anxiety Disorder Treatment Market Shifts & Advancements
Novel anxiolytic mechanisms targeting glutamate, GABA-A, and neurosteroid pathways are disrupting serotonin-centric development portfolios. Three forces are reshaping competitive positioning: rapid-onset delivery formats, regulatory acceleration for mechanism novelty, and care model integration.
Neurosteroid modulators such as zuranolone are collapsing the latency-to-efficacy gap that has constrained SSRI adoption in acute crisis settings. Psychiatric emergency departments and inpatient units are piloting these agents for same-day symptom control. This compression of onset timelines is enabling hospital-at-home models that displace extended inpatient stays.
EMA's digital health framework and FDA's guidance on prescription digital therapeutics are converging to create regulated software-as-medical-device categories for anxiety management. European reimbursement authorities are piloting value-based contracts tying digital therapeutic payments to validated symptom reduction scores. Germany's DiGA fast-track pathway and France's ANSM digital health pilot are accelerating market access for cognitive behavioral therapy apps as adjuncts to pharmacotherapy.
Integrated behavioral health networks in the United States are unbundling traditional psychiatric referrals into embedded primary care workflows. Kaiser Permanente and Veterans Health Administration systems are deploying collaborative care models where nurse care managers coordinate SSRI initiation with psychotherapy scheduling. This channel shift concentrates prescribing authority among primary care physicians trained in standardized anxiety protocols, reducing specialist dependency in mild-to-moderate severity segments.
Global Anxiety Disorder Treatment Market Segmentation
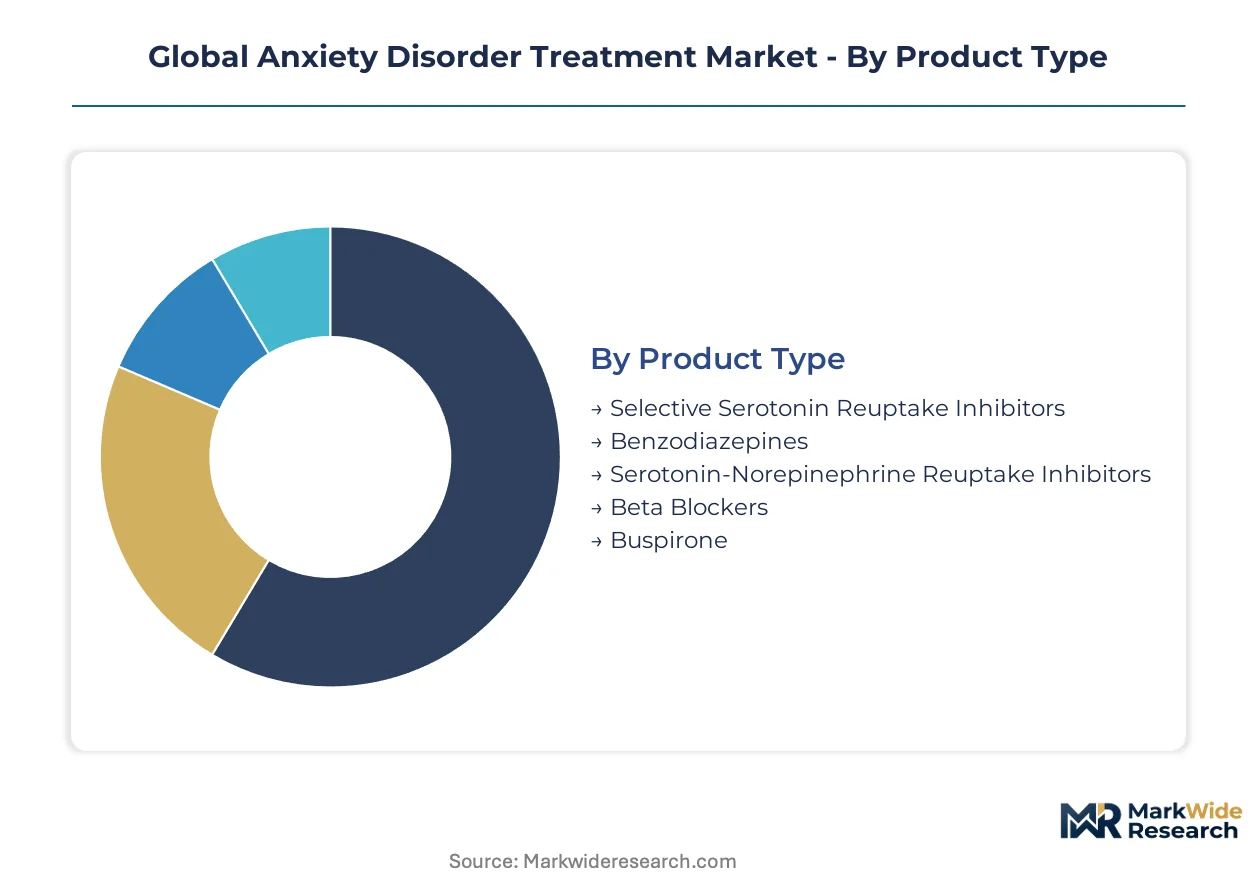
Anxiety disorder treatment markets fragment across mechanism classes, clinical presentations, and care delivery settings. Each segmentation axis reveals distinct competitive dynamics: mature oral agents defend volume against novel delivery formats, while care model shifts redistribute prescribing authority across provider types.
Product Type:
Mature monoamine modulators dominate commercial volume, yet emerging mechanism classes are capturing fastest-growing prescription share through differentiated onset profiles.
- Selective Serotonin Reuptake Inhibitors:First-line agents blocking 5-HT transporters with established efficacy in generalized anxiety and comorbid depression. Demand concentrates in primary care networks across the United States and Germany where standardized screening protocols drive high-volume initiation. Generic availability has collapsed pricing power, forcing branded portfolios to defend through fixed-dose combinations and pediatric indications.
- Serotonin-Norepinephrine Reuptake Inhibitors:Dual-mechanism agents addressing noradrenergic and serotonergic pathways simultaneously. Prescribing clusters in pain-anxiety comorbid populations within Veterans Health Administration systems and German statutory insurance networks, where duloxetine and venlafaxine XR face accelerating generic erosion.
- Benzodiazepines:GABA-A positive allosteric modulators reserved for acute crisis intervention due to dependence liability.
- Beta Blockers:Sympathetic nervous system antagonists targeting somatic anxiety manifestations without cognitive sedation.
- Buspirone:5-HT1A partial agonist with delayed onset but favorable abuse liability profile for chronic maintenance.
Selective Serotonin Reuptake Inhibitors retain volume leadership; Serotonin-Norepinephrine Reuptake Inhibitors hold the steepest expansion curve.
Therapy Area:
Application segmentation mirrors diagnostic prevalence and reimbursement granularity, with high-frequency disorders commanding dedicated development programs.
- Generalized Anxiety Disorder:Persistent excessive worry with functional impairment across occupational and social domains. Treatment demand concentrates in integrated behavioral health networks throughout Kaiser Permanente and United States commercial insurance panels, where collaborative care models embed SSRI initiation into primary care workflows.
- Post-Traumatic Stress:Trauma-related dysregulation of fear circuitry with high unmet need for rapid-acting interventions. Prescribing growth centers on Veterans Health Administration facilities and Israeli Defense Forces medical systems, where prazosin and novel glutamatergic mechanisms receive priority formulary placement.
- Panic Disorder:Recurrent unexpected panic attacks with anticipatory anxiety and agoraphobic avoidance.
- Social Anxiety:Performance and interactional fear driving significant occupational disability in younger demographics.
- Phobias:Circumscribed fear responses amenable to exposure-based psychotherapy with adjunctive pharmacotherapy.
Generalized Anxiety Disorder captures the largest addressable population; Post-Traumatic Stress demonstrates the most rapid mechanism innovation uptake.
Delivery Mode:
Route of administration segmentation reflects the tension between convenience optimization and clinical urgency, with acute settings privileging onset speed over patient preference.
- Oral:Tablet and capsule formulations enabling outpatient self-administration and long-term adherence. Manufacturing concentrates among Indian contract manufacturers supplying sertraline and escitalopram to European and North American formulators, exposing supply chains to API trade friction.
- Injectable:Intramuscular and subcutaneous formats for psychiatric emergency departments and hospital-at-home programs. Adoption accelerates in United States academic medical centers piloting brexanolone for postpartum anxiety and ketamine derivatives for treatment-resistant presentations.
- Intravenous:Hospital-based infusion requiring monitoring infrastructure for neurosteroid and dissociative anesthetic protocols.
- Transdermal:Patch delivery systems under development for steady-state neurosteroid administration.
- Sublingual:Rapid buccal absorption formats addressing breakthrough anxiety with faster onset than conventional oral routes.
Oral formulations retain volume leadership; Injectable formats gain share fastest in crisis intervention settings.
End User:
Customer type segmentation tracks the unbundling of psychiatric specialty care into distributed primary care and community-based models.
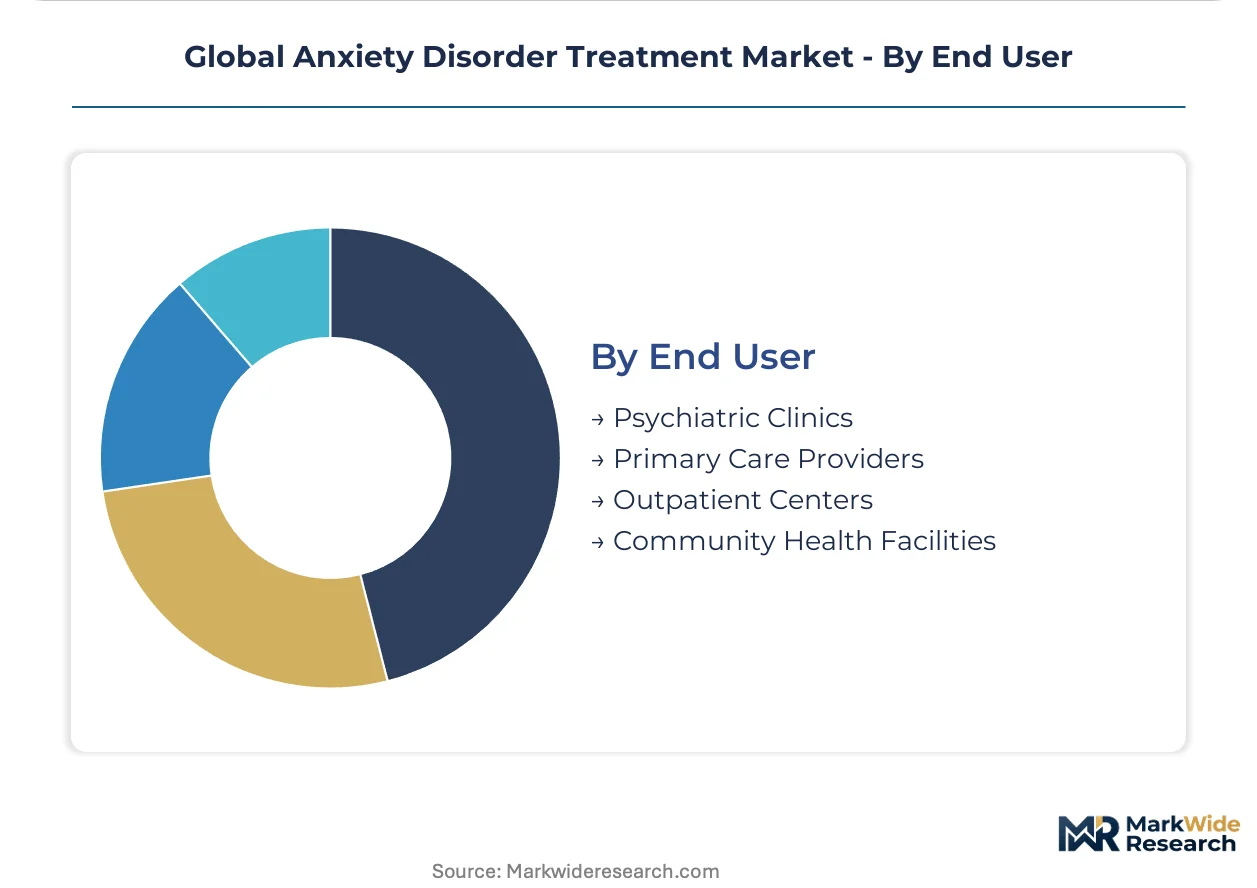
- Primary Care Providers:Internal medicine and family practice physicians initiating first-line pharmacotherapy per standardized anxiety protocols. Prescribing authority concentrates in United States accountable care organizations embedding behavioral health screening into Medicare Annual Wellness Visits, expanding addressable pools beyond traditional psychiatric channels.
- Psychiatric Clinics:Specialist-managed care for treatment-resistant and complex comorbid presentations. Demand localizes in urban academic centers throughout Boston, London, and Tel Aviv where pharmacogenomic stratification and novel mechanism trials concentrate.
- Outpatient Centers:Freestanding mental health facilities delivering psychotherapy-pharmacotherapy integration.
- Community Health Facilities:Federally qualified health centers and rural clinics addressing access disparities through telepsychiatry support.
Primary Care Providers capture the highest prescription volume; Psychiatric Clinics maintain the steepest per-patient revenue trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net pharmaceutical trade flows reveal a pronounced import dependency across European and Asian markets, while the United States and Switzerland maintain substantial active pharmaceutical ingredient and formulation export surpluses in central nervous system therapeutics.
United States
FDA breakthrough therapy designations for novel anxiolytic mechanisms attract venture financing into Boston and San Francisco biotech clusters. The Veterans Health Administration operates the country's largest integrated psychiatric formulary, driving volume procurement for post-traumatic stress interventions. Kaiser Permanente's collaborative care models in California embed anxiety screening into primary care workflows, expanding prescription initiation beyond specialist channels.
Germany
Statutory health insurance funds reimburse cognitive behavioral therapy apps through the DiGA fast-track pathway, creating Europe's most mature digital therapeutic market. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, aligns with EMA accelerated assessment procedures for novel neurosteroid mechanisms. Manufacturing concentration in North Rhine-Westphalia supplies escitalopram active pharmaceutical ingredients to European formulators.
Japan
PMDA's Sakigake designation system compresses review timelines for mechanism-first anxiolytics, rewarding sponsors with domestic clinical trial infrastructure. Metabolic-psychiatry convergence trials in Tokyo academic medical centers explore GLP-1 receptor agonist applications in comorbid anxiety presentations. Osaka-based contract manufacturers produce sertraline intermediates for Asia-Pacific distribution networks.
India
CDSCO accelerated approval pathways for generic SSRI formulations sustain the country's position as the leading exporter of sertraline and escitalopram active pharmaceutical ingredients. Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad supply oral anxiolytic formulations to African and Latin American markets. The country's central drug regulator has tightened good manufacturing practice inspections for export-oriented contract manufacturers.
Switzerland
Swissmedic's reliance procedures leverage EMA assessments for novel anxiolytic approvals, reducing regulatory duplication for sponsors with European marketing authorizations. Basel's pharmaceutical research corridor concentrates pharmacogenomic stratification capabilities for CYP450-guided SSRI selection. The country's specialized CNS-focused developers export neurosteroid modulators to United States academic medical centers.
Global Anxiety Disorder Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mechanism-specific development niches. The anxiety disorder treatment market structures around three archetypes: metabolic-psychiatry convergents, serotonin-modulation incumbents, and CNS-focused mechanism innovators. Competitive intensity concentrates in M&A activity targeting late-phase neurosteroid assets and strategic partnerships between digital therapeutic developers and traditional pharmaceutical sponsors.
Among metabolic-psychiatry convergents, Eli Lilly and Company anchors positions in comorbid anxiety-depression indications through its GLP-1 receptor agonist pipeline. Pfizer Inc. exemplifies the serotonin-modulation incumbent archetype, sustaining manufacturing scale across oral and injectable delivery platforms. H. Lundbeck A/S occupies the CNS-focused mechanism innovator tier, competing on receptor-target novelty rather than portfolio breadth. These three entities represent distinct strategic postures within a market tilting toward rapid-onset formats and outcome-linked reimbursement contracts.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| AstraZeneca plc |
| AbbVie Inc. |
| Novartis AG |
| H. Lundbeck A/S |
| Others |
Supply & Pricing Matrix
Hyderabad's pharmaceutical manufacturing cluster anchors global supply of sertraline and escitalopram active pharmaceutical ingredients, concentrating upstream capacity among Indian contract manufacturers whose output fluctuations transmit directly into downstream pricing volatility for European and North American formulators.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where branded novel mechanisms command premium positioning against generic serotonin modulators. Price differentiation rests on FDA breakthrough therapy designation status and pharmacogenomic stratification capabilities, with Medicare Part D step-therapy protocols intensifying cost compression in first-line oral segments. Hospital procurement committees exhibit lowest price sensitivity for intravenous neurosteroid formats in emergency department settings, while primary care networks face highest sensitivity due to formulary tier placement constraints.
Supply Chain Analysis
Upstream feedstock dependencies for anxiolytic APIs concentrate manufacturing inputs across India, China, and Switzerland, with sertraline intermediates and escitalopram base compounds drawing from Hyderabad, Ahmedabad, and Basel production corridors. Key inputs span 5-HT transporter ligands, GABA-A modulator precursors, and neurosteroid synthesis substrates. Single-source vulnerability from Indian API concentration exposes formulators to CDSCO inspection disruptions and geopolitical trade friction. Distribution runs through specialized pharmaceutical wholesalers and hospital purchasing cooperatives into integrated behavioral health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where FDA accelerated approval pathways and EMA digital health frameworks erect formidable barriers against mechanism replication, locking in advantage for sponsors with established real-world evidence infrastructure.
For Market Incumbents: Build data-asset moats through patient registry infrastructure that captures post-market functional recovery metrics required by commercial payers. Consolidate advantage by acquiring late-phase neurosteroid developers before Phase II readouts compress competitive timelines. Counter the threat from GLP-1 metabolic-psychiatry convergence by anchoring CNS-specific expertise in prescriber education networks.
For New Entrants and Emerging Players: Southeast Asian psychiatric markets present underpenetrated addressable pools where CDSCO-aligned regulatory familiarity enables faster generic SSRI formulation entry. Target white-space in prescription digital therapeutic adjacencies through Germany's DiGA reimbursement pathway, leveraging cognitive behavioral therapy app certification as a lower-capital market access wedge. Pursue hospital-at-home crisis intervention formats where rapid-onset delivery gaps persist.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators with subscription-based patient support programs and value-based payer contracts. Long-term viability across the analysis window favors CNS-focused mechanism innovators over serotonin-modulation incumbents facing patent cliff erosion. Monitor pharmacogenomic stratification adoption rates among United States accountable care organizations as the inflection signal for prescribing authority shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Breakthrough therapy designation compresses FDA timelines from Phase II to commercialization. |
| Regulatory Approval Pathway | EMA's digital health framework enables DiGA fast-track reimbursement for prescription therapeutics. |
| Manufacturing Scale-Up | Indian API capacity expansion secures supply continuity for sertraline and escitalopram formulators. |
| Pipeline Diversification | Neurosteroid mechanism expansion addresses acute crisis settings where SSRI latency fails. |
| Strategic Partnership | Collaborative care models embed anxiety screening into Kaiser Permanente primary care workflows. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation spanning FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical expenditure estimates across regional regulatory clusters.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning mechanism class, delivery mode, therapy area, and end-user provider type. CAGRs derived from epidemiological prevalence trajectories, treatment rate assumptions, and pricing elasticity parameters informed value projections. Forecast inputs incorporated pharmacogenomic stratification adoption curves and digital therapeutic reimbursement pilot outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by metabolic-psychiatry convergents or neurosteroid specialists would shift outcomes beyond modeled ranges. Cross-checking against CMS Medicare Part D expenditure trends and Veterans Health Administration formulary placement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Mental Health Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
US Psychiatry Clinic Market