
 Syringeless Injector Market | 2026-2036
Syringeless Injector Market Size, Share, and Industry Trends Forecast 2026-2036
Syringeless Injector Market Insights
Preventive maintenance contracts and software-defined flow-rate programming are consolidating as the primary revenue layer beyond hardware sales. Bracco Imaging leverages its installed base of contrast delivery systems to attach long-term service agreements across European hospital networks. Bayer anchors its position through R&D intensity in electronic control modules that enable real-time pressure feedback during injection cycles. GE HealthCare competes by extending its imaging equipment service infrastructure into injector calibration and compliance monitoring.
A syringeless injector is a closed fluid delivery system that propels medication through a narrow orifice at high velocity without a conventional needle, typically operating at pressures between 100 and 3,000 psi depending on tissue depth and viscosity. The device serves pharmaceutical and clinical settings where elimination of needlestick risk, reduction of biohazard waste, and improvement of patient adherence are prioritized. Spring-loaded systems dominate current installed volumes due to mechanical simplicity and lower unit cost, while piezoelectric architectures represent the fastest-expanding segment because they enable programmable dose-volume profiles with microsecond precision. Gas-powered injectors occupy a mature niche in mass vaccination campaigns where single-use disposable nozzles simplify field logistics.
FDA 510(k) premarket notification and EU MDR technical documentation requirements shape product development timelines and predicate-device strategies for manufacturers seeking dual-territory approval. EPA hazardous waste regulations and OSHA bloodborne pathogen standards in the United States reinforce demand for needle-free systems that eliminate sharps disposal liability. Stakeholders must monitor evolving reimbursement codes for needle-free drug delivery across Medicare and national health systems, as coverage determination will dictate whether adoption accelerates beyond early-adopter hospital networks into mainstream outpatient settings.
Market Dynamics
Hospital procurement departments in the United States are expanding adoption of needle-free delivery platforms to reduce sharps injuries and associated liability costs, compressing vendor selection cycles and elevating preventive maintenance contracts as primary revenue anchors.
Growth Catalysts
- EU Medical Device Regulation harmonized standards:Outpatient clinic networks in Germany are retrofitting injection suites with gas-powered and electromagnetic systems to achieve compliance, accelerating hardware refresh cycles.
- Spring-loaded mechanical simplicity:Lower unit costs and field-proven reliability drive installed volumes in mass vaccination campaigns where disposable nozzles simplify logistics.
- Piezoelectric programmable precision:Microsecond dose-volume control enables therapeutic applications requiring exact tissue penetration depths, expanding addressable clinical use cases.
Market Restraints
- High-pressure component sourcing:Precision ceramic nozzles and corrosion-resistant seals concentrate among Japanese and German specialty suppliers, creating input bottlenecks.
- FDA 510(k) predicate-device dependency:Manufacturers without established clearance pathways face extended timelines for Class II medical device approval, advantaging incumbents.
- Spring-loaded system substitution:Lower-cost mechanical alternatives limit pricing power for piezoelectric and electromagnetic architectures in budget-constrained settings.
Strategic Opportunities
- Software-defined flow-rate programming:Real-time pressure feedback modules enable outcome-based service contracting, shifting revenue from hardware to recurring calibration and compliance monitoring.
- Retrofit demand in Germany:EU MDR implementation deadlines create concentrated upgrade cycles for existing installed bases across outpatient networks.
- Biologic drug viscosity expansion:High-molecular-weight formulations requiring 2,000+ psi delivery pressures favor next-generation electromagnetic architectures over legacy spring systems.
Industry Challenges
- Cross-functional talent scarcity:Engineers combining fluid dynamics expertise with embedded systems programming command premium compensation, constraining R&D scaling.
- Legacy imaging equipment integration:Calibration protocols for syringeless injectors must interface with proprietary GE HealthCare and Siemens Healthineers contrast delivery workflows, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syringeless Injector Market |
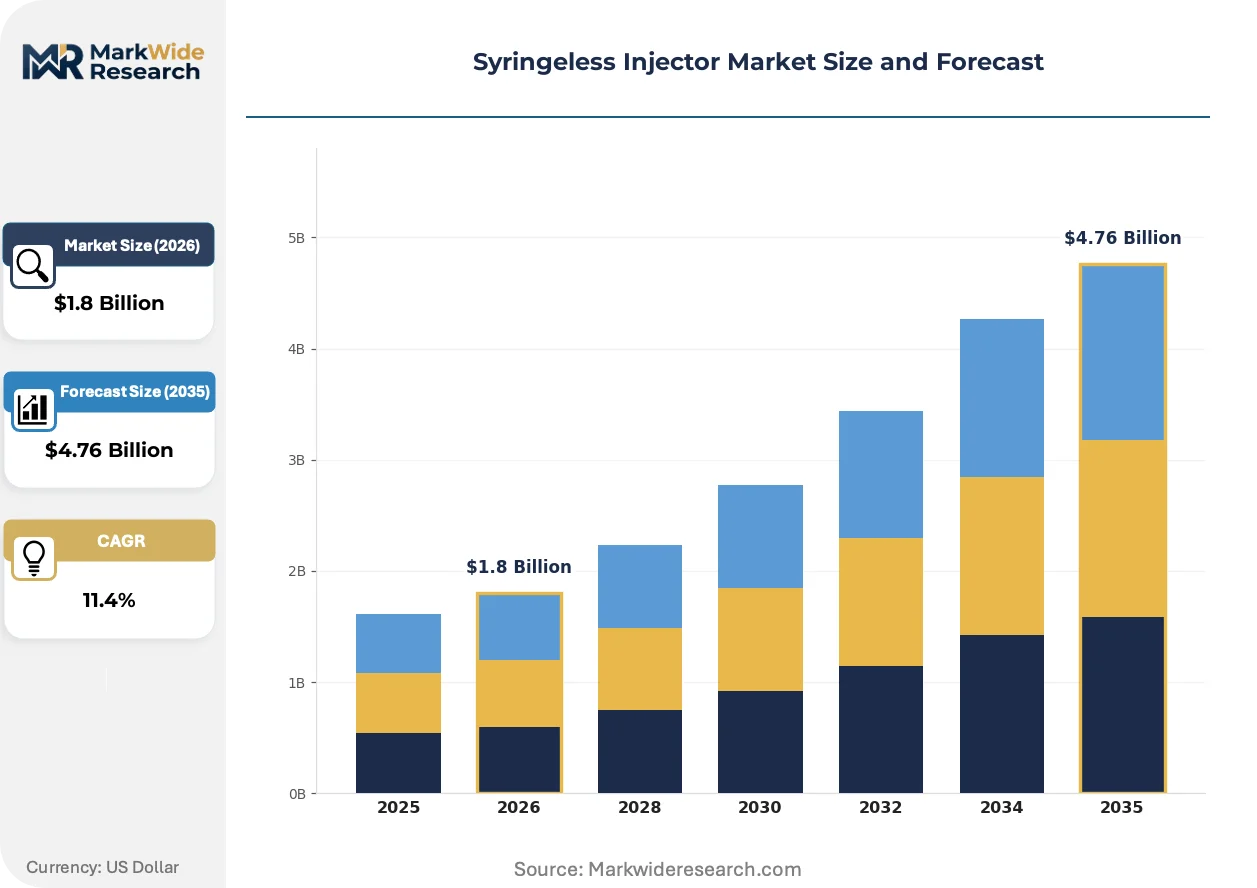
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring-Loaded, Gas-Powered, Piezoelectric, Electromagnetic Technology: Jet Injection, Needle-Free, Electronic Control, Mechanical Application: Vaccination Delivery, Insulin Administration, Dermatological Treatment, Veterinary Care End User: Pharmaceutical Companies, Research Institutions, Animal Hospitals, Home Healthcare Providers |
| Companies Covered | Bracco Imaging, Bayer, GE HealthCare, Guerbet, Ulrich GmbH & Co. KG, MEDTRON AG, Nemoto Kyorindo, Shenzhen Antmed, Shenzhen Seacrown Electromechanical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syringeless Injector Market Trends and Innovations
Piezoelectric architectures are modularizing device platforms around programmable dose engines, enabling rapid reconfiguration across therapeutic categories without hardware redesign.
Electromagnetic injection systems are modularizing around interchangeable nozzle cartridges and software-defined pressure curves, allowing hospitals to service multiple drug viscosities through a single base unit. Academic medical centers in the United States are piloting these platforms for both diagnostic contrast and therapeutic biologics, collapsing the traditional separation between imaging suites and infusion centers. The structural consequence is compressing capital equipment refresh cycles from seven-year replacement schedules to three-year upgrade intervals.
EU MDR technical documentation requirements are forcing manufacturers to revalidate predicate-device equivalence claims, extending product development timelines for dual-territory approval seekers. Device firms are responding by front-loading clinical evidence generation for electromagnetic platforms to preempt notified body scrutiny. German outpatient networks face the most acute compliance pressure given their concentration of legacy spring-loaded systems requiring retrofit documentation.
After-sales service unbundling is accelerating as hospital procurement departments negotiate calibration and compliance monitoring separately from hardware acquisition. European hospital networks are leading this shift, demanding multi-vendor service agreements that decouple maintenance from original equipment manufacturer lock-in. The transformation is most visible in Germany, where clinic chains negotiate centralized preventive maintenance contracts across distributed injection suites.
Syringeless Injector Market Segmentation
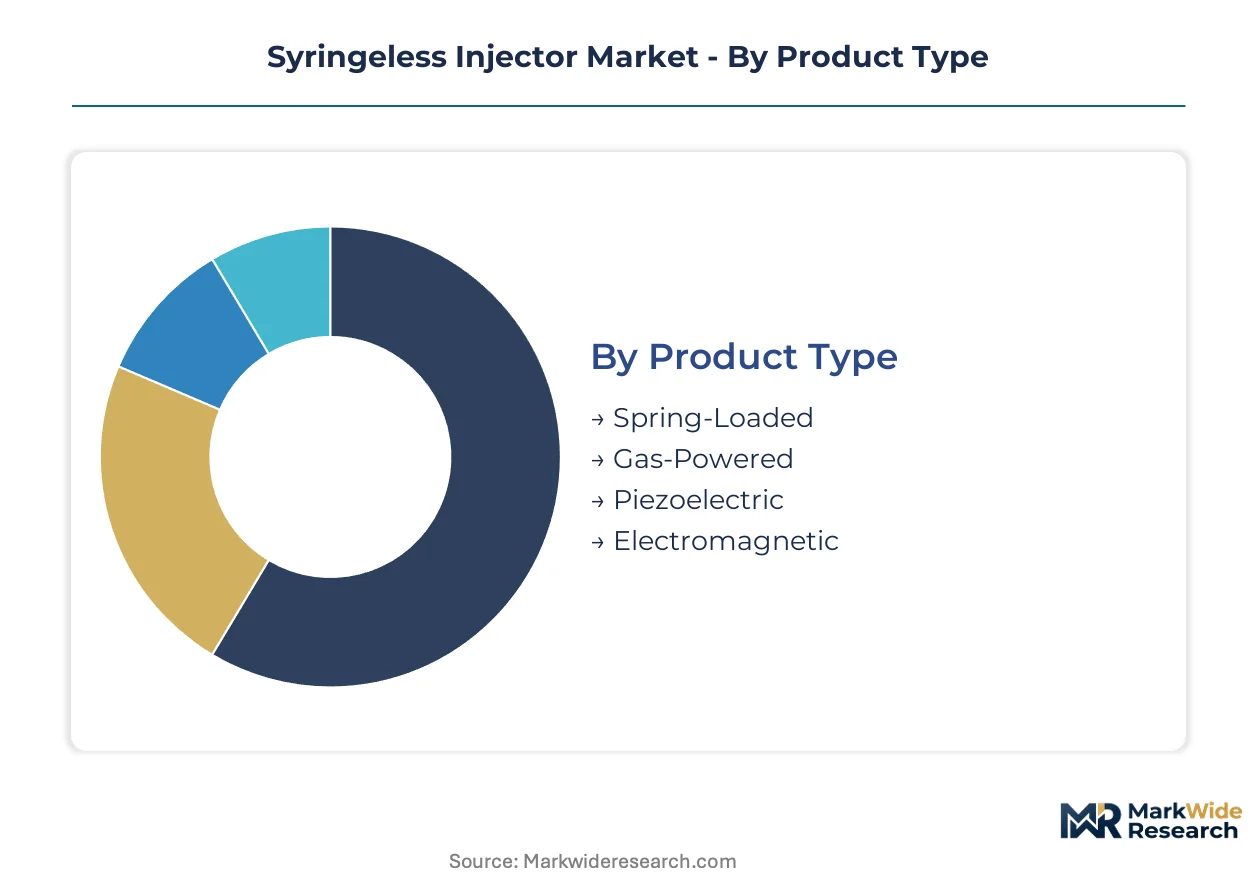
Device architecture and delivery mechanism determine procurement priorities across clinical settings. Buyers segment sharply between mechanical reliability for high-volume campaigns and programmable precision for therapeutic biologics.
Product Type:
Cost tier separates mass vaccination buyers from specialty therapeutic purchasers.
- Spring-Loaded:Mechanical compression systems store energy in coiled springs for instantaneous release. Mass vaccination campaigns in the United States favor these units for field durability and minimal training requirements. Lower unit costs sustain installed volumes despite limited dose adjustability.
- Piezoelectric:Ceramic crystal displacement enables microsecond flow-rate modulation with pressure feedback loops. Academic medical centers in Germany pilot these for biologic delivery requiring exact tissue penetration depths. Programmable precision commands premium positioning in outpatient clinic networks.
- Gas-Powered:Compressed gas cartridges propel medication through disposable nozzles for single-use applications.
- Electromagnetic:Linear motor architectures deliver variable force curves across viscosity ranges.
Spring-Loaded leads volumes today; Piezoelectric is gaining share fastest.
Technology:
Application setting dictates whether electronic oversight or mechanical simplicity prevails.
- Jet Injection:High-velocity fluid streams penetrate skin through narrow orifices at 100-3,000 psi. Hospital procurement departments specify these systems for sharps injury elimination and liability reduction. OSHA bloodborne pathogen compliance reinforces specification in United States networks.
- Electronic Control:Embedded pressure sensors and real-time feedback modules enable dose-volume profiling. German outpatient clinics retrofit injection suites with these platforms to satisfy EU MDR harmonized standards for traceable delivery parameters.
- Needle-Free:Elimination of conventional needles across all pressure-generation architectures.
- Mechanical:Purely physical energy storage without electronic oversight or feedback loops.
Mechanical systems dominate installed base; Electronic Control is climbing the fastest.
Application:
Volume scale and reimbursement environment fragment demand across therapeutic categories.
- Vaccination Delivery:Population-scale immunization programs require disposable nozzles and minimal cold-chain dependency. Campaign logistics in the United States prioritize gas-powered field units with simplified operator training.
- Insulin Administration:Daily self-injection protocols demand compact, patient-operable devices with dose accuracy verification. Home healthcare providers in Germany specify piezoelectric platforms for adherence monitoring and digital connectivity.
- Dermatological Treatment:Superficial tissue targeting with adjustable penetration depths for cosmetic and therapeutic indications.
- Veterinary Care:Large-animal dosing with enhanced pressure tolerance for thicker dermal layers.
Vaccination Delivery commands largest shipment volumes; Insulin Administration shows steepest expansion trajectory.
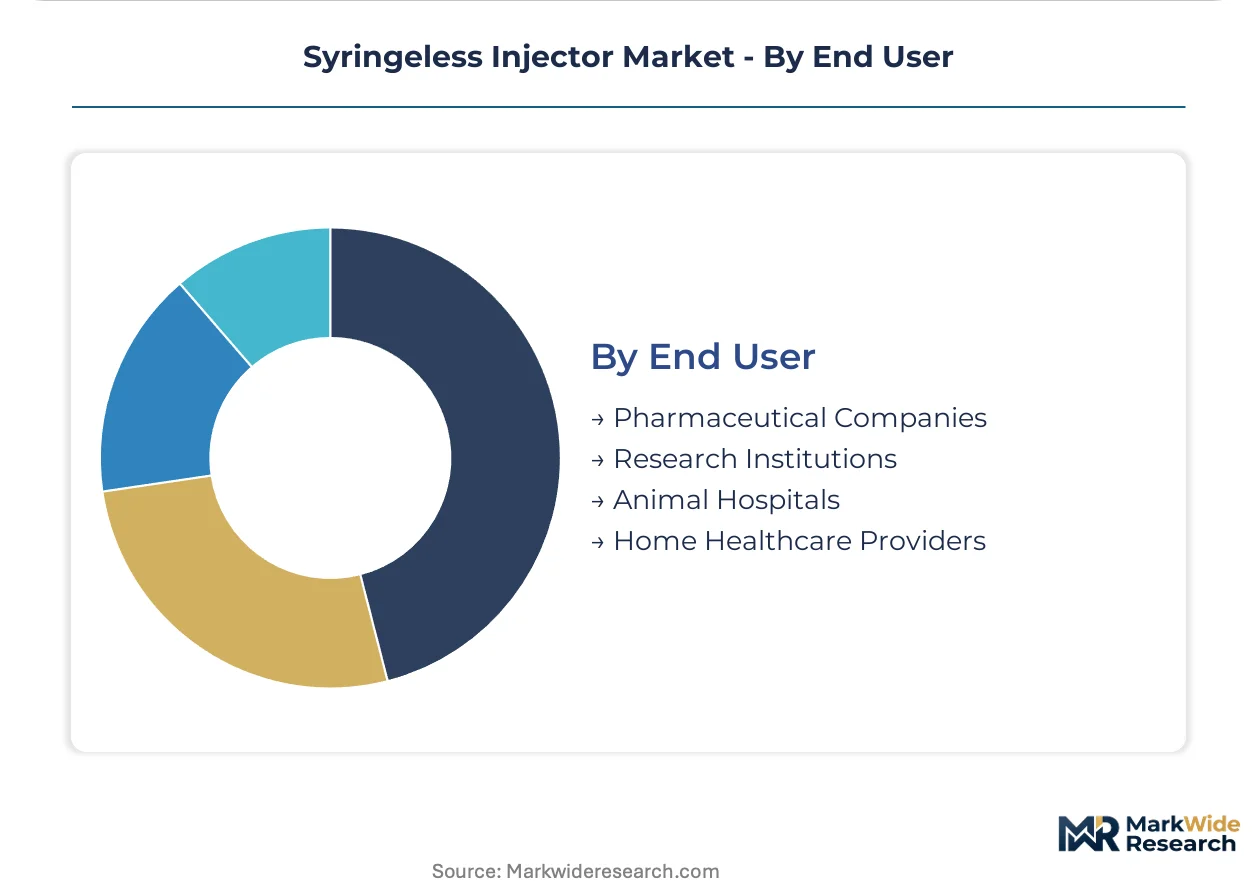
End User:
Capital intensity and regulatory sophistication determine procurement authority and service contract structures.
- Pharmaceutical Companies:Drug-device combination development requires validated injection platforms for regulatory submission packages. Bayer and Bracco Imaging anchor demand through R&D partnerships and long-term service agreements.
- Home Healthcare Providers:Patient-directed administration shifts specification toward portability, error-proofing, and connectivity. Medicare reimbursement code evolution in the United States will determine whether adoption accelerates beyond early-adopter networks.
- Research Institutions:Preclinical and clinical trial applications with customizable parameter ranges.
- Animal Hospitals:Veterinary-specific dosing with species-calibrated pressure profiles.
Pharmaceutical Companies concentrate procurement value today; Home Healthcare Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States prioritize sharps injury reduction more aggressively than German outpatient networks, where EU MDR harmonized standards drive retrofit cycles for legacy spring-loaded systems.
United States
OSHA bloodborne pathogen standards and EPA hazardous waste regulations reinforce specification of needle-free platforms across hospital networks. FDA 510(k) clearance pathways compress time-to-market for manufacturers with established predicate devices. Boston and Minneapolis medical device clusters concentrate R&D partnerships between imaging OEMs and injector specialists.
Germany
Outpatient clinic networks retrofit injection suites with gas-powered and electromagnetic systems to satisfy EU MDR technical documentation requirements. BfArM oversight of Class IIa medical devices extends validation timelines for predicate-device equivalence claims. Baden-Württemberg and Bavaria host the densest concentrations of notified body consulting and electromagnetic actuator manufacturing.
Japan
PMDA quality management system inspections favor manufacturers with established ISO 13485 certification and domestic clinical evidence. METI industrial technology grants support piezoelectric ceramic research for precision dosing applications. Tokyo and Osaka metropolitan areas concentrate pharmaceutical-device combination development partnerships.
China
NMPA innovation pathway designations accelerate review timelines for electromagnetic injection platforms with domestic clinical data. Provincial procurement consortia in Jiangsu and Guangdong pilot centralized needle-free device tenders for mass vaccination stockpiles. Yangtze River Delta electronics manufacturing clusters supply precision pressure sensors and embedded control modules.
India
CDSCO medical device rules harmonization with IMDRF guidelines simplifies import licensing for established electromagnetic platforms. PLI scheme incentives attract contract manufacturing of spring-loaded disposable nozzles for export markets. Hyderabad and Bengaluru biotech corridors incubate local assembly partnerships for gas-powered field units.
Syringeless Injector Market Competitive Landscape
Top-tier vendors anchor imaging equipment integration, while mid-tier specialists compete on electromagnetic platform modularity. The vendor base stratifies across three tiers: imaging OEMs extending service infrastructure, pharmaceutical-device combination developers, and pure-play injection technology specialists. Two strategic archetypes dominate: preventive maintenance contract aggregators and software-defined flow-rate programming innovators. Competitive moves concentrate on strategic partnerships for imaging workflow integration and geographic expansion through notified body consulting networks.
Among imaging-integrated service providers, GE HealthCare and Bracco Imaging represent the maintenance contract archetype, anchoring long-term calibration and compliance monitoring agreements across European hospital networks. Bayer occupies a position exemplifying pharmaceutical-device combination development, with R&D intensity in electronic control modules. Shenzhen Antmed and Shenzhen Seacrown Electromechanical sit within the emerging manufacturing tier, supplying electromagnetic base units and precision nozzle cartridges.
| Leading Market Players |
|---|
| Bracco Imaging |
| Bayer |
| GE HealthCare |
| Guerbet |
| Ulrich GmbH & Co. KG |
| MEDTRON AG |
| Nemoto Kyorindo |
| Shenzhen Antmed |
| Shenzhen Seacrown Electromechanical |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Germany and Japan anchor precision ceramic nozzle manufacturing, translating concentrated ownership into disciplined capacity management that shields premium-tier pricing from commoditization pressures while constraining supply elasticity for electromagnetic actuator platforms.
Pricing Analysis
Capacity additions in China are reshaping price floors for spring-loaded disposable nozzles, compressing margins on mechanical systems while piezoelectric platforms sustain premium-mid-economy pricing differentiation through FDA 510(k) certification tiers and embedded software modules. Price differentiation hinges on EU MDR technical documentation completeness and real-time pressure feedback capability. Pricing pressure stems from hospital procurement departments unbundling after-sales service from hardware acquisition. Mass vaccination buyers exhibit highest price sensitivity; academic medical centers demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA innovation pathway are reshaping sourcing patterns for electromagnetic base units and precision pressure sensors. Manufacturing concentrates in China, Germany, and Japan. Component sourcing draws from Japanese ceramic foundries, German seal specialists, and Yangtze River Delta electronics clusters. Single-source vulnerability persists for piezoelectric crystal substrates. Distribution runs through imaging OEM service infrastructure and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in syringeless injectors rests on software-defined service revenue displacing transactional hardware economics, with electromagnetic platforms capturing premium positioning as biologic drug viscosity requirements escalate delivery pressure specifications.
For Market Incumbents: Cement preventive maintenance contract density across European hospital networks before outpatient clinic procurement committees consolidate vendor panels. Acquire electromagnetic actuator engineering talent in Baden-Württemberg to preempt capability gaps. Lock in long-term ceramic nozzle supply agreements with Japanese specialty suppliers to defend against input bottlenecks. For New Entrants and Emerging Players: The price-point gap between premium piezoelectric systems and economy spring-loaded units opens white space for modular electromagnetic platforms with software-upgradeable pressure curves. Target German outpatient clinic networks facing EU MDR retrofit deadlines. Pursue hospital system partnerships offering imaging workflow integration as the go-to-market anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play injection technology specialists lacking imaging OEM service infrastructure. Five-to-ten-year viability favors firms with electromagnetic platform modularity and notified body consulting capabilities. Monitor Medicare reimbursement code evolution for needle-free drug delivery as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Pathway | Front-loaded clinical evidence generation preempts notified body scrutiny for electromagnetic platforms in Germany. |
| Hospital System Partnership | GE HealthCare and Bracco Imaging leverage imaging equipment service infrastructure for injector calibration lock-in. |
| Software Companion Development | Real-time pressure feedback modules enable outcome-based service contracting beyond hardware margins. |
| Backward Integration into Ceramic Nozzles | Japanese and German specialty supplier relationships mitigate high-pressure component sourcing bottlenecks. |
| Reimbursement Strategy | Medicare coverage determination for needle-free delivery dictates outpatient clinic adoption acceleration in the United States. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market combining interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and SEC filings. Bottom-up and top-down triangulation cross-checks manufacturer shipment data against end-user installation records.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, modeling device architecture, delivery mechanism, application setting, and end-user capital intensity as core segmentation dimensions. CAGRs derive from installed base replacement cycles, retrofit demand concentration, and reimbursement code evolution. Forecast inputs incorporate biologic drug viscosity expansion trajectories and EU MDR implementation deadlines.
The model assumes a particular technology adoption path; alternative pathways for piezoelectric platform cost reduction would alter the outlook. Forecasts reflect assumptions around FDA clearance timeline compression and OSHA enforcement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
North America Medical Devices Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Medical Coatings Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Treatment Pumps Market
Medical Devices
Trial Prostheses Market