
 Saudi Arabia Facial Aesthetics Market | 2026-2036
Saudi Arabia Facial Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Facial Aesthetics Market Insights
Clinic-based distribution is tilting toward medical spa and hospital-affiliated centers as patient preference shifts toward supervised environments. Galderma S.A. leverages its botulinum toxin portfolio to anchor premium positioning in Riyadh's dermatology corridor. Merz Pharma competes through specialized filler formulations targeting Middle Eastern facial anatomy. Alma Lasers controls the energy-based device segment with localized service infrastructure.
Facial aesthetics encompasses minimally invasive and non-invasive procedures that modify skin texture, volume, and contour using injectable neuromodulators, hyaluronic acid formulations, chemical exfoliants, or thermal energy devices operating at wavelengths between 532 nm and 10,600 nm depending on target chromophore. These interventions primarily serve cosmetic enhancement and age-related facial restoration in outpatient settings. Botulinum toxin and dermal fillers dominate product type revenue due to repeat treatment cycles and established safety profiles, while laser therapy leads technology adoption for skin resurfacing applications. Lip enhancement and non-surgical rhinoplasty represent faster-growing application areas as social media visibility drives demand for defined facial features among Saudi consumers aged 25 to 40.
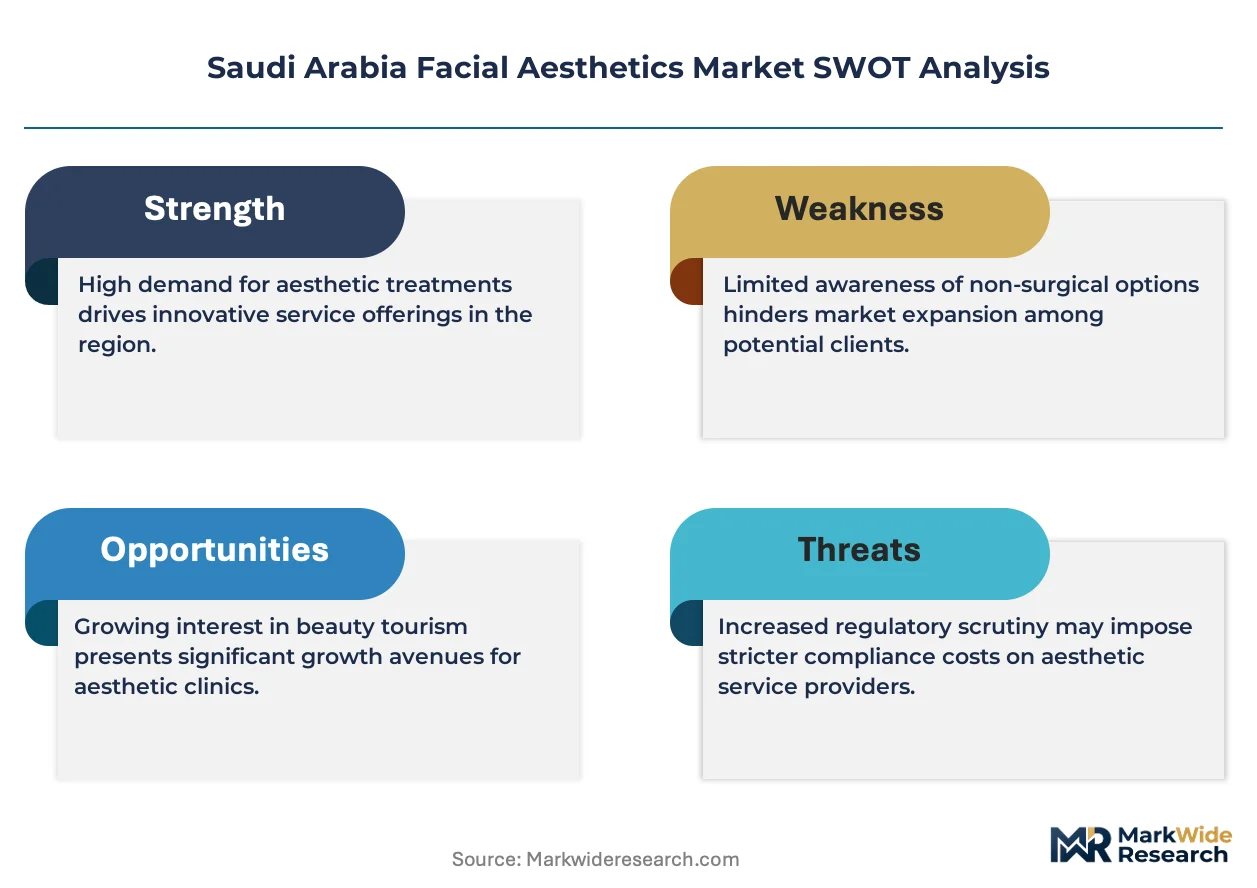
SFDA oversees medical device approval and post-market surveillance for aesthetic equipment, while the Saudi Commission for Health Specialties regulates practitioner licensing and facility accreditation standards. These frameworks elevate compliance costs for new entrants but protect established providers with certified training programs and documented adverse event protocols. Stakeholders must monitor evolving ministry directives on combination therapies and cross-border teleconsultation services that could reshape patient acquisition channels.
Market Dynamics
SFDA device registration requirements and Saudi Commission for Health Specialties licensing rules are compressing market entry timelines and elevating capital thresholds for aesthetic equipment providers.
Growth Catalysts
- Preventive treatment protocols:Younger patient cohorts in Riyadh and Jeddah are initiating neuromodulator regimens earlier, compressing treatment intervals and expanding lifetime value per consumer.
- SFDA medical device framework:Streamlined registration pathways for Class II aesthetic devices are accelerating commercialization timelines for energy-based equipment manufacturers.
- Central Region healthcare clustering:Premium clinic networks anchored by Riyadh's dermatology corridor concentrate purchasing power and drive technology upgrade cycles.
Market Restraints
- Practitioner certification bottlenecks:Saudi Commission for Health Specialties mandates for injectable procedure licensing create enrollment backlogs that constrain service capacity expansion.
- Device import dependency:Energy-based equipment and hyaluronic acid formulations rely on European and Korean manufacturing clusters, exposing distributors to currency volatility and shipping disruptions.
- Adverse event documentation requirements:SFDA post-market surveillance protocols impose reporting burdens that elevate compliance staffing costs for mid-sized clinic operators.
Strategic Opportunities
- Western Region penetration:Jeddah and Mecca corridors remain underserved relative to Riyadh saturation, presenting first-mover positioning for specialized filler portfolios.
- Combination therapy protocols:Sequential application of botulinum toxin with fractional laser resurfacing is commanding premium pricing in hospital-affiliated centers.
- Teleconsultation integration:Ministry of Health directives on cross-border digital health services are opening patient acquisition channels for outbound medical tourism recovery.
Industry Challenges
- Injection technique specialization:Shortage of certified practitioners for Middle Eastern facial anatomy protocols limits service menu expansion in secondary cities.
- Equipment amortization pressure:Multi-wavelength laser platforms require high utilization rates to justify capital outlay, squeezing margin in competitive catchment areas.
- Combination therapy liability:Unclear adverse event attribution between device and injectable components complicates malpractice coverage and informed consent documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Facial Aesthetics Market |
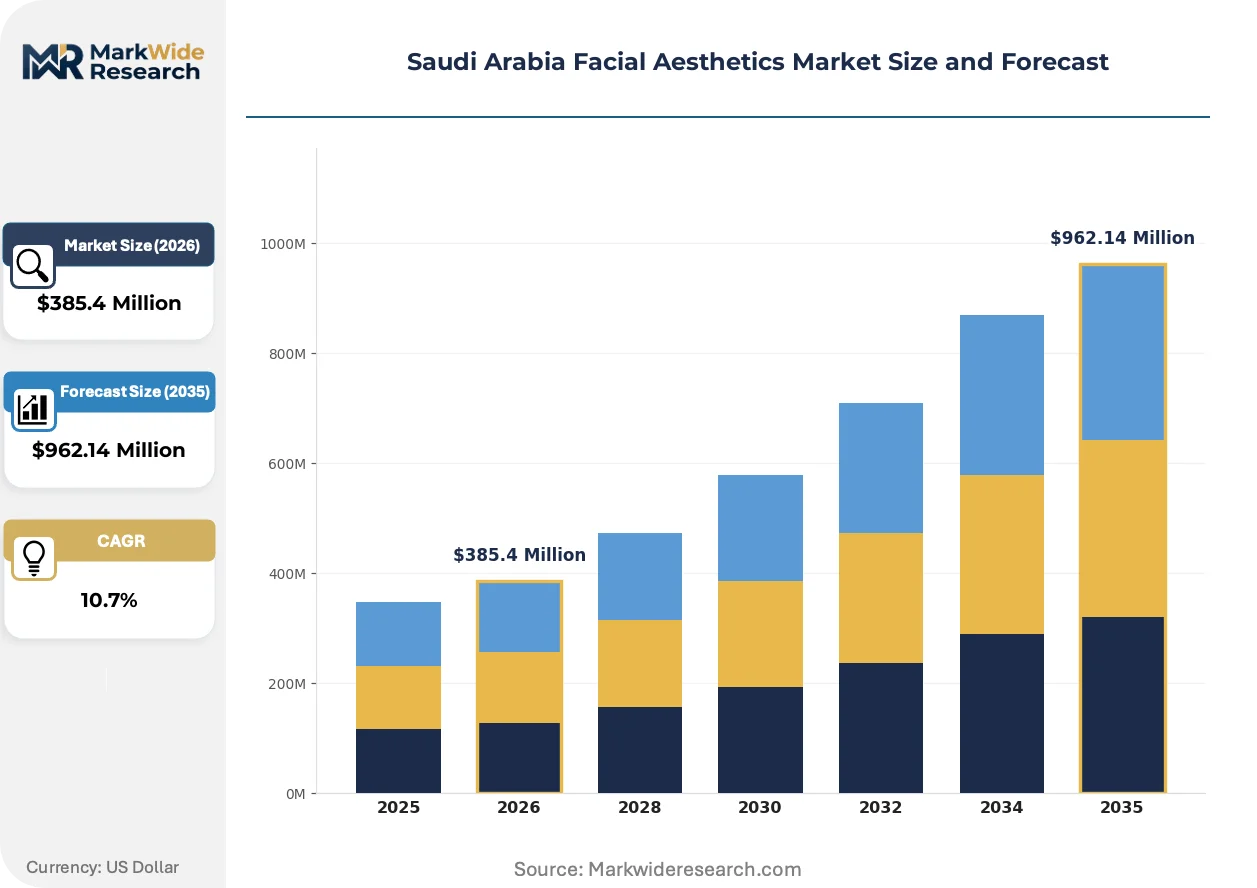
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $962.14 Million |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Dermal Fillers, Chemical Peels, Microdermabrasion Application: Wrinkle Reduction, Lip Enhancement, Skin Resurfacing, Non-Surgical Rhinoplasty End User: Clinics, Beauty Salons, Medical Spas, Hospitals Technology: Laser Therapy, Ultrasound, Radiofrequency, Microneedling |
| Companies Covered | Galderma S.A., Merz Pharma, Lumenis Inc., Ipsen SA, Cynosure, Candela Medical, Alma Lasers, Magrabi Health, AbbVie Inc (Allergan Aesthetics), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Facial Aesthetics Market Trends and Innovations
Digital simulation tools and energy-device miniaturization are compressing consultation-to-treatment timelines while expanding addressable patient bases beyond traditional clinic footprints.
Artificial intelligence-powered facial mapping software is virtualizing pre-treatment visualization for non-surgical rhinoplasty and lip enhancement planning. Dermatology clinics in Riyadh are deploying these platforms to reduce consultation duration and improve conversion rates. The technology is virtualizing patient expectations and reducing revision rates by aligning outcomes with simulated previews.
SFDA updated guidance on energy-based device classification is redefining quality benchmarks for imported aesthetic equipment. Manufacturers must now submit localized clinical data demonstrating efficacy on Middle Eastern skin phototypes. This regulatory tightening is accelerating consolidation among distributors with established adverse event tracking infrastructure.
Subscription-based treatment packages are displacing single-session pricing across premium clinic networks. Younger Saudi consumers aged 25 to 35 prefer locked-in annual rates for neuromodulator maintenance over per-visit charges. This behavioral shift is most visible in Jeddah's medical spa segment, where membership models now account for the majority of recurring revenue.
Saudi Arabia Facial Aesthetics Market Segmentation
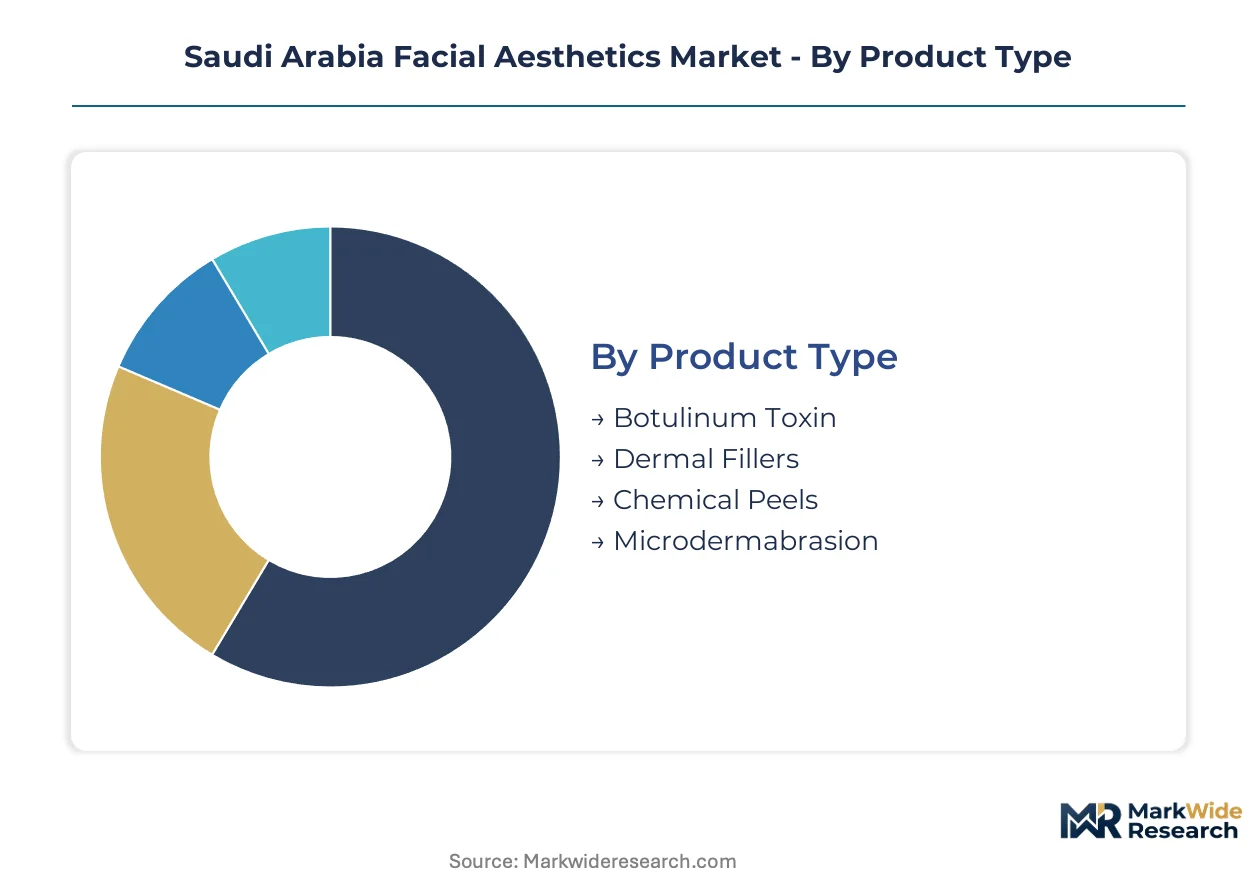
Segmentation in Saudi Arabia's facial aesthetics market reveals distinct procurement patterns across product categories and service delivery channels. Understanding these divides helps stakeholders align inventory, certification, and capital deployment with where purchasing power concentrates.
Product Type:
After-sales service intensity varies sharply across injectable portfolios, with botulinum toxin requiring cold-chain logistics support and hyaluronic acid fillers demanding technique-specific practitioner training programs.
- Botulinum Toxin:Purified neuroprotein formulations temporarily inhibit acetylcholine release at neuromuscular junctions to smooth dynamic rhytids. Riyadh's dermatology corridor accounts for the majority of vial consumption as preventive treatment protocols expand among Saudi consumers aged 25 to 40.
- Dermal Fillers:Cross-linked hyaluronic acid or calcium hydroxylapatite gels restore facial volume through subdermal or deep dermal injection. Jeddah's medical spa segment drives demand for lip enhancement and non-surgical rhinoplasty applications as social media visibility pressures intensify.
- Chemical Peels:Acid-based exfoliation solutions ranging from superficial glycolic to deep phenol formulations target dyschromia and textural irregularities.
- Microdermabrasion:Mechanical resurfacing using aluminum oxide crystals or diamond-tipped wands offers entry-level skin rejuvenation with minimal downtime requirements.
By volume, botulinum toxin leads. By growth pace, dermal fillers are expanding most quickly.
Application:
Cost tier stratification separates premium hospital-affiliated centers performing combination therapies from mid-market clinics focused on single-modality treatments.
- Wrinkle Reduction:Neuromodulator injections targeting glabellar lines, crow's feet, and forehead furrows constitute the foundational revenue stream across Saudi clinic networks.
- Lip Enhancement:Hyaluronic acid volumization of vermilion borders and philtral columns commands premium pricing in Jeddah and Riyadh as defined facial features gain cultural priority.
- Skin Resurfacing:Ablative and non-ablative laser protocols, chemical peels, and mechanical exfoliation address photodamage and acne scarring in outpatient settings.
- Non-Surgical Rhinoplasty:Injectable filler contouring of nasal dorsum and tip represents the fastest-climbing application as digital simulation tools reduce patient hesitation.
Wrinkle reduction generates the highest procedure counts. Non-surgical rhinoplasty shows the steepest expansion trajectory.
End User:
Customer type segmentation distinguishes supervised medical environments from cosmetology settings based on SFDA licensing requirements and practitioner certification tiers.
- Clinics:Dermatology and plastic surgery practices in Riyadh's healthcare cluster anchor premium positioning through SFDA-registered device inventories and specialist physician oversight.
- Medical Spas:Hybrid facilities combining aesthetic medicine with wellness services concentrate in Jeddah's Western Region corridor, capturing younger demographics through membership pricing models.
- Hospitals:Hospital-affiliated centers leverage combination therapy protocols and adverse event management infrastructure for complex revision cases.
- Beauty Salons:Non-medical establishments face tightening restrictions under Saudi Commission for Health Specialties rules limiting injectable scope.
Clinics dominate current revenue. Medical spas are gaining share fastest.
Technology:
Supply concentration among Korean and European equipment manufacturers shapes distributor strategies and service contract structures across energy-based modalities.
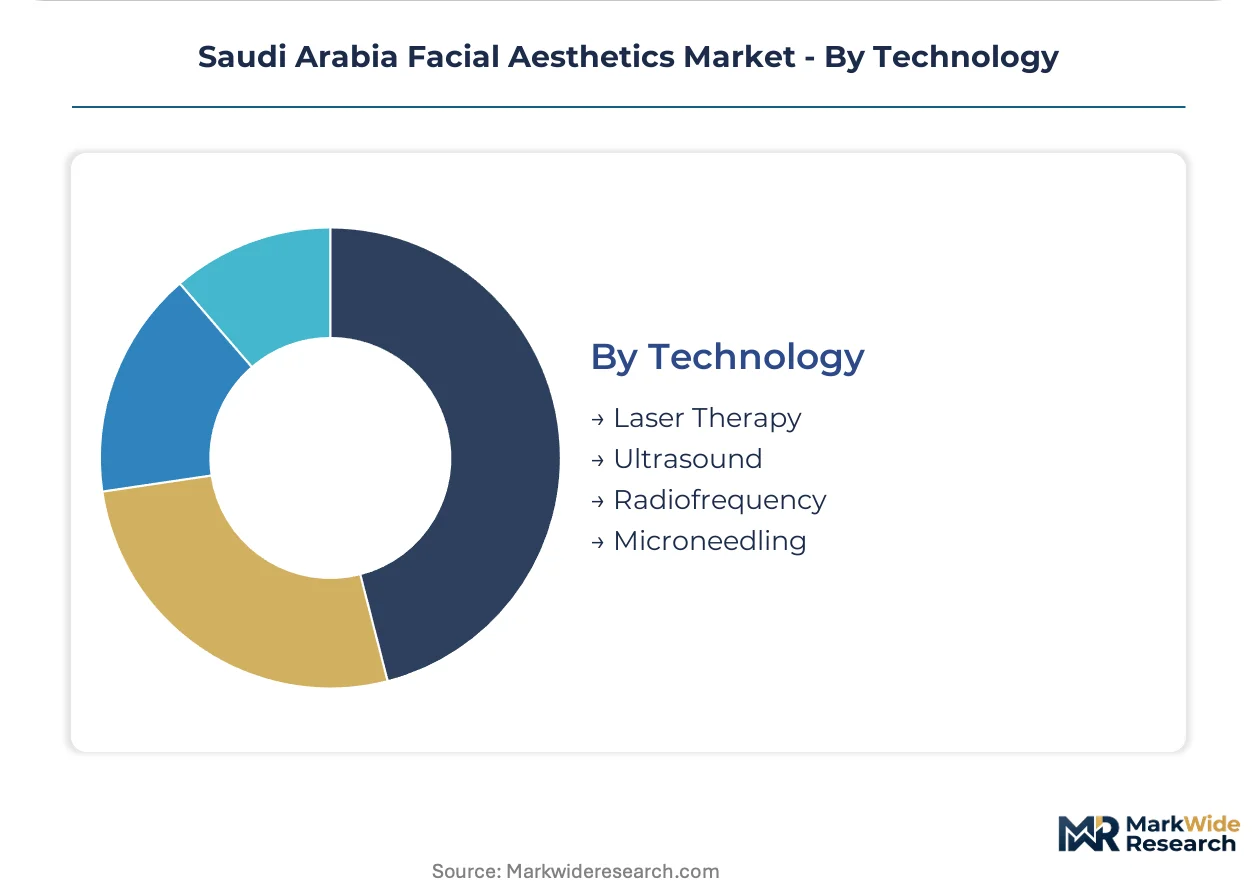
- Laser Therapy:Multi-wavelength platforms operating at 532 nm to 10,600 nm target specific chromophores for vascular lesions, pigmentation, and tissue ablation. Riyadh's premium clinic networks drive upgrade cycles for fractional CO2 and erbium:YAG systems.
- Radiofrequency:Thermal energy delivery through monopolar, bipolar, or fractional applicators stimulates neocollagenesis for skin tightening applications.
- Ultrasound:Microfocused and high-intensity focused ultrasound platforms penetrate to SMAS layers for non-invasive lifting.
- Microneedling:Percutaneous collagen induction using motorized or radiofrequency-coupled needle arrays addresses acne scarring and textural improvement with lower capital requirements.
Laser therapy holds the largest installed base. Radiofrequency systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium clinic networks in Riyadh extract pricing premiums that Jeddah's emerging medical spa corridor cannot yet match, creating a Central-to-Western Region value gap that shapes distributor investment priorities.
Riyadh
Preventive neuromodulator regimens among consumers aged 25 to 40 compress treatment intervals and expand per-patient lifetime value. SFDA medical device registration requirements tighten quality benchmarks for imported energy-based equipment. The King Faisal Specialist Hospital cluster anchors dermatology corridor expansion with certified practitioner training programs.
Jeddah
Membership-based pricing models for hyaluronic acid maintenance displace single-session charges among younger demographics. Saudi Commission for Health Specialties licensing rules constrain injectable procedure capacity expansion. The King Abdulaziz Medical City corridor concentrates medical spa development along the Western Region healthcare axis.
Eastern Province
Industrial workforce demand for minimal-downtime resurfacing protocols drives laser therapy adoption in outpatient settings. SFDA post-market surveillance protocols elevate compliance staffing costs for mid-sized operators. Dhahran's Aramco-affiliated healthcare network purchases multi-wavelength platforms for employee wellness programs.
Mecca Corridor
Pilgrimage-season patient flows create utilization spikes for temporary enhancement procedures. Ministry of Health directives on cross-border teleconsultation services open digital acquisition channels. Taif's emerging clinic networks target medical tourism recovery with combination therapy packages.
NEOM Northwest
Greenfield healthcare infrastructure construction embeds aesthetic medicine within wellness-focused master planning. Updated cosmetic procedure licensing frameworks from the Saudi Commission for Health Specialties apply prospectively to new facilities. The linear city development attracts device manufacturers seeking flagship installation sites.
Saudi Arabia Facial Aesthetics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and single-modality device supply. Market structure tilts toward concentrated injectable portfolios and fragmented energy-based equipment distribution. Three archetypes dominate: multinational pharmaceutical manufacturers with toxin portfolios, specialized laser OEMs with regional service infrastructure, and local distributor-integrators with SFDA registration expertise. Competitive moves concentrate on practitioner certification partnerships and adverse event tracking infrastructure.
Within the multinational pharmaceutical tier, Galderma S.A. and Merz Pharma exemplify divergent positioning strategies. Galderma anchors premium toxin positioning through Riyadh dermatology corridor penetration. Merz occupies a specialized filler formulation position targeting Middle Eastern facial anatomy protocols. Alma Lasers represents the energy-based device archetype with localized service infrastructure. These three entities collectively illustrate how regulatory compliance depth and clinical training investment separate sustainable market presence from transactional distribution.
| Leading Market Players |
|---|
| Galderma S.A. |
| Merz Pharma |
| Lumenis Inc. |
| Ipsen SA |
| Cynosure |
| Candela Medical |
| Alma Lasers |
| Magrabi Health |
| AbbVie Inc (Allergan Aesthetics) |
| Others |
Pricing and Supply Chain Analysis
SFDA device registration bottlenecks and Korean manufacturing concentration create dual chokepoints that compress margin tiers and force distributor consolidation. Pricing stratifies across premium clinic networks with full regulatory compliance infrastructure and mid-market operators absorbing higher cold-chain logistics costs.
Pricing Analysis
The customization-premium spread separates configured-to-order hyaluronic acid formulations from standard botulinum toxin vials. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Pricing pressure stems from membership model proliferation in Jeddah's medical spa segment. Younger demographics aged 25 to 35 exhibit highest price sensitivity through subscription preference, while hospital-affiliated centers show lowest sensitivity due to adverse event insurance requirements.
Supply Chain Analysis
Export-control restrictions on multi-wavelength laser platforms limit European and Korean OEM flows into Saudi distribution channels. Manufacturing concentrates in South Korea, Germany, and Switzerland for energy-based equipment, with hyaluronic acid raw materials drawing from Japanese and French bioprocessing clusters. Single-source vulnerability runs through Seoul-based laser OEMs serving Riyadh's dermatology corridor. Distribution runs through SFDA-registered importer-integrators with localized service technicians.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi facial aesthetics market sits in early-cycle recovery as pilgrimage-season patient flows normalize and medical tourism channels reopen. Younger cohort treatment initiation compresses repeat purchase cycles and expands addressable lifetime value.
For Market Incumbents: Build certification moats through Saudi Commission for Health Specialties partnership programs for Middle Eastern facial anatomy protocols. Deepen backward integration into cold-chain logistics to offset Korean import dependency. Secure exclusive distribution rights for next-generation fractional laser platforms before SFDA registration pathways tighten.
For New Entrants and Emerging Players: Build out Western Region presence in Taif and Mecca corridors where clinic density lags Riyadh saturation. Target medical spa membership models as the most penetrable channel. Pursue teleconsultation-integrated acquisition funnels aligned with Ministry of Health digital health directives.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors adverse-event-tracking infrastructure owners. Long-term viability over a 5-10 year window rests on regulatory compliance depth rather than device portfolio breadth. Monitor SFDA post-market surveillance staffing ratios as the inflection signal for mid-tier operator distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner Certification Partnership | Saudi Commission for Health Specialties alignment reduces enrollment backlogs and expands service capacity. |
| Cold-Chain Logistics Integration | In-house temperature-controlled distribution mitigates Korean import volatility for botulinum toxin portfolios. |
| Digital Simulation Platform Deployment | AI-powered facial mapping reduces consultation duration and improves conversion rates in Riyadh corridor. |
| Western Region Clinic Network Expansion | First-mover positioning in Jeddah and Mecca corridors captures underserved patient flows. |
| Combination Therapy Protocol Development | Sequential botulinum toxin and laser resurfacing commands premium pricing in hospital-affiliated centers. |
Research Methodology
The analysis maps injectable neuromodulators, energy-based devices, chemical peels, and microdermabrasion segments, each validated through dermatology clinic operators, biomedical equipment procurement managers, and SFDA regulatory consultants. Primary interviews with plastic surgery practice owners and medical spa franchise heads combined with secondary validation against Saudi Commission for Health Specialties licensing records, SFDA medical device registration databases, and hospital procurement contract filings. Bottom-up procedure volume estimates triangulated with top-down healthcare expenditure flows.
Assumptions held fixed include SFDA regulatory framework continuity and Korean-European supply chain stability, while pilgrimage-season patient flow volatility and currency fluctuation were stress-tested across scenarios. Segmentation modeling spanned product type, application, end user, and technology dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating practitioner certification pipeline constraints and equipment replacement cycle patterns specific to aesthetic medicine.
Stress conditions across SFDA registration timeline delays, Korean won volatility, and Saudi consumer confidence indices were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on preventive treatment protocol adoption rates and medical spa membership penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Non-Surgical Fat Reduction Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market