
 Non-Invasive Fat Reduction Market | 2026-2036
Non-Invasive Fat Reduction Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Fat Reduction Market Intelligence
Pay-per-procedure leasing and asset-light clinic partnerships are tilting competitive dynamics toward mid-scale operators that previously faced capital barriers. Alma Lasers leverages its multi-technology platform to serve diverse clinic footprints across Europe and Asia. BTL Industries anchors its position through in-house manufacturing of electromagnetic and cryotherapy systems. Candela Corporation differentiates via integrated laser and energy-based device portfolios that span fat reduction and skin rejuvenation.
Non-invasive fat reduction encompasses energy-based body-contouring procedures that apply controlled thermal, mechanical, or electromagnetic energy to adipose tissue without surgical incision, typically operating at temperatures between minus eleven and forty-three degrees Celsius depending on modality. These technologies serve commercial aesthetic medicine by offering outpatient alternatives to liposuction with minimal downtime and lower complication profiles. Cryolipolysis systems occupy mature margin pools in established clinic networks, while high-intensity focused ultrasound represents the fastest-growing technology segment as practitioners seek deeper tissue penetration with shorter treatment durations. Radiofrequency platforms sustain steady demand through dual applications in skin tightening and cellulite treatment, creating cross-selling opportunities that ultrasound and laser modalities rarely match.
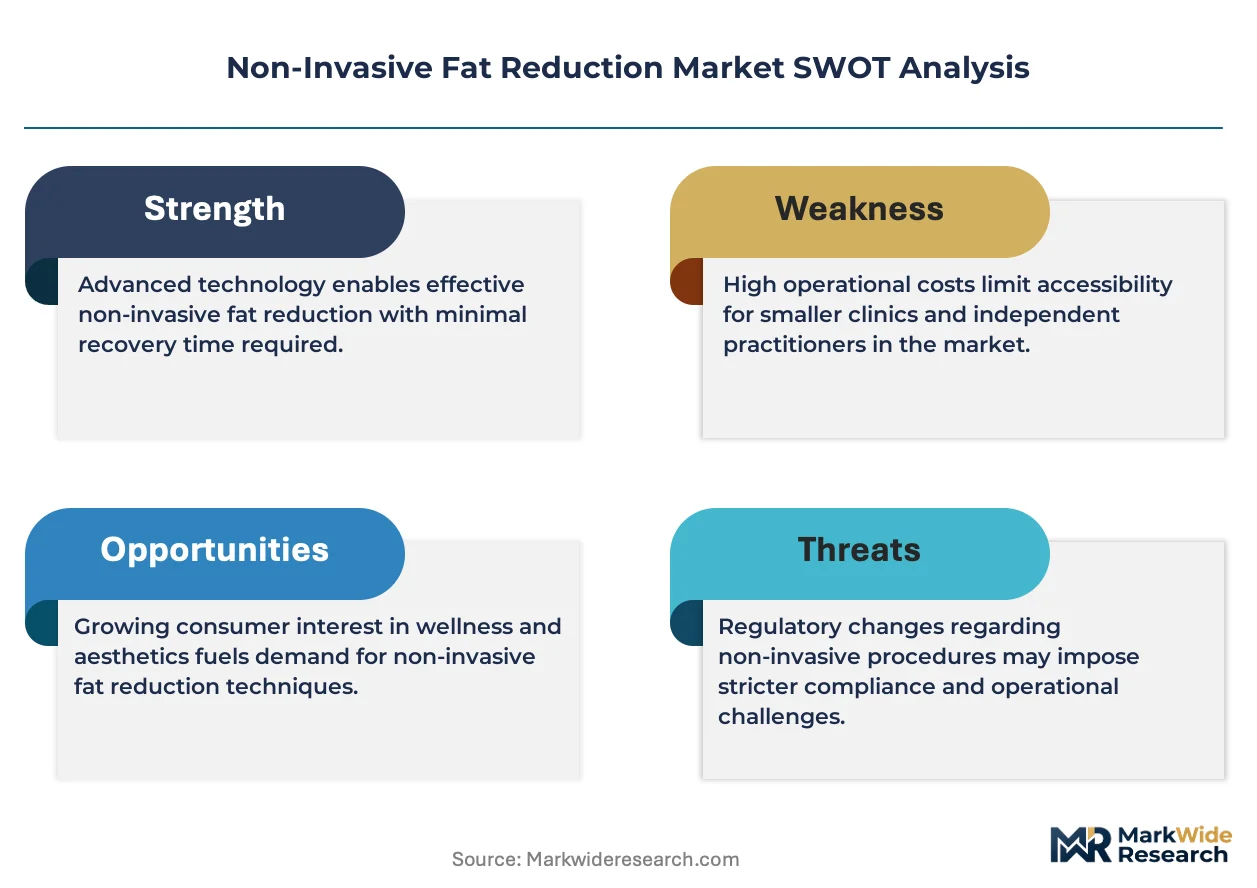
FDA device-clearance requirements under 510(k) and de novo pathways govern market entry for cryolipolysis and laser systems in the United States, while the EU Medical Device Regulation mandates notified-body conformity assessments for CE-marked energy-based aesthetic devices sold across European member states. China's National Medical Products Administration implements clinical-trial and registration standards that delay foreign product launches but incentivize domestic development of radiofrequency and ultrasound platforms. Stakeholders must monitor evolving reimbursement classifications for aesthetic procedures in Germany and South Korea, where selective coverage for medically indicated fat reduction could reshape volume distribution between hospital outpatient departments and private clinic settings.
Market Dynamics
Pay-per-procedure leasing models are compressing capital barriers for mid-scale aesthetic clinics, tilting competitive dynamics toward operators that previously lacked balance-sheet capacity for cryolipolysis and radiofrequency platforms. This financial innovation is reshaping how device manufacturers structure partnerships and revenue recognition.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter CE-marking requirements for energy-based aesthetic devices are filtering out marginal competitors and concentrating demand among notified-body-certified manufacturers with established clinical dossiers.
- Radiofrequency dual applications:Practitioners increasingly cross-sell skin tightening alongside fat reduction, expanding per-patient revenue without incremental device capital.
- Metropolitan clinic density:United States urban markets demonstrate procedure volume concentration that justifies dedicated cryolipolysis suites and amortizes fixed costs across higher throughput.
Market Restraints
- Electromagnetic component supply:Concentrated sourcing of high-power RF generators from German and Japanese suppliers creates input vulnerability for mid-tier device assemblers.
- FDA 510(k) pathway friction:Substantial equivalence determinations for novel thermal delivery profiles extend clearance timelines and defer commercial launch revenue.
- Surgical liposuction substitution:Persistent price compression in traditional suction-assisted lipectomy limits ceiling pricing for non-invasive alternatives in cost-sensitive patient segments.
Strategic Opportunities
- South Korea reimbursement expansion:Selective national health insurance coverage for medically indicated adipose reduction could shift volume from private clinics to hospital outpatient departments.
- Cryolipolysis-ultrasound convergence:Hybrid platforms combining controlled cooling with high-intensity focused ultrasound enable deeper tissue targeting and shorter session durations.
- Asset-light clinic partnerships:Revenue-sharing arrangements with dermatology chains and med-spa networks reduce customer acquisition costs for device vendors.
Industry Challenges
- Clinical training standardization:Heterogeneous certification requirements across state medical boards and professional societies complicate workforce deployment for multi-site clinic operators.
- Legacy EMR integration:Proprietary device software interfaces require custom middleware development to synchronize treatment documentation with existing practice management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Fat Reduction Market |
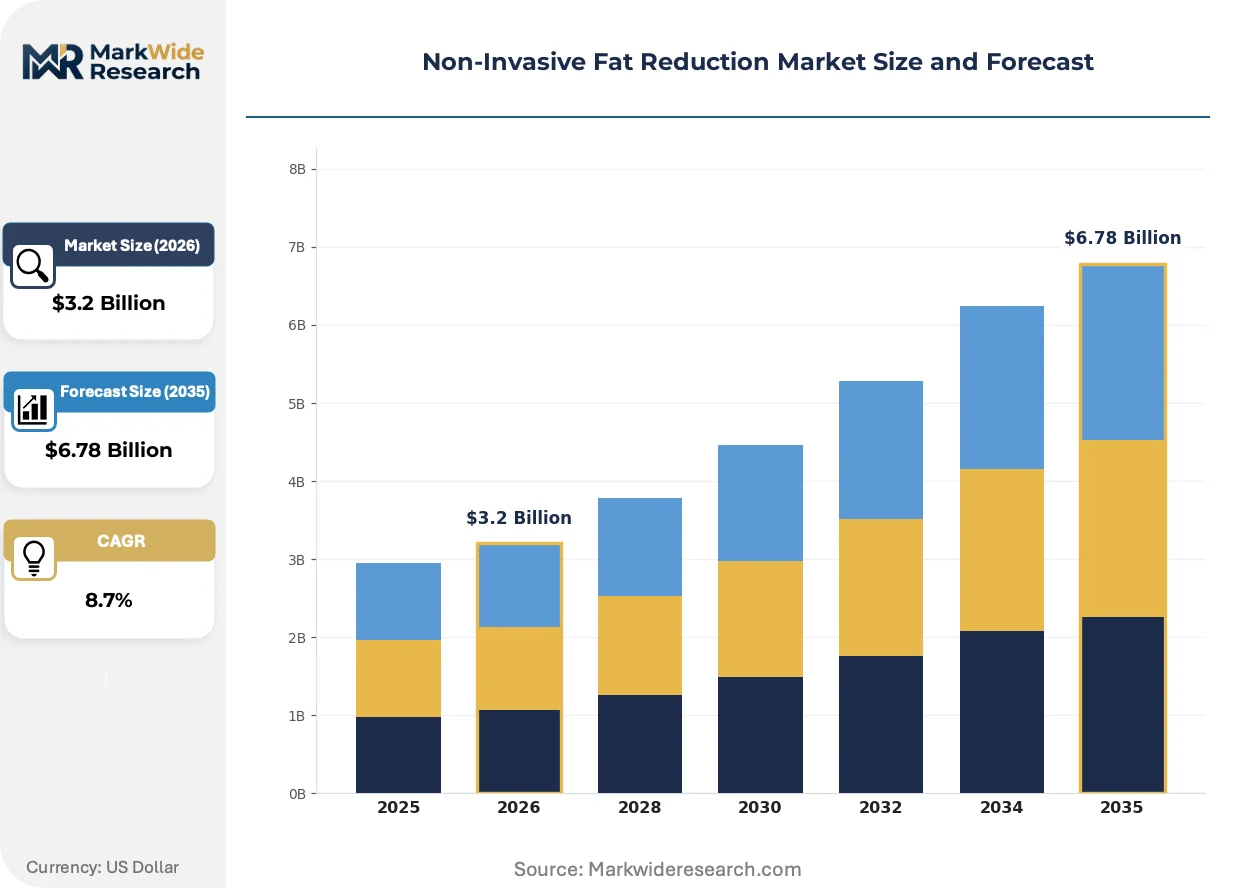
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryolipolysis, Ultrasound, Radiofrequency, Laser Therapy End User: Clinics, Spas, Hospitals, Home Users Application: Body Contouring, Cellulite Treatment, Skin Tightening, Weight Loss Technology: Cool Sculpting, High-Intensity Focused Ultrasound, Vacuum Therapy, LED Therapy |
| Companies Covered | Candela Corporation, Alma Lasers, AbbVie (Allergan Aesthetics), Bausch Health (Solta Medical), Venus Concept, Cynosure, BTL Industries, Lumenis, Cutera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Fat Reduction Market Strategic Shifts & Innovations
Real-time tissue monitoring capabilities are redefining treatment safety margins and enabling personalized energy delivery algorithms that adapt to individual adipose thickness and vascularity patterns.
Artificial intelligence-guided treatment planning is digitizing pre-procedure assessment workflows. Aesthetic medicine practitioners in German university hospitals are piloting computer-vision platforms that map subcutaneous fat distribution and predict optimal applicator positioning. This capability compresses consultation duration while standardizing outcomes documentation for liability protection.
China's National Medical Products Administration (NMPA) has implemented accelerated review tracks for domestically manufactured radiofrequency and ultrasound platforms that demonstrate equivalence to predicate devices. Foreign manufacturers face extended clinical trial requirements that delay market entry by 18-24 months relative to domestic competitors. South Korean and Japanese device firms are responding by establishing joint ventures with NMPA-registered local entities to bypass direct registration bottlenecks.
Subscription-based equipment access is displacing outright purchase for independent dermatology practices. United States-based clinic operators increasingly favor all-inclusive per-procedure fees covering device maintenance, consumables, and software updates. This shift transfers technology obsolescence risk from clinic balance sheets to manufacturer retained ownership, concentrating vendor working capital requirements.
Non-Invasive Fat Reduction Market Segmentation
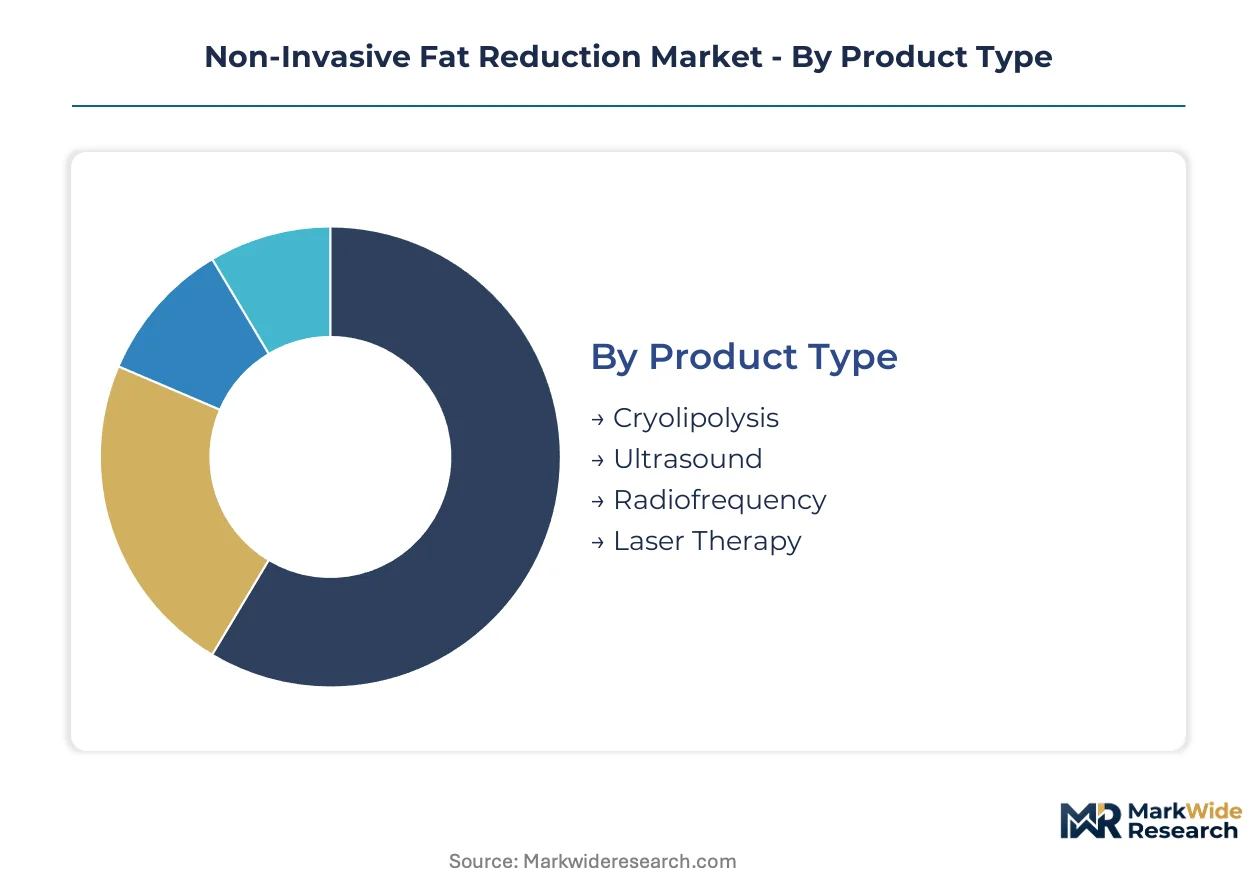
Energy modality selection dictates capital deployment, reimbursement positioning, and patient throughput economics for aesthetic providers. Technology convergence and end-user diversification are fragmenting traditional segment boundaries as cryolipolysis platforms integrate secondary radiofrequency capabilities.
Product Type:
Use-case spectrum spans immediate fat reduction through adipocyte apoptosis to gradual collagen remodeling for skin laxity correction.
- Cryolipolysis:Controlled cooling at minus eleven degrees Celsius induces selective adipocyte crystallization without epidermal damage. United States metropolitan clinic networks concentrate demand where FDA-cleared applicator portfolios justify dedicated treatment suites and premium per-session pricing.
- Radiofrequency:Thermal delivery at forty-three degrees Celsius enables dual-revenue streams combining fat reduction with cellulite treatment. German aesthetic medicine practices favor these platforms for cross-selling opportunities that ultrasound and laser modalities rarely match.
- Ultrasound:Mechanical energy disrupts adipose membranes through cavitation effects for patients seeking non-thermal alternatives.
- Laser Therapy:Low-level energy applications target superficial fat layers with minimal downtime requirements.
The dominant share belongs to cryolipolysis, while radiofrequency is closing the gap fastest.
End User:
Customer-type concentration determines device specifications, financing structures, and regulatory compliance burdens.
- Clinics:Medical aesthetic facilities require FDA 510(k)-cleared or CE-marked platforms with clinical training protocols and liability documentation systems. South Korea's clinic density supports manufacturer direct sales forces and localized technical service networks.
- Spas:Wellness-oriented operators prioritize compact footprint devices with simplified operator interfaces and lower consumable costs.
- Hospitals:Outpatient departments in Germany and South Korea demand integration with electronic medical records and standardized outcome tracking for potential reimbursement eligibility.
- Home Users:Direct-to-consumer segments concentrate in markets with established e-commerce aesthetic device distribution and consumer protection frameworks.
Clinics command the installed base majority, though hospital outpatient departments are expanding most quickly.
Application:
Volume distribution correlates with treatment duration, session count requirements, and patient expectation management complexity.
- Body Contouring:Comprehensive adipose reduction across abdominal, flank, and thigh zones requires multiple applicator configurations and extended treatment protocols. United States demand concentrates where patient willingness to undergo serial sessions supports per-procedure leasing economics.
- Skin Tightening:Collagen contraction applications leverage radiofrequency platforms for facial and neck zones with shorter treatment windows and higher per-minute revenue rates.
- Cellulite Treatment:Subdermal tissue remodeling targets connective tissue septae through combined thermal-mechanical approaches.
- Weight Loss:Adjunctive metabolic positioning remains commercially marginal due to limited clinical evidence and regulatory classification challenges.
Body contouring holds the volume lead, while skin tightening is gaining share fastest.
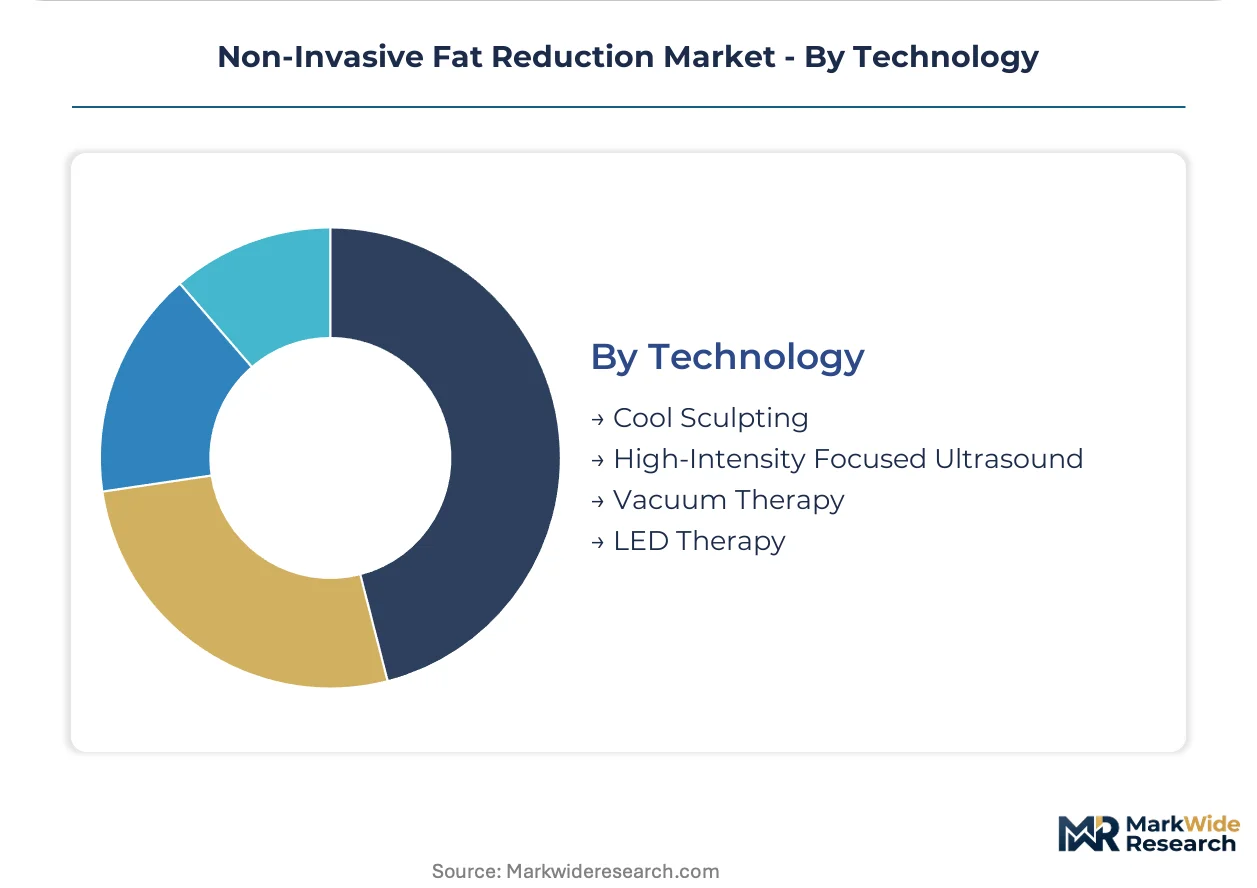
Technology:
Supply concentration for high-power electromagnetic components shapes vendor manufacturing strategies and input cost structures.
- Cool Sculpting:Proprietary controlled-cooling protocols with vacuum-assisted tissue draw enable standardized applicator positioning and reproducible outcomes. The technology anchors mature margin pools in established clinic networks with extensive installed bases.
- High-Intensity Focused Ultrasound:Deep tissue penetration at higher energy densities compresses treatment duration and expands treatable adipose thickness ranges. South Korean device manufacturers lead platform development with MFDS-registered systems.
- Vacuum Therapy:Mechanical manipulation combined with thermal or cooling energy enhances lymphatic drainage and treatment comfort profiles.
- LED Therapy:Photobiomodulation applications target superficial adipose with minimal thermal load and reduced contraindication profiles.
Cool sculpting retains the largest installed base, though high-intensity focused ultrasound is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands a 35-40% premium over German metropolitan markets, while South Korean clinics compress margins through density-driven competition and faster device depreciation cycles.
United States
FDA 510(k) clearances for cryolipolysis applicators concentrate demand among notified-body-certified manufacturers with established clinical dossiers. Metropolitan clinic networks in New York, Los Angeles, and Miami justify dedicated treatment suites through higher procedure throughput. The FDA's substantial equivalence pathway shapes product development timelines for novel thermal delivery profiles.
Germany
The EU Medical Device Regulation filters out marginal competitors through stricter CE-marking requirements for energy-based aesthetic devices. Radiofrequency platforms sustain dual-revenue streams combining fat reduction with cellulite treatment in Berlin and Munich aesthetic medicine practices. Germany's notified-body conformity assessments mandate comprehensive clinical evidence for market access.
South Korea
MFDS-registered high-intensity focused ultrasound systems lead platform development through domestic manufacturers in Seoul and Busan. Selective national health insurance coverage for medically indicated adipose reduction could shift volume from private clinics to hospital outpatient departments. The country's clinic density supports manufacturer direct sales forces and localized technical service networks.
China
NMPA accelerated review tracks favor domestically manufactured radiofrequency and ultrasound platforms demonstrating equivalence to predicate devices. Foreign manufacturers face extended clinical trial requirements that delay market entry relative to domestic competitors in Shanghai and Beijing. Joint ventures with NMPA-registered local entities bypass direct registration bottlenecks.
Japan
METI standards and PMDA device classifications govern market entry for energy-based body-contouring platforms in Tokyo and Osaka aesthetic medicine markets. Conservative reimbursement positioning limits hospital outpatient department adoption compared to private clinic settings. Domestic distributors maintain preferred relationships with regional dermatology chains.
Non-Invasive Fat Reduction Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying high-power RF generators and electromagnetic assemblies to mid-tier device assemblers. The vendor base concentrates among multi-technology holding companies with diversified energy modality portfolios and pure-play cryolipolysis or ultrasound specialists with focused R&D pipelines. Three archetypes dominate: diversified energy-platform conglomerates, single-modality technology originators, and regional device assemblers dependent on outsourced electromagnetic components. Competitive moves center on pay-per-procedure leasing structures that transfer technology obsolescence risk to manufacturer balance sheets, and asset-light clinic partnerships that reduce customer acquisition costs.
Within the diversified energy-platform tier, Candela Corporation and Alma Lasers exemplify integrated laser and energy-based device portfolios spanning fat reduction and skin rejuvenation applications. BTL Industries occupies a position among vertically integrated manufacturers with in-house production of electromagnetic and cryotherapy systems. These three entities represent distinct strategic postures: portfolio breadth through acquisition-led expansion, multi-technology platform serving diverse clinic footprints, and captive manufacturing control over critical subsystems.
| Leading Market Players |
|---|
| Candela Corporation |
| Alma Lasers |
| AbbVie (Allergan Aesthetics) |
| Bausch Health (Solta Medical) |
| Venus Concept |
| Cynosure |
| BTL Industries |
| Lumenis |
| Cutera |
| Others |
Cost & Logistics Intelligence
Overcapacity in German RF generator manufacturing is compressing margins for mid-tier device assemblers while concentrating pricing power among vertically integrated OEMs with captive electromagnetic component production. This utilization asymmetry drives supplier consolidation and reshapes procurement strategies across cryolipolysis and ultrasound platform vendors.
Pricing Analysis
The customization-premium spread between configured-to-order cryolipolysis suites and standard radiofrequency platforms spans three-tier pricing structure across premium, standard, and economy levels. FDA 510(k) certification tier and applicator portfolio breadth drive price differentiation, with metropolitan clinic networks commanding volume discounts unavailable to independent dermatology practices. Cost compression in economy-tier devices is intensifying because electromagnetic component sourcing from concentrated German and Japanese suppliers limits assembler flexibility. Spas and wellness operators exhibit highest price sensitivity, while hospital outpatient departments in South Korea and Germany demonstrate lowest sensitivity due to potential reimbursement eligibility.
Supply Chain Analysis
Contract-manufacturing concentration for high-power RF generators centers on specialized electromagnetic component foundries in Germany, Japan, and select South Korean facilities. Cryolipolysis systems draw from concentrated sourcing of vacuum pumps and thermal control modules, while ultrasound platforms rest on piezoelectric transducer supply from Japanese and South Korean specialists. Single-source vulnerability for MFDS-registered HIFU subsystems creates procurement risk for non-integrated device vendors. Distribution runs through manufacturer direct sales forces in high clinic-density markets and specialized medical device distributors in fragmented geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from surgical liposuction price compression in cost-sensitive patient segments, requiring defensive repositioning around clinical outcome differentiation and capital-light partnership structures.
For Market Incumbents: Harden regulatory dossiers through expanded FDA 510(k) predicate device portfolios and accelerated CE marking under EU MDR notified-body pathways. Deepen upstream control over electromagnetic component supply through captive manufacturing or long-term offtake agreements with German and Japanese RF generator specialists. Surgical liposuction substitution threatens pricing floors; defend through pay-per-procedure leasing structures that transfer technology obsolescence risk from clinic balance sheets. For New Entrants and Emerging Players: Hospital outpatient departments in South Korea undergoing reimbursement expansion for medically indicated adipose reduction represent the most penetrable entry point for MFDS-registered platforms. Mid-scale aesthetic clinics in United States metropolitan markets previously excluded by capital barriers offer secondary white-space through asset-light partnership structures. Joint venture formations with NMPA-registered Chinese entities bypass direct registration bottlenecks and accelerate market access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subscription-based equipment access models as manufacturers retain ownership and working capital requirements concentrate on vendor balance sheets. Platform integrators with diversified energy modality portfolios demonstrate superior long-term viability against single-modality specialists vulnerable to technology displacement. Monitor South Korean national health insurance reimbursement decisions as inflection indicator for volume shift from private clinics to hospital outpatient departments.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified-body certification filters marginal competitors and concentrates demand among established clinical dossier holders. |
| Hospital System Partnership | Integration with electronic medical records in German and South Korean outpatient departments enables reimbursement eligibility positioning. |
| Software Companion Development | AI-guided treatment planning platforms in German university hospitals compress consultation duration and standardize outcomes documentation. |
| Reimbursement Strategy | Selective national health insurance coverage for medically indicated fat reduction in South Korea reshapes volume distribution between settings. |
| Joint Venture Formation | NMPA-registered local entities in China bypass direct registration bottlenecks and accelerate market entry for foreign manufacturers. |
Research Approach
The analysis maps cryolipolysis, radiofrequency, ultrasound, and laser therapy sub-sectors, each validated through aesthetic medicine practitioners, biomedical engineers, clinic procurement managers, and GPO contracts managers. Primary interviews with device manufacturers and clinic operators combined with secondary validation from FDA 510(k) filings, MFDS registration databases, EU MDR notified-body certificates, and NMPA clinical trial disclosures. Bottom-up procedure volume estimates and top-down market sizing triangulate across energy modality, end-user type, application, and geographic regulatory cluster dimensions.
Assumptions held fixed include current FDA clearance pathways and EU MDR conformity assessment timelines, while variables included South Korean reimbursement expansion scenarios and NMPA accelerated review track eligibility. Segmentation dimensions modeled encompass energy modality, end-user category, application type, and technology platform across the analysis window. CAGRs derive from procedure volume trajectories, installed base depreciation cycles, and per-session pricing dynamics. Forecast inputs incorporate clinic density metrics, pay-per-procedure leasing penetration rates, and electromagnetic component supply constraints.
Practitioners should monitor South Korean reimbursement classification decisions, NMPA registration timeline revisions, and EU MDR notified-body capacity constraints for early signals of forecast deviation. Regulatory pathway friction, supply concentration in RF generator manufacturing, and surgical liposuction substitution intensity constitute primary revision triggers. Quarterly review of FDA 510(k) clearance velocity, CE marking issuance rates, and hospital outpatient department adoption curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Italy Aesthetic Market