
 Aesthetic Medicine and Cosmetic Surgery Market | 2026-2036
Aesthetic Medicine and Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Aesthetic Medicine and Cosmetic Surgery Market Analysis
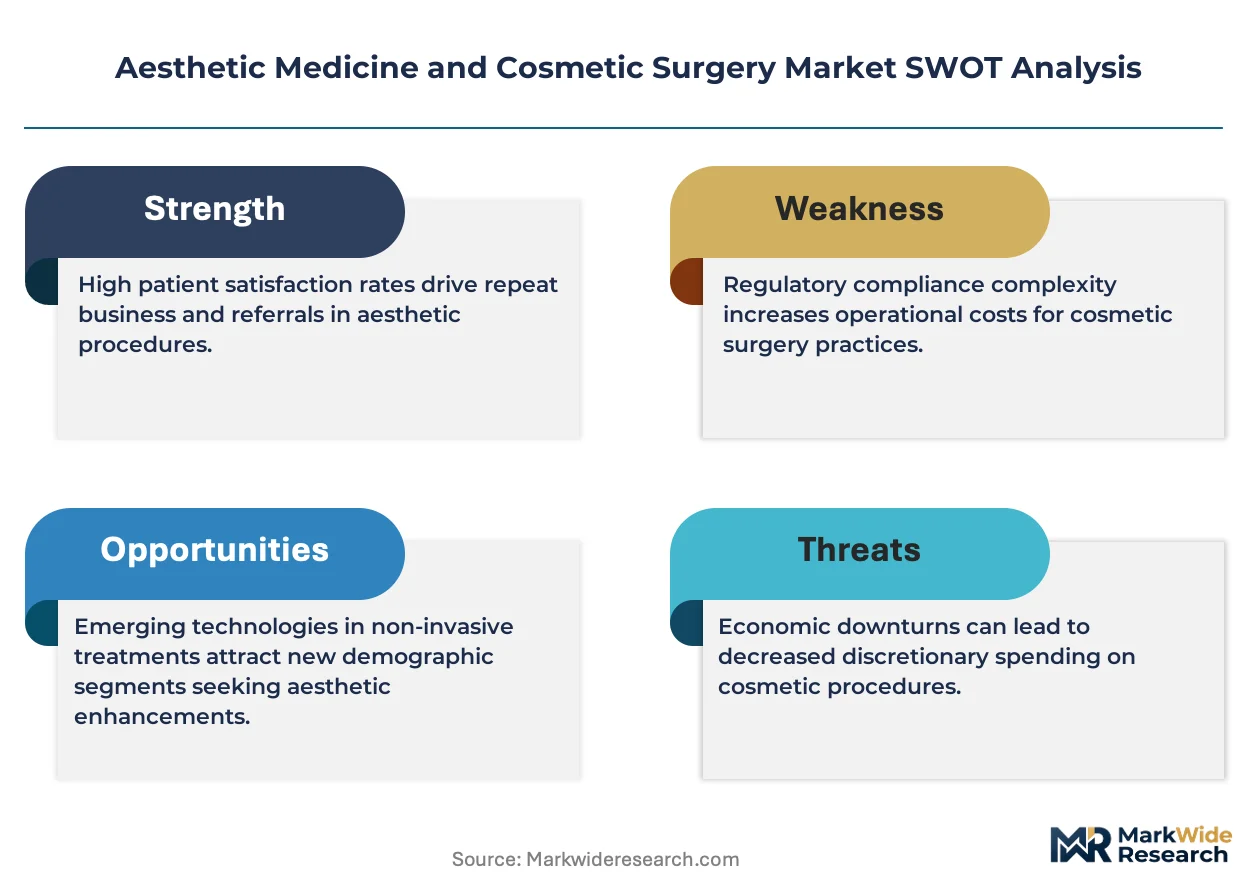
Board-certified plastic surgeons and dermatologists is bifurcating the competitive landscape into premium credential-driven practices and volume-oriented technician-staffed clinics. AbbVie/Allergan Aesthetics leverages its vertically integrated injectable portfolio to dominate high-margin botulinum toxin segments. Galderma sustains R&D intensity across hyaluronic acid filler chemistry, extending its therapeutic reach from wrinkles to facial contouring. Alma Lasers anchors geographic dominance in Asia-Pacific through localized manufacturing and regulatory registration support for its multi-platform aesthetic workstations.
Aesthetic medicine and cosmetic surgery encompasses minimally invasive and surgical interventions that modify soft tissue, bone structure, or skin appearance using pharmacological agents, thermal or light-based energy delivery, or mechanical instrumentation, typically requiring sterile field protocols and imaging guidance for precision outcomes. The field serves consumer-driven appearance enhancement and reconstructive restoration across ambulatory and inpatient settings. Injectable products lead current revenue pools due to repeat purchase cycles and lower capital requirements for administration, while laser treatments represent the fastest-growing service type as fractional and picosecond technologies expand indications beyond hair removal into pigmentation and scar revision. Surgical instruments occupy a mature margin structure where robotic-assisted platforms and disposable kits concentrate value capture among integrated device manufacturers.
The US FDA and the EU Medical Device Regulation shape product standards through distinct premarket review pathways for energy-based devices and implantable fillers, with FDA 510(k) clearance timelines directly influencing commercial launch sequencing for multinational portfolios. South Korea's MFDS and Ministry of Health and Welfare enforce advertising restrictions on before-and-after imagery and mandate cooling-off periods for surgical procedures, constraining direct-to-consumer marketing while elevating clinic reputation as the primary patient acquisition channel. Stakeholders must monitor evolving reimbursement categorization for reconstructive versus cosmetic indications across national health systems, as boundary shifts between elective and medically necessary procedures determine addressable patient pools and pricing autonomy.
Market Dynamics
The FDA's 510(k) clearance pathway for energy-based devices is compressing commercial launch timelines, forcing multinational manufacturers to sequence regulatory filings across jurisdictions while medspa chains absorb volume from traditional hospital outpatient departments.
Growth Catalysts
- MFDS advertising protocols:South Korea's cooling-off period mandates for surgical procedures elevate clinic reputation management over direct-to-consumer marketing, channeling patient acquisition toward accredited provider networks.
- Fractional laser platforms:Picosecond pulse durations expand treatment indications from hair removal into pigmentation disorders and scar revision, opening repeat-visit revenue pools in dermatology practices.
- Cross-border medical tourism:Government-backed infrastructure in Seoul clusters accredited clinics, attracting aesthetic patients from China and Southeast Asia through streamlined visa pathways and interpreter services.
Market Restraints
- Hyaluronic acid raw material concentration:Fermentation-grade sodium hyaluronate supply concentrates among three specialized bioproduction hubs, exposing filler manufacturers to batch consistency risks and input cost volatility.
- EU MDR technical documentation:Extended clinical evidence requirements for implantable fillers delay CE marking renewals, compressing commercial runway for legacy product portfolios ahead of certificate expiration.
- Non-invasive device substitution:Home-use LED masks and microcurrent tools capture maintenance-phase patients, eroding clinic visit frequency for established light-based treatment protocols.
Strategic Opportunities
- Sub-regional Brazil expansion:ANVISA's streamlined registration reciprocity with Mercosur neighbors creates white-space entry for multi-platform aesthetic workstations across São Paulo and Rio de Janeiro clinic networks.
- Combination therapy protocols:Convergence of botulinum toxin with radiofrequency microneedling enables bundled service pricing, differentiating premium credential-driven practices from technician-staffed volume clinics.
- Teleconsultation pre-screening:Digital triage platforms reduce no-show rates and optimize operating room utilization, particularly for reconstructive procedures requiring multi-stage surgical planning.
Industry Challenges
- Robotic surgical system integration:Capital-intensive platform adoption demands retraining of operating room staff and recalibration of sterile field protocols, stretching implementation timelines for mid-scale hospital systems.
- Biologics Master File navigation:Complex licensing arrangements between toxin producers and finished-device manufacturers create IP friction, delaying co-development partnerships for next-generation neurotoxin formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aesthetic Medicine and Cosmetic Surgery Market |
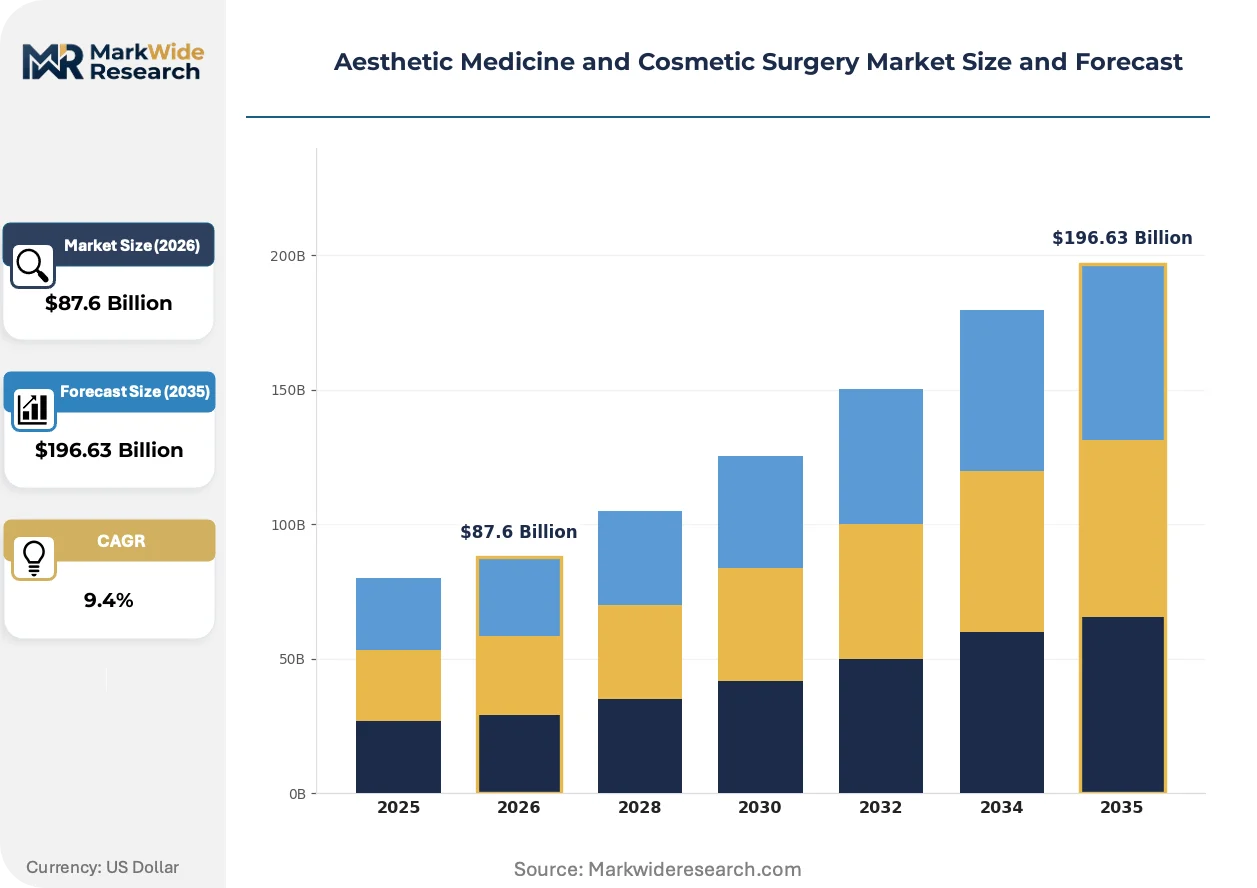
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Botox, Dermal Fillers, Laser Treatments, Chemical Peels End User: Individuals, Clinics, Hospitals, Medspas Procedure Type: Non-Surgical, Surgical, Minimally Invasive, Reconstructive Product Type: Injectables, Skincare Products, Surgical Instruments, Others |
| Companies Covered | Revance Therapeutics, Cynosure Lutronic, AbbVie/Allergan Aesthetics, Johnson & Johnson, Bausch Health Companies, Galderma, Alma Lasers, Anika Therapeutics, Merz Aesthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aesthetic Medicine and Cosmetic Surgery Market Emerging Trajectories
Energy delivery mechanisms and patient acquisition channels are undergoing parallel transformation, with device portability and digital front-door strategies displacing legacy capital-intensive installation models.
Portable diode laser systems for hair removal and vascular lesion treatment is miniaturizing handheld platforms below 500-gram thresholds, enabling physician extenders and nurse practitioners to administer protocols previously restricted to board-certified specialists. Medspa chains deploy these units in satellite locations with minimal build-out requirements, compressing patient access time from weeks to days while fragmenting procedure volume across distributed sites.
EU Medical Device Regulation's post-market surveillance requirements mandate systematic implant registries for long-duration fillers, compelling manufacturers to fund longitudinal safety databases. The regulatory burden falls heaviest on mid-tier hyaluronic acid producers lacking legacy clinical infrastructure, accelerating portfolio consolidation toward vertically integrated incumbents with dedicated pharmacovigilance operations.
Subscription-based maintenance programs for neurotoxin injections displace per-visit pricing in affluent urban markets, with patients pre-purchasing annual treatment cycles through mobile-enabled platforms. Los Angeles and Miami aesthetic practices report highest adoption of these membership models, where patient lifetime value calculations now incorporate churn probability and referral coefficient metrics alongside unit economics.
Aesthetic Medicine and Cosmetic Surgery Market Segmentation
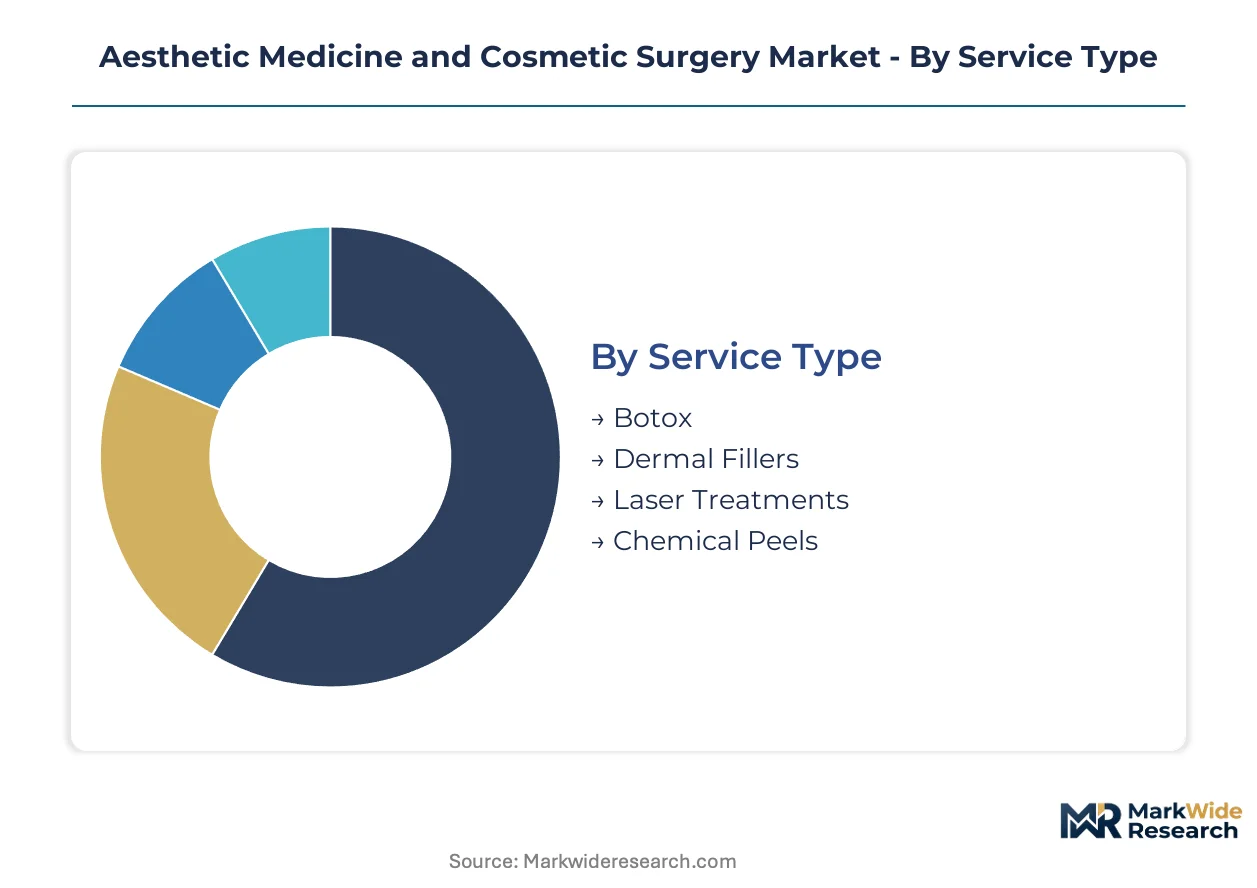
Segmentation in aesthetic medicine reveals how margin capture concentrates in repeat-purchase injectables versus capital-intensive surgical platforms, with channel choice determining pricing autonomy and patient lifetime value calculations.
Service Type:
Margin pools concentrate in neurotoxin and hyaluronic acid services where recurring appointment cycles generate predictable revenue streams independent of equipment depreciation schedules.
- Botox:Purified botulinum toxin type A formulations temporarily paralyze targeted facial muscles through precise intramuscular injection. Demand clusters in affluent urban corridors of Los Angeles and Miami where subscription-based annual treatment cycles displace per-visit pricing models.
- Dermal Fillers:Cross-linked hyaluronic acid gels restore volume through subdermal or supraperiosteal placement with reversible enzymatic dissolution options. Seoul's accredited clinic networks attract cross-border patients from China seeking facial contouring protocols beyond wrinkle reduction.
- Laser Treatments:Fractional and picosecond platforms address pigmentation disorders and scar revision with thermal or photomechanical tissue interaction.
- Chemical Peels:Acid-based exfoliation protocols ranging from superficial alpha-hydroxy applications to deep phenol resurfacing.
Botox holds installed capacity across premium credential-driven practices. Laser treatments are rotating up the share rankings as fractional technologies expand indications.
End User:
Channel configuration determines whether services deploy through hospital sterile fields or outpatient convenience settings, with regulatory compliance burdens varying sharply across site types.
- Individuals:Direct-to-consumer home-use LED masks and microcurrent tools capture maintenance-phase patients between professional interventions.
- Clinics:Board-certified plastic surgeon and dermatologist practices command premium pricing through credential-driven differentiation.
- Hospitals:Inpatient surgical suites accommodate complex reconstructive procedures requiring general anesthesia and overnight observation protocols.
- Medspas:Technician-staffed volume operations absorb outpatient aesthetic demand through distributed satellite locations with minimal build-out requirements.
Medspas hold installed capacity across distributed geographic footprints. Clinics are rotating up the share rankings as patients prioritize provider credentials.
Procedure Type:
Technical invasiveness correlates directly with reimbursement categorization complexity, as boundary shifts between elective cosmetic and medically necessary reconstructive indications determine addressable patient pools.
- Non-Surgical:Energy-based or pharmacological interventions requiring no incisions or sterile field protocols, encompassing neurotoxin injections and light-based hair removal.
- Surgical:Incision-based tissue modification with general or regional anesthesia, including rhinoplasty and abdominoplasty procedures.
- Minimally Invasive:Small-incision techniques with local anesthesia and abbreviated recovery periods, such as thread lifts or micro-liposuction.
- Reconstructive:Restoration of form and function following trauma, congenital anomaly, or oncologic resection, often qualifying for insurance reimbursement.
Non-surgical procedures hold installed capacity across outpatient channels. Minimally invasive techniques are rotating up the share rankings as device miniaturization enables broader provider administration.
Product Type:
Supply chain configuration separates high-margin biologic formulations requiring fermentation-grade raw materials from commodity surgical instrumentation with mature pricing structures.
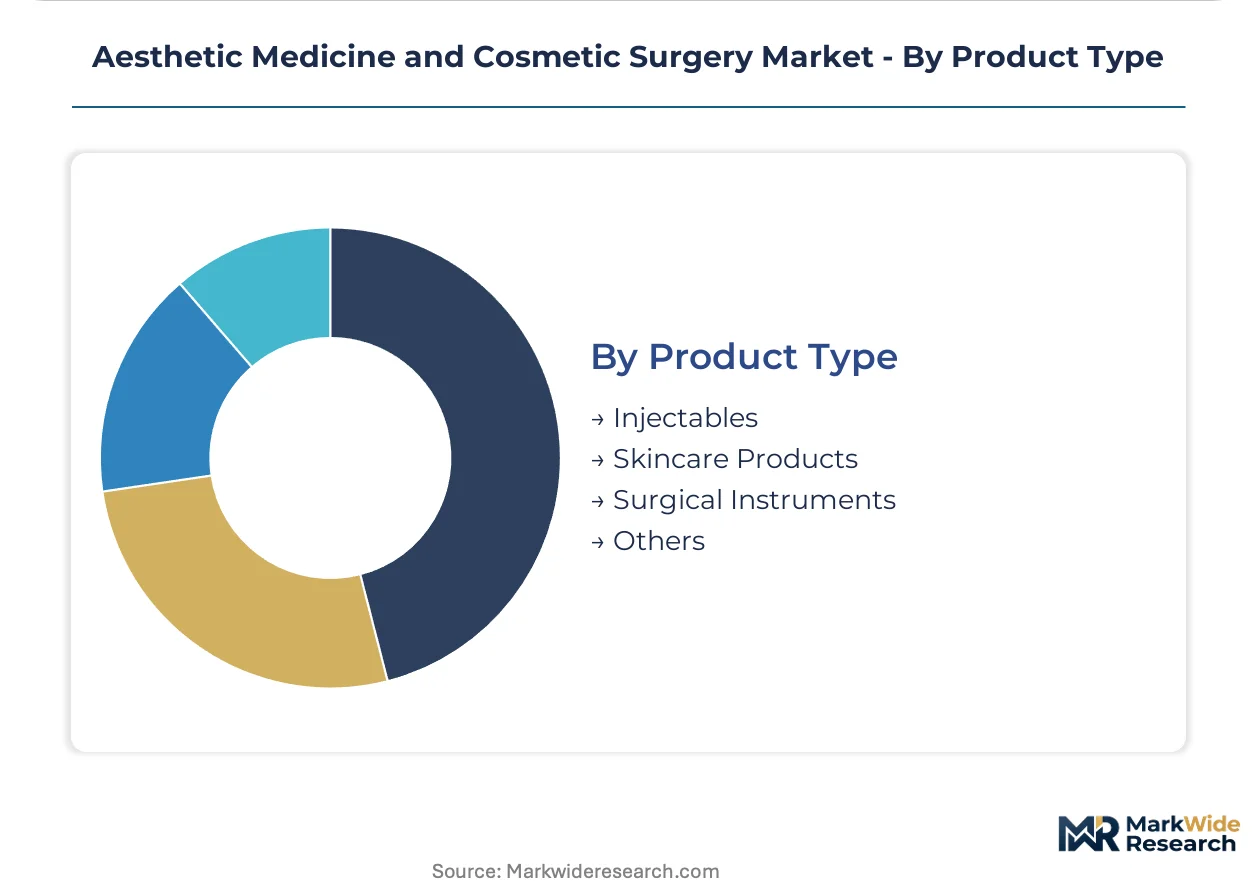
- Injectables:Botulinum toxin and hyaluronic acid formulations lead revenue pools through repeat purchase cycles and lower capital requirements for administration.
- Skincare Products:Topical retinoids, antioxidant serums, and sun protection formulations extend treatment outcomes between procedural interventions.
- Surgical Instruments:Robotic-assisted platforms and disposable kits concentrate value capture among integrated device manufacturers.
- Others:Implantable meshes, suture materials, and wound care products supporting operative and post-operative management.
Injectables hold installed capacity through vertically integrated manufacturing footprints. Skincare products are rotating up the share rankings as combination therapy protocols bundle topical maintenance with procedural services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the dominant geography, with MFDS protocols in South Korea and EU MDR frameworks in Germany collectively shaping commercial sequencing across energy-based devices and implantable formulations.
United States
Los Angeles and Miami corridor practices drive subscription-based neurotoxin adoption through mobile-enabled annual treatment platforms. FDA 510(k) review timelines compress launch windows for fractional laser systems entering dermatology channels. Manhattan and Beverly Hills clinic networks concentrate premium credential-driven capacity for combination therapy protocols.
South Korea
Seoul's Gangnam district clusters accredited clinics attracting cross-border patients from China through streamlined visa pathways and interpreter infrastructure. MFDS cooling-off period mandates for surgical procedures channel patient acquisition toward reputation-managed provider networks rather than direct-to-consumer advertising. Busan-Ulsan corridor expands manufacturing capacity for portable diode laser platforms.
Germany
EU MDR technical documentation requirements for implantable fillers extend CE marking renewal cycles, compressing commercial runway for legacy portfolios. Munich and Düsseldorf aesthetic medicine centers concentrate demand for hyaluronic acid facial contouring beyond wrinkle reduction. EMA post-market surveillance mandates fund longitudinal safety databases for long-duration filler formulations.
Brazil
São Paulo and Rio de Janeiro clinic networks absorb demand for multi-platform aesthetic workstations through ANVISA registration reciprocity with Mercosur neighbors. Brazilian patients gravitate toward minimally invasive thread lift protocols with abbreviated recovery periods. Porto Alegre surgical centers maintain reconstructive procedure capacity qualifying for national health system reimbursement.
Japan
Tokyo and Osaka metropolitan practices adopt picosecond laser platforms expanding indications from hair removal into pigmentation disorders and scar revision. PMDA regulatory frameworks require localized clinical evidence for energy-based device approvals, extending market entry timelines for multinational portfolios. Nagoya medical device distributors concentrate import logistics for fractional radiofrequency systems.
Aesthetic Medicine and Cosmetic Surgery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical-origin incumbents controlling biologic formulation supply chains while device manufacturers fragment across energy-delivery modalities. The competitive landscape separates into three archetypes: vertically integrated toxin producers with captive fermentation capacity, multi-platform laser specialists with geographic registration support operations, and mid-tier filler manufacturers exposed to raw material concentration risks. Consolidation pressure concentrates in the hyaluronic acid segment where EU MDR compliance costs favor incumbents with dedicated pharmacovigilance infrastructure. Geographic expansion through regulatory reciprocity agreements and combination therapy protocol bundling represent the dominant competitive vectors.
Within the integrated pharmaceutical tier, AbbVie/Allergan Aesthetics and Galderma occupy positions exemplifying vertically controlled botulinum toxin and hyaluronic acid portfolios. Alma Lasers represents the multi-platform device archetype with Asia-Pacific manufacturing footprints. Merz Aesthetics anchors the mid-cap specialist position across neurotoxin and filler segments. Johnson & Johnson and Bausch Health Companies exemplify diversified health conglomerates with aesthetic medicine divisions sitting within broader surgical and ophthalmic portfolios. Cynosure Lutronic and Anika Therapeutics represent regional specialists concentrated in energy-based systems and regenerative formulations respectively.
| Leading Market Players |
|---|
| Revance Therapeutics |
| Cynosure Lutronic |
| AbbVie/Allergan Aesthetics |
| Johnson & Johnson |
| Bausch Health Companies |
| Galderma |
| Alma Lasers |
| Anika Therapeutics |
| Merz Aesthetics |
| Others |
Supply Flow & Price Mechanics
Picosecond laser platforms displacing legacy fractional systems are redrawing procurement geography toward East Asian component suppliers while compressing capital-equipment pricing cycles for dermatology practices.
Pricing Analysis
Long-term offtake contracts for fermentation-grade sodium hyaluronate dominate hyaluronic acid filler pricing, with three-tier pricing structure across premium, standard, and economy levels differentiated by MFDS certification tier and clinic volume scale. Price differentiation stems from brand premium commanded by vertically integrated toxin producers versus raw material cost volatility squeezing mid-tier filler manufacturers. Pricing pressure intensifies as home-use LED masks capture maintenance-phase patients, eroding clinic visit frequency. Medspa chains exhibit highest price sensitivity due to technician-staffed volume models, while board-certified plastic surgeon practices maintain lowest sensitivity through credential-driven premium positioning.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan ports constrain multi-platform aesthetic workstation distribution, particularly for fractional laser systems sourced from South Korean manufacturing hubs. Fermentation-grade sodium hyaluronate concentrates in South Korea, China, and Japan, with botulinum toxin master cell banks anchored in Swiss and Irish bioproduction facilities. Supply chain risk centers on single-source vulnerability for specialized optical components in picosecond laser assemblies. Distribution runs through medspa chain procurement consortia and hospital GPO contracts, with regulatory registration support services bundled into manufacturer pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) clearance timelines and MFDS advertising protocols creates durable barriers against rapid competitive displacement.
For Market Incumbents: Consolidate pharmacovigilance infrastructure ahead of EU MDR post-market surveillance mandates, capturing mid-tier hyaluronic acid producers unable to fund longitudinal implant registries. Acquire portable diode laser distribution networks in São Paulo and Rio de Janeiro before ANVISA reciprocity agreements attract multinational device entrants. Deepen backward integration into fermentation-grade raw material supply to buffer batch consistency risks from concentrated bioproduction hubs. For New Entrants and Emerging Players: Lead with teleconsultation pre-screening platforms targeting reconstructive surgery segments where digital triage reduces no-show rates and optimizes operating room utilization. White-space entry concentrates in subscription-based neurotoxin maintenance programs across Los Angeles and Miami corridor practices, where patient lifetime value calculations remain underdeveloped among incumbent providers. Deploy mobile-enabled annual treatment platforms as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed medspa chain consolidators lacking credential-driven differentiation against board-certified plastic surgeon networks. Long-term viability hinges on regulatory compliance infrastructure rather than pure volume scale, favoring targets with dedicated FDA and MFDS registration operations. Watch for EU MDR certificate expiration waves as inflection indicators for distressed acquisition opportunities in legacy filler portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements compress commercial runway for implantable filler portfolios. |
| Hospital System Partnership | Reconstructive procedure networks in Porto Alegre qualify for national health system reimbursement. |
| Software Companion Development | Mobile-enabled subscription platforms for neurotoxin injections displace per-visit pricing in urban corridors. |
| Reimbursement Strategy | Boundary shifts between cosmetic and reconstructive indications determine addressable patient pools. |
| Regulatory Registration Support | Localized manufacturing in Busan-Ulsan corridor accelerates MFDS clearance for Asia-Pacific laser deployment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with board-certified plastic surgeons, dermatology clinic directors, medspa chain procurement managers, and biomedical engineers at laser device manufacturers. Secondary validation drew from FDA 510(k) clearance databases, MFDS advertising protocol filings, EU MDR technical documentation submissions, and hospital GPO contract repositories. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning service type, end-user channel configuration, procedure invasiveness tier, and product supply chain integration level. CAGRs derived from procedure frequency projections and average selling price trajectories incorporated regulatory approval timelines, cross-border medical tourism flow estimates, and substitution effects from home-use devices.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance pathway efficiency and stable hyaluronic acid raw material supply would require recalibration. Forecasts reflect assumptions regarding MFDS cooling-off period enforcement continuity and EU MDR post-market surveillance cost absorption capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Global Aesthetic Threads Market