
 Asia-Pacific Facial Aesthetics Market | 2026-2036
Asia-Pacific Facial Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Facial Aesthetics Market Insights
Energy-based device integration with injectable protocols is tilting treatment workflows toward combination approaches that improve patient retention and per-session value. AbbVie Inc. (Allergan Aesthetics) leverages its portfolio breadth across toxins and fillers to anchor premium positioning in Australian and Japanese clinics. Galderma sustains R&D intensity in biostimulatory fillers, while Lumenis competes on laser-IPL platform versatility across dermatology chains in South Korea and Thailand.
Facial aesthetics encompasses minimally invasive and non-invasive procedures that modify soft-tissue contours, skin quality, or facial volume using pharmacologic agents, thermal energy, or mechanical resurfacing, with hyaluronic acid fillers typically formulated at 20-24 mg/mL cross-linked concentration for mid-to-deep dermal placement. The primary commercial purpose centers on elective appearance enhancement for aging populations and younger demographics seeking preventive intervention. Injectables occupy the dominant revenue position given repeat purchase cycles and established clinician training infrastructure, while laser treatments capture margin pools from capital equipment leases and consumable attachments. Radiofrequency technology leads device-based skin tightening applications due to collagen remodeling efficacy at controlled dermal depths, with ultrasound modalities gaining traction for non-surgical lifting in premium clinic segments across Singapore and Taiwan.
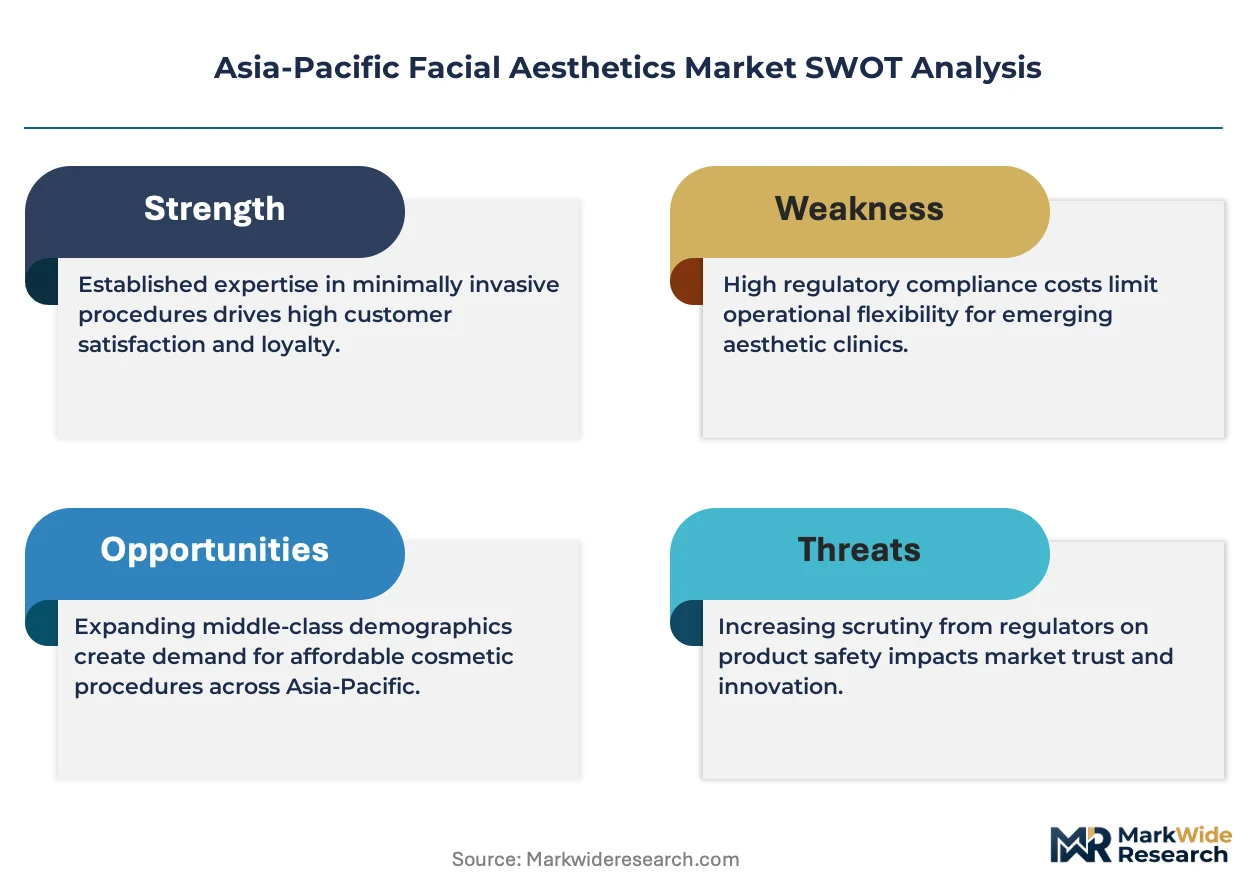
Japan's PMDA maintains stringent biocompatibility testing requirements for novel filler substances, while Australia's TGA mandates adverse event reporting that shapes product liability exposure for distributors. South Korea's MFDS operates accelerated review tracks for devices with predicate approvals in major reference markets, compressing time-to-commercialization for multinational manufacturers. Stakeholders must monitor how China's evolving GB standards for aesthetic medical devices and India's CDSCO notification pathways for Class C imports will reshape competitive access across the region's two largest addressable patient populations.
Market Dynamics
China's NMPA streamlined approval pathways for novel hyaluronic acid fillers are compressing product registration timelines and accelerating competitive entry into tier-one cities where disposable income growth concentrates demand.
Growth Catalysts
- Biostimulatory filler R&D intensity:Galderma and domestic Chinese manufacturers expand poly-L-lactic acid and calcium hydroxylapatite portfolios to capture collagen-stimulating demand beyond volume replacement.
- MFDS accelerated review tracks:South Korea's device regulator compresses time-to-commercialization for laser-IPL platforms with predicate approvals in reference markets, drawing multinational capital equipment manufacturers.
- Combination therapy adoption:Medical spas across Seoul, Tokyo, and Sydney pair radiofrequency skin tightening with neurotoxin protocols to lift per-session value and improve patient retention rates.
Market Restraints
- Cross-linked hyaluronic acid supply concentration:Fermentation-derived sodium hyaluronate raw material production clusters in Shandong and Zhejiang provinces, creating input cost volatility during environmental compliance crackdowns.
- PMDA biocompatibility testing burden:Japan's pharmaceutical regulator mandates extended cytotoxicity and sensitization studies for novel filler substances, extending pre-market timelines by 18-24 months versus regional peers.
- Non-surgical lifting substitution:High-intensity focused ultrasound devices capture premium clinic spend in Singapore and Taiwan, diverting maintenance budgets from repeat filler injections.
Strategic Opportunities
- Tier-two China expansion:Chengdu, Hangzhou, and Xi'an demonstrate rising per-capita aesthetic spending with undersupplied specialist clinic infrastructure relative to Beijing and Shanghai saturation.
- Energy-device lease models:Dermatology chains in Thailand and Vietnam adopt fractional laser and IPL platforms through equipment-as-a-service arrangements, lowering capital barriers for mid-market expansion.
- GB standards harmonization:China's evolving national standards for aesthetic medical devices create regulatory tailwinds for compliant multinationals ahead of stricter enforcement phases.
Industry Challenges
- Injector certification timelines:Australia's TGA adverse event reporting requirements and South Korea's specialist licensing pathways constrain qualified clinician supply relative to clinic expansion rates.
- Multi-modal protocol integration:Medical spas struggle to train staff on sequential toxin-filler-laser workflows, creating service inconsistency and liability exposure.
- Cross-border e-commerce enforcement:Unlicensed filler imports through informal channels undermine pricing integrity and complicate distributor compliance in Southeast Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Facial Aesthetics Market |
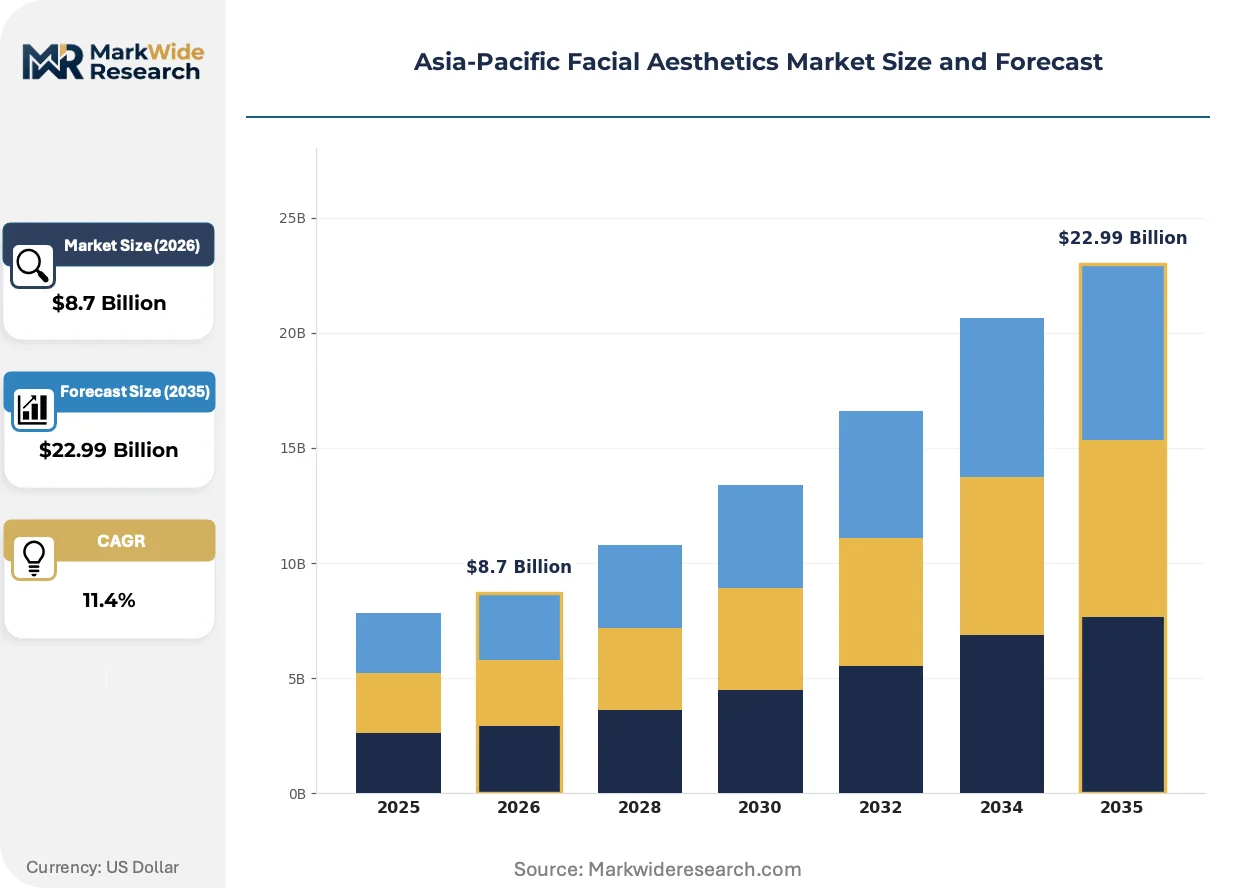
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Treatments, Dermal Fillers, Chemical Peels End User: Clinics, Medical Spas, Hospitals, Home Users Application: Wrinkle Reduction, Skin Tightening, Volume Restoration, Skin Rejuvenation Technology: Radiofrequency, Ultrasound, Microdermabrasion, LED Therapy |
| Companies Covered | AbbVie Inc. (Allergan Aesthetics), Galderma, Lumenis, Bausch Health Companies Inc., Merz Pharma, Johnson & Johnson, Cynosure, Cutera Inc., Medytox, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Facial Aesthetics Market Trends and Innovations
Injectable protocols are converging with energy-based modalities to create sequential treatment workflows that reshape clinic economics and patient retention strategies across developed Asia-Pacific markets.
Micro-cannula delivery techniques for hyaluronic acid fillers are migrating from specialist dermatology clinics to mainstream medical spa settings. Nurse injectors and aesthetic physicians in Melbourne and Bangkok adopt blunt-tip cannulas to reduce vascular occlusion risk and expand treatment areas per session. This technique diffusion is compressing the differentiation window for premium clinics that previously commanded margins on advanced injection expertise.
Japan's PMDA implemented streamlined QMS inspection protocols for manufacturers with ISO 13485 certification and prior FDA or CE approvals, reducing facility audit burdens for established multinationals. Domestic Japanese filler manufacturers face heightened documentation requirements for novel cross-linking technologies, pushing R&D investment toward incremental formulation improvements rather than breakthrough chemistries. Australian and New Zealand distributors benefit from mutual recognition arrangements that accelerate TGA listing for products with Japanese or South Korean approvals.
Social media-driven consultation models are displacing traditional referral networks in China's tier-one cities. Xiaohongshu and Douyin content creators in Shanghai and Shenzhen generate patient flow through before-after documentation and live treatment broadcasts, forcing clinics to allocate marketing spend toward influencer partnerships and platform algorithm optimization. This channel shift compresses customer acquisition costs for digitally native entrants while eroding legacy clinic dependence on physician reputation and hospital affiliations.
Asia-Pacific Facial Aesthetics Market Segmentation
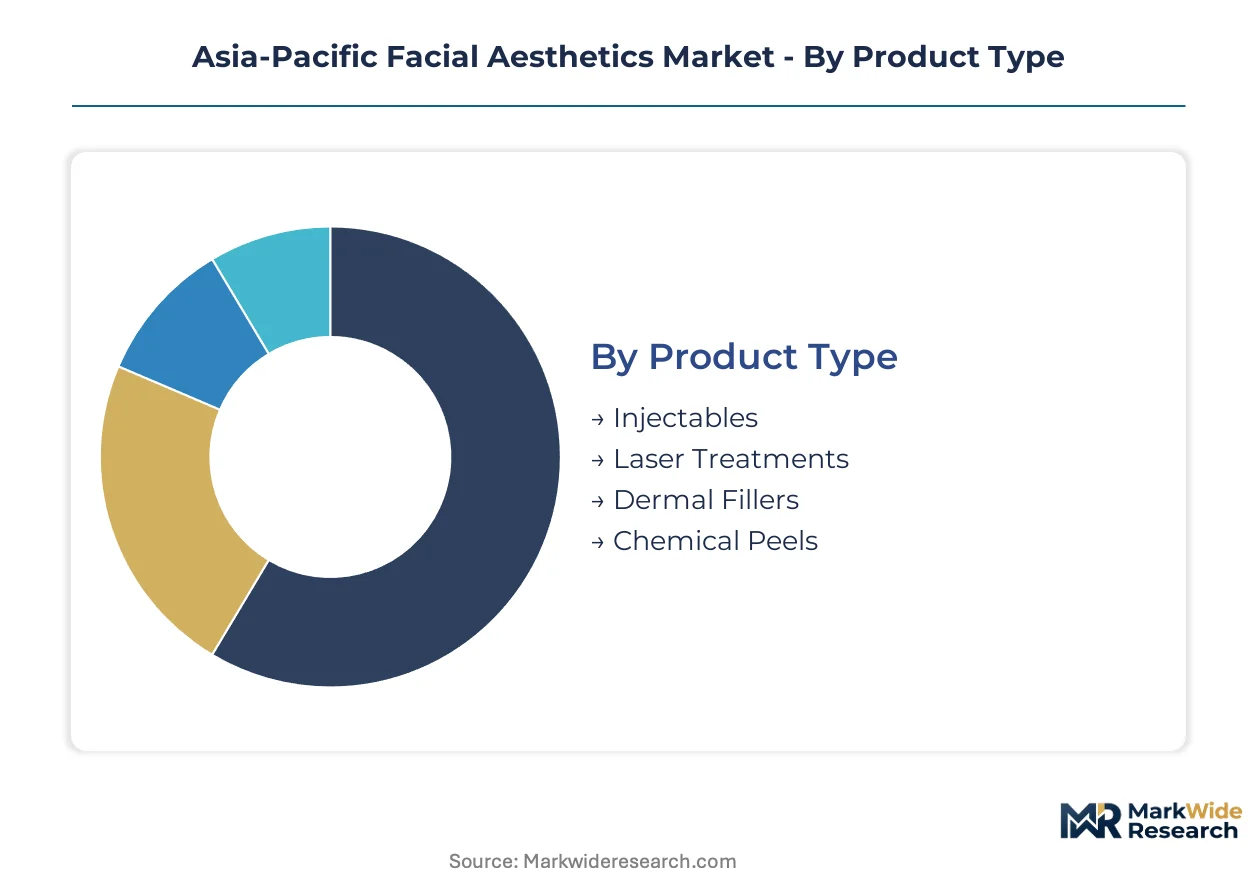
Segmentation in Asia-Pacific facial aesthetics reveals how treatment modalities, delivery settings, and underlying technologies compete for patient spend across diverse regulatory and cultural contexts. Understanding these divides illuminates where capital equipment investments concentrate versus where consumable-driven repeat purchases dominate clinic economics.
Product Type:
Use-case spectrum spans maintenance-oriented injectables through capital-intensive energy platforms, with each modality commanding distinct margin profiles and patient retention mechanics.
- Injectables:Neurotoxins and biostimulatory agents delivered via needle or micro-cannula dominate repeat purchase cycles in Seoul and Sydney medical spas. China's tier-one cities drive per-capita spending on preventive toxin protocols among demographics under 35.
- Dermal Fillers:Cross-linked hyaluronic acid formulations at 20-24 mg/mL concentration enable mid-to-deep dermal volume restoration. South Korean MFDS approvals for novel cross-linking chemistries accelerate product turnover in Busan and Incheon clinic chains.
- Laser Treatments:Ablative and non-ablative fractional platforms address photodamage and textural irregularities through controlled thermal injury.
- Chemical Peels:Superficial to medium-depth acid formulations target epidermal renewal in lower-tier China markets where device capital constraints persist.
Established volume favors injectables; emerging adoption favors laser-IPL platforms as lease models spread through Thailand and Vietnam.
End User:
Cost tier stratification separates premium clinic experiences from scaled medical spa delivery, with regulatory licensing requirements determining qualified injector supply in each channel.
- Medical Spas:Nurse-led injection protocols and combination therapy menus in Tokyo and Melbourne capture maintenance-oriented patients seeking convenience. Social media-driven appointment booking compresses customer acquisition costs for digitally native operators.
- Clinics:Dermatologist and plastic surgeon practices in Singapore and Hong Kong command premium positioning through advanced cannula techniques and complication management capabilities. Australia's TGA adverse event reporting requirements shape liability exposure and staffing ratios.
- Hospitals:Academic medical centers in Beijing and Shanghai integrate aesthetic services with reconstructive protocols.
- Home Users:LED masks and microcurrent devices target maintenance between professional treatments in Japan's aging suburban demographics.
Medical spas capture volume growth; hospital-affiliated clinics retain premium pricing power through specialist credentialing.
Application:
Patient age and treatment intent segment demand across preventive, corrective, and restorative objectives, with geography influencing which applications dominate local practice patterns.
- Wrinkle Reduction:Neurotoxin protocols for dynamic rhytides constitute the entry point for first-time aesthetic patients across China's tier-one cities. Xiaohongshu content creators normalize maintenance scheduling among professionals aged 25-40.
- Volume Restoration:Hyaluronic acid and biostimulatory filler protocols address mid-face hollowing and perioral atrophy in Japan's aging population. PMDA biocompatibility testing burdens extend pre-market timelines for novel substances versus regional peers.
- Skin Tightening:Radiofrequency and ultrasound modalities stimulate collagen remodeling without volume addition.
- Skin Rejuvenation:Combination approaches pairing chemical exfoliation with phototherapy target dyschromia and textural quality.
Wrinkle reduction commands procedure frequency; volume restoration commands per-session spend as filler portfolios expand.
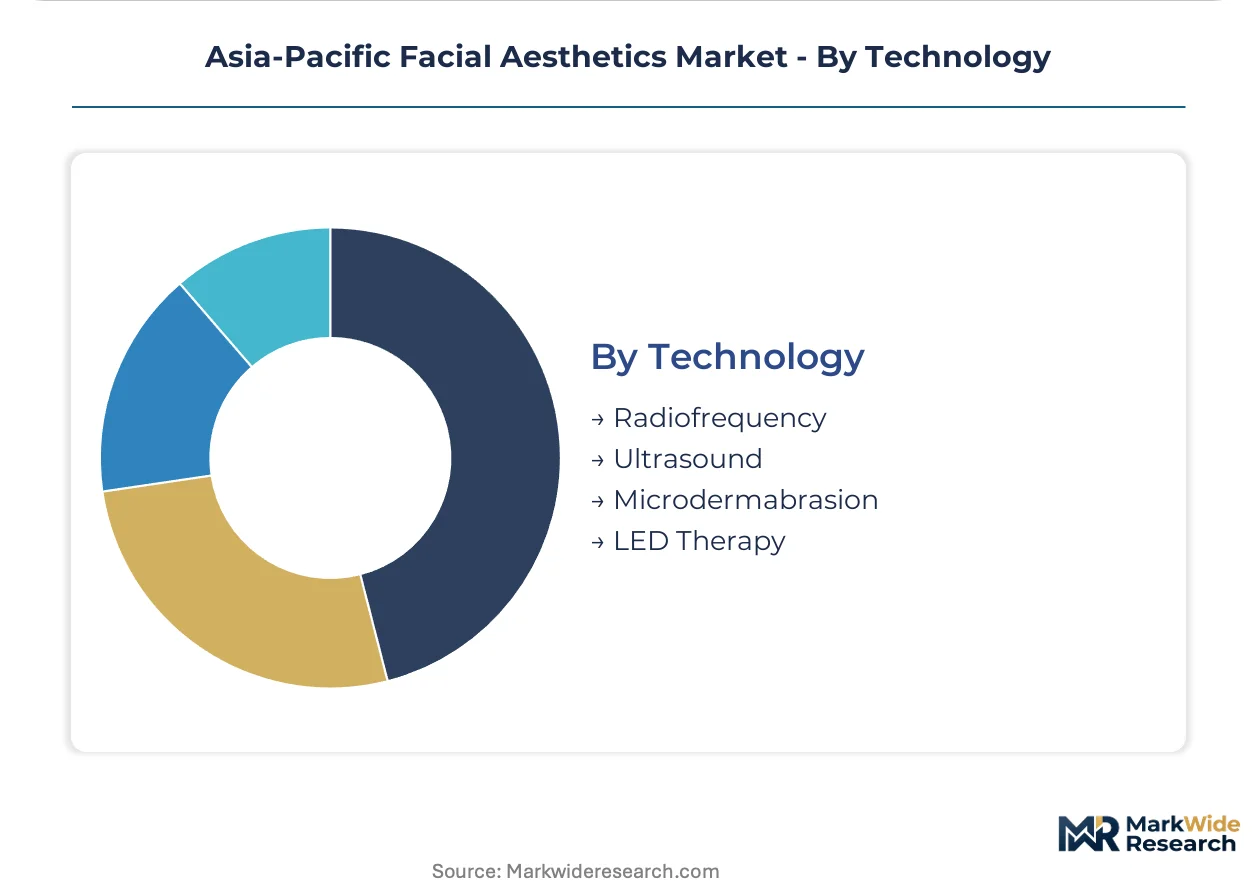
Technology:
Technology maturity curves separate established thermal modalities from emerging light-based protocols, with regulatory predicate pathways determining multinational market entry speed.
- Radiofrequency:Monopolar and bipolar configurations deliver controlled dermal heating for collagen contraction and neocollagenesis. South Korean device manufacturers leverage MFDS accelerated review tracks to compress time-to-commercialization for platforms with FDA or CE predicates.
- Ultrasound:High-intensity focused ultrasound enables non-surgical lifting at specified tissue depths, diverting maintenance budgets from repeat filler injections in premium Singapore and Taiwan clinic segments.
- Microdermabrasion:Mechanical exfoliation platforms occupy entry-level price points in Southeast Asian markets.
- LED Therapy:Photobiomodulation wavelengths target inflammation and collagen synthesis in post-procedure recovery protocols.
Radiofrequency retains installed base dominance; ultrasound modalities climb fastest in premium tier positioning against surgical alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean device manufacturers export radiofrequency and laser-IPL platforms to Australian dermatology chains and Thai medical spa networks, establishing Seoul-Bangkok-Sydney as the dominant trade-flow corridor for aesthetic capital equipment.
China
Tier-one cities Shanghai, Beijing, and Shenzhen concentrate per-capita aesthetic spending as disposable income growth meets social media-driven consultation models. NMPA streamlined approval pathways for novel hyaluronic acid fillers compress registration timelines versus historical benchmarks. Yangtze River Delta manufacturing clusters in Shandong and Zhejiang provinces supply fermentation-derived sodium hyaluronate raw materials, exposing input costs to environmental compliance volatility.
Japan
Aging demographics sustain demand for volume restoration procedures targeting mid-face hollowing and perioral atrophy. PMDA mandates extended cytotoxicity and sensitization studies for novel filler substances, extending pre-market timelines by 18-24 months relative to regional peers. Kanto region clinics in Tokyo and Yokohama anchor premium positioning through specialist credentialing and advanced cannula technique adoption.
South Korea
Seoul medical spas normalize combination therapies pairing neurotoxins with radiofrequency skin tightening to lift per-session value. MFDS accelerated review tracks compress time-to-commercialization for laser-IPL platforms with FDA or CE predicate approvals. Busan and Incheon clinic chains drive rapid product turnover for novel cross-linking chemistries approved under streamlined device regulations.
Australia
TGA adverse event reporting requirements shape distributor liability exposure and staffing ratios across Melbourne and Sydney clinic networks. Mutual recognition arrangements with Japanese and South Korean regulators accelerate product listing timelines for established multinationals. Nurse-led injection protocols in mainstream medical spa settings compress differentiation windows for premium specialist practices.
Singapore
Premium clinic segments divert maintenance budgets toward high-intensity focused ultrasound devices for non-surgical lifting applications. Regulatory alignment with ASEAN harmonization frameworks facilitates import pathways for Class C aesthetic devices. Specialist dermatology practices command pricing power through complication management capabilities and advanced energy-device protocol integration.
Asia-Pacific Facial Aesthetics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented clinic and medical spa distribution tiers. The vendor base clusters around three strategic archetypes: multinational pharmaceutical-device conglomerates with portfolio breadth across toxins and fillers; pure-play energy-device manufacturers competing on platform versatility; and domestic Chinese and South Korean specialists leveraging regulatory familiarity and cost positioning. Dominant competitive moves include portfolio diversification into combination therapy workflows and geographic expansion through distributor partnerships in tier-two China cities and Southeast Asian lease-model markets.
Among multinational conglomerates, AbbVie Inc. (Allergan Aesthetics) and Galderma occupy positions exemplifying portfolio-breadth archetypes across Australian and Japanese premium clinic segments. Lumenis represents the energy-device specialist tier competing on laser-IPL platform versatility. These three entities anchor competitive reference points without exhaustive market share claims, serving as structural anchors for understanding how regulatory predicate pathways and combination therapy adoption reshape positioning across Seoul, Tokyo, and Sydney medical spa networks.
| Leading Market Players |
|---|
| AbbVie Inc. (Allergan Aesthetics) |
| Galderma |
| Lumenis |
| Bausch Health Companies Inc. |
| Merz Pharma |
| Johnson & Johnson |
| Cynosure |
| Cutera Inc. |
| Medytox |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta manufacturing clusters in Shandong and Zhejiang provinces anchor global sodium hyaluronate supply, with environmental compliance crackdowns transmitting directly into downstream filler pricing volatility and procurement uncertainty for Seoul and Sydney clinic chains.
Pricing Analysis
Current-generation cross-linked hyaluronic acid fillers command substantial premiums over prior-generation formulations, while next-generation biostimulatory agents target ultra-premium positioning. Three-tier pricing structure across premium cannula-delivered protocols, standard needle-based fillers, and economy-grade unbranded alternatives dominates clinic procurement. Pricing pressure stems from nurse-led injection protocols in Melbourne medical spas compressing differentiation windows for specialist practices. Tier-two China cities demonstrate highest buyer price sensitivity as clinic density lags disposable income growth.
Supply Chain Analysis
Contract manufacturing for fermentation-derived hyaluronate concentrates among Shandong-based biotech processors and Zhejiang specialty chemical houses. Geographic supply concentration centers on China, South Korea, and Japan for raw fermentation capacity, with Germany and Switzerland contributing precision cross-linking reagents. Raw material dependencies include pharmaceutical-grade glucose feedstocks, cross-linking agents, and sterilization packaging. Single-source vulnerability persists in high-purity sodium hyaluronate extraction. Distribution runs through authorized medical device distributors with NMPA, MFDS, or TGA licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific facial aesthetics operates as a regulatory-moat market where NMPA, PMDA, and MFDS approval timelines create entrenched switching costs that protect incumbent positions against fast-follower competition.
For Market Incumbents: Insulate market position by deepening backward integration into Shandong fermentation capacity to secure hyaluronate supply amid environmental compliance volatility. Expand MFDS predicate approval portfolios to compress competitor time-to-commercialization. Prioritize certification investment in China's evolving GB standards ahead of enforcement phases. For New Entrants and Emerging Players: Build out white-space presence in Chengdu, Hangzhou, and Xi'an medical spa networks where specialist clinic infrastructure remains undersupplied relative to Beijing saturation. Target equipment-as-a-service lease models in Thai and Vietnamese dermatology chains to bypass capital barriers. Deploy influencer partnership go-to-market strategies on Xiaohongshu and Douyin to compress customer acquisition costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biostimulatory filler portfolios with collagen-stimulating repeat protocols versus one-time laser device placements. Long-term viability favors manufacturers with regulatory predicates across NMPA, MFDS, and TGA jurisdictions. Monitor MFDS accelerated review track utilization rates as inflection signal for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Harmonization | NMPA alignment with evolving national standards accelerates compliant multinational market access ahead of enforcement. |
| Combination Therapy Certification | Sequential toxin-filler-laser protocol training addresses medical spa liability exposure and service inconsistency. |
| Tier-Two China Expansion | Chengdu and Xi'an clinic networks capture rising per-capita aesthetic spending with lower competitive density. |
| Equipment-as-a-Service Models | Lease arrangements for fractional laser platforms lower capital barriers in Thai and Vietnamese mid-market expansion. |
| Biostimulatory R&D Intensity | Poly-L-lactic acid and calcium hydroxylapatite portfolios extend patient retention beyond volume replacement cycles. |
Research Methodology
A spread of perspectives from aesthetic clinic operators, biomedical engineers at device manufacturers, NMPA regulatory consultants, and dermatology chain procurement managers converged on the working assumptions shaping demand forecasts. Primary interviews combined with secondary validation against MFDS approval databases, NMPA registration filings, TGA adverse event reports, and hospital procurement records. Bottom-up clinic capacity modeling and top-down disposable income elasticity estimates were triangulated to anchor projections.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product type, end-user setting, application intent, and technology modality. CAGRs derived from procedure volume growth rates, per-session value trajectories, and equipment replacement cycles. Forecast inputs included social media influencer penetration metrics in China's tier-one cities and MFDS accelerated review track approval velocities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by domestic Chinese manufacturers or abrupt NMPA enforcement shifts would shift outcomes. Regulatory pathway delays, environmental compliance disruptions in Shandong fermentation clusters, and cross-border e-commerce enforcement actions in Southeast Asia represent primary revision risks. Quarterly review of NMPA registration timelines and MFDS predicate approval volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Global Buttock Augmentation Market