
 North America Medical Aesthetic Devices Market | 2026-2036
North America Medical Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Aesthetic Devices Market Analytics
Aftermarket service revenue is narrowing as manufacturers bundle multi-year maintenance contracts into initial capital sales. AbbVie Inc. (Allergan PLC) leverages its injectables portfolio to anchor recurring consumable revenue alongside capital equipment placements. Candela Medical competes through vertically integrated laser source manufacturing that sustains margin control across radiofrequency and pulsed-dye platforms. Sisram Medical Ltd. (Alma Lasers) dominates the mid-market segment with modular device architectures that reduce clinic upgrade costs.
Medical aesthetic devices encompass electromechanical and energy-based systems engineered to deliver controlled thermal, mechanical, or chemical effects at specified tissue depths—typically 0.1 mm to 10 mm—with pulse durations ranging from milliseconds to continuous wave for indications including adipocyte disruption, collagen remodeling, and melanocyte targeting. Laser Devices and radiofrequency platforms command the largest installed base due to versatility across skin rejuvenation and hair removal, while cryolipolysis and ultrasound-based body contouring represent the fastest-expanding technology category as clinics seek non-surgical alternatives to liposuction. Dermatology Clinics and Cosmetic Surgery Centers absorb the majority of capital expenditure, though Home Care channels are emerging for lower-intensity LED and microcurrent systems.
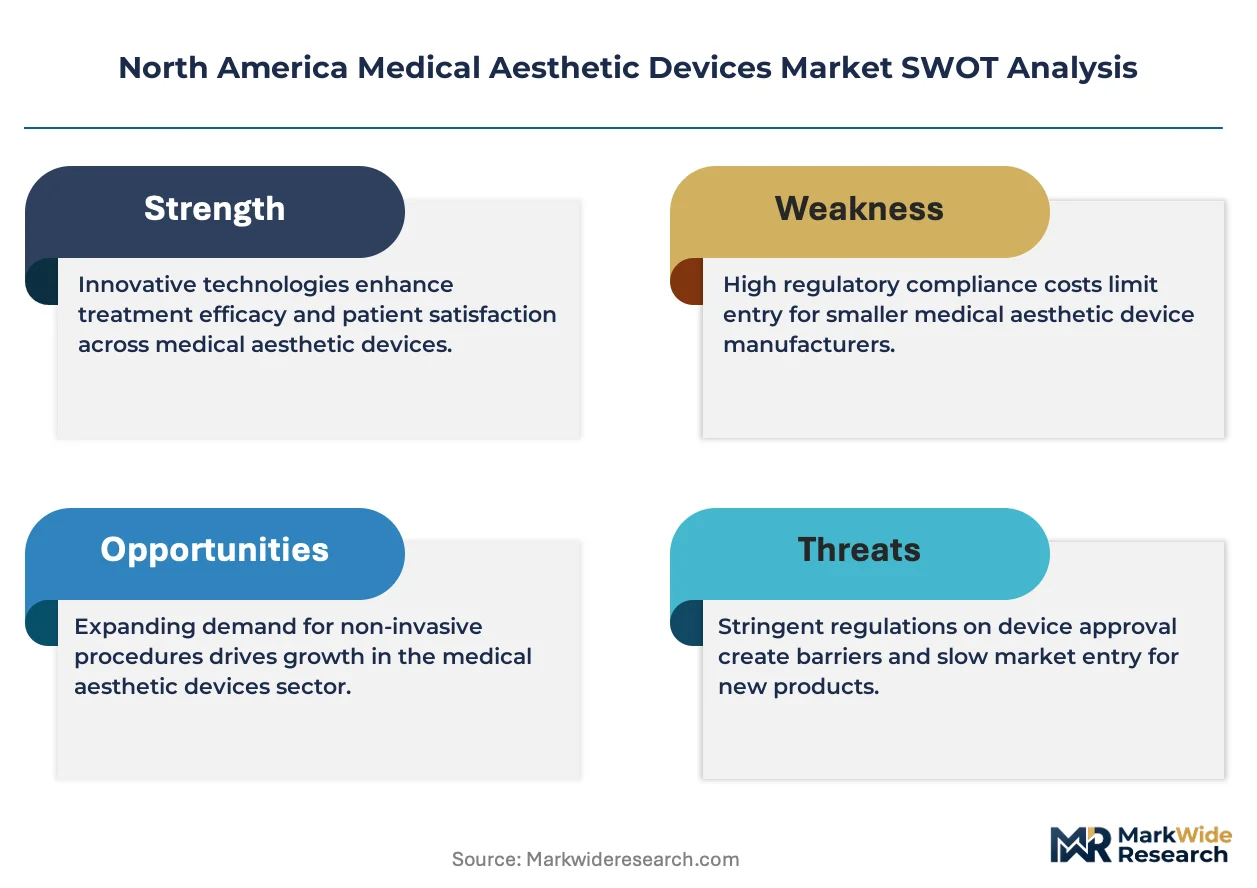
FDA 510(k) clearance requirements and Health Canada Medical Device Licensing shape product development timelines and predicate device strategies for manufacturers seeking North American market access. State-level medical board regulations in California, Texas, and Florida govern operator certification and supervision protocols, directly influencing device training revenue and clinic compliance costs. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device and AI-enabled treatment planning as these frameworks will determine competitive moats for next-generation platforms.
Market Dynamics
Device manufacturers face compressed upgrade cycles as FDA 510(k) clearance pathways accelerate time-to-market for laser and radiofrequency platforms, forcing incumbents to defend installed bases through consumable lock-in strategies rather than capital equipment refresh alone.
Growth Catalysts
- Medspa Density Concentration:California, Texas, and Florida host the highest clinic-per-capita ratios in the United States, creating localized demand clusters that absorb premium-tier energy-based systems faster than national averages.
- FDA 510(k) Streamlining:Predicate device pathways for laser and radiofrequency platforms reduce regulatory review timelines, enabling manufacturers to commercialize next-generation thermal delivery systems within compressed development windows.
- Non-Surgical Body Contouring:Cryolipolysis and high-intensity focused ultrasound technologies capture patient flow previously directed toward liposuction, expanding addressable procedure volume across dermatology and plastic surgery practices.
Market Restraints
- Capital Equipment Intensity:Radiofrequency and laser platforms require six-figure upfront investment per unit, constraining adoption among independent dermatology practices and small multi-specialty clinics with limited credit access.
- Operator Certification Fragmentation:State medical board regulations in California, Texas, and Florida impose divergent supervision protocols, forcing manufacturers to maintain multiple training curricula and compliance documentation systems.
- Consumable Margin Compression:Bundled multi-year maintenance contracts shift service revenue recognition forward, reducing aftermarket cash flow predictability for device vendors.
Strategic Opportunities
- Home Care Channel Expansion:Lower-intensity LED and microcurrent systems open consumer-direct revenue streams outside clinic-dependent distribution, with Health Canada Medical Device Licensing creating a parallel regulatory pathway for at-home skin rejuvenation devices.
- AI-Enabled Treatment Planning:Software-as-a-medical-device frameworks under evolving FDA guidance position algorithmic dosing and thermal mapping as differentiable features for next-generation platforms.
- Modular Device Architectures:Upgradeable handpiece and energy-source configurations reduce clinic capital obsolescence risk, lowering barrier-to-entry for mid-market aesthetic practices in secondary metropolitan areas.
Industry Challenges
- Technical Staffing Scarcity:Biomedical engineers with laser optics and thermal modeling expertise command premium compensation, constraining manufacturer R&D expansion and field service coverage in underserved markets.
- Legacy System Integration:Clinic information management platforms lack standardized APIs for device-generated treatment data, forcing manual workflow bridges that delay AI-enabled analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Aesthetic Devices Market |
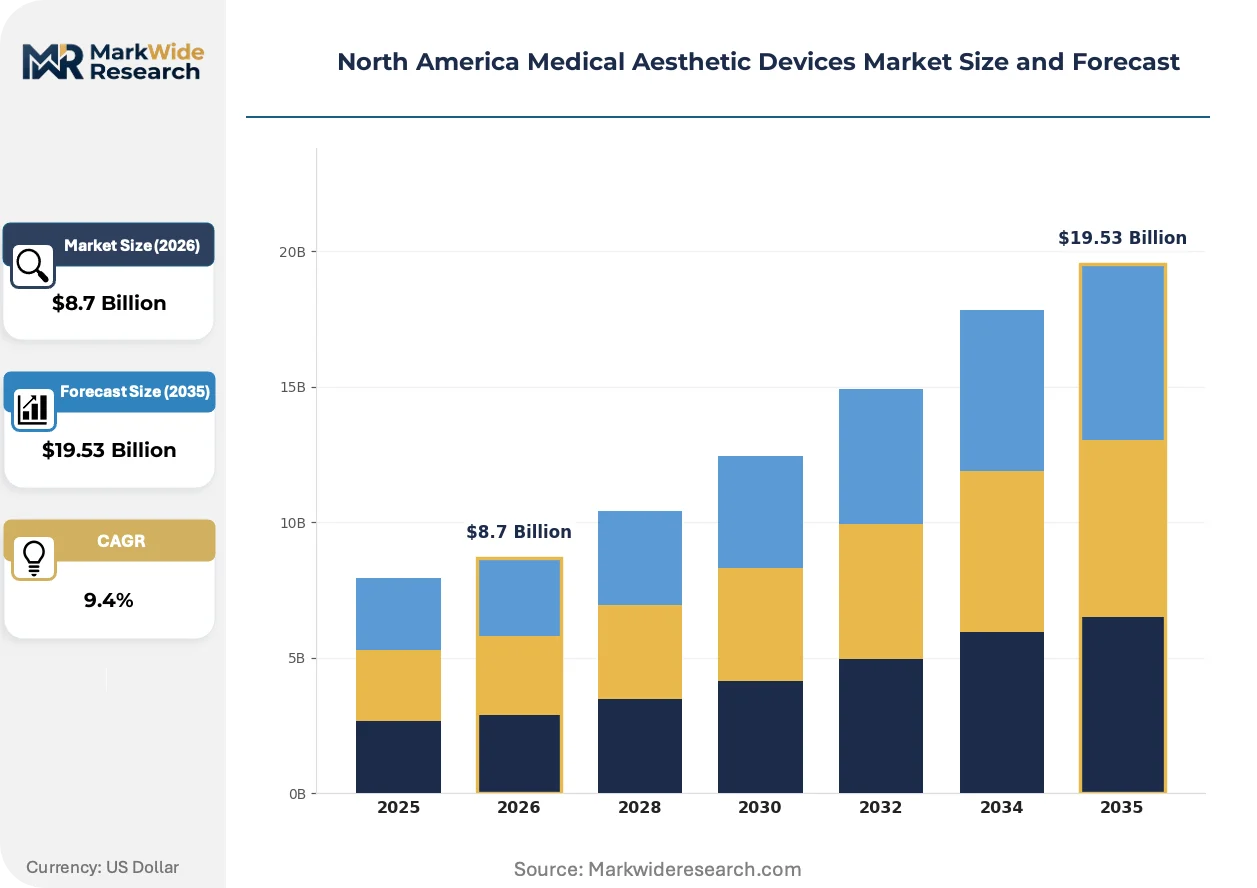
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Microdermabrasion Equipment, Facial Aesthetics, Body Contouring Technology: Radiofrequency, Ultrasound, Cryolipolysis, Chemical Peels End User: Dermatology Clinics, Cosmetic Surgery Centers, Beauty Salons, Home Care Application: Skin Rejuvenation, Anti-Aging, Hair Removal, Acne Treatment |
| Companies Covered | AbbVie Inc. (Allergan PLC), Bausch Health Companies Inc., Sisram Medical Ltd. (Alma Lasers), Cutera Inc., Cynosure LLC, Candela Medical, Merz Pharma, Lumenis Be Ltd., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Aesthetic Devices Market Evolving Landscape
Energy delivery modalities are converging with computational control systems, reshaping competitive differentiation from raw power specifications toward software-defined treatment precision and predictive outcome modeling.
Multi-wavelength laser platforms are hybridizing discrete chromophore targeting into single-session protocols. Dermatology clinics in Florida and Texas adopt these systems to compress patient visit duration while expanding indication breadth. The technology is hybridizing capital efficiency expectations, pressuring single-modality vendors to demonstrate superior efficacy per dollar of equipment deployed.
FDA guidance on software-as-a-medical-device is recalibrating product development roadmaps for algorithmic treatment planning tools. Manufacturers must submit premarket notifications for AI-enabled dosing systems previously classified as accessory software. Laser and radiofrequency vendors with embedded thermal feedback loops face the steepest compliance recalibration, diverting engineering resources toward 510(k) documentation for 2024-2025 submissions.
Aftermarket service unbundling is accelerating as clinic procurement teams negotiate à-la-carte maintenance against bundled multi-year contracts. Independent dermatology practices in California lead this behavior, citing cash flow optimization needs. The shift pressures manufacturers to demonstrate discrete service value rather than relying on contractual lock-in for recurring revenue stability.
North America Medical Aesthetic Devices Market Segmentation
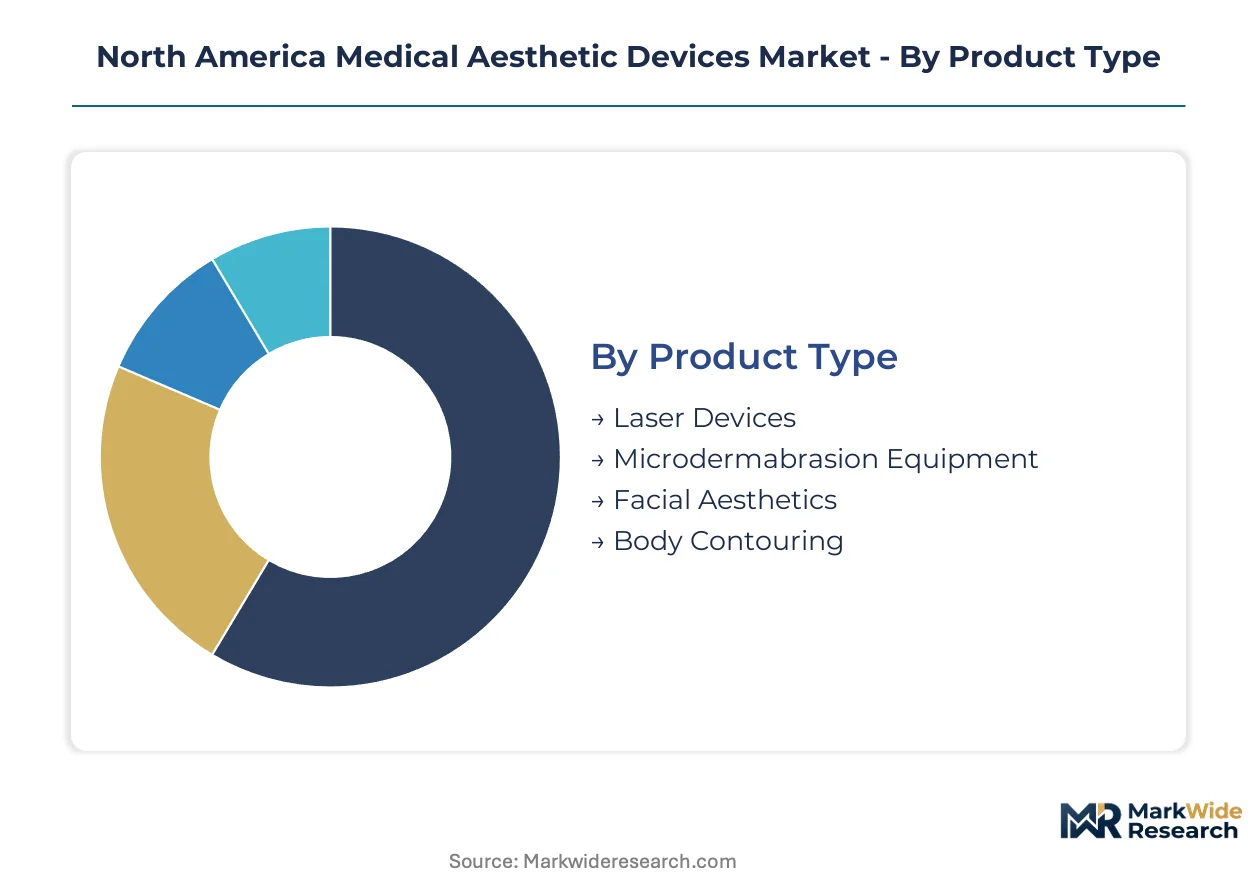
Medical aesthetic devices fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology choices dominate capital allocation decisions, while end-user channel and application specificity shape recurring revenue potential.
Product Type:
Cost tier stratification separates premium capital equipment from consumable-dependent systems and lower-investment modalities.
- Laser Devices:Multi-wavelength platforms deliver controlled thermal energy at tissue depths from 0.1 mm to 10 mm for indications spanning hair removal, vascular lesions, and skin resurfacing. Dermatology clinics in California, Texas, and Florida absorb the majority of high-power laser placements as medspa density concentrates demand for versatile single-session protocols.
- Body Contouring:Cryolipolysis and high-intensity focused ultrasound systems target adipocyte disruption without surgical intervention. Cosmetic surgery centers in Florida and Texas rotate these platforms into service fastest as patient flow shifts away from liposuction toward non-surgical alternatives.
- Facial Aesthetics:Injectable delivery systems and energy-based platforms address wrinkle reduction and volume restoration.
- Microdermabrasion Equipment:Mechanical exfoliation systems operate at lower capital intensity with compressed training requirements.
Laser Devices hold installed capacity. Body Contouring is rotating up the share rankings.
Technology:
Application specificity determines which energy modality clinics prioritize based on patient demographics and indication breadth.
- Radiofrequency:Thermal delivery systems generate controlled dermal heating for collagen remodeling and skin tightening across multiple tissue depths. Dermatology clinics leverage radiofrequency versatility across facial and body applications, with FDA 510(k) predicate pathways accelerating platform upgrades.
- Cryolipolysis:Controlled cooling protocols induce adipocyte apoptosis without damaging surrounding tissue. Texas and Florida cosmetic surgery centers deploy these systems to capture patient demand for non-invasive fat reduction, compressing procedure volume previously directed toward surgical alternatives.
- Ultrasound:High-intensity focused energy enables precise thermal targeting at specified depths.
- Chemical Peels:Topical acid formulations deliver controlled epidermal exfoliation at minimal capital investment.
Radiofrequency maintains the broadest installed footprint. Cryolipolysis is climbing the fastest among energy-based modalities.
End User:
Customer type segmentation separates regulated medical channels from emerging consumer-direct pathways with divergent compliance burdens.
- Dermatology Clinics:Physician-supervised practices absorb premium-tier laser and radiofrequency platforms, generating recurring consumable revenue through high procedure volume. California, Texas, and Florida host the densest clinic concentrations, creating localized demand clusters for multi-modality capital equipment.
- Home Care:Lower-intensity LED and microcurrent systems bypass clinic-dependent distribution entirely. Health Canada Medical Device Licensing creates a parallel regulatory pathway for at-home skin rejuvenation devices, opening consumer-direct revenue streams outside traditional medical channels.
- Cosmetic Surgery Centers:Surgical practices integrate energy-based systems for pre- and post-operative optimization.
- Beauty Salons:Non-medical operators face state-level supervision restrictions that limit device intensity and indication scope.
Dermatology Clinics command the capital expenditure concentration. Home Care is gaining share fastest as regulatory pathways mature.
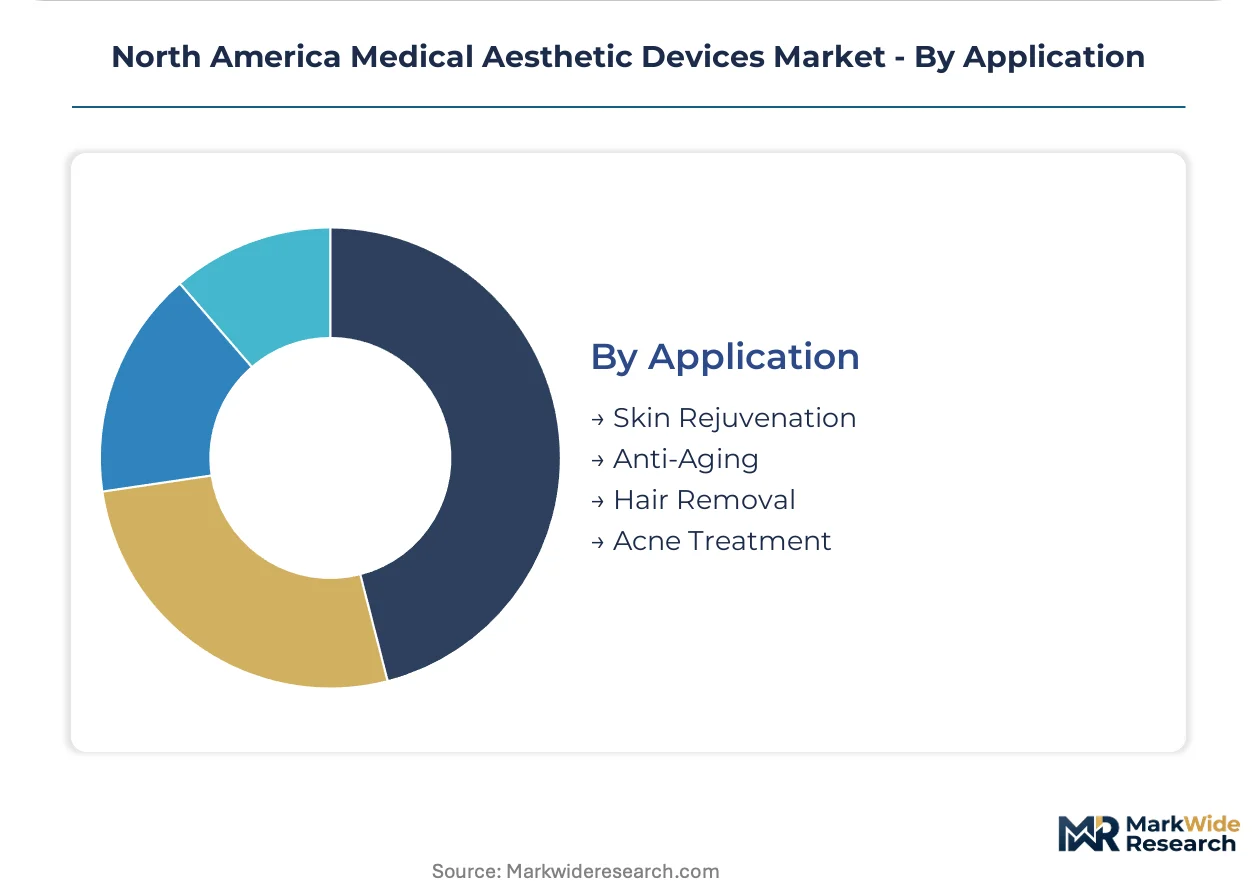
Application:
Volume distribution across indications reflects demographic aging patterns and cultural preferences for specific aesthetic outcomes.
- Skin Rejuvenation:Collagen remodeling and texture improvement procedures span laser, radiofrequency, and chemical peel modalities. Dermatology clinics in California prioritize these platforms as patient demand concentrates on preventative and restorative facial treatments.
- Hair Removal:Laser-based permanent hair reduction targets melanin in follicular structures across diverse skin types. Texas and Florida clinics deploy advanced cooling technologies to expand treatable patient populations beyond traditional Fitzpatrick skin type limitations.
- Anti-Aging:Wrinkle reduction and volume restoration spans injectables and energy-based tightening.
- Acne Treatment:Sebaceous gland targeting and bacterial reduction protocols address persistent inflammatory conditions.
Skin Rejuvenation anchors procedure volume. Hair Removal is rotating up the share rankings as technology expands addressable demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply: the United States concentrates premium capital equipment deployment in medspa-dense metropolitan corridors, while Canada channels demand through physician-supervised dermatology networks with tighter Health Canada oversight, and Mexico absorbs refurbished systems through cross-border procurement channels serving price-sensitive cosmetic surgery centers.
United States
California, Texas, and Florida absorb the majority of high-power laser and radiofrequency placements as medspa density and disposable income create localized demand clusters. FDA 510(k) clearance pathways compress commercialization timelines for thermal delivery platforms. Los Angeles and Miami anchor the highest clinic-per-capita concentrations, driving faster upgrade cycles for multi-wavelength systems.
Canada
Ontario and Quebec concentrate device procurement through dermatology clinics with stricter Health Canada Medical Device Licensing compliance burdens. The country's national pharmaceutical regulator requires standalone licensing for software-as-a-medical-device features, slowing AI-enabled platform deployment. Toronto hosts the densest cluster of aesthetic practices, generating disproportionate consumable revenue for injectable-compatible energy systems.
Mexico
Cosmetic surgery centers in Mexico City and Guadalajara absorb refurbished laser platforms through cross-border procurement from Texas distributors. The country's national pharmaceutical regulator maintains lighter oversight on capital equipment than Health Canada or FDA, enabling faster adoption of previous-generation systems. Baja California corridor clinics serve medical tourism flows with mid-tier radiofrequency devices.
North America Medical Aesthetic Devices Market Competitive Landscape
Capability concentration sits with vertically integrated laser source manufacturers; scale advantage sits with diversified pharmaceutical conglomerates with injectables portfolios. The vendor base organizes around three strategic archetypes: premium-tier integrated manufacturers controlling upstream component supply, mid-market modular platform specialists reducing clinic upgrade costs, and diversified health conglomerates anchoring recurring consumable revenue. Dominant competitive moves include consumable lock-in strategies bundling multi-year service contracts into initial capital sales, and predicate device regulatory strategies accelerating 510(k) clearance timelines.
Within the premium-tier integrated manufacturer archetype, Candela Medical and Lumenis Be Ltd. exemplify vertical control over laser source production. AbbVie Inc. (Allergan PLC) occupies a distinct position as a diversified health conglomerate leveraging injectables portfolios to anchor recurring revenue alongside capital placements. Sisram Medical Ltd. (Alma Lasers) represents the mid-market modular specialist tier, reducing clinic capital obsolescence risk through upgradeable handpiece architectures.
| Leading Market Players |
|---|
| AbbVie Inc. (Allergan PLC) |
| Bausch Health Companies Inc. |
| Sisram Medical Ltd. (Alma Lasers) |
| Cutera Inc. |
| Cynosure LLC |
| Candela Medical |
| Merz Pharma |
| Lumenis Be Ltd. |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Israeli and German laser source manufacturers determines both pricing tier spreads and supply chain shape across the North American medical aesthetic devices market. FDA 510(k) clearance bottlenecks amplify this concentration by compressing predicate device alternatives, forcing buyers into premium-tier contracts or extended lead times for qualified substitutes.
Pricing Analysis
Long-term service bundling dominates contract structures, with manufacturers embedding multi-year maintenance into initial capital sales to lock recurring revenue. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated laser platforms from modular mid-market systems and refurbished previous-generation units. Cost compression in the economy tier intensifies as Texas-based distributors channel refurbished inventory from Mexico procurement networks. Independent dermatology practices in California exhibit highest price sensitivity, while cosmetic surgery centers in Florida absorb premium pricing for multi-wavelength platforms.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for optical components and semiconductor laser diodes. Manufacturing concentrates in Israel, Germany, and the United States for precision laser sources, with China supplying lower-tier LED and microcurrent assemblies. Component dependencies rest on gallium arsenide laser diodes, sapphire cooling crystals, and FDA-compliant biocompatible handpiece materials. Distribution runs through manufacturer-direct sales teams for premium platforms and specialized medical device distributors for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as dermatology clinic chains in California and Texas consolidate procurement through group purchasing organizations, fragmenting the historically fragmented independent practice landscape. This consolidation shifts negotiating leverage toward volume-based contract terms and unbundled service pricing.
For Market Incumbents: Pre-empt modular platform specialists by accelerating upgradeable handpiece architectures that reduce clinic capital obsolescence risk. Lock in consumable revenue through proprietary connector standards that block third-party handpiece compatibility. FDA software-as-a-medical-device guidance expansion threatens algorithmic dosing moats; divert R&D toward thermal feedback loop patents. For New Entrants and Emerging Players: Home care channels in Canada represent the most penetrable entry point given Health Canada's parallel licensing pathway for lower-intensity LED and microcurrent systems. Secondary metropolitan areas in Texas and Florida absorb mid-tier radiofrequency platforms as medspa density saturates primary markets. Direct-to-consumer digital marketing bypasses clinic-dependent distribution entirely. For Investors and Strategic Acquirers: FDA guidance finalization on AI-enabled treatment planning reshapes the acquisition landscape toward software-capable device platforms. Five-to-ten year viability favors manufacturers with embedded algorithmic dosing and predictive outcome modeling. Target vertically integrated laser source producers with captive component supply. Monitor Health Canada standalone licensing requirements for software-as-a-medical-device as the inflection signal for North American regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate device strategies compress commercialization timelines for thermal delivery platforms. |
| Software-as-a-Medical-Device Development | Algorithmic dosing systems differentiate next-generation laser and radiofrequency platforms under evolving FDA guidance. |
| Hospital System Partnership | Dermatology clinic chains in California and Texas consolidate procurement through integrated delivery networks. |
| Modular Handpiece Architecture | Upgradeable configurations reduce capital obsolescence risk for mid-market aesthetic practices. |
| Reimbursement Strategy | Category III CPT code applications expand addressable patient populations beyond cosmetic self-pay. |
Research Methodology
Operator-level perspectives from dermatology clinic owners, biomedical engineers, GPO contracts managers, and FDA regulatory consultants anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, Health Canada Medical Device Licensing records, hospital procurement databases, and state medical board regulatory documentation. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates across product type, technology, end user, and application dimensions.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around FDA clearance timelines and Health Canada software licensing pathways. Segmentation dimensions modeled include product type tier, energy modality, clinic channel, and procedure indication. CAGRs derived from procedure volume growth, device replacement cycles, and consumable attach rates. Forecast inputs incorporated medspa density clustering in California, Texas, and Florida, plus cross-border procurement flows from Mexico.
Practitioners should monitor FDA software-as-a-medical-device guidance finalization, Health Canada standalone licensing expansion, and tariff policy shifts on optical components for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Asia-Pacific Dermal Fillers Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
North America Aesthetic Dermatology Market