
 Global Sex Reassignment Surgery Market | 2026-2036
Global Sex Reassignment Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sex Reassignment Surgery Market Foresight
Buyer concentration among academic medical centers is realigning as community hospitals and ambulatory surgery centers build gender-affirming programs. Mayo Clinic leverages its multidisciplinary model across integrated transplant and reconstructive units. Mount Sinai Centre for Transgender Medicine and Surgery anchors East Coast referral networks through fellowship-trained surgical volume. Cleveland Clinic competes on robotic-assisted platform specialization within its urologic reconstruction division.
Sex reassignment surgery encompasses reconstructive procedures that modify primary and secondary sexual characteristics to align with gender identity, employing microvascular free-flap transfer, penile inversion techniques, and robotic-assisted peritoneal pull-through with operative durations extending four to twelve hours. Vaginoplasty dominates procedural volume due to established surgical pathways and mature reimbursement frameworks. Phalloplasty sustains premium positioning through multi-stage complexity and microsurgical flap requirements. Robotic surgery is gaining fastest within academic settings where capital equipment and fellowship training coincide.
FDA oversight of surgical devices and biologic grafts intersects with CMS national coverage determinations and state-level Medicaid expansion decisions to shape market access. The EU Medical Device Regulation and Thailand's Ministry of Public Health facility licensing standards impose divergent compliance burdens on cross-border surgical tourism. Stakeholders must monitor evolving insurance parity enforcement and robotic platform training credentialing as determinants of sustainable program economics.
Market Dynamics
Insurance parity enforcement and robotic platform credentialing are restructuring competitive economics, as academic medical centers race to deploy capital-intensive surgical systems before community hospitals can replicate fellowship-trained volume.
Growth Catalysts
- US Affordable Care Act Section 1557:Federal nondiscrimination protections mandate coverage for gender-affirming procedures, expanding addressable patient populations across Medicaid expansion states.
- Robotic-assisted peritoneal pull-through:Reduced operative morbidity and shortened recovery windows attract self-pay surgical tourism from markets lacking domestic capacity.
- Thailand's universal coverage expansion:Ministry of Public Health facility licensing standards now include gender-affirming care, legitimizing Bangkok and Phuket as regional referral hubs.
Market Restraints
- Microsurgical flap supply concentration:Donor site morbidity and specialized reconstructive training bottlenecks limit phalloplasty throughput to a handful of high-volume centers.
- EU Medical Device Regulation compliance:Biologic graft reclassification as Class III devices imposes clinical evidence burdens that delay market entry for tissue-engineered products.
- State-level Medicaid exclusion variability:Nineteen US states maintain categorical exclusions for transition-related care, fragmenting reimbursement geography and distorting patient migration patterns.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Emerging regulatory framework for innovative surgical devices creates first-mover positioning for robotic platform manufacturers.
- Ambulatory surgery center migration:Select vaginoplasty procedures shift to outpatient settings where facility fees and anesthesia costs compress total episode spending.
- Peritoneal and buccal mucosa graft convergence:Tissue engineering advances enable autologous cell expansion, reducing dependence on intestinal segment harvest for vaginal lining construction.
Industry Challenges
- Fellowship pipeline constraints:Gender-affirming surgery fellowship positions number fewer than forty annually across accredited US programs, creating decade-long specialist scarcity.
- Robotic credentialing fragmentation:Manufacturer-specific training modules lack cross-platform standardization, complicating staffing flexibility and program scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sex Reassignment Surgery Market |
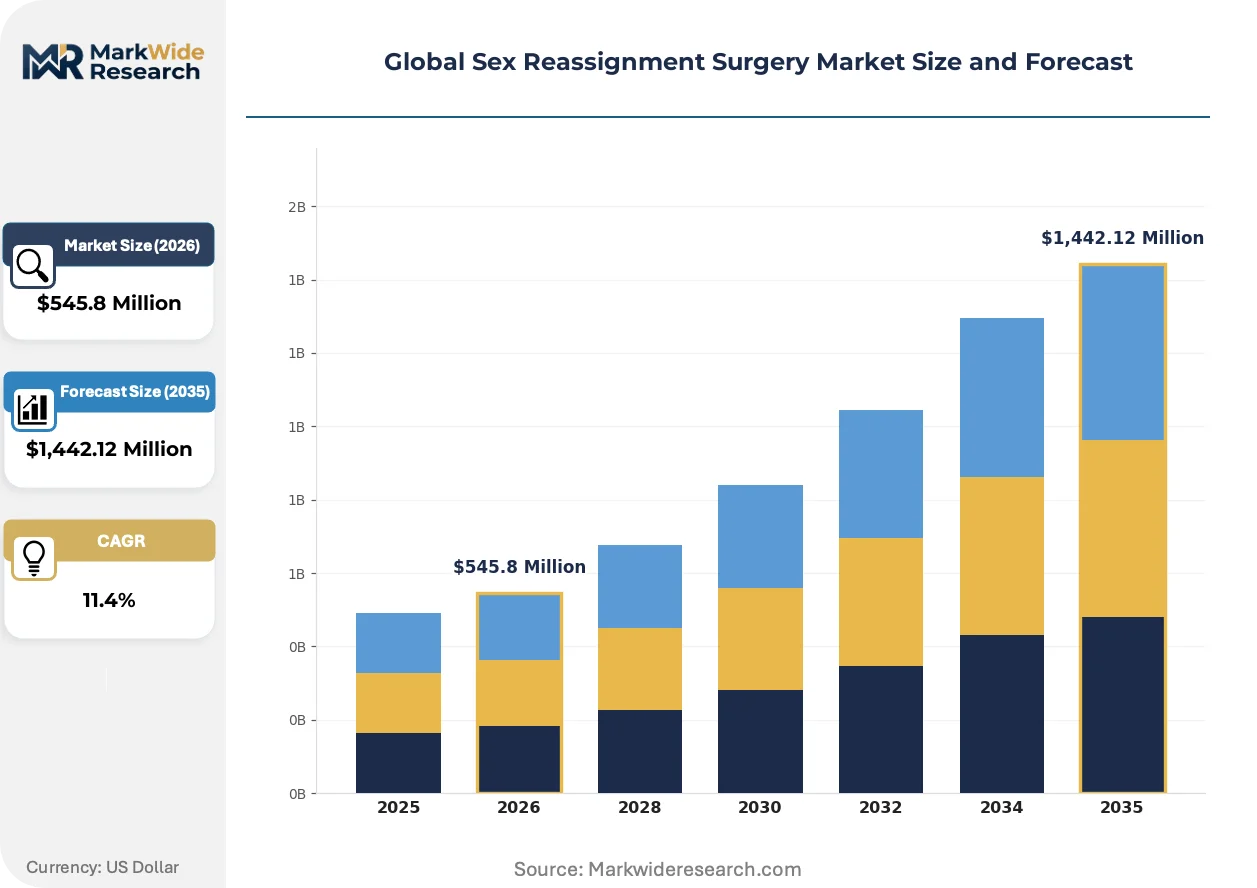
| Market Size in 2026 | $545.8 Million |
| Market Size in 2035 | $1,442.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Vaginoplasty, Phalloplasty, Orchiectomy, Penectomy, Hysterectomy, Metoidioplasty Technique: Robotic Surgery, Laparoscopic Surgery, Open Surgery, Microsurgery, Laser Surgery Patient Demographic: Adult Male-to-Female, Adult Female-to-Male, Transgender Youth, Non-binary Individuals, Gender Nonconforming Care Setting: Specialized Clinics, Academic Hospitals, Ambulatory Surgery Centers, Private Hospitals, Community Hospitals |
| Companies Covered | Boston Medical Center, Mayo Clinic, Mount Sinai Centre for Transgender Medicine and Surgery, Chettawut Plastic Surgery Centre, Johns Hopkins University / Center for Transgender Health, Cleveland Clinic, Transgender Surgery Institute, Rumercosmetics, Cedars-Sinai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sex Reassignment Surgery Market Shifts & Advancements
Reconstructive technique evolution and reimbursement model experimentation are compressing traditional care pathways, while digital preoperative planning tools reshape patient selection and surgical consent processes.
Robotic surgical platforms are integrating haptic feedback and three-dimensional visualization into gender-affirming procedures, enabling finer dissection in pelvic nerve-sparing operations. Academic medical centers in Germany and the United States deploy these systems at accelerating cadence, though capital constraints exclude most community hospitals. The technology is integrating previously separate urologic and gynecologic surgical domains into unified reconstructive services.
The EU Medical Device Regulation reclassification of biologic grafts and synthetic meshes imposes post-market surveillance obligations that smaller manufacturers struggle to fulfill. Clinical evidence generation timelines now extend eighteen to thirty-six months for novel implantable materials. Gender-affirming applications face particular scrutiny given limited historical trial enrollment, forcing sponsors to pursue conditional approvals with real-world data commitments.
Patient self-advocacy and peer network information sharing compress traditional referral pathways, with individuals increasingly selecting surgeons based on published complication registries and social media documentation. Direct-to-consumer consultation platforms disrupt primary care gatekeeping functions in urban United States and Western European markets. Thailand's private hospital groups respond with transparent pricing portals and video consultation infrastructure targeting English-speaking and Mandarin-speaking prospects.
Global Sex Reassignment Surgery Market Segmentation
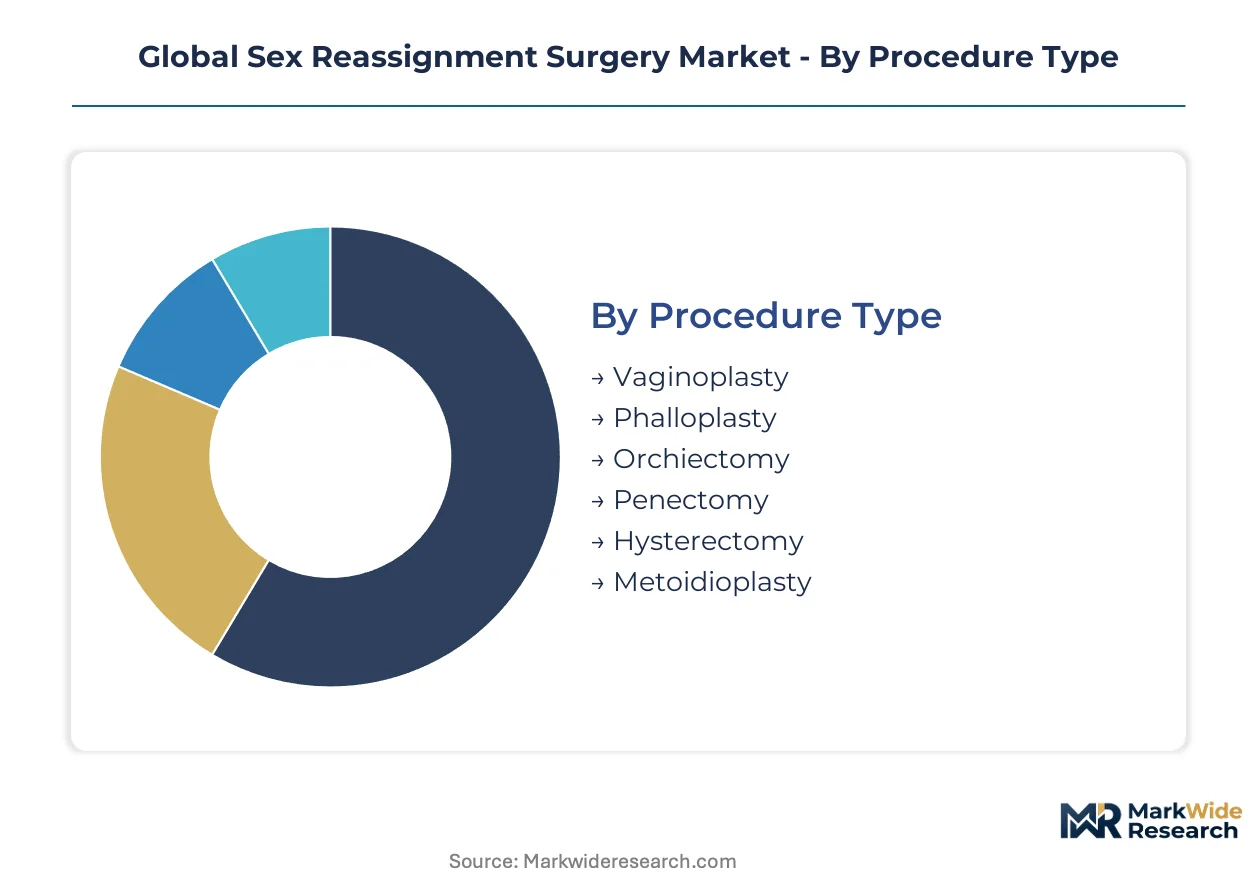
Segmentation reveals how capital deployment, regulatory complexity, and patient acuity stratify service delivery across the Global Sex Reassignment Surgery Market. Each dimension exposes distinct barriers to entry and reimbursement pathways that shape competitive positioning.
Procedure Type:
Capital intensity concentrates in multi-stage reconstructive pathways requiring microsurgical infrastructure and extended operative theater block scheduling.
- Vaginoplasty:Penile inversion and peritoneal pull-through techniques dominate procedural volume with established four-to-six-hour operative windows. Demand clusters in Thailand's private hospital networks and US academic medical centers where CMS coverage determinations and self-pay tourism intersect.
- Phalloplasty:Multi-stage microvascular free-flap reconstruction from radial forearm or anterolateral thigh donor sites demands specialized teams and eighteen-to-twenty-four-month treatment arcs. Throughput remains constrained to fewer than fifteen high-volume centers globally due to flap harvest morbidity and fellowship-trained specialist scarcity.
- Orchiectomy:Single-session gonadectomy with reduced facility requirements enables migration to ambulatory settings where anesthesia and facility fees compress episode costs.
- Penectomy:Tissue-sparing techniques preserve neurovascular bundles for subsequent reconstruction, limiting this segment to integrated gender surgery programs.
- Hysterectomy:Laparoscopic and robotic routes predominate as gynecologic surgeons cross-train into gender-affirming service lines.
- Metoidioplasty:Clitoral release and urethral lengthening from testosterone-enlarged genital tissue offers reduced morbidity for patients declining phalloplasty complexity.
Most installed capacity flows through vaginoplasty. Expansion is steepest in phalloplasty as microsurgical training pipelines mature.
Technique:
Technology adoption curves separate academic centers with capital equipment access from community programs constrained by depreciation schedules and case volume minimums.
- Robotic Surgery:Da Vinci platforms enable peritoneal pull-through vaginoplasty with three-dimensional visualization and tremor-filtered dissection. Germany's university hospitals and US academic medical centers deploy these systems fastest, though manufacturer-specific training modules fragment credentialing portability.
- Laparoscopic Surgery:Minimally invasive hysterectomy and orchiectomy routes reduce inpatient stays and attract payor preference for outpatient reimbursement bands.
- Open Surgery:Penile inversion vaginoplasty and complex revision cases retain open approaches where tactile feedback and direct visualization outweigh minimally invasive constraints.
- Microsurgery:Free-flap phalloplasty and nerve coaptation require operating microscopes and specialized nursing teams that concentrate in Bangkok, Berlin, and Cleveland surgical corridors.
- Laser Surgery:Tissue ablation and hair removal preconditioning for graft harvest sites utilize dermatologic laser platforms co-located within gender clinic service lines.
Robotic systems absorb the steepest capital allocation. Laparoscopic volumes are climbing fastest as training generalizes across gynecologic and urologic residencies.
Patient Demographic:
Clinical eligibility criteria and informed consent frameworks segment addressable populations by age thresholds and diagnostic classification systems.
- Adult Male-to-Female:Vaginoplasty demand concentrates among patients aged twenty-five to forty-five with established hormone therapy histories and mental health clearances. Thailand's Yanhee and PAI Hospitals target this segment through transparent pricing portals.
- Adult Female-to-Male:Chest reconstruction and hysterectomy precede phalloplasty or metoidioplasty in staged treatment arcs with distinct reimbursement coding.
- Transgender Youth:Puberty suppression and fertility preservation protocols precede surgical eligibility, limiting this segment to specialized pediatric endocrinology centers in the United States and Germany.
- Non-binary Individuals:Customized surgical plans combining masculinizing and feminizing elements challenge standardized procedural bundles and insurance prior authorization pathways.
- Gender Nonconforming:Chest reconstruction without genital modification represents fastest-growing demand among patients seeking partial anatomical alignment.
Adult male-to-female patients generate the highest surgical encounter volume. Gender nonconforming presentations are expanding most quickly as diagnostic categories broaden.
Care Setting:
Facility licensing standards and reimbursement tiering stratify service delivery across institutional types with divergent cost structures.
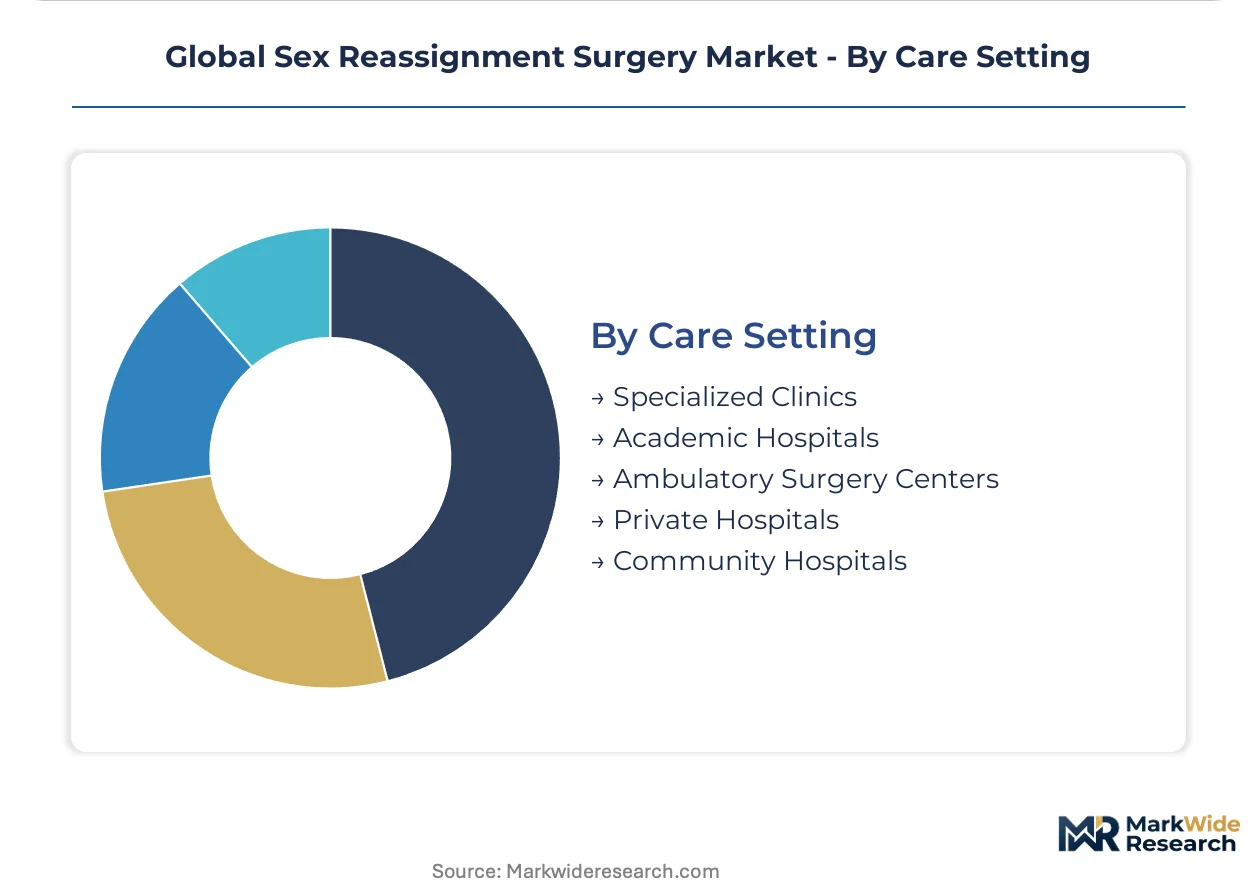
- Specialized Clinics:Bangkok's Kamol Hospital and Mount Sinai's dedicated center concentrate fellowship-trained surgeons and multidisciplinary care coordination. These settings command premium self-pay pricing and complex referral network positioning.
- Academic Hospitals:Mayo Clinic and Cleveland Clinic integrate gender surgery within transplant and reconstructive divisions, leveraging robotic platforms and research protocols.
- Ambulatory Surgery Centers:Select orchiectomy and vaginoplasty cases migrate to outpatient settings where facility fees and anesthesia costs compress total episode spending.
- Private Hospitals:Thailand's Bumrungrad and Bangkok Hospital groups compete on surgical tourism infrastructure with Mandarin and English consultation services.
- Community Hospitals:Emerging programs in Medicaid expansion states build referral relationships with academic centers for complex case backup.
Specialized clinics retain the deepest surgeon concentration. Ambulatory surgery centers are gaining share fastest as vaginoplasty techniques standardize for outpatient safety profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's surgical tourism infrastructure attracts cross-border patients at price points one-third below US academic centers, while Germany's statutory health insurance system removes cost barriers entirely for domestic residents.
United States
Medicaid expansion under the Affordable Care Act and Section 1557 nondiscrimination enforcement have opened reimbursement pathways in thirty-two states. Cleveland Clinic and Mayo Clinic anchor Midwest surgical corridors with robotic platform investments. California and New York Metro areas concentrate fellowship-trained surgeon density.
Germany
Statutory health insurance covers gender-affirming procedures without prior diagnosis requirements, eliminating financial barriers for eligible patients. The EU Medical Device Regulation shapes biologic graft approval timelines for tissue-engineered products. Berlin and Munich university hospitals lead peritoneal pull-through technique adoption.
Thailand
Ministry of Public Health facility licensing standards now include gender-affirming care within universal coverage expansion. Bangkok's Yanhee and PAI Hospitals compete on transparent pricing portals and Mandarin-language consultation services. Phuket surgical tourism clusters target Australian and Chinese self-pay patients.
United Kingdom
NHS England's Gender Identity Services program funds surgical referrals through designated gender identity clinics with multi-year waiting lists. The Care Quality Commission inspects private providers entering the market. London anchors specialist concentration with ties to European academic networks.
Brazil
ANVISA's emerging fast-track pathway for innovative surgical devices creates regulatory positioning opportunities for robotic platform manufacturers. São Paulo's private hospital networks build gender-affirming service lines. Federal court rulings have mandated public health system coverage for transition-related care.
Global Sex Reassignment Surgery Market Competitive Landscape
US academic medical centers anchor one tier; Thai private hospital specialists hold cost-advantaged positioning for cross-border patients. The market structures around institutional reputation, surgical volume credentialing, and robotic platform access. Three archetypes dominate: integrated academic health systems, dedicated gender surgery institutes, and surgical tourism hospitals. Competitive moves concentrate on fellowship-trained surgeon recruitment and robotic system deployment.
Within the academic health system tier, Mayo Clinic and Cleveland Clinic exemplify capital-intensive positioning through integrated reconstructive divisions. Chettawut Plastic Surgery Centre anchors Bangkok's surgical tourism corridor with dedicated gender-affirming infrastructure. Mount Sinai Centre for Transgender Medicine and Surgery occupies a referral-network position on the US East Coast.
| Leading Market Players |
|---|
| Boston Medical Center |
| Mayo Clinic |
| Mount Sinai Centre for Transgender Medicine and Surgery |
| Chettawut Plastic Surgery Centre |
| Johns Hopkins University / Center for Transgender Health |
| Cleveland Clinic |
| Transgender Surgery Institute |
| Rumercosmetics |
| Cedars-Sinai |
| Others |
Supply & Pricing Matrix
Academic medical center premiums versus surgical tourism discount tiers bifurcate the Global Sex Reassignment Surgery Market, with Thailand's self-pay corridors compressing price floors while US robotic platform investments sustain elevated reimbursement bands. This divergence maps directly onto supply chain configurations: Bangkok's dedicated gender clinics consolidate microsurgical teams and biologic graft sourcing under single-facility licensing, whereas fragmented US procurement routes separate hospital purchasing committees from manufacturer credentialing modules.
Pricing Analysis
Capacity additions in Thailand's private hospital networks are reshaping price floors for vaginoplasty procedures, forcing US academic centers to justify premiums through robotic-assisted outcomes data and bundled complication coverage. Three-tier pricing structure across premium robotic, standard open, and economy tourism levels stratifies patient access, with FDA-credited biologic grafts commanding tier premiums over Thai-sourced alternatives. Pricing pressure stems from Medicaid expansion variability across nineteen US exclusion states, redirecting domestic patients toward cross-border options. Self-pay surgical tourists exhibit highest price sensitivity; insured patients at Mayo Clinic and Cleveland Clinic demonstrate lowest elasticity due to network-restricted plan designs.
Supply Chain Analysis
Freight costs for temperature-sensitive biologic grafts and robotic platform spare parts elevate landed costs for European and Southeast Asian facilities distant from German and US manufacturing hubs. Supply concentrates in Germany for peritoneal pull-through instrumentation, Thailand for dedicated gender-clinic nursing labor, and the United States for robotic system manufacturing and fellowship-trained surgeon pipelines. Raw material dependencies center on human acellular dermal matrix products, titanium surgical fasteners, and CO₂ laser platforms for preoperative hair removal. Single-source vulnerability pervades the Da Vinci robotic ecosystem, where manufacturer-specific training modules tether hospital programs to proprietary service contracts. Distribution runs through GPO-negotiated hospital supply chains in the United States, direct manufacturer relationships in Germany's statutory system, and vertically integrated procurement within Thai surgical tourism hospital groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in robotic platform utilization efficiency and ambulatory migration of select procedures, as capital-intensive academic positioning meets outpatient cost compression. Fellowship-trained surgeon scarcity and biologic graft standardization represent the primary levers for sustainable premium capture.
For Market Incumbents: To counter ambulatory surgery center encroachment on routine vaginoplasty volume, Mayo Clinic and Cleveland Clinic should deepen captive supply of fellowship-trained surgeons through endowed training positions and exclusive employment contracts. Defensive moves require backward integration into biologic graft processing partnerships that secure preferential allocation during EU Medical Device Regulation compliance bottlenecks.
For New Entrants and Emerging Players: Launch via direct-to-consumer consultation platforms targeting Medicaid exclusion-state patients with transparent pricing portals and video preoperative assessment infrastructure. White-space concentration exists in Brazilian private hospital networks building gender-affirming service lines under ANVISA's emerging fast-track pathway, and in US community hospitals seeking academic center backup relationships for complex phalloplasty referrals.
For Investors and Strategic Acquirers: Consolidation pressure builds where robotic platform credentialing fragmentation and fellowship pipeline constraints create decade-long specialist scarcity. Long-term viability favors vertically integrated hospital groups with captive surgeon training pipelines and biologic graft sourcing relationships. The signal to watch is CMS national coverage determination expansion for peritoneal pull-through techniques, which would validate capital-intensive robotic positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Credentialing Standardization | Cross-platform training modules would unlock staffing flexibility for hospital systems deploying multiple manufacturer systems. |
| Biologic Graft Processing Partnership | EU MDR compliance investments by tissue banks secure preferential supply allocation during approval bottlenecks. |
| Fellowship Training Pipeline Expansion | Endowed positions at Mount Sinai and Johns Hopkins address decade-long specialist scarcity constraining phalloplasty throughput. |
| Ambulatory Surgery Center Licensing | Outpatient vaginoplasty migration compresses episode costs and attracts payor preference for lower reimbursement bands. |
| Surgical Tourism Infrastructure Investment | Bangkok Hospital Group's Mandarin-language consultation portals capture Chinese and Australian self-pay patient flows. |
Research Methodology
Coverage spans the United States, Germany, Thailand, the United Kingdom, and Brazil, with primary inputs from each market's distinct regulatory and reimbursement environment. The research combines structured interviews with gender-affirming surgeons, hospital procurement managers, biologic graft regulatory affairs specialists, and GPO contracts administrators with secondary validation against FDA 510(k) filings, EMA medical device registration databases, CMS national coverage determinations, and Thai Ministry of Public Health facility licensing records. Bottom-up procedure volume estimates triangulate against top-down health system expenditure data.
Granularity-level modeling disaggregates forecasts across procedure type, surgical technique, patient demographic, and care setting dimensions, with additional stratification by payer category and robotic platform deployment status. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and policy inflection points. Industry-specific forecast inputs include fellowship training pipeline graduation rates, EU MDR approval timelines for tissue-engineered products, and state-level Medicaid expansion probability assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under federal regulatory reversal of Section 1557 protections or accelerated EU MDR enforcement against biologic graft manufacturers. Model assumptions reflect current reimbursement pathways and training pipeline constraints. A model refresh is warranted upon material change in CMS national coverage determination scope or Thai universal coverage expansion pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Global Leishmaniasis Treatment Market