
 Global Stretch Marks Treatment Market | 2026-2036
Global Stretch Marks Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stretch Marks Treatment Market Foresight
The EU Medical Device Regulation is recalibrating clinical evidence standards for laser and microneedling platforms entering European markets. Clarins leverages botanical R&D intensity to sustain premium positioning in topical creams across French and Asian markets. Cynosure anchors North American installed base leadership through service contracts and training ecosystems. Laboratoires Expanscience competes via pharmacy channel control and postpartum-specific formulations.
Stretch marks treatment encompasses topical formulations, energy-based devices, and procedural interventions designed to remodel dermal collagen and reduce striae visibility through mechanisms including fractional laser resurfacing, controlled micro-injury, and epidermal renewal. These modalities serve both medical correction of dermal tearing and elective cosmetic enhancement across outpatient and home-use settings. Topical creams occupy the largest revenue pool due to accessibility and repeat purchase economics, while laser therapy captures premium margins concentrated in dermatology clinics and medical spas. Home care users represent the fastest-growing end user segment as direct-to-consumer devices and tele-dermatology expand access beyond clinical settings.
The FDA governs device clearance pathways for laser and microneedling systems through 510(k) and De Novo classifications, while the EU MDR mandates notified body involvement and post-market surveillance for equivalent platforms in Europe. REACH compliance in the European Union further constrains formulation chemistry for topical actives, elevating R&D costs for botanical and peptide-based creams. Stakeholders must monitor evolving MDR implementation timelines and FDA software-as-medical-device guidance for connected home-use technologies.
Market Dynamics
The EU MDR is compressing time-to-market for laser and microneedling platforms while postpartum care protocols in dermatology clinics expand procedural volumes. Device manufacturers face dual pressure from tightened clinical evidence requirements and concentrated buyer power among medical spa chains.
Growth Catalysts
- Postpartum protocol expansion:Dermatology clinics in the United States and France are integrating striae reduction into bundled maternity wellness packages, driving recurring procedural revenue.
- REACH compliance innovation:Formulation chemistry constraints under EU chemical regulations are accelerating botanical R&D investment for peptide-based topical actives.
- Tele-dermatology platforms:Remote consultation infrastructure enables prescription-grade home device distribution beyond traditional clinic channels.
Market Restraints
- Clinical evidence cost inflation:EU MDR notified body involvement and post-market surveillance mandates double regulatory expenditure for laser platform market entry.
- Input concentration risk:Fractional laser component supply concentrates among German and Japanese optical subsystem specialists, creating procurement vulnerability.
- Topical efficacy ceiling:Epidermal penetration limits of cream formulations constrain outcomes for mature striae, ceding severe cases to energy-based alternatives.
Strategic Opportunities
- Underpenetrated Indian market:Rising disposable income and pharmacy channel expansion create entry points for mid-priced topical formulations.
- Connected home device convergence:Integration of fractional RF with smartphone-guided treatment protocols opens direct-to-consumer subscription models.
- Brazilian regulatory tailwind:ANVISA streamlining of aesthetic device classifications accelerates approval timelines for microneedling platforms.
Industry Challenges
- Energy device technician scarcity:Safe operation of fractional laser systems requires certified dermatology staff, creating bottlenecked service capacity.
- Legacy clinic software integration:Connected home-use devices face interoperability friction with established electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stretch Marks Treatment Market |
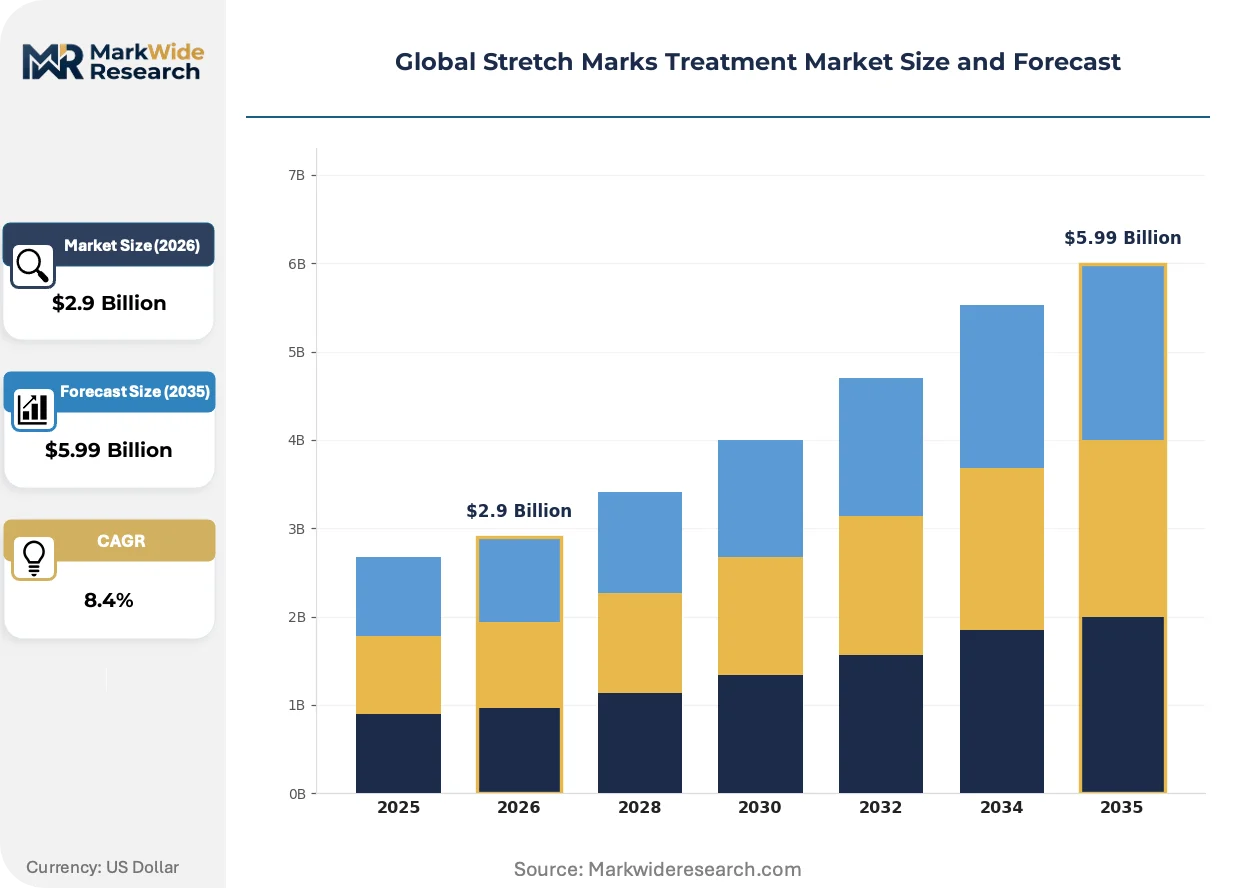
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Laser Therapy, Microneedling Devices, Chemical Peels, Surgery Application: Postpartum Care, Weight Loss Recovery, Puberty, Cosmetic Enhancement, Scar Reduction End User: Dermatology Clinics, Medical Spas, Cosmetic Surgery Centers, Home Care Users, Wellness Centers Distribution Channel: Online Retail, Beauty Salons, Pharmacies, Direct Sales, Dermatologist Recommendations |
| Companies Covered | Clarins, Cynosure, Laboratoires Expanscience, Merz North America, Candela Corporation, Helix BioMedix, Alliance Pharma, Weleda, Union Swiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stretch Marks Treatment Market Shifts & Advancements
Energy-based modalities are fragmenting into hybrid platforms while regulatory frameworks on both sides of the Atlantic recalibrate evidence standards. Distribution channels are bifurcating between high-touch clinical delivery and algorithm-guided home protocols.
Radiofrequency microneedling is electrifying collagen remodeling protocols by delivering thermal energy at precise dermal depths. Medical spa chains in the United States are adopting these platforms at accelerated replacement cycles. The technology is electrifying margin structures by collapsing multiple treatment sessions into single-visit protocols.
EU MDR post-market surveillance requirements are extending clinical obligation timelines for laser manufacturers. Device vendors must now maintain active safety monitoring across European installed bases. Dermatology clinics in Germany and France are prioritizing suppliers with established notified body relationships.
Subscription-based home device programs are displacing one-time retail purchases for mid-tier striae treatments. Direct-to-consumer brands are bundling tele-dermatology consultations with fractional RF hardware. This model concentrates adoption among postpartum consumers in the United States seeking privacy-preserving alternatives to clinic visits.
Global Stretch Marks Treatment Market Segmentation
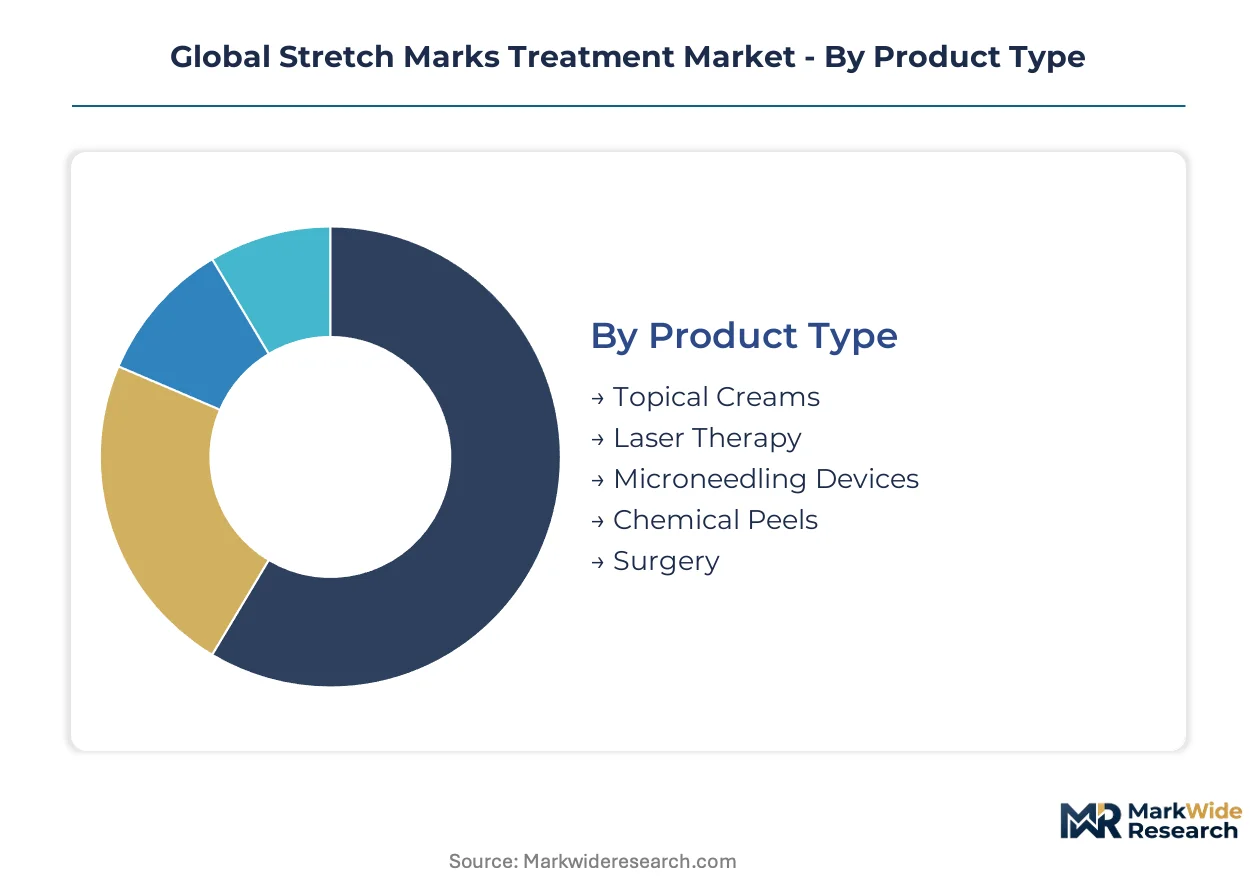
Stretch marks treatment modalities span radically different price points, clinical intensity, and user autonomy. Segmentation reveals how manufacturers allocate R&D resources across prescription-grade devices and mass-market topicals. Channel strategy diverges sharply between clinic-dependent energy platforms and pharmacy-distributed creams.
Product Type:
Laser wavelength specifications and penetration depths define clinical efficacy tiers.
- Topical Creams:Peptide and botanical formulations dominate pharmacy shelves. Clarins and Laboratoires Expanscience concentrate R&D spend in France and Japan where postpartum consumers drive repeat purchase cycles.
- Laser Therapy:Fractional CO2 and erbium:YAG systems remodel collagen through controlled thermal injury. Cynosure maintains installed base leadership in United States dermatology clinics through service contract lock-in.
- Microneedling Devices:Radiofrequency-augmented platforms deliver energy at precise dermal depths. Medical spa chains in California and Texas are replacing legacy systems at accelerated cycles.
- Chemical Peels:Trichloroacetic acid and glycolic acid protocols address epidermal discoloration. Demand clusters in South Korea aesthetic clinics seeking non-laser alternatives.
- Surgery:Abdominoplasty and skin excision procedures target severe striae cases. Brazilian cosmetic surgery centers report elevated procedural volumes for post-bariatric patients.
Mature deployment sits with Topical Creams. Newer deployment is concentrated in Microneedling Devices.
Application:
Patient life-stage determines treatment urgency, privacy preferences, and willingness to pay.
- Postpartum Care:Bundled maternity wellness packages in United States and French clinics now include striae reduction protocols. Privacy concerns drive demand for home-use alternatives among first-time mothers.
- Weight Loss Recovery:Bariatric surgery patients require extensive skin remodeling. German medical spas have developed specialized protocols addressing rapid tissue expansion damage.
- Puberty:Adolescent striae present early intervention opportunities. Indian pharmacy channels are expanding mid-priced topical access for this demographic.
- Cosmetic Enhancement:Elective procedures among fitness enthusiasts emphasize abdominal and thigh aesthetics. Dubai wellness centers market combination packages to expatriate professionals.
- Scar Reduction:Trauma and surgical scar overlap with stretch mark morphology. Japanese dermatology clinics apply fractional laser protocols developed for burn reconstruction.
Volume leadership belongs to Postpartum Care. Steepest expansion trajectory is concentrated in Weight Loss Recovery.
End User:
Capital intensity and staff certification requirements stratify service delivery models.
- Dermatology Clinics:Board-certified practitioners operate FDA-cleared laser platforms. United States reimbursement pathways for medically indicated striae treatment support premium pricing.
- Medical Spas:Non-physician operators under physician supervision deliver microneedling protocols. Chains like Ideal Image and Sono Bello standardize training across 200-plus locations.
- Cosmetic Surgery Centers:Combined surgical and non-surgical offerings attract high-acuity cases. Brazilian centers leverage ANVISA regulatory streamlining for device procurement.
- Home Care Users:Direct-to-consumer fractional RF devices with smartphone guidance expand access. Subscription models in United States concentrate among postpartum consumers seeking privacy.
- Wellness Centers:Holistic positioning integrates topical protocols with nutritional counseling. French thalassotherapy resorts bundle marine-based creams with hydrotherapy.
Revenue concentration sits with Dermatology Clinics. Gaining share fastest is Home Care Users.
Distribution Channel:
Channel control determines margin capture and patient relationship ownership.
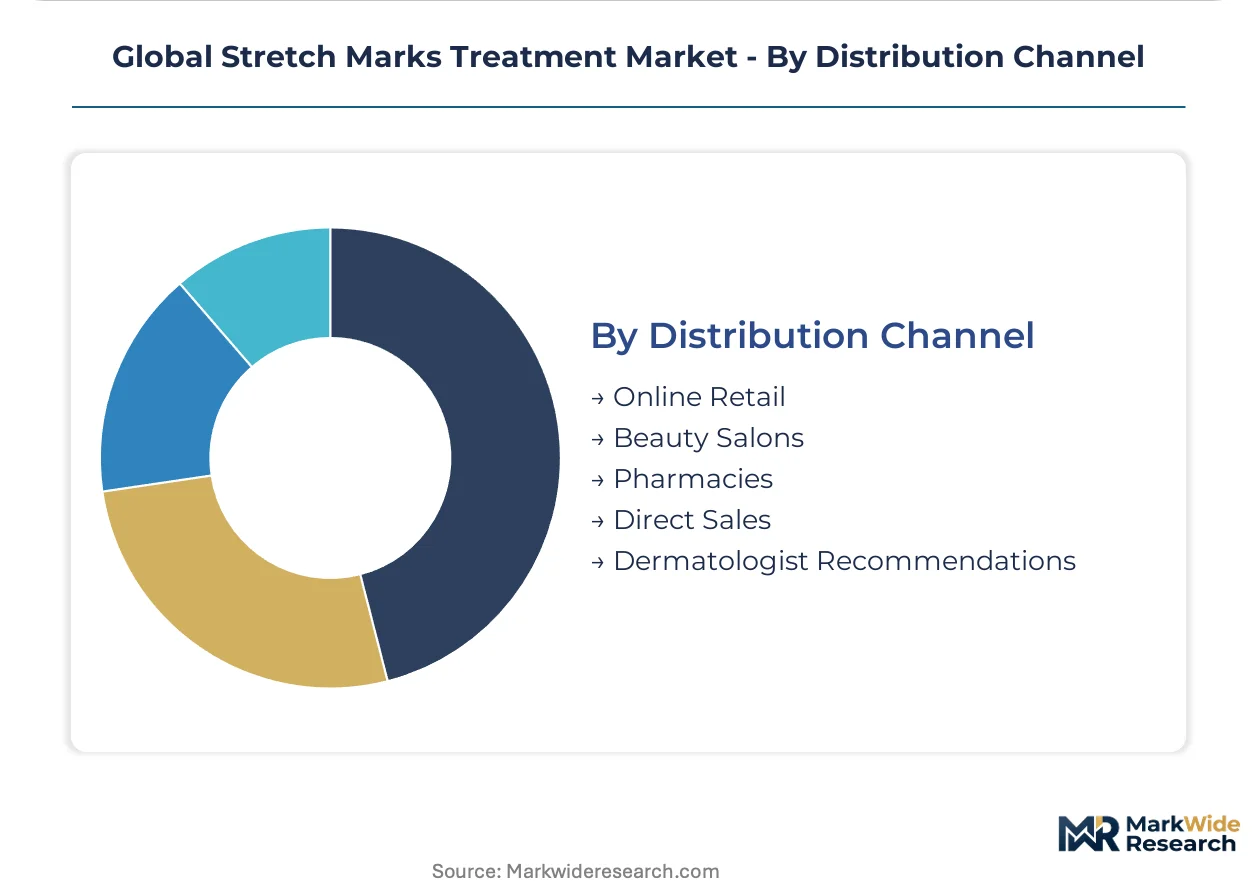
- Online Retail:Amazon and dedicated tele-dermatology platforms enable prescription-grade device distribution. Direct-to-consumer brands bypass clinic gatekeepers through influencer marketing.
- Beauty Salons:Non-medical venues sell cosmeceutical topicals with limited clinical claims. South Korean salon chains integrate skin analysis technology for personalized recommendations.
- Pharmacies:Laboratoires Expanscience controls shelf space through Mustela brand presence. French pharmacy exclusivity agreements protect margin structures.
- Direct Sales:Manufacturer-owned clinics and pop-up consultation events build brand equity. Cynosure operates training centers that double as demonstration facilities.
- Dermatologist Recommendations:Physician endorsement drives pharmacy fulfillment of prescription actives. United States tele-dermatology platforms automate this pathway for home device prescriptions.
Established volume sits with Pharmacies. Channel investment is concentrating in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the United States aesthetic device ecosystem, with medical spa chains and cosmetic surgery centers driving procedural volume for fractional laser and microneedling platforms. Demand concentrates in postpartum care protocols and weight loss recovery segments across metropolitan clusters.
United States
FDA 510(k) clearance pathways govern laser and microneedling device entry, with De Novo classifications emerging for connected home-use technologies. Medical spa chains in Texas and Florida standardize training protocols across multi-state footprints. Postpartum consumers in California drive subscription-based home device adoption through tele-dermatology platforms.
Germany
EU MDR notified body involvement mandates extended clinical evidence timelines for laser platform manufacturers. Dermatology clinics in Munich and Frankfurt prioritize suppliers with established BSI or TÜV SÜD relationships. REACH compliance constraints elevate R&D investment for botanical topical actives targeting pharmacy distribution.
France
ANSM post-market surveillance requirements align with EU MDR implementation for energy-based devices. Laboratoires Expanscience controls pharmacy shelf space through Mustela brand presence in Paris and Lyon corridors. Thalassotherapy resorts in Brittany bundle marine-based creams with hydrotherapy protocols.
Brazil
ANVISA streamlining of aesthetic device classifications accelerates microneedling platform approval timelines. Cosmetic surgery centers in São Paulo report elevated procedural volumes for post-bariatric striae cases. Rio de Janeiro clinics leverage regulatory clarity to expand service menus for weight loss recovery segments.
India
CDSCO medical device rules classify laser platforms under risk-based frameworks with notified body consultation. Pharmacy channel expansion in Maharashtra and Karnataka creates entry points for mid-priced topical formulations. Rising disposable income in Delhi-NCR drives demand for adolescent striae interventions.
Global Stretch Marks Treatment Market Competitive Landscape
The competitive structure tilts toward dermatology device specialists with installed base lock-in through service contracts. Topical cream manufacturers compete via pharmacy channel control and botanical R&D differentiation. Three archetypes dominate: energy platform vendors with training ecosystems, formulation specialists with pharmacy exclusivity, and direct-to-consumer brands with subscription hardware models. Competitive moves concentrate on M&A for regulatory capabilities and geographic expansion into underpenetrated Asian markets.
Among French formulation specialists, Clarins and Laboratoires Expanscience exemplify the pharmacy-channel archetype with postpartum-focused positioning. Cynosure represents the installed-base leadership model for energy platforms, anchoring United States dermatology clinic relationships through service infrastructure. These three entities occupy distinct competitive vectors without direct product overlap.
| Leading Market Players |
|---|
| Clarins |
| Cynosure |
| Laboratoires Expanscience |
| Merz North America |
| Candela Corporation |
| Helix BioMedix |
| Alliance Pharma |
| Weleda |
| Union Swiss |
| Others |
Supply & Pricing Matrix
Certified dermatology technician scarcity in Germany and Japan concentrates labor cost differentials across procedural tiers, widening spreads between premium clinic-delivered laser protocols and economy home-use device subscriptions.
Pricing Analysis
Outcome-based pricing anchors fractional laser and RF microneedling platforms to visible striae reduction metrics rather than per-session fees. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinic systems from direct-to-consumer hardware and mass-market topicals. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the home-use tier is intensifying because tele-dermatology platforms collapse consultation overhead. Postpartum consumers in the United States exhibit lowest price sensitivity; pharmacy-channel adolescents in India show highest.
Supply Chain Analysis
Direct-to-clinic channels handle high-value laser platform deployment, while direct-to-consumer distribution runs through Amazon and tele-dermatology portals for home devices. Optical subsystem manufacturing concentrates in Germany and Japan. Fractional laser production draws from precision-machined sapphire lenses, RF generators, and motion-control encoders. Single-source vulnerability sits with Japanese optical component specialists. Pharmacy-channel topicals flow through Laboratoires Expanscience's controlled wholesale network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiofrequency microneedling is displacing legacy fractional CO2 systems as the dominant collagen remodeling protocol, compressing replacement cycles and reshaping vendor competitive dynamics.
For Market Incumbents: Cement installed base lock-in through multi-year service contracts covering preventive maintenance and technician certification renewals. Deepen backward integration into RF generator manufacturing to offset Japanese optical component supply risk. Prioritize EU MDR notified body relationship investment to compress approval timelines for next-generation platforms. For New Entrants and Emerging Players: Tele-dermatology platforms represent the most penetrable channel for prescription-grade home device distribution. Target postpartum consumers in the United States through privacy-preserving subscription models bundled with remote consultation. Enter the Indian market via mid-priced topical formulations through expanding pharmacy networks in Maharashtra and Karnataka. For Investors and Strategic Acquirers: The window for entry favors device manufacturers with established FDA 510(k) clearance pathways and EU MDR technical documentation capabilities. Long-term viability hinges on convergence between clinic-grade efficacy and home-use convenience. Monitor ANVISA regulatory streamlining in Brazil as inflection indicator for Latin American market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market entry timelines for laser platforms through notified body relationship depth. |
| Tele-Dermatology Platform Partnership | Enables prescription-grade home device distribution beyond traditional clinic gatekeepers. |
| Botanical R&D Capacity Expansion | Addresses REACH compliance constraints for peptide-based topical actives in European pharmacy channels. |
| RF Generator Manufacturing Integration | Reduces procurement vulnerability to Japanese optical subsystem concentration. |
| Postpartum Consumer Subscription Model | Captures privacy-driven demand among first-time mothers seeking home-based striae treatment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dermatology clinic operators, medical spa chain procurement directors, biomedical device engineers, and pharmacy channel managers across the United States, Germany, France, and Brazil. FDA 510(k) databases, EU MDR notified body registers, ANVISA approval records, and CDSCO medical device classifications provided device pathway validation. Bottom-up procedural volume estimates triangulated against top-down market sizing from customs export data and manufacturer revenue disclosures.
Product type, application, end user, and distribution channel dimensions were modeled at country-level granularity across the projection horizon. CAGRs derived from regression analysis of historical procedural volumes against demographic drivers and regulatory event impacts. Forecast inputs incorporated EU MDR implementation timeline assumptions, tele-dermatology platform adoption curves, and postpartum care protocol expansion rates in bundled maternity wellness packages.
Caveats apply where EU MDR notified body capacity constraints or FDA software-as-medical-device guidance revisions could materially shift the outlook for connected home-use technologies. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Non-Surgical Fat Reduction Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Alexandrite Laser Treatment Market