
 Body Contouring Market | 2026-2036
Body Contouring Market Size, Share, and Industry Trends Forecast 2026-2036
Body Contouring Market Intelligence
Medical spas is consolidating as the fastest-expanding end-user channel, overtaking traditional cosmetic surgery practices in device procurement volume. Alma Lasers leverages its multi-technology platform to serve this channel shift, while InMode sustains R&D intensity in radiofrequency-based body sculpting systems. Candela Medical competes through its established dermatology and plastic surgery relationships, and Venus Concept anchors its position with subscription-based device placement models.
Body contouring encompasses non-invasive and minimally invasive procedures that reduce adipose tissue or tighten skin through thermal, cryogenic, or electromagnetic energy delivery, typically operating at temperatures between minus eleven degrees Celsius and sixty degrees Celsius depending on modality. These procedures serve aesthetic medicine practitioners seeking alternatives to surgical liposuction with shorter patient recovery intervals. Laser and cryolipolysis technologies command the largest installed base, while electromagnetic muscle stimulation represents the fastest-growing technology segment due to its dual fat reduction and muscle toning value proposition. Among applications, post-pregnancy body reshaping generates premium pricing, whereas skin tightening applications attract an aging demographic with higher procedure frequency.
FDA 510(k) clearance requirements govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for energy-based aesthetic devices in Europe. These frameworks elevate barriers for new entrants but validate premium pricing for established manufacturers with robust regulatory dossiers. Stakeholders must monitor evolving reimbursement classifications for medically indicated versus purely cosmetic applications, as this boundary shift will determine addressable patient populations and pricing power across channels.
Market Dynamics
Radiofrequency-cryolipolysis hybrid platforms are consolidating device procurement decisions at medical spas, compressing capital deployment timelines and forcing single-modality manufacturers toward technology licensing or obsolescence.
Growth Catalysts
- EU Medical Device Regulation (MDR) clinical evidence standards:Established manufacturers with robust dossiers capture premium pricing as smaller competitors exit, consolidating procurement at dermatology chains.
- Medical spa channel expansion:Non-invasive procedure portfolios attract capital from private equity, accelerating device placement velocity beyond traditional cosmetic surgery clinics.
- Electromagnetic muscle stimulation:Dual fat reduction and muscle toning value propositions expand addressable patient populations into fitness-oriented demographics previously unreached by thermal or cryogenic modalities.
Market Restraints
- Capital intensity of FDA 510(k) clearance pathways:Clinical trial requirements and predicate device substantiation consume twelve to eighteen months, elevating barriers for energy-based aesthetic device entrants.
- Supply concentration in radiofrequency generator components:Korean and Israeli component suppliers control high-precision RF source manufacturing, exposing device assemblers to single-source risk.
- Substitution threat from surgical liposuction:Improved tumescent techniques and reduced anesthesia recovery intervals recover share among patients prioritizing single-session volume reduction.
Strategic Opportunities
- Brazilian aesthetic medicine infrastructure:Deep cultural acceptance of elective body sculpting and established physician training networks create whitespace for subscription-based device placement models.
- Post-pregnancy body reshaping applications:Premium pricing tolerance among demographic segments with elevated disposable income and specific anatomical correction needs remains underpenetrated.
- Convergence of AI-guided treatment planning with thermal monitoring:Real-time adipose tissue response algorithms reduce operator skill requirements and standardize outcomes across practitioner experience levels.
Industry Challenges
- Electromagnetic compatibility certification timelines:FCC Part 18 industrial, scientific, and medical equipment approvals for RF devices extend market entry schedules unpredictably.
- Integration complexity with legacy clinic management systems:Device connectivity protocols require middleware development for electronic health record synchronization and outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Contouring Market |
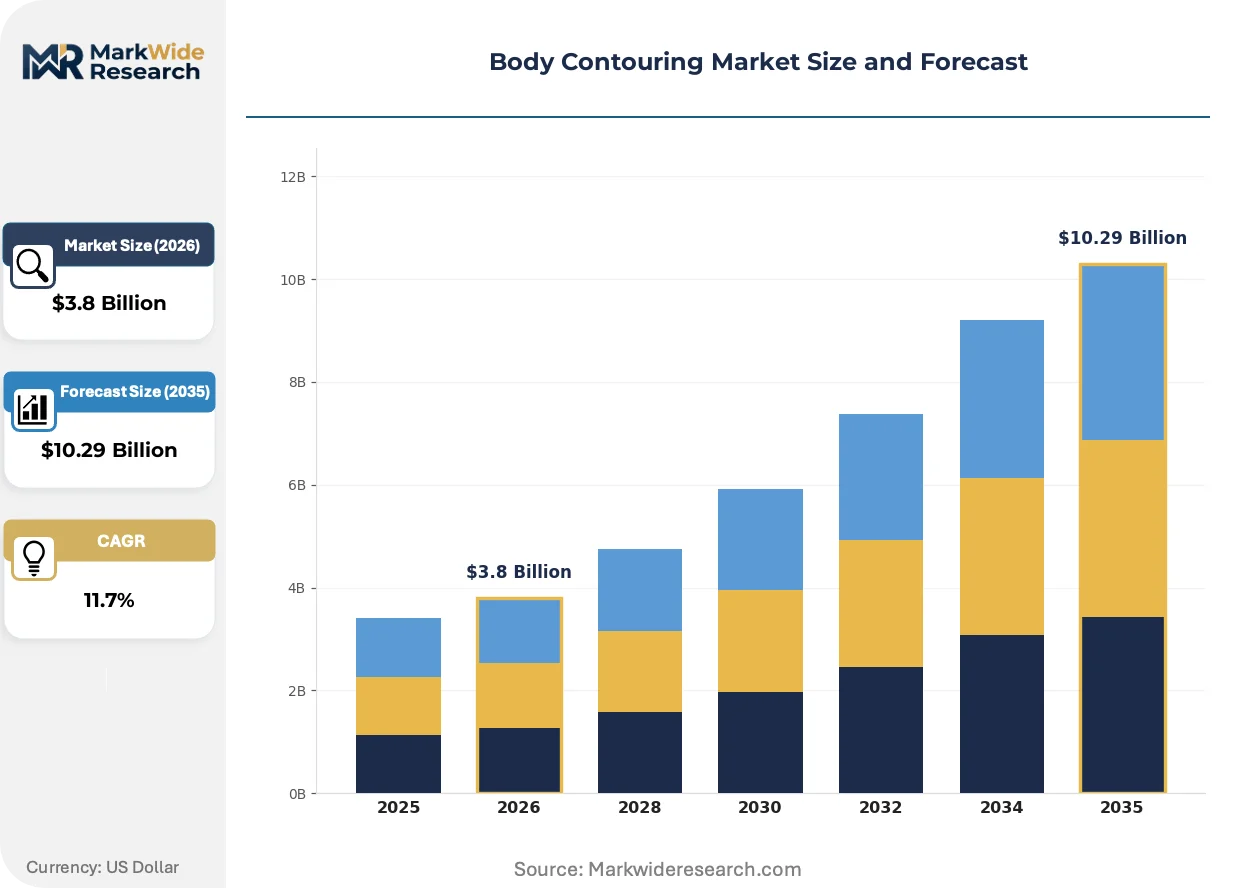
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Liposuction, Cool Sculpting, Radiofrequency, Ultrasound Technology: Laser, Cryolipolysis, Electromagnetic, Vacuum Therapy End User: Clinics, Medical Spas, Cosmetic Surgeons, Home Users Application: Weight Management, Post-Pregnancy, Body Reshaping, Skin Tightening |
| Companies Covered | Cutera, Alma Lasers, AbbVie, Venus Concept, Candela Medical, InMode, Cynosure, Lumenis, Bausch Health Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Contouring Market Strategic Shifts & Innovations
Hybrid energy delivery systems are compressing the traditional modality-specialist model, while regulatory evidence requirements and procurement centralization reshape competitive positioning across channels.
Multi-technology platforms combining cryolipolysis with radiofrequency skin tightening are unifying capital expenditure decisions at medical spa chains. Procurement directors at US dermatology groups prioritize single-vendor relationships covering adipose reduction and dermal laxity correction simultaneously. This consolidation is unifying service menus and compressing vendor rosters from four or five specialists to one or two full-suite suppliers.
The EU Medical Device Regulation imposes stricter clinical evidence standards for energy-based aesthetic devices than predecessor directives. Manufacturers must submit post-market surveillance data and biocompatibility testing for reusable applicators. European distributors are responding by consolidating representation agreements with dossier-complete suppliers and declining novel technology introductions lacking MDR certification.
Subscription-based device placement models are displacing outright capital purchase at independent cosmetic surgery practices. Venus Concept pioneered this structure, and competitors now replicate hardware-as-a-service arrangements with per-procedure revenue sharing. This financing shift is most visible in South Korea and Brazil, where physician-owned clinics face working capital constraints amid rapid technology refresh cycles.
Body Contouring Market Segmentation
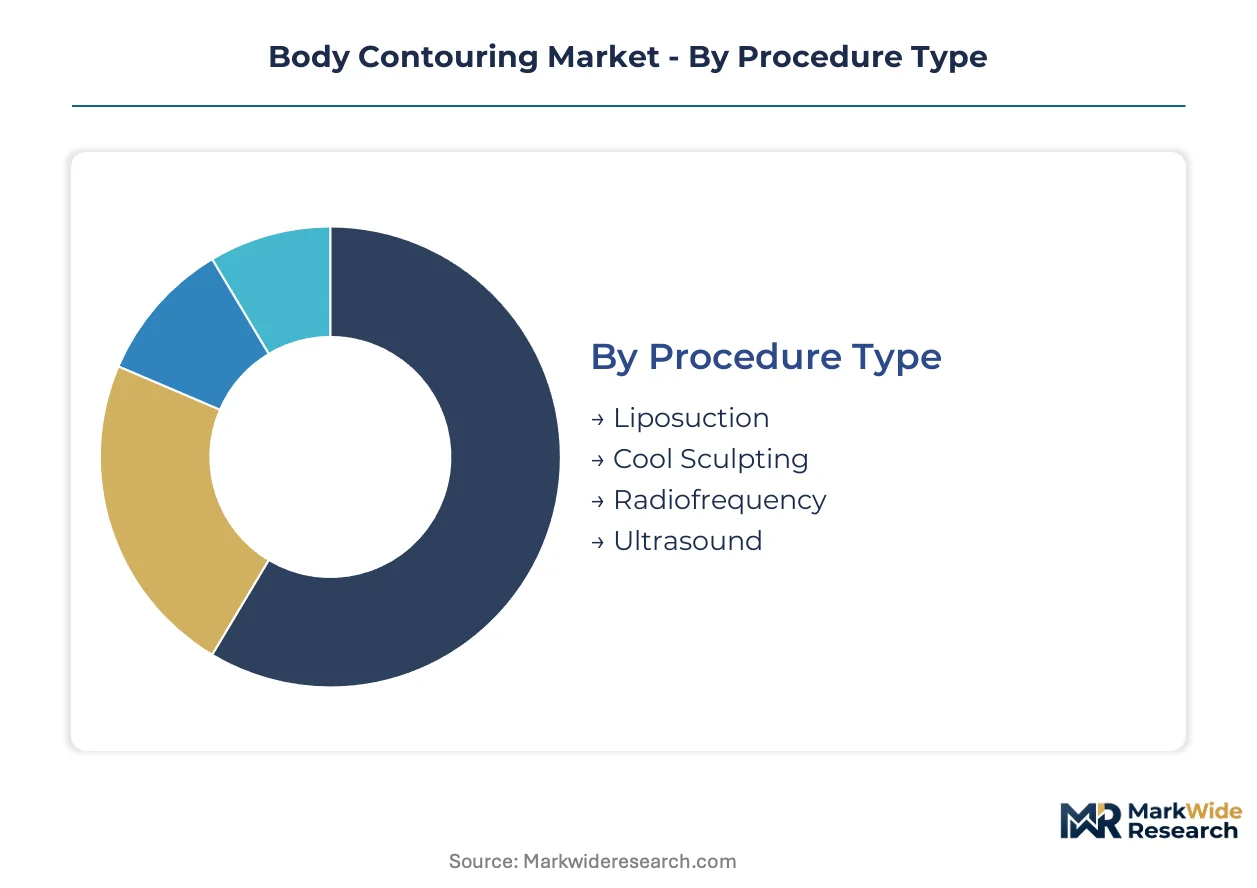
Technology modality and procedure type determine capital allocation patterns across aesthetic medicine channels. Segmentation reveals where procurement centralization concentrates and which patient demographics command premium pricing tolerance.
Procedure Type:
Energy delivery mechanisms define clinical outcomes, recovery intervals, and reimbursement positioning across practice settings.
- Liposuction:Surgical aspiration of adipose tissue through tumescent or ultrasound-assisted techniques remains the volume benchmark for single-session fat reduction. Demand concentrates among cosmetic surgeons in Brazil and South Korea where physician-owned clinics prioritize immediate, measurable outcomes over repeat visit economics.
- Radiofrequency:Thermal energy delivery at 40-60°C induces collagen remodeling and adipocyte apoptosis through controlled dermal heating. Medical spas in the United States deploy RF systems most intensively, driven by FDA 510(k) clearance pathways that validate marketing claims and reduce liability exposure.
- Cool Sculpting:Cryolipolysis at minus eleven degrees Celsius triggers selective adipocyte crystallization without dermal injury.
- Ultrasound:High-intensity focused acoustic energy disrupts fat cell membranes through mechanical cavitation.
Mature deployment sits with liposuction. Newer deployment is concentrated in radiofrequency.
Technology:
Platform architecture determines whether manufacturers capture single-modality or full-suite procurement relationships.
- Cryolipolysis:Controlled cooling applicators operate at precisely calibrated sub-zero temperatures to induce adipocyte apoptosis while preserving surrounding tissue. Dermatology chains in the United States favor cryolipolysis for its non-invasive profile and minimal operator training requirements.
- Electromagnetic:High-intensity focused electromagnetic fields induce supramaximal muscle contractions that simultaneously reduce fat and increase muscle mass. This dual-action mechanism is expanding most quickly into fitness-oriented demographics previously unreached by thermal modalities, with South Korean medical spas leading adoption velocity.
- Laser:Diode and Nd:YAG wavelengths target adipose tissue through photothermal or photomechanical effects.
- Vacuum Therapy:Mechanical suction combined with massage or thermal energy mobilizes lymphatic drainage and temporarily reduces cellulite appearance.
Established installed bases favor laser. Steepest expansion trajectory belongs to electromagnetic.
End User:
Channel economics determine whether device procurement follows capital purchase or subscription-based financing models.
- Medical Spas:Non-physician supervised facilities offering aesthetic procedures without surgical licensure requirements. These operators in the United States are overtaking traditional cosmetic surgery practices in device procurement volume, driven by private equity capital deployment and centralized purchasing at multi-location chains.
- Cosmetic Surgeons:Board-certified plastic surgeons performing surgical and non-surgical body contouring. This channel in Brazil maintains premium pricing power through established physician training networks and deep cultural acceptance of elective aesthetic procedures.
- Clinics:Dermatology and multi-specialty practices integrating body contouring into broader service menus.
- Home Users:Consumer-grade devices with reduced energy output for unsupervised domestic use.
Traditional procurement authority rests with cosmetic surgeons. Fastest channel growth concentrates in medical spas.
Application:
Patient life-stage and anatomical concern shape procedure frequency and pricing tolerance.
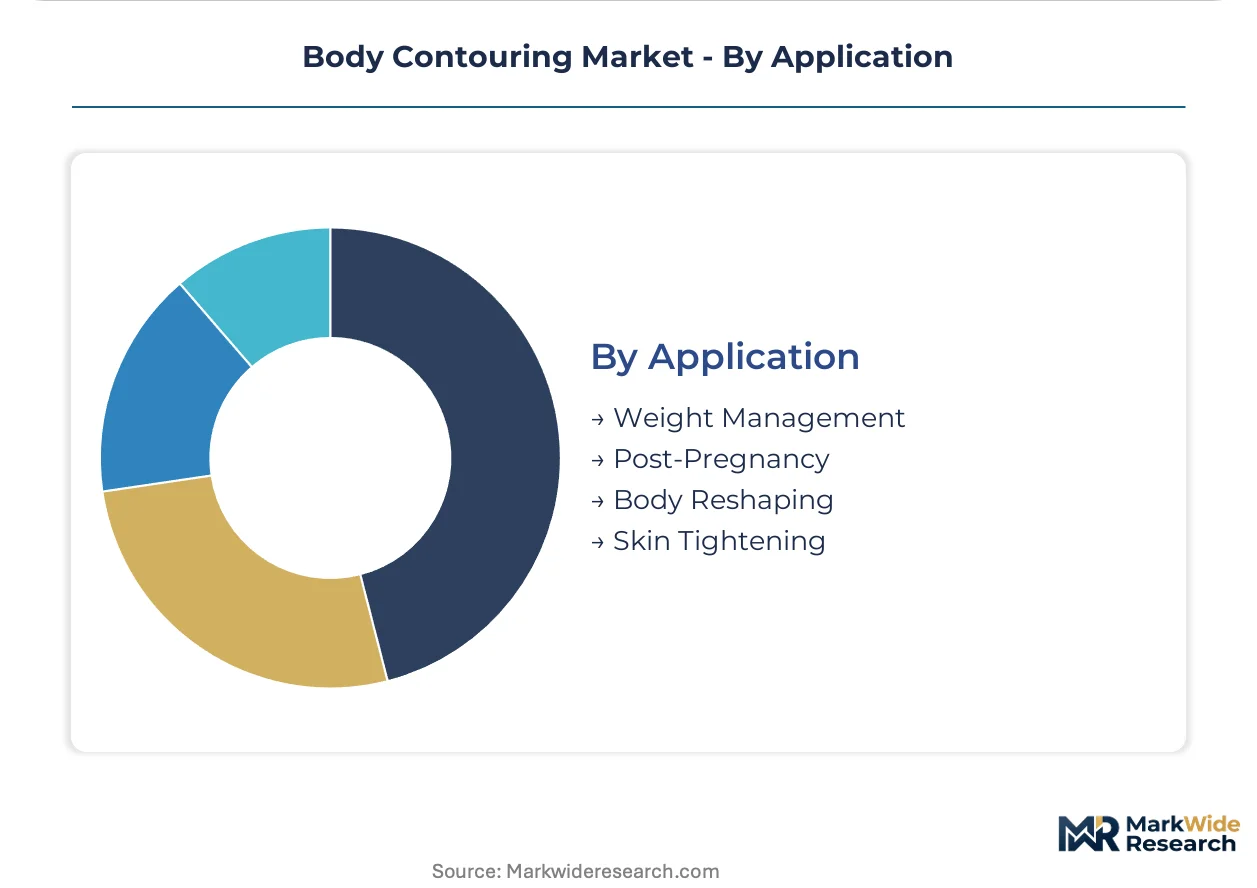
- Post-Pregnancy:Diastasis recti correction and abdominal contouring following childbirth. This segment commands premium pricing in the United States among demographics with elevated disposable income and specific anatomical correction needs that resist diet and exercise intervention.
- Skin Tightening:Dermal laxity correction through thermal collagen remodeling. An aging patient population in South Korea drives higher procedure frequency here, with repeat visit economics supporting device utilization rates at medical spa chains.
- Weight Management:General adipose reduction for body mass index optimization.
- Body Reshaping:Contour refinement across multiple anatomical zones.
Established volume sits with weight management. Premium pricing expansion concentrates in post-pregnancy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Dubai and São Paulo concentrate device distribution hubs serving adjacent markets. Medical tourism corridors in Seoul and Miami accelerate technology transfer. Regulatory divergence between FDA pathways and EU MDR timelines fragments product launch sequencing.
United States
Private equity consolidation of medical spa chains concentrates procurement decisions in Dallas and Miami metropolitan clusters. FDA 510(k) clearance requirements govern commercialization timelines for radiofrequency and cryolipolysis platforms. Los Angeles and New York serve as early adoption markets for hybrid energy delivery systems.
Brazil
Physician-owned cosmetic surgery practices in São Paulo and Rio de Janeiro maintain premium pricing power through established training networks. ANVISA registration requirements for energy-based aesthetic devices elevate barriers for non-dossier-complete suppliers. The São Paulo Free Trade Zone anchors import logistics for Israeli and Korean device manufacturers.
South Korea
Medical spas in Seoul and Busan lead adoption velocity for electromagnetic muscle stimulation technologies. MFDS certification standards for high-intensity focused electromagnetic equipment exceed baseline IEC requirements. The Pangyo Techno Valley cluster houses domestic device assemblers sourcing precision RF generators from local component suppliers.
Germany
Dermatology chains in Munich and Hamburg prioritize MDR-certified multi-technology platforms for capital efficiency. EU Medical Device Regulation post-market surveillance obligations compress vendor rosters toward dossier-complete manufacturers. The Düsseldorf medical technology corridor hosts distribution headquarters serving Central European aesthetic medicine practices.
United Arab Emirates
Dubai Healthcare City free zone incentives attract regional headquarters for US and European device manufacturers. MOHAP registration pathways for non-invasive body contouring equipment align with GCC harmonization initiatives. Jumeirah and Downtown Dubai medical spas serve medical tourism flows from Saudi Arabia and Egypt.
Body Contouring Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing procurement consolidation at medical spa chains while single-modality assemblers retreat toward component supply. The vendor base organizes into three tiers: full-suite suppliers with multi-technology platforms, RF or cryolipolysis specialists defending installed bases, and electromagnetic segment entrants scaling manufacturing. Dominant competitive moves include technology licensing to address modality gaps and subscription-based financing structures displacing capital purchase.
Among full-suite platform vendors, Alma Lasers, InMode, and Candela Medical exemplify the integrated archetype competing for single-vendor relationships at US dermatology groups. Venus Concept occupies a distinct position with hardware-as-a-service arrangements replicated across South Korean and Brazilian physician-owned clinics. These four entities anchor the competitive structure through divergent channel strategies.
| Leading Market Players |
|---|
| Cutera |
| Alma Lasers |
| AbbVie |
| Venus Concept |
| Candela Medical |
| InMode |
| Cynosure |
| Lumenis |
| Bausch Health Companies |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA 510(k) dossier-complete systems and emerging MDR-pending platforms manifests simultaneously in procurement premiums and component sourcing strategies. Premium-tier manufacturers command placement velocity at US medical spa chains while commodity assemblers face extended validation timelines that compress their addressable buyer pool.
Pricing Analysis
Short lead-time availability commands premium positioning at US dermatology groups, while spot inventory of single-modality cryolipolysis units trades at discounted rates. Subscription-based hardware-as-a-service structures dominate, separating premium multi-technology platforms from economy-tier refurbished systems. Price differentiation rests on FDA clearance tier and bundled training packages. Cost compression in the economy tier intensifies as Korean component suppliers extend payment terms to maintain volume. Medical spa procurement directors exhibit highest price sensitivity, whereas Brazilian physician-owned clinics prioritize outcome reliability over capital outlay.
Supply Chain Analysis
Workforce availability constraints in Israeli and South Korean precision electronics manufacturing limit RF generator output capacity. Device assembly concentrates in South Korea, Israel, and the United States, drawing from specialized semiconductor foundries and medical-grade cooling system fabricators. Single-source vulnerability in high-precision RF source manufacturing exposes assemblers to allocation risk during demand surges. Distribution runs through Dubai and São Paulo free trade zones serving adjacent regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid radiofrequency-cryolipolysis platforms are displacing legacy single-modality systems, compressing technology refresh cycles and restructuring competitive positioning across procurement channels.
For Market Incumbents: To counter electromagnetic muscle stimulation entrants, incumbents should deepen backward integration into RF generator supply and accelerate MDR dossier completion for European market defense. Channel control through exclusive multi-year service contracts at consolidating US dermatology chains provides additional moat. For New Entrants and Emerging Players: Begin with post-pregnancy body reshaping applications in Brazil, where premium pricing tolerance and underpenetrated demand create viable entry economics. Direct-to-physician training partnerships bypass established distributor relationships that incumbents dominate. For Investors and Strategic Acquirers: Re-rating potential sits with subscription-model platform vendors given medical spa channel consolidation and recurring revenue visibility. Long-term viability over the next decade favors manufacturers with dual FDA and MDR certification depth. Watch electromagnetic muscle stimulation adoption velocity in Seoul medical spas as inflection signal for modality shift magnitude.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | EU Medical Device Regulation dossier completion unlocks premium pricing at German dermatology chains. |
| Multi-Technology Platform Launch | Combined cryolipolysis-RF systems capture single-vendor procurement decisions at US medical spa groups. |
| Subscription Financing Structure | Hardware-as-a-service models displace capital purchase at Brazilian and South Korean physician clinics. |
| AI-Guided Treatment Software | Real-time adipose response algorithms reduce operator training requirements and standardize outcomes. |
| Component Supply Agreement | Long-term RF generator sourcing contracts with Israeli or Korean suppliers mitigate single-source risk. |
Research Approach
Independent corroboration across primary interviews with medical spa procurement directors, biomedical engineers at device manufacturers, and regulatory affairs specialists, combined with secondary validation of FDA 510(k) filings, ANVISA registration databases, and EU MDR certification records, underwrites the qualitative findings. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Comparable-period anchoring to historical technology adoption curves and installed base refresh cycles structured the forecast framework. The quantitative approach modeled procedure type, technology modality, end-user channel, and application dimensions throughout the projection horizon. CAGR derivation incorporated capital expenditure patterns at medical spa chains and reimbursement classification shifts for medically indicated versus cosmetic applications.
Underlying measurement precision varies by segment; FDA-cleared technology segments carry tighter precision than emerging electromagnetic categories. Forecasts reflect assumptions regarding regulatory timeline stability and private equity deployment velocity at US medical spa consolidators. Material deviation in MDR enforcement intensity or RF component supply allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Japan Facial Aesthetics Market