
 Middle East and Africa Dermal Fillers Market | 2026-2036
Middle East and Africa Dermal Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Dermal Fillers Market Foresight
High-net-worth individuals and younger professional women is bifurcating demand away from traditional hospital-based cosmetic surgery toward outpatient aesthetic medicine. Galderma leverages its hyaluronic acid portfolio to anchor premium clinic networks across the Gulf Cooperation Council states. Merz Aesthetics competes through specialized product lines targeting facial volume restoration. AbbVie Inc. sustains brand recognition from its legacy Allergan aesthetic franchise in South African metropolitan markets.
Dermal fillers comprise biocompatible gel or particulate formulations—predominantly cross-linked hyaluronic acid, calcium hydroxylapatite microspheres, or poly-L-lactic acid—administered via injection to restore subcutaneous volume, smooth rhytides, or sculpt facial contours. Hyaluronic acid formulations dominate commercial volume due to reversibility with hyaluronidase and established safety profiles, while calcium hydroxylapatite commands premium positioning in deeper structural augmentation. Application demand concentrates in facial contouring and lip enhancement procedures, with wrinkle reduction representing a mature, price-competitive segment where margin pools have compressed.
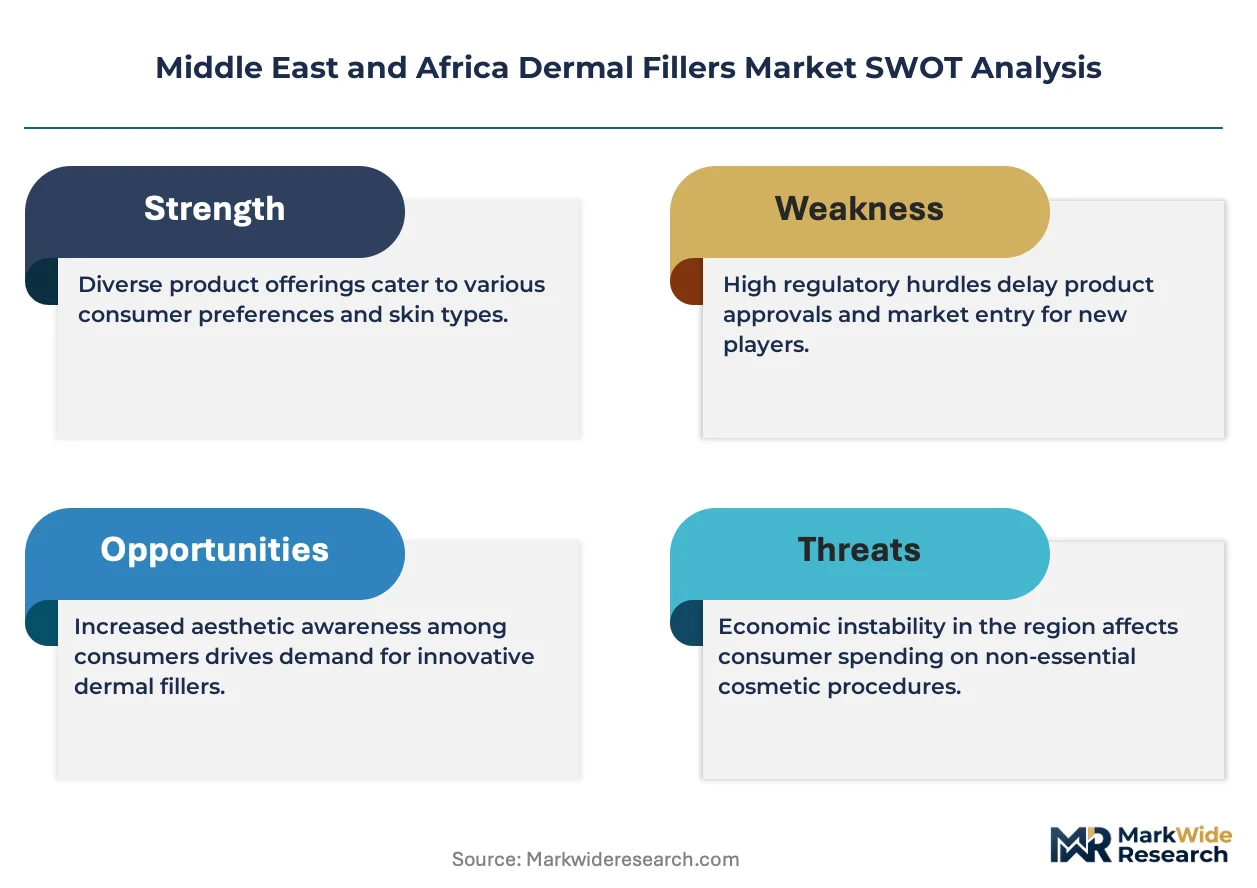
SFDA in Saudi Arabia and MOHAP in the UAE enforce registration requirements for injectable medical devices, compelling manufacturers to submit clinical evidence and stability data before market authorization. South Africa's national health regulator applies Medicine Control Council standards that classify certain dermal fillers as Schedule 4 medicines, restricting dispensing to licensed medical practitioners. Stakeholders must monitor evolving registration harmonization between Gulf health authorities and European CE marking reciprocity agreements to anticipate competitive entry timelines.
Market Dynamics
SFDA and MOHAP registration pathway tightening is compressing competitive entry timelines while concentrating market access among manufacturers with established clinical dossiers and Gulf regulatory infrastructure.
Growth Catalysts
- Hyaluronic acid reversibility:Immediate correction capability with hyaluronidase drives adoption in Dubai and Abu Dhabi aesthetic corridors where patient safety expectations run high.
- MOHAP streamlined device registration:Accelerated pathways for cross-linked gel formulations reduce time-to-market for compliant manufacturers holding European CE documentation.
- Medical spa network expansion:Outpatient aesthetic medicine capacity in Saudi Arabia and the UAE absorbs demand migrating from hospital-based cosmetic surgery.
Market Restraints
- Schedule 4 medicine classification:South Africa's Medicine Control Council restricts dermal filler dispensing to licensed practitioners, limiting retail channel development.
- Calcium hydroxylapatite supply concentration:Premium structural augmentation materials depend on limited North American and European manufacturing bases.
- Poly-L-lactic acid technical limitation:Delayed onset of volumetric correction requires multiple treatment sessions, compressing per-procedure economics.
Strategic Opportunities
- Egyptian medical tourism infrastructure:Cairo and Alexandria clinic networks remain underpenetrated relative to Gulf aesthetic corridor density.
- CE marking reciprocity expansion:Harmonization negotiations between Gulf health authorities and European notified bodies would accelerate product authorization timelines.
- Telemedicine consultation integration:Digital pre-assessment channels reduce patient acquisition costs for Johannesburg and Cape Town dermatology networks.
Industry Challenges
- Injection technique certification gaps:Standardized training frameworks for facial anatomy and complication management remain inconsistently deployed across Nigerian and Kenyan markets.
- Cold chain integrity requirements:Hyaluronic acid formulation stability demands complicate distribution into interior South African provinces and secondary Saudi cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Dermal Fillers Market |
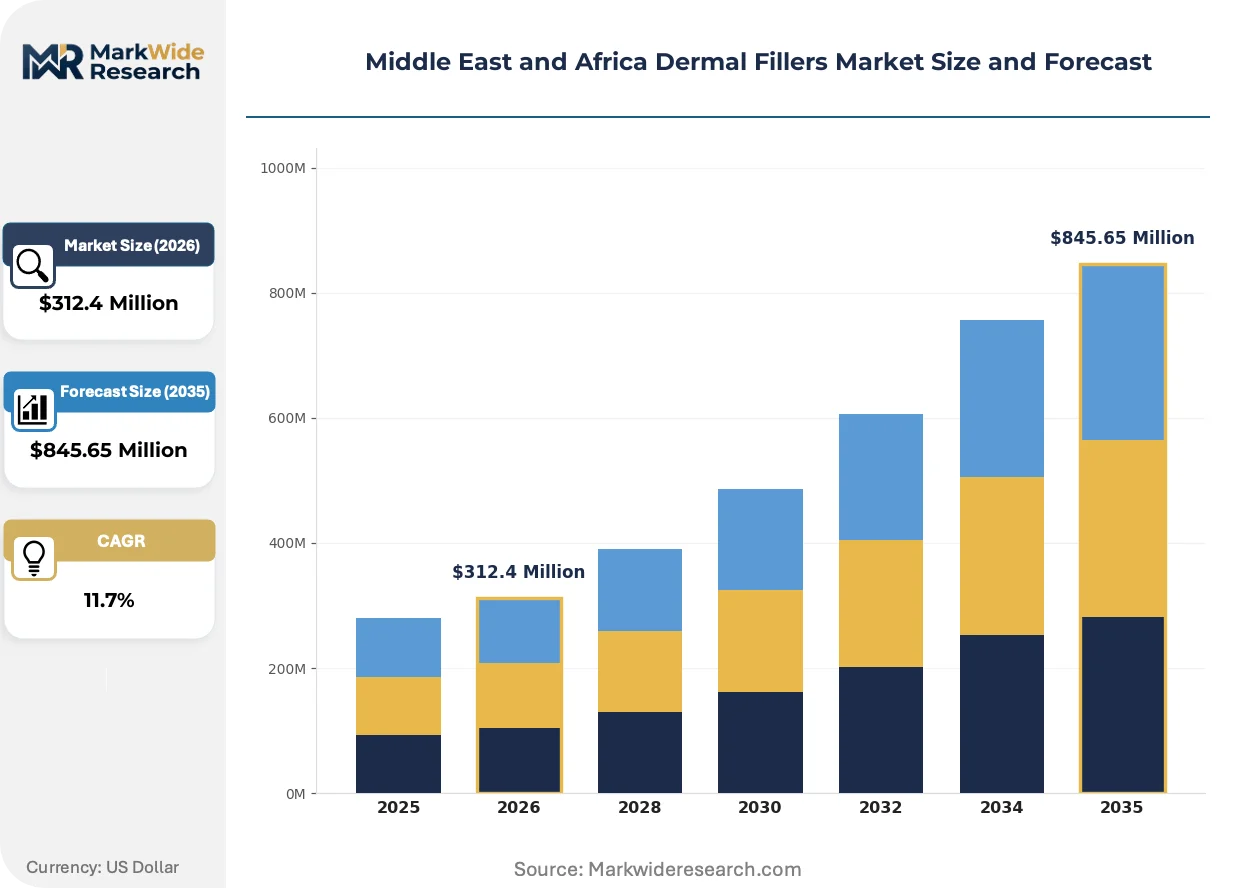
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-lactic Acid, Collagen Application: Facial Contouring, Lip Enhancement, Wrinkle Reduction, Scar Treatment End User: Dermatology Clinics, Beauty Salons, Hospitals, Medical Spas Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Suneva Medical, Prollenium Medical Technologies, AbbVie Inc., Allergan plc, Huadong Medicine Co., Ltd., Galderma, Teoxane Laboratories, Merz Aesthetics, Merz Pharma, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Dermal Fillers Market Shifts & Advancements
Cross-linked gel rheology engineering and regulatory data requirements are reshaping product development priorities across Middle East and Africa aesthetic medicine markets.
Viscoelastic modulus optimization in hyaluronic acid formulations is displacing older concentration-based product differentiation. Dubai dermatology clinics now specify G-prime and G-double-prime values in procurement tenders. This shift compresses margin pools for manufacturers lacking rheological characterization capabilities.
SFDA clinical evidence requirements for injectable medical devices now mandate stability data and biocompatibility testing exceeding prior notification thresholds. Saudi Arabian manufacturers and importers face extended dossier preparation cycles. European CE-marked products with existing technical documentation capture accelerated review slots.
Younger professional women in Gulf Cooperation Council states now initiate aesthetic treatment sequences earlier in the aging trajectory. Medical spa networks respond with subscription-based maintenance protocols replacing episodic intervention models. This pattern concentrates in the UAE aesthetic corridor linking Dubai and Abu Dhabi.
Middle East and Africa Dermal Fillers Market Segmentation
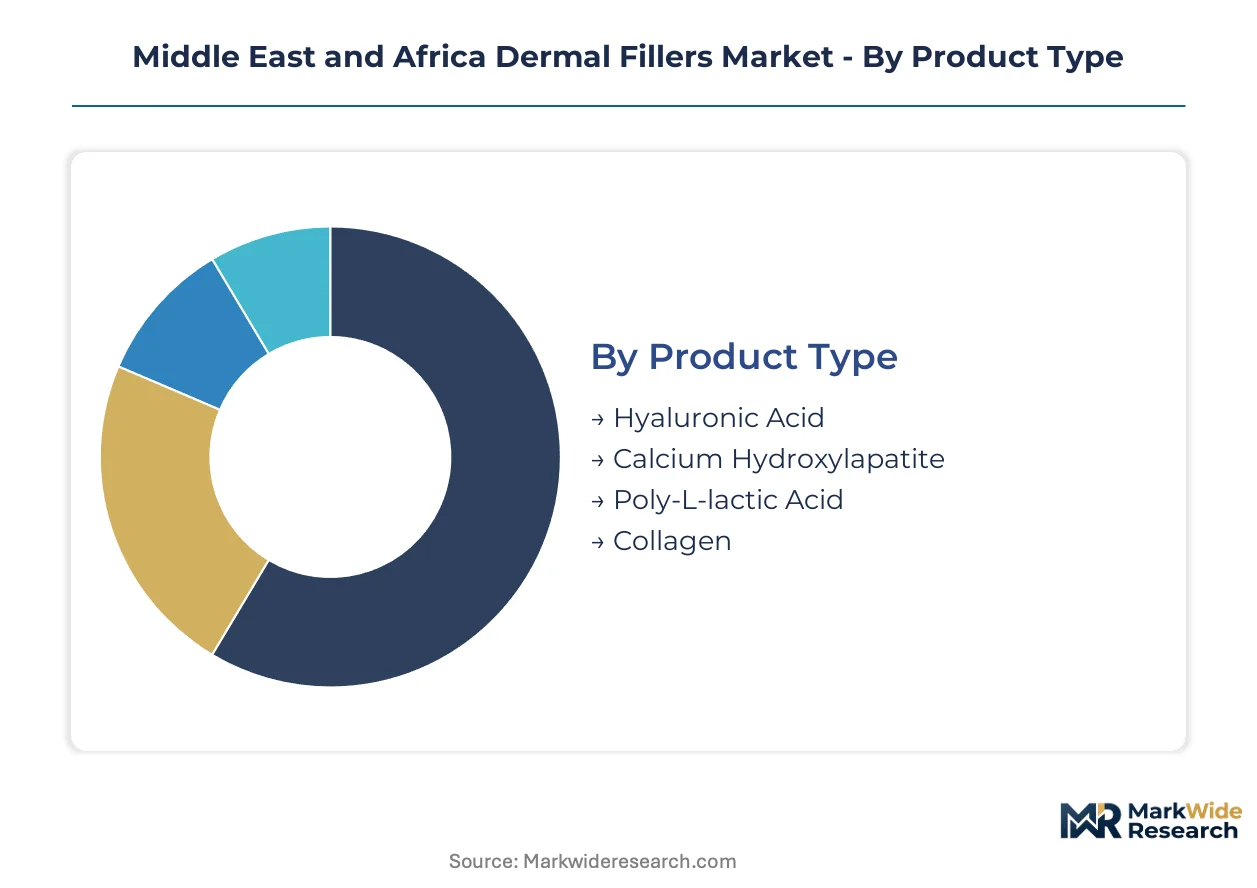
Segmentation in the Middle East and Africa dermal fillers market reveals how regulatory classification, clinical setting, and product reversibility reshape procurement patterns across Gulf Cooperation Council states and South African metropolitan corridors.
Product Type:
Calcium hydroxylapatite and poly-L-lactic acid face intensifying substitution pressure from next-generation hyaluronic acid formulations with engineered viscoelastic profiles.
- Hyaluronic Acid:Cross-linked gel formulations dominate commercial volume through immediate reversibility with hyaluronidase. Dubai and Abu Dhabi dermatology clinics specify G-prime and G-double-prime values in procurement tenders, displacing concentration-based differentiation.
- Calcium Hydroxylapatite:Microsphere suspensions command premium positioning in deeper structural augmentation. Supply concentration in North American and European manufacturing bases limits penetration into Saudi Arabian secondary cities where cold chain infrastructure remains underdeveloped.
- Poly-L-lactic Acid:Biostimulatory particles require multiple treatment sessions, compressing per-procedure economics in Johannesburg medical spa networks.
- Collagen:Bovine and porcine-derived matrices persist in niche applications within Cairo clinic networks despite declining share against synthetic alternatives.
Hyaluronic acid anchors the volume base while calcium hydroxylapatite gains share at the steepest rate among premium structural augmentation protocols.
Application:
Cost tier stratification separates high-margin facial sculpting from commoditized wrinkle management where price competition has compressed margin pools.
- Facial Contouring:Cheek, jawline, and temple volumization procedures concentrate demand in UAE aesthetic corridors. Younger professional women in Gulf Cooperation Council states initiate treatment sequences earlier in the aging trajectory, extending patient lifetime value.
- Lip Enhancement:Vermilion border definition and philtrum column restoration represent the fastest-expanding application segment. Cape Town and Johannesburg dermatology networks report highest procedure frequency among women aged 25-35.
- Wrinkle Reduction:Nasolabial fold and marionette line correction constitutes a mature segment with price-competitive dynamics.
- Scar Treatment:Acne and traumatic scar revision applications remain underpenetrated relative to facial aesthetic procedures across Egyptian medical tourism infrastructure.
Wrinkle reduction retains the largest procedure volume while lip enhancement climbs fastest among younger demographic cohorts.
End User:
Patient migration from hospital-based cosmetic surgery toward outpatient aesthetic medicine is redistributing volume across facility types.
- Dermatology Clinics:Physician-supervised injection protocols anchor premium positioning in Saudi Arabian and UAE markets. SFDA and MOHAP registration requirements favor established clinic networks with compliant procurement systems.
- Medical Spas:Outpatient aesthetic medicine capacity expands across Riyadh and Jeddah, absorbing demand through subscription-based maintenance protocols.
- Hospitals:Traditional cosmetic surgery departments face volume erosion as minimally invasive alternatives capture facial rejuvenation cases.
- Beauty Salons:Non-medical aesthetic venues operate under restricted scope in South Africa where Schedule 4 medicine classification limits dispensing to licensed practitioners.
Dermatology clinics capture the highest value per procedure while medical spas expand capacity most aggressively.
Distribution Channel:
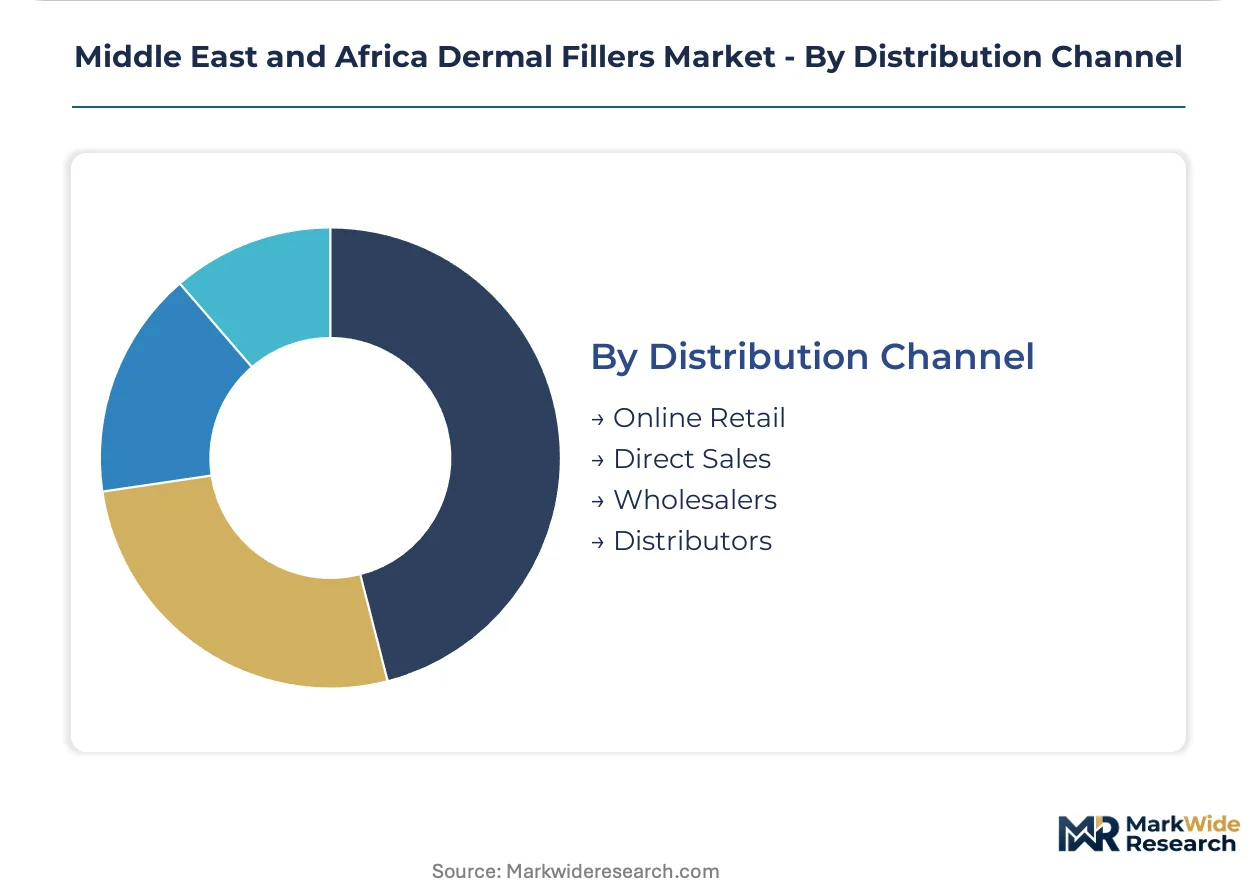
Supply chain configuration directly determines market access speed for manufacturers navigating divergent regulatory pathways across Gulf and African markets.
- Distributors:Authorized medical device distributors with SFDA and MOHAP infrastructure dominate Gulf state market entry. European CE-marked products leverage existing technical documentation for accelerated review slots.
- Direct Sales:Manufacturer-to-clinic relationships concentrate in South African metropolitan markets where legacy Allergan aesthetic franchise recognition sustains brand loyalty.
- Wholesalers:Regional pharmaceutical wholesalers facilitate penetration into interior South African provinces and secondary Saudi cities where cold chain integrity demands complicate hyaluronic acid formulation stability.
- Online Retail:Digital channels face regulatory constraints under UAE and Saudi Arabian medical device regulations prohibiting direct-to-consumer injectable sales.
Distributors control the broadest geographic reach while direct sales relationships deliver the highest margin retention for premium product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European and North American manufacturers ship cross-linked hyaluronic acid formulations to Gulf Cooperation Council distribution hubs. South African metropolitan corridors absorb direct sales volumes from legacy aesthetic franchises.
United Arab Emirates
Dubai and Abu Dhabi aesthetic corridors concentrate demand from younger professional women initiating early intervention protocols. MOHAP streamlined device registration accelerates market entry for CE-marked products. Medical spa networks across the emirates expand subscription-based maintenance models.
Saudi Arabia
Riyadh and Jeddah clinic networks absorb patient volume migrating from hospital-based cosmetic surgery. SFDA clinical evidence requirements mandate stability data and biocompatibility testing for injectable medical devices. The Eastern Province remains underpenetrated relative to western urban centers.
South Africa
Johannesburg and Cape Town dermatology networks report highest lip enhancement procedure frequency among women aged 25-35. The Medicine Control Council classifies certain dermal fillers as Schedule 4 medicines, restricting dispensing to licensed practitioners. Cold chain integrity demands complicate distribution into interior provinces.
Egypt
Cairo and Alexandria clinic infrastructure remains underpenetrated relative to Gulf aesthetic corridor density. The national pharmaceutical regulator applies medical device standards that lag Gulf harmonization efforts. Medical tourism positioning attracts regional patients seeking cost-competitive facial contouring procedures.
Israel
Tel Aviv metropolitan aesthetic medicine practices pioneer telemedicine consultation integration for pre-assessment workflows. The national health regulator maintains stringent import licensing for injectable biologics. Private clinic networks concentrate along the coastal plain.
Middle East and Africa Dermal Fillers Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier capabilities and Gulf market access infrastructure. The vendor base fragments across manufacturers holding European CE documentation and those building SFDA clinical evidence portfolios. Three archetypes dominate: multinational pharmaceutical incumbents with legacy aesthetic franchises, specialized dermal filler pure-plays with rheological engineering capabilities, and regional distributors with MOHAP registration infrastructure. Competitive moves concentrate on M&A for regulatory dossier acquisition and direct clinic network partnerships.
Among Swiss and German-based aesthetic specialists, Galderma, Merz Aesthetics, and Teoxane Laboratories exemplify the premium formulation tier. Galderma occupies a position anchored in hyaluronic acid portfolio breadth across Gulf Cooperation Council states. Merz Aesthetics sits within the specialized facial volume restoration segment. Teoxane Laboratories represents the rheological characterization frontier where Dubai procurement tenders now specify G-prime and G-double-prime values.
| Leading Market Players |
|---|
| Suneva Medical |
| Prollenium Medical Technologies |
| AbbVie Inc. |
| Allergan plc |
| Huadong Medicine Co., Ltd. |
| Galderma |
| Teoxane Laboratories |
| Merz Aesthetics |
| Merz Pharma |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with Gulf distributors lock in hyaluronic acid supply access while anchoring price visibility for European manufacturers navigating SFDA and MOHAP registration timelines. These arrangements concentrate procurement power among clinic networks with compliant cold chain infrastructure across Dubai and Abu Dhabi.
Pricing Analysis
Next-generation hyaluronic acid formulations with engineered viscoelastic profiles command 40-60% premiums over prior-generation concentration-based products, while economy-tier collagen matrices face persistent price erosion. Three-tier pricing structure across premium structural augmentation, standard facial contouring, and economy wrinkle correction segments reflects certification grade and rheological characterization capabilities. Cost compression in the mature wrinkle reduction tier stems from commoditized hyaluronic acid sourcing and medical spa network consolidation. Medical spas exhibit highest price sensitivity due to subscription-based maintenance protocol economics, while Dubai dermatology clinics prioritize G-prime specifications over unit cost.
Supply Chain Analysis
Inventory cycles for cross-linked gel formulations extend to 8-12 weeks in Saudi Arabian secondary cities where cold chain integrity demands complicate last-mile distribution. Manufacturing concentration in Switzerland, Germany, and France feeds Gulf Cooperation Council distribution hubs, while South African metropolitan corridors draw direct shipments from legacy European suppliers. Sodium hyaluronate raw material, cross-linking agents, and sterilization packaging constitute critical input dependencies. Single-source vulnerability in calcium hydroxylapatite microsphere supply from North American bases exposes premium structural augmentation lines to tariff and logistics disruption. Distribution runs through authorized medical device distributors with SFDA and MOHAP infrastructure dominating Gulf state market entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa dermal fillers market sits in early-cycle expansion as younger professional women in Gulf Cooperation Council states initiate aesthetic treatment sequences earlier in the aging trajectory, extending patient lifetime value and subscription protocol adoption.
For Market Incumbents: Consolidate clinic network partnerships in the UAE aesthetic corridor to defend against pure-play rheological engineering specialists capturing procurement tenders with G-prime specification capabilities. Deepen backward integration into hyaluronic acid fermentation capacity to secure raw material cost position as European supply faces biopharma sector competition. Prioritize SFDA clinical evidence dossier expansion ahead of anticipated registration harmonization with European CE marking reciprocity. For New Entrants and Emerging Players: Subscription-based maintenance protocol under-penetration in Egyptian medical tourism infrastructure offers immediate white-space access with lower competitive density than Gulf markets. Target Cairo and Alexandria clinic networks with cost-competitive hyaluronic acid formulations positioned for facial contouring procedures attracting regional medical tourists. Deploy telemedicine consultation integration as a differentiated patient acquisition channel to reduce customer acquisition costs versus established distributor-dependent incumbents. For Investors and Strategic Acquirers: Regional distributors with MOHAP registration infrastructure and established Gulf clinic network relationships represent the highest-conviction acquisition archetype for exposure to accelerated market entry timelines. Monitor CE marking reciprocity negotiation progress between Gulf health authorities and European notified bodies as the critical inflection signal for competitive entry dynamics and valuation multiple expansion across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Clinical Evidence Dossier Expansion | Accelerated review slots for European manufacturers with existing stability data and biocompatibility testing documentation. |
| Telemedicine Consultation Integration | Reduces patient acquisition costs for Johannesburg and Cape Town dermatology networks competing with medical spa expansion. |
| Backward Integration into Hyaluronic Acid Fermentation | Captures raw material cost position as biopharma sector demand tightens sodium hyaluronate supply from European bases. |
| Subscription-Based Maintenance Protocol Launch | Extends patient lifetime value among younger professional women in Dubai and Abu Dhabi aesthetic corridors. |
| Egyptian Medical Tourism Infrastructure Partnership | Positions cost-competitive facial contouring services for regional patients seeking alternatives to premium Gulf pricing tiers. |
Research Methodology
Operator-level perspectives from dermatology clinic directors, medical spa network operators, biomedical procurement managers at Gulf hospital systems, and regulatory affairs specialists at SFDA and MOHAP anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation from European Medicines Agency device registration databases, SFDA medical device guidance documents, South African Medicine Control Council Schedule 4 medicine classifications, and Gulf customs trade data. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Sensitivity analysis across hyaluronic acid concentration tiers, viscoelastic modulus specifications, and regional regulatory pathway scenarios informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application, end-user facility category, and distribution channel structure. CAGRs derived from procedure volume growth rates adjusted for per-procedure pricing trajectory assumptions. Key forecast inputs incorporated medical spa network expansion capacity, CE marking reciprocity negotiation status, and cold chain infrastructure development in secondary Saudi cities.
Forecasts assume regulatory continuity in SFDA, MOHAP, and South African Medicine Control Council regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Global Aesthetic Fillers Market