
 Assembly Trays Market | 2026-2036
Assembly Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Assembly Trays Market Intelligence
The capital investment gap between high-volume commodity tray production and specialized, custom-molding capabilities is rotating the competitive landscape. Molded Fiber Glass Tray Company leverages its expertise in composite materials for durable, reusable solutions. Conductive Containers, Inc. specializes in electrostatic discharge (ESD) safe trays essential for the electronics sector. Meanwhile, LewisBins+ competes on a broad portfolio of standardized plastic bins and trays for general industrial use.
Assembly trays are purpose-built containers designed to securely hold, orient, and transport components through manual or automated manufacturing processes. These trays are often thermoformed or injection-molded from materials like polypropylene or polyethylene. They feature custom-designed pockets engineered to fit specific parts, preventing damage and streamlining assembly. Plastic trays dominate the market due to their low cost and design flexibility, particularly in electronics and automotive applications.
Regulatory frameworks directly influence material selection and product design. The US FDA's requirements for food-contact materials govern trays used in food packaging, while Europe's REACH regulation restricts certain chemicals in plastics. In China, GB standards for material safety and performance are critical for market access in industrial sectors. Stakeholders must now decide whether to invest in advanced polymers and automation-compatible designs or focus on high-volume, standardized offerings.
Market Dynamics
The push for full-scale automation in electronics and automotive assembly is the central force shaping the assembly tray market. This drive necessitates trays that are not merely containers but precise instruments engineered for robotic handling, dimensional accuracy, and material-specific properties like ESD safety.
Growth Catalysts
- Component Miniaturization:The continuous reduction in the size of electronic components, particularly in semiconductors and micro-electromechanical systems (MEMS), requires highly precise, custom-molded trays with electrostatic discharge (ESD) safe properties to prevent damage during automated handling.
- Automation Standards:The adoption of standardized robotic systems in manufacturing facilities across Germany and Japan is creating demand for trays with uniform dimensions, fiducial marks, and features that ensure consistent interfacing with automated equipment.
- Advanced Manufacturing Hubs:Demand is concentrating in high-tech industrial zones in South Korea and Taiwan, where massive investment in semiconductor fabrication and electronics assembly lines creates a large, recurring need for specialized process and shipping trays.
Market Restraints
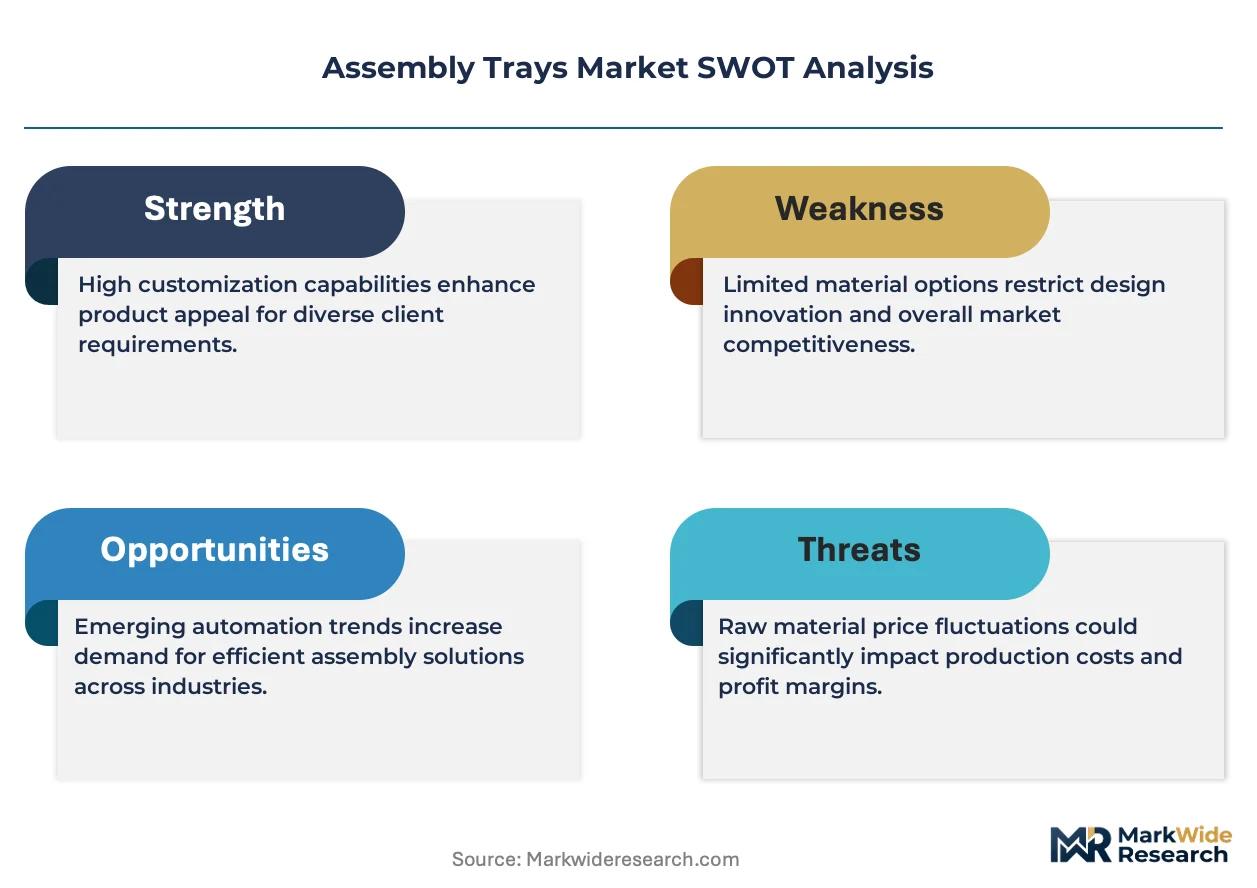
- Raw Material Price Volatility:Fluctuations in the cost of petroleum-based polymers, such as polypropylene and polyethylene, directly impact tray manufacturing costs and profit margins, making long-term price stability difficult for producers.
- High Tooling Costs:The significant upfront investment and long lead times required to design and fabricate custom injection molds act as a barrier, particularly for smaller-volume, highly specialized applications in niche industries.
- Substitution from Generic Solutions:For less sensitive, non-automated assembly tasks, lower-cost alternatives like standard-sized bins, corrugated boxes with dividers, or foam inserts can serve as adequate substitutes, limiting the market for custom-engineered trays.
Strategic Opportunities
- Sustainable Materials:Developing trays from biodegradable polymers or recycled plastics presents an opportunity to meet corporate sustainability mandates and comply with environmental regulations like the EU Green Deal, appealing to environmentally conscious customers.
- Medical Device and Pharma Expansion:The medical device manufacturing sector requires sterile, traceable, and often single-use trays for assembly and packaging, representing an underpenetrated market with stringent quality requirements and high-value potential.
- Smart Tray Integration:Embedding RFID tags or QR codes directly into trays enables real-time tracking and data collection within smart factories, creating a new value proposition centered on logistics efficiency and Industry 4.0 integration.
Industry Challenges
- Capital Investment for Automation:Upgrading production lines with high-precision injection molding machines and thermoforming equipment capable of handling advanced polymers and complex geometries requires significant capital expenditure.
- Fragmented Regulatory Compliance:Manufacturers must navigate a complex web of international material safety standards, such as adhering to Europe's REACH framework for chemicals and China's GB standards for plastics, increasing testing and documentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assembly Trays Market |
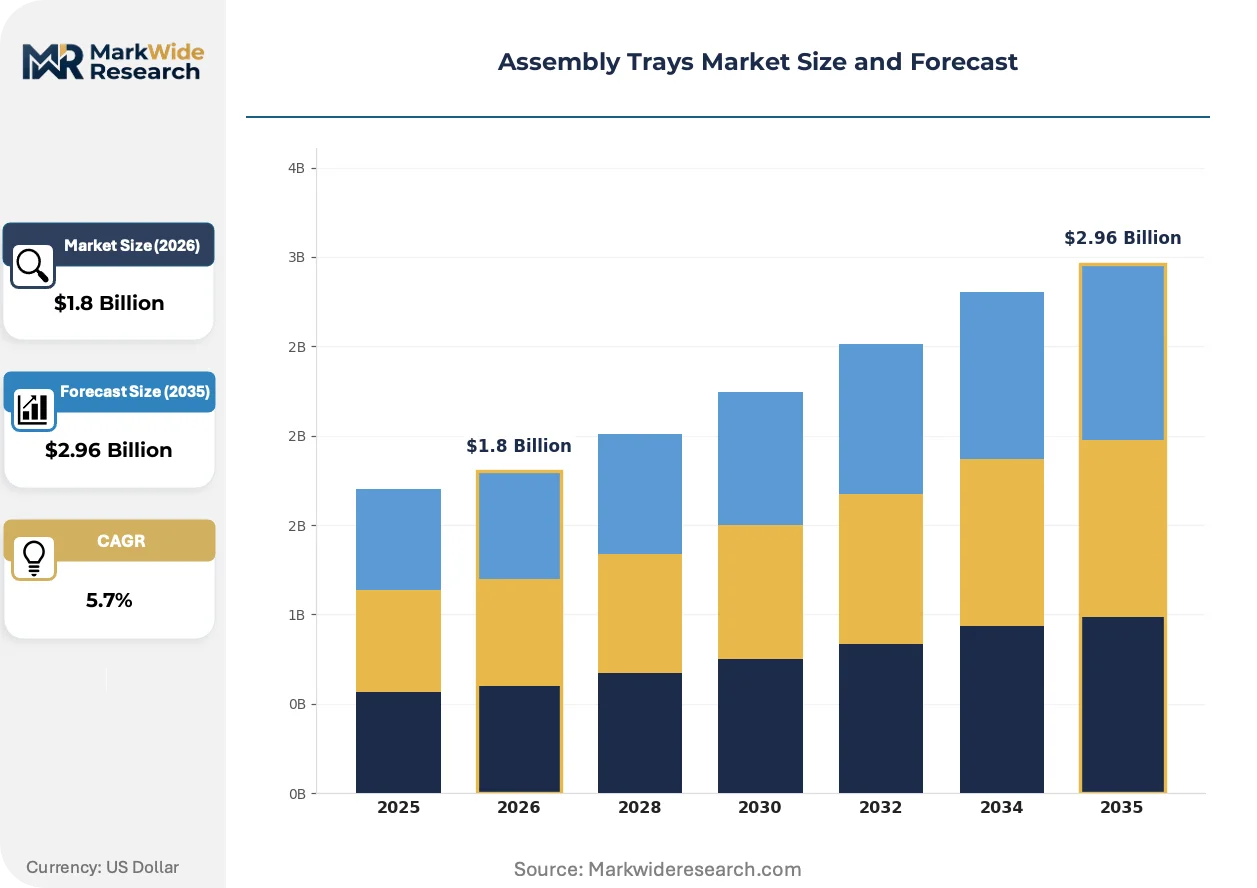
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Trays, Metal Trays, Wood Trays, Disposable Trays End User: Electronics Manufacturers, Automotive Assemblers, Food Packaging, Medical Device Firms Tray Size: Small, Medium, Large, Custom Sizes Material: Polyethylene, Polypropylene, Aluminum, Others |
| Companies Covered | Molded Fiber Glass Tray Company, Impala Plastics, LewisBins+, Conductive Containers, Inc, W.W. Grainger, Inc., Engineered Components & Packaging, LLC, Gilmore Kramer Co, Z-Mar Technology, Inc., Production Automation Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assembly Trays Market Strategic Shifts & Innovations
The evolution of assembly trays is defined by a shift from passive containers to active enablers of factory automation. Performance attributes like dimensional stability, material purity, and electrostatic discharge protection are now primary design drivers, especially within precision manufacturing sectors.
Advanced polymer development, including carbon-fiber-reinforced composites and permanently static-dissipative plastics, delivers superior durability and ESD protection. Electronics and aerospace manufacturers are adopting these materials for handling fragile and high-value components. This trend is bifurcating the market, separating high-performance, custom-molded solutions from high-volume, standard polyethylene or polypropylene trays used in general assembly.
Europe's REACH regulation imposes strict controls on chemical substances used in manufacturing, including those within plastic polymers. This framework forces material suppliers and tray molders to verify the absence of restricted chemicals, impacting material selection. Consequently, producers targeting the EU electronics and medical device markets are reformulating products and re-qualifying their raw material supply chains to ensure full compliance.
A clear shift in buying behavior shows customers demanding integrated handling solutions rather than just physical trays. This model displaces traditional component sales with partnerships where suppliers provide design-for-automation services, simulation, and validation. The trend is most pronounced in Germany's automotive sector and South Korea's semiconductor fabrication plants, where seamless robotic integration is a primary purchasing criterion.
Assembly Trays Market Segmentation
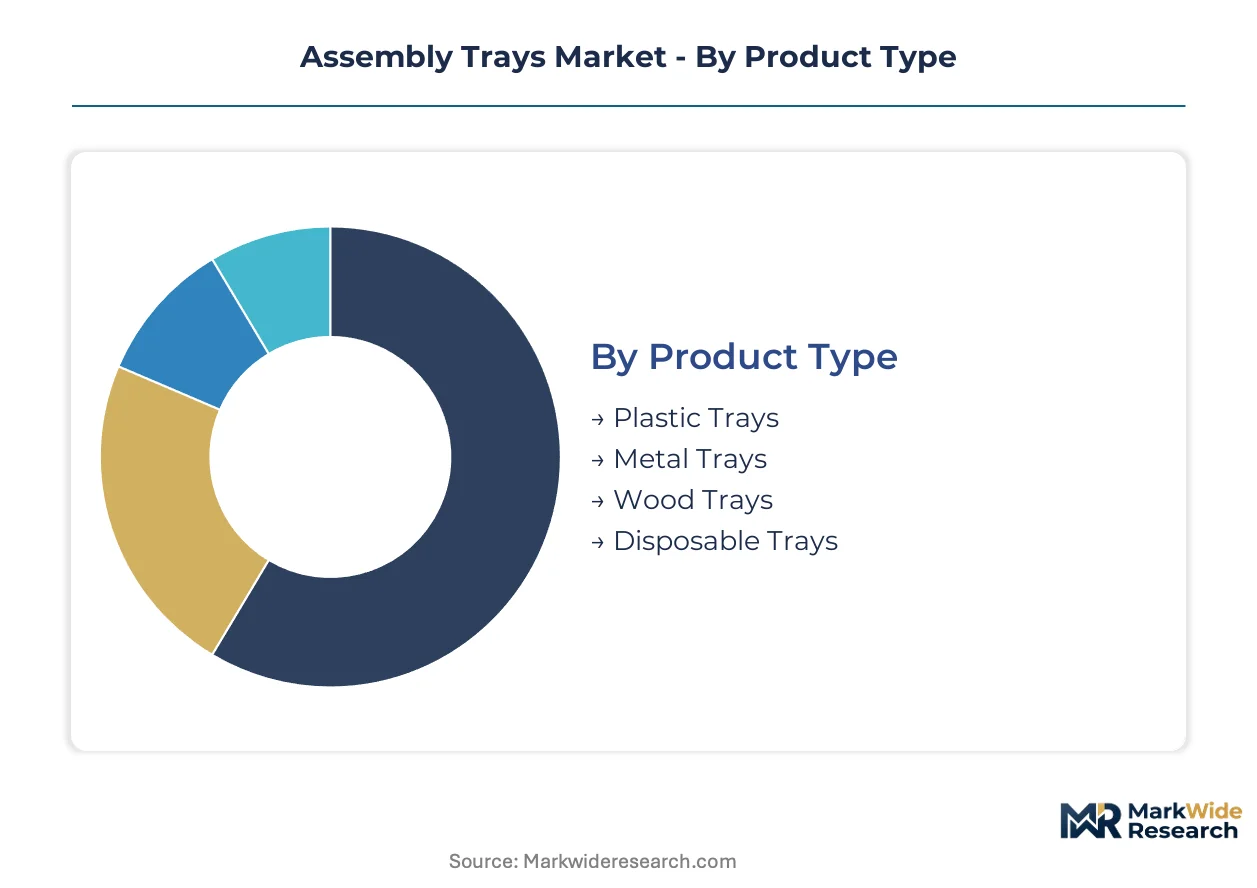
Understanding the varied requirements across industrial applications is critical for dissecting the assembly trays market. This segmentation analysis illuminates the diverse product specifications and end-user demands that shape material selection, design complexity, and market dynamics for these essential manufacturing components.
Product Type:
The product type segmentation highlights varying degrees of substitution pressure, with standardized alternatives posing a threat to custom solutions in certain applications.
- Plastic Trays:These are thermoformed or injection-molded from polymers such as polypropylene or polyethylene, offering design flexibility and cost efficiency. Plastic trays dominate electronics and automotive applications due to their adaptability and ability to be made ESD-safe.
- Disposable Trays:Designed for single-use, these trays are often made from pulp, thin plastics, or biodegradable materials. They are critical for medical device assembly and food packaging, where sterility and contamination control are paramount.
- Metal Trays:Durable, often constructed from stainless steel or aluminum. These trays are used in high-temperature environments or for heavy-duty industrial components requiring robust handling.
- Wood Trays:Traditional and sturdy, these trays are typically employed for less sensitive, heavier components. Their use is less prevalent in modern precision manufacturing compared to plastic or metal.
Plastic Trays anchor the volume base while Disposable Trays gain share at the steepest rate.
End User:
End-user segments exhibit distinct cost-tier sensitivities, influencing material selection and design complexity for assembly trays.
- Electronics Manufacturers:These firms require highly precise, ESD-safe trays engineered for miniaturized components, such as semiconductors and micro-electromechanical systems (MEMS). Demand concentrates in South Korea and Taiwan, driven by continuous innovation in device fabrication.
- Medical Device Firms:This sector demands sterile, traceable, and often single-use trays to maintain product integrity and comply with strict regulatory frameworks like the US FDA and Europe's MDR. High-value potential exists for specialized, compliant solutions.
- Automotive Assemblers:Utilize robust, automation-compatible trays. These support the high-volume production of vehicle components and sub-assemblies, particularly in advanced manufacturing hubs like Germany.
- Food Packaging:This segment requires FDA-compliant, food-grade materials. Trays ensure hygiene and safety for packaged food products, adhering to strict material safety standards.
Electronics Manufacturers drive substantial volume, while Medical Device Firms present high-value niche opportunities.
Tray Size:
Tray size directly correlates with application precision and component scale, dictating manufacturing complexity.
- Custom Sizes:These trays are engineered precisely for specific components and automated assembly lines, often featuring intricate pockets and fiducial marks. They are essential for precision fitting and robotic integration in advanced manufacturing facilities across Germany and Japan.
- Small:Designed for micro-components and delicate parts, these trays are critical for semiconductor and MEMS fabrication processes where precision and ESD protection are paramount. Demand is high in advanced manufacturing hubs like South Korea.
- Medium:Accommodates a broad range of standard components. These trays are common in general industrial assembly and logistics for a variety of manufacturing tasks.
- Large:Used for bulk handling of larger parts. These robust trays support heavy-duty applications in automotive and general machinery assembly.
Custom Sizes attract premium demand, while Small trays are expanding most quickly in high-tech sectors.
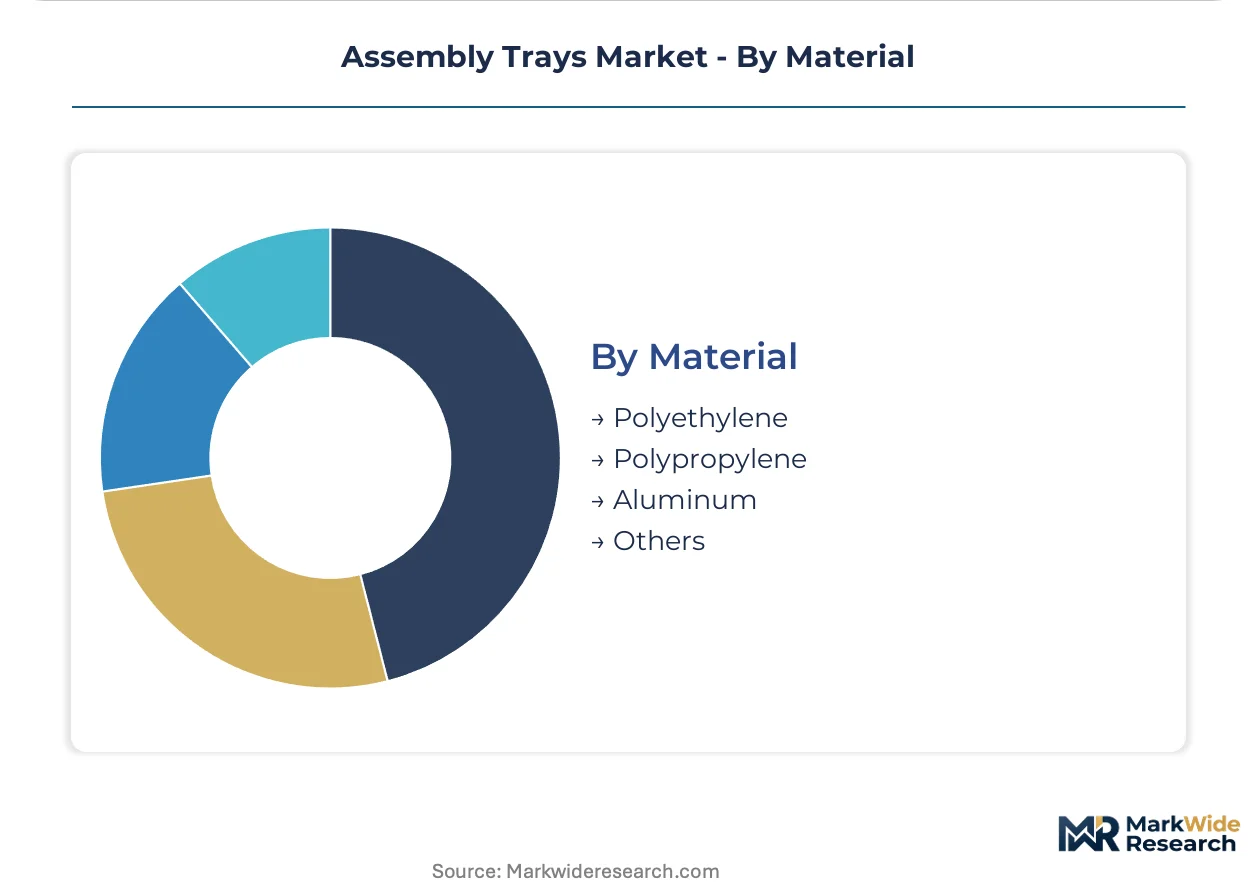
Material:
Material segmentation reveals supply concentration dynamics, with petroleum-based polymers forming the core of the market's raw material base.
- Polypropylene:This versatile polymer is often used for rigid, thermoformed, or injection-molded trays due to its chemical resistance and ability to be made permanently static-dissipative. It is favored in electronics and automotive for its performance attributes.
- Polyethylene:A flexible and cost-effective plastic, polyethylene is widely adopted for general-purpose trays due to its durability, impact resistance, and ease of molding. It serves a broad range of industrial applications.
- Aluminum:This lightweight and corrosion-resistant metal is preferred for high-temperature applications or where robust structural integrity and cleanliness are required. It finds use in specialized industrial settings.
- Others:This category includes specialized composites, such as carbon-fiber-reinforced materials, and biodegradable polymers. These address niche requirements for extreme performance or corporate sustainability mandates.
Polypropylene and Polyethylene are subject to evolving chemical regulations, influencing material reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for assembly trays varies significantly, with buyers in high-precision sectors exhibiting less price sensitivity for specialized solutions. Conversely, general industrial users prioritize cost efficiency for standardized offerings. This bifurcation influences material selection and design complexity across different regions.
South Korea
South Korea's robust semiconductor and electronics manufacturing drives demand for precise, ESD-safe trays. The nation's Ministry of Food and Drug Safety (MFDS) regulates material safety for medical device applications. Major technology hubs like Seoul and Gyeonggi Province require continuous innovation in process and shipping trays.
Taiwan
Taiwan's dominance in semiconductor fabrication necessitates advanced custom-molded trays for delicate components. Local Environmental Protection Administration (EPA) regulations guide sustainable material development for plastics. Science parks in Hsinchu and Tainan concentrate demand for automation-compatible trays.
Germany
German automotive and advanced manufacturing sectors require robust, automation-compatible trays. Europe's REACH regulation significantly impacts material selection for plastic polymers. Industrial clusters in Bavaria and Baden-Württemberg integrate smart tray solutions for enhanced logistics.
United States
The United States electronics and medical device industries create strong demand for sterile and ESD-safe trays. The US FDA's stringent requirements dictate specific product designs. Silicon Valley and Boston's biotech corridor are key areas for specialized tray procurement.
China
China's expansive electronics manufacturing and automotive assembly industries generate significant volume demand. GB standards for material safety are critical for market access. Production centers in the Yangtze River Delta and Pearl River Delta drive the need for both standardized and custom-engineered tray solutions.
Assembly Trays Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the assembly trays market. The competitive landscape shows a bifurcation between highly specialized solution providers and high-volume commodity manufacturers. Strategic archetypes include composite material specialists, electrostatic discharge (ESD) safety innovators, and broad industrial suppliers. Companies are pursuing strategic partnerships for automation integration, expanding capacity for advanced polymer molding, and diversifying portfolios to capture niche applications.
Specialists in composite materials and durable solutions include Molded Fiber Glass Tray Company, exemplifying expertise in high-performance applications. This firm caters to sectors demanding robust, reusable options. Meanwhile, Conductive Containers, Inc. represents the niche for electrostatic discharge (ESD) safe trays, crucial for sensitive electronics manufacturing and automated handling. LewisBins+ occupies a position among suppliers offering a broad portfolio of standardized plastic bins and trays for general industrial use, emphasizing versatility and cost-efficiency. These companies collectively illustrate the varied strategic focus across material science, specialized protection, and general utility within the market.
| Leading Market Players |
|---|
| Molded Fiber Glass Tray Company |
| Impala Plastics |
| LewisBins+ |
| Conductive Containers, Inc |
| W.W. Grainger, Inc. |
| Engineered Components & Packaging, LLC |
| Gilmore Kramer Co |
| Z-Mar Technology, Inc. |
| Production Automation Corporation |
| Others |
Cost & Logistics Intelligence
Large-scale injection molding capacity, particularly for commodity plastic trays, drives cost efficiencies that establish competitive price floors. This scale also influences supply concentration and material sourcing strategies within the assembly tray market.
Pricing Analysis
Integrated handling solutions and design-for-automation services represent a high-value revenue tier for specialized assembly tray providers. Pricing models often shift from transactional per-unit sales to value-based or project-based engagements for custom solutions. Price differentiation stems from the customization level required for specific components and the advanced material properties like ESD safety or FDA compliance. Pricing pressure stems from raw material price volatility, particularly for petroleum-based polymers. High-precision electronics and medical device firms exhibit the lowest price sensitivity, while general industrial users prioritize cost efficiency for standardized offerings.
Supply Chain Analysis
Long lead times for custom injection mold fabrication dictate strategic inventory management and advance planning for specialized tray orders. The supply chain for assembly trays draws heavily from manufacturing hubs in China, South Korea, and Taiwan. Key raw material dependencies include polypropylene, polyethylene, and specialized composites. Raw material price volatility, especially for petroleum-based plastics, represents a significant structural risk across the supply chain. Distribution for high-value, custom-engineered trays predominantly runs through direct partnerships with manufacturers to ensure seamless integration into automated assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The assembly trays market presents a fragmentation opportunity, driven by the demand-side shift towards highly specialized, automation-compatible solutions for precision manufacturing.
For Market Incumbents: Compound existing expertise in advanced materials, such as carbon-fiber-reinforced composites, to solidify leadership in high-performance segments. Expand capacity for advanced polymer molding in strategic geographies like Germany and South Korea. Deepen design-for-automation services and simulation capabilities to offer integrated handling solutions, mitigating competitive threats from generic alternatives. Invest in certification processes for evolving regulatory frameworks like Europe's REACH and the US FDA to maintain market access and premium positioning.
For New Entrants and Emerging Players: Lead with specialized material innovations or smart tray technologies to target underpenetrated, high-value niches. Focus on medical device manufacturing, which demands sterile, traceable, and often single-use trays, presenting a significant white-space opportunity. Develop sustainable material alternatives, such as biodegradable polymers or recycled plastics, to align with corporate sustainability mandates. A go-to-market angle centered on rapid prototyping and regulatory compliance for specific applications can accelerate market penetration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized solution providers with strong intellectual property in advanced materials or automation integration. Long-term viability is strong for firms enabling Industry 4.0 through smart tray integration and data analytics. Identify acquisition targets that offer proprietary ESD-safe materials or possess deep expertise in custom-molding complex geometries for miniaturized components. The signal to watch is the adoption rate of RFID or QR code integration in high-volume manufacturing lines, indicating readiness for smart factory ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Advanced Polymer Molding Capacity | Increases production scale for high-performance, custom-molded trays for electronics manufacturing. |
| Develop Sustainable Tray Materials | Addresses corporate sustainability mandates and complies with environmental regulations, attracting environmentally conscious customers. |
| Form Automation Integration Partnerships | Enables seamless robotic handling and data exchange, crucial for Industry 4.0 adoption in automotive assembly. |
| Pursue Medical Device Certifications | Unlocks high-value opportunities in the medical sector requiring sterile, traceable, and FDA-compliant packaging solutions. |
| Integrate Smart Tracking Technologies | Enhances logistics efficiency and real-time data collection within smart factories, creating new value propositions. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved discussions with production managers at electronics firms, procurement specialists at automotive OEMs, R&D directors at material suppliers, and regulatory compliance officers. This was triangulated with secondary data from industry association reports, government trade statistics, and regulatory body publications from the US FDA, Europe's REACH, and China's GB standards, ensuring a robust bottom-up and top-down approach.
The analytical framework projected market dynamics across the analysis window, segmenting by product type, end user, tray size, and material composition. Compound Annual Growth Rates were derived from historical trends, component miniaturization rates, and projected automation adoption curves within key manufacturing hubs. Industry-specific forecast inputs included polymer price indices and capital expenditure trends in semiconductor fabrication and automotive assembly, providing a granular view of market evolution.
Forecasts assume regulatory continuity in US FDA, Europe's REACH, and China's GB standards; material policy shifts would require re-modeling. This analysis acknowledges potential revisions due to raw material price volatility or geopolitical trade shifts affecting key manufacturing regions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Membrane Boxes Market
Packaging Containers
Telescope Box Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Can Holders Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Custom Boxes Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Portion Packs Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Shipping Mailers Market