
 Shipping Mailers Market | 2026-2036
Shipping Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Mailers Market Analytics
Aftermarket service revenue from mailer customization and print-on-demand branding is narrowing as converters integrate these capabilities directly into production workflows. Sealed Air Corporation leverages its automated packaging systems to control high-volume e-commerce channels. Mondi Group anchors European demand through kraft paper specialization and certified recycling streams. Smurfit Kappa Group dominates corrugated hybrid mailers with integrated fulfillment partnerships.
Shipping mailers are protective enclosures manufactured from polyethylene film, laminated kraft paper, or bubble-lined composites, typically sealing via self-adhesive strips and designed for single-use parcel transit with dimensional stability below two kilograms. Poly mailers lead volume due to moisture resistance and freight density advantages, though paper mailers represent the fastest-growing category as the EU Green Deal and PPWR mandate recyclability thresholds. Custom sizing captures premium margin pools from subscription box services and branded unboxing experiences, while small-format bubble mailers sustain demand in electronics and pharmaceutical last-mile delivery.
The EU Packaging and Packaging Waste Regulation (PPWR) and FDA food-contact substance notifications for mailers used in meal-kit delivery shape material selection and migration testing protocols across the value chain. REACH compliance on adhesive chemistries and California's SB 54 extended producer responsibility framework force reformulation investments in plastic-based segments. Stakeholders must monitor how fragmented national enforcement timelines for recycled content mandates reshape supplier qualification criteria and regional sourcing decisions.
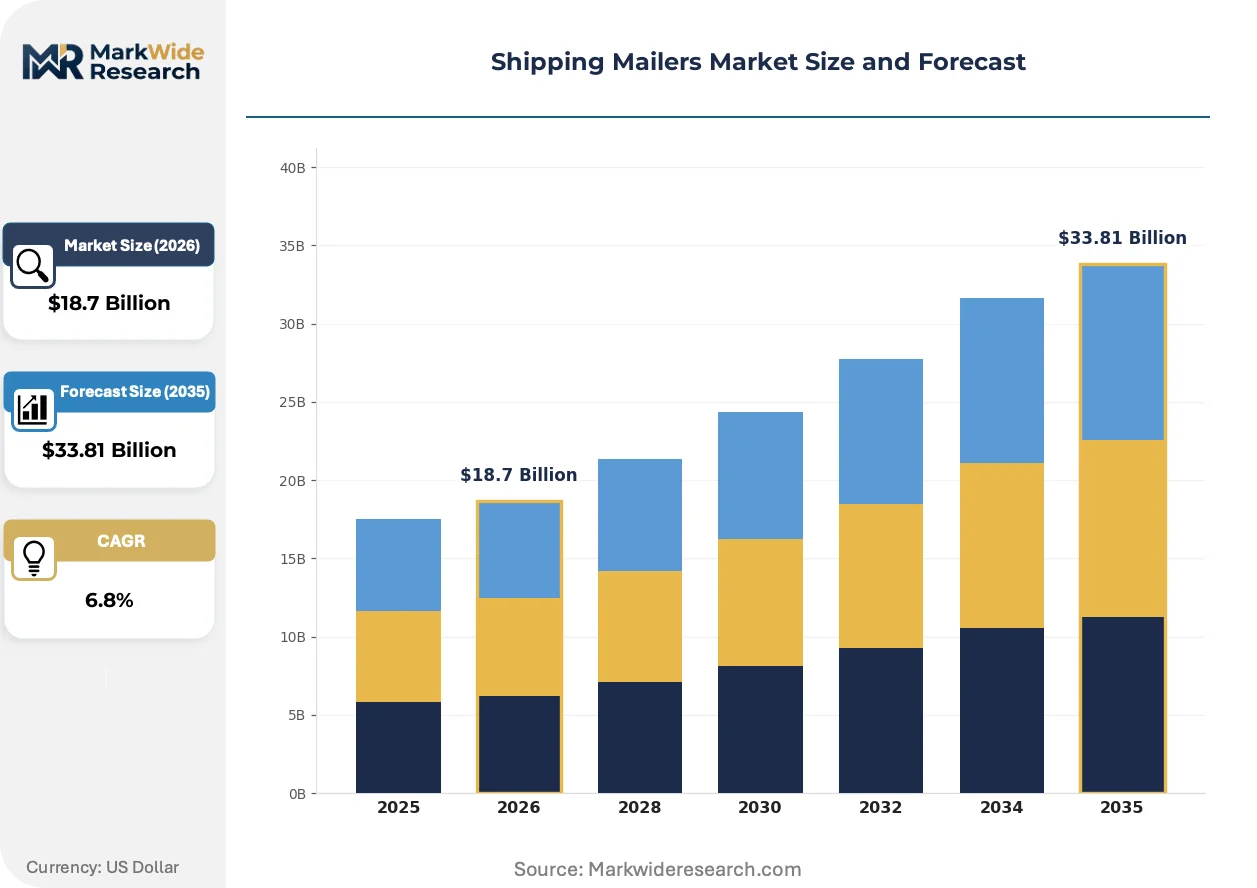
Market Dynamics
The EU Packaging and Packaging Waste Regulation (PPWR) is compressing virgin plastic demand while redirecting capital toward fiber-based production lines and certified recycling infrastructure. This regulatory pivot is restructuring supplier qualification criteria across European fulfillment networks.
Growth Catalysts
- E-commerce fulfillment networks:Third-party logistics providers in Germany and the Netherlands are standardizing mailer specifications across centralized distribution hubs, creating volume concentration that favors automated packaging system integration.
- REACH compliance on adhesive chemistries:Reformulation investments in water-based and bio-derived sealants are opening certified product lines for meal-kit and pharmaceutical last-mile delivery applications.
- California SB 54 extended producer responsibility framework:The state's plastic pollution reduction mandates are accelerating post-consumer recycled content adoption among US-based subscription box services and direct-to-consumer brands.
Market Restraints
- Kraft pulp price volatility:Fiber-based mailer converters face margin compression when Nordic pulp supply tightens during quarterly maintenance cycles at Scandinavian mills.
- Regional sorting infrastructure gaps:Eastern European markets lack optical separation capacity for laminated paper-plastic hybrid formats, limiting compliant product rollout beyond Western EU member states.
- Performance ceiling of fiber alternatives:Kraft paper mailers fail moisture resistance thresholds for electronics and pharmaceutical cold-chain transit, preserving polyethylene demand in premium protective segments.
Strategic Opportunities
- Polish and Romanian e-commerce penetration:Underdeveloped fulfillment infrastructure in these markets creates first-mover positioning for converters offering EU-compliant mailer formats with localized print-on-demand branding.
- Dual carbon goals in China:The country's national emissions targets are forcing domestic parcel platforms to pilot fiber-based alternatives, opening technology licensing partnerships for European kraft specialists.
- Print-on-demand integration:Converters embedding digital printing directly into production workflows are capturing subscription box customization revenue previously held by aftermarket service providers.
Industry Challenges
- Migration testing protocols:FDA food-contact substance notifications for meal-kit mailers require extended laboratory validation timelines that delay product launches by 8-14 months.
- Legacy adhesive system replacement:Hot-melt equipment retrofits for bio-based sealants demand capital outlays that mid-volume converters struggle to finance without green bond access.
- Fragmented national enforcement timelines:Recycled content mandates across EU member states lack synchronization, complicating pan-European product standardization and inventory pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Mailers Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Poly Mailers, Bubble Mailers, Paper Mailers, Couriers Material: Plastic, Kraft Paper, Recycled Materials, Aluminum Size: Small, Medium, Large, Custom End User: E-commerce, Retail, Logistics, Manufacturing |
| Companies Covered | Sealed Air Corporation, Mondi Group, International Paper, Pregis Corporation, Smurfit Kappa Group, DS Smith Plc, ProAmpac LLC, Intertape Polymer Group Inc., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Mailers Market Evolving Landscape
Material science advances and regulatory stringency are converging to collapse the traditional segmentation between protective performance and circular design. This compression is forcing simultaneous innovation across substrate chemistry, adhesive formulation, and end-of-life processing infrastructure.
Water-activated tape and fiber-based cushioning laminates are rendering obsolete conventional bubble-lined polyethylene mailers in European electronics fulfillment. German consumer electronics retailers and Dutch pharmaceutical distributors are piloting these formats at scale. The technology is rendering obsolete established supply relationships with Asian bubble film extruders who lack kraft lamination capability.
The EU Green Deal's packaging recyclability thresholds are mandating mono-material construction and standardized dimensions across national borders. Industrial consequence includes disqualification of multi-layer laminates from extended producer responsibility fee discounts. Small-format bubble mailers for electronics and subscription boxes face the steepest compliance redesign costs, with converters accelerating investment in paper-based cushioning alternatives.
Subscription box services are consolidating vendor relationships around converters offering integrated design, digital print, and fulfillment partnerships. The traditional separation between packaging procurement and marketing agencies is dissolving as unboxing experience becomes a retention metric. This behavioral shift is most visible in UK and German direct-to-consumer apparel and beauty verticals, where churn rates now correlate with mailer customization quality scores.
Shipping Mailers Market Segmentation
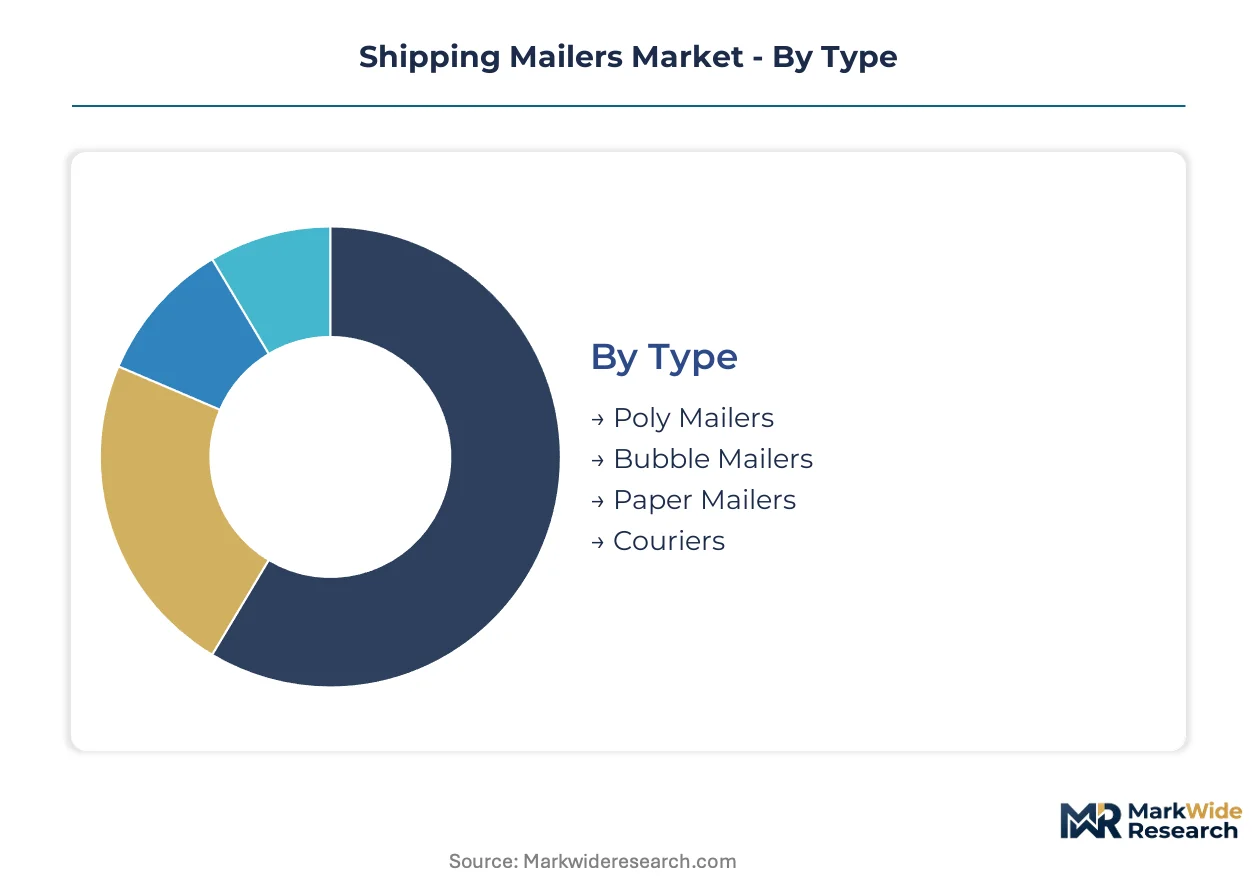
Shipping mailer segmentation reveals how material chemistry, dimensional formats, and end-use requirements fragment procurement patterns across fulfillment networks. E-commerce volume concentration and EU regulatory thresholds are compressing viable product configurations while elevating certified alternatives.
Type:
Mature formats dominate current throughput, though emerging constructions are capturing regulatory-driven replacement cycles.
- Poly Mailers:Polyethylene film constructions with self-adhesive strips deliver moisture resistance and freight density advantages for high-volume parcel transit. German third-party logistics providers and Dutch pharmaceutical distributors standardize these specifications across automated packaging lines, though PPWR recyclability thresholds are forcing post-consumer recycled content reformulation investments.
- Paper Mailers:Kraft paper and fiber-based alternatives with water-activated or pressure-sensitive seals address EU Green Deal mandates for circular design. Demand concentrates in German electronics retail and UK subscription box services where unboxing experience correlates with customer retention metrics.
- Bubble Mailers:Bubble-lined polyethylene composites provide protective cushioning for fragile goods transit.
- Couriers:Rigid document sleeves and specialized flat mailers serve legal and financial sector document protection.
Poly mailers handle the majority of throughput; paper mailers are expanding most quickly on share as fiber-based alternatives displace plastic in EU-compliant channels.
Material:
Cost tier stratification separates virgin feedstocks from certified circular alternatives with qualification complexity driving vendor consolidation.
- Plastic:Virgin and recycled polyethylene films offer moisture barrier performance and heat-seal compatibility for automated fulfillment systems. California SB 54 mandates are accelerating post-consumer recycled content adoption among US direct-to-consumer brands, though migration testing protocols for meal-kit applications extend validation timelines.
- Kraft Paper:Unbleached virgin and recycled pulp constructions provide tear resistance and printability for branded unboxing experiences. Nordic pulp supply volatility during quarterly mill maintenance cycles compresses converter margins when fiber markets tighten.
- Recycled Materials:Post-consumer fiber and reclaimed plastic blends qualify for extended producer responsibility fee discounts.
- Aluminum:Metallized barrier layers serve pharmaceutical cold-chain and high-value electronics segments requiring moisture and oxygen exclusion.
Plastic retains volume leadership across automated fulfillment networks; kraft paper is climbing the fastest as REACH-compliant adhesive systems enable broader application scope.
Size:
Application-specific dimensional requirements fragment production runs, with custom formats capturing premium margin pools from subscription services.
- Small:Formats under 230mm width accommodate jewelry, electronics accessories, and pharmaceutical samples. Electronics last-mile delivery in the Netherlands and pharmaceutical cold-chain transit in Germany sustain demand despite fiber alternatives' moisture resistance limitations.
- Custom:Dimensional tailoring for subscription box services and branded unboxing experiences captures premium pricing from UK and German direct-to-consumer apparel and beauty verticals where churn rates correlate with packaging customization quality.
- Medium:Standard apparel and soft goods dimensions suit bulk e-commerce fulfillment.
- Large:Expanded formats handle bulk textiles and multi-item consolidated shipments.
Small formats sustain protective segment demand; custom sizing is gaining share fastest as marketing procurement merges with packaging specification.
End User:
Customer type concentration determines automation compatibility requirements and certification burden intensity across the value chain.
- E-commerce:Direct-to-consumer platforms and marketplace sellers drive standardization toward automated packaging system integration. German centralized distribution hubs and Polish fulfillment infrastructure development create volume concentration that favors compliant mailer formats with localized print-on-demand branding capability.
- Logistics:Third-party providers and parcel networks prioritize freight density and sortation compatibility. EU PPWR material recovery targets redirect procurement toward fiber-based alternatives with certified recycling stream documentation.
- Retail:Brick-and-mortar replenishment and ship-from-store operations require inventory flexibility.
- Manufacturing:Industrial component protection and spare parts distribution emphasize dimensional stability.
E-commerce channels handle the majority of throughput; logistics procurement is expanding most quickly on share as third-party providers consolidate vendor relationships around integrated compliance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's centralized fulfillment infrastructure consumes shipping mailers at density rates unmatched elsewhere, while Chinese parcel platforms pilot fiber alternatives under dual carbon targets that diverge sharply from Western regulatory timelines.
Germany
Third-party logistics providers operate automated packaging lines across Ruhr Valley distribution hubs, standardizing mailer specifications for e-commerce volume concentration. The EU Packaging and Packaging Waste Regulation enforces material recovery thresholds that redirect procurement toward certified fiber-based formats. Stuttgart's industrial corridor hosts converter facilities specializing in kraft paper lamination for electronics retailers.
United States
Subscription box services and direct-to-consumer brands drive demand for custom-sized formats with print-on-demand branding capabilities. California's SB 54 extended producer responsibility framework mandates post-consumer recycled content adoption, accelerating reformulation investments among domestic converters. Chicago's central logistics positioning supports inventory pooling for multi-channel fulfillment networks.
China
Domestic parcel platforms face national emissions targets that force pilot programs for fiber-based alternatives to conventional polyethylene mailers. The Ministry of Ecology and Environment enforces dual carbon goals that reshape material selection protocols across fulfillment infrastructure. Yangtze River Delta manufacturing clusters develop technology licensing partnerships with European kraft specialists.
Netherlands
Pharmaceutical distributors and consumer electronics retailers pilot water-activated tape formats at scale, displacing bubble-lined polyethylene constructions. REACH compliance on adhesive chemistries enables certified product lines for meal-kit and cold-chain applications. Rotterdam's port logistics integration supports pan-European distribution of compliant mailer formats.
Poland
Underdeveloped fulfillment infrastructure creates first-mover positioning for converters offering EU-compliant formats with localized branding capabilities. E-commerce penetration accelerates demand for automated packaging system integration across emerging distribution networks. Warsaw's logistics corridor attracts vendor consolidation from Western European mailer suppliers seeking cost-advantaged production bases.
Shipping Mailers Market Competitive Landscape
Capability concentration sits with specialty converters mastering kraft lamination and certified recycling documentation; scale advantage sits with integrated packaging conglomerates controlling automated fulfillment system partnerships. The market structures around three tiers: multinational material science groups with captive pulp supply, mid-volume regional converters with print-on-demand integration, and niche protective packaging specialists serving electronics cold-chain segments. Dominant competitive moves include backward integration into pulp sourcing and strategic partnerships with third-party logistics providers for vendor consolidation.
Among European-based material groups, Mondi Group and Smurfit Kappa Group exemplify the integrated tier, with the former anchoring kraft paper specialization and the latter dominating corrugated hybrid formats. Sealed Air Corporation represents the automation-integrated archetype, leveraging packaging system control to secure high-volume e-commerce channels. These three occupy positions that span the capability-scale spectrum, with fiber-based certification and automated fulfillment integration serving as the primary competitive axes.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Mondi Group |
| International Paper |
| Pregis Corporation |
| Smurfit Kappa Group |
| DS Smith Plc |
| ProAmpac LLC |
| Intertape Polymer Group Inc. |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Nordic pulp price volatility compresses converter margins during quarterly mill maintenance cycles, forcing three-tier pricing structure across premium, standard, and economy levels while simultaneously reshaping sourcing footprints toward Baltic and Iberian fiber alternatives.
Pricing Analysis
Long-term offtake contracts dominate procurement between German third-party logistics providers and major converters, though spot purchasing persists for custom-sized formats serving UK subscription box services. Price differentiation stems from REACH-compliant adhesive certification tiers and volume scale commitments to automated packaging lines. Pricing pressure intensifies in fiber-based segments as Nordic supply tightens, while polyethylene tiers face cost compression from California SB 54 recycled content mandates. Small-format bubble mailers for electronics exhibit lowest price sensitivity due to performance requirements, whereas standard poly mailers face acute margin pressure from commoditized Asian supply.
Supply Chain Analysis
Extended payment terms from German e-commerce platforms strain converter working capital, accelerating supply-chain finance facility adoption among mid-volume regional producers. Raw material sourcing draws from Swedish and Finnish kraft pulp mills, Chinese polyethylene resin producers, and Dutch adhesive compounders. Single-source vulnerability concentrates in Nordic bleached pulp for pharmaceutical-grade mailers. Distribution runs through Rotterdam port logistics for pan-European fulfillment, with secondary consolidation at Ruhr Valley distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern vendor consolidation as subscription box services merge packaging procurement with marketing spend, creating interoperability lock-in around converters offering integrated design-to-fulfillment workflows.
For Market Incumbents: Pre-empt displacement by Asian bubble film extruders through captive kraft lamination capacity in Stuttgart's industrial corridor. Anchor vendor consolidation by embedding digital printing into production workflows before aftermarket service providers recover customization revenue. Certification investment in EU PPWR-compliant formats serves as the defensive moat against regional converter entrants. For New Entrants and Emerging Players: Pursue Polish and Romanian e-commerce infrastructure gaps where underdeveloped fulfillment networks favor first-mover positioning with localized print-on-demand branding. White-space concentration sits in fiber-based alternatives for Chinese parcel platforms piloting dual carbon compliance. Go-to-market leverage rests on technology licensing partnerships with European kraft specialists rather than greenfield mill investment. For Investors and Strategic Acquirers: The market sits at a regulatory-inflection phase that favors converters with certified recycling documentation and automated packaging system partnerships. Long-term viability over the next decade hinges on backward integration into pulp sourcing and control of pan-European distribution nodes. Watch migration testing protocol delays at FDA as the signal for meal-kit mailer market access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Sourcing | Captive Nordic fiber supply insulates margin compression during quarterly mill maintenance cycles. |
| Automated Packaging System Partnership | German third-party logistics standardization locks in high-volume e-commerce channel access. |
| REACH-Compliant Adhesive Certification | Water-based sealant qualification opens pharmaceutical and meal-kit last-mile delivery segments. |
| Digital Print Workflow Embedding | Converters reclaim subscription box customization revenue from aftermarket service providers. |
| Polish Production Footprint Expansion | Cost-advantaged base serves emerging Central European e-commerce fulfillment infrastructure. |
Research Methodology
Desk research of EU regulatory filings, trade customs data, and SEC disclosures preceded structured interviews with converter plant managers, third-party logistics procurement leads, subscription box brand managers, and adhesive R&D directors. Primary fieldwork across German distribution hubs and Dutch pharmaceutical corridors combined with secondary validation from PPWR implementation documents and REACH compliance databases. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Assumptions held EU PPWR enforcement timelines and Nordic pulp supply elasticity fixed while varying e-commerce penetration rates and recycled content mandate stringency across member states. The analytical framework modeled material chemistry, dimensional format, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level volume trajectories and price elasticity responses to fiber substitution, with specific inputs including German automated packaging line deployment schedules and California SB 54 compliance cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration by Asian resin producers or accelerated EU Green Deal threshold tightening would shift outcomes. Macroeconomic demand contraction in e-commerce, pulp supply disruption from Nordic labor actions, or breakthrough moisture-resistant fiber formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Assembly Trays Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Candle Box Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Bottles Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Portion Packs Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Food Grade Bottles Market