
 Plasma Bottle Market | 2026-2036
Plasma Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Bottle Market Analytics
Modular bundling of plasma bottles with replacement lids, carry loops, and cleaning kits is broadening buyer choice beyond the base vessel. SGD Pharma leverages its glass-forming expertise to anchor premium positioning in laboratory-grade plasma storage. Thermo Fisher Scientific specializes in temperature-stable configurations for biologics transport. Amcor Limited extends its polymer science capabilities into lightweight, shatter-resistant alternatives that compete on portability.
A plasma bottle is a rigid or semi-rigid container engineered for the storage, transport, or consumption of liquids, typically fabricated from glass, stainless steel, BPA-free plastic, or aluminum with wall thicknesses ranging from 0.5 mm to 2.5 mm depending on thermal insulation requirements. Its primary purpose spans consumer hydration, clinical specimen handling, and pharmaceutical cold-chain logistics where material inertness and seal integrity prevent contamination or degradation. Stainless steel variants command the deepest margin pools due to durability premiums and brand differentiation potential, while BPA-Free Plastic dominates unit volume through cost accessibility and color customization. Sports configurations represent the fastest-expanding product type as athletic participation rates rise and bottle aesthetics become social signaling devices.
FDA food-contact notifications and EU REACH compliance on polymer additives shape material selection and supplier qualification timelines for plasma bottle manufacturers serving regulated end uses. China's SAMR enforces GB standards for plastic food containers that directly affect import eligibility and domestic production specifications. Stakeholders must monitor evolving extended-producer-responsibility frameworks in Europe and North America that will recast cost structures for multi-material bottles and determine which material platforms sustain long-term investment.
Market Dynamics
Urban fitness adoption in China is compressing purchase cycles for plasma bottles as hydration tracking becomes embedded in workout culture, while tightening food-contact material rules in the EU and US are forcing material substitutions across the supply base.
Growth Catalysts
- Fitness Enthusiast Demand:Athletic participation rates in China are rising sharply, with hydration tracking now standard in workout culture. This end-use segment is pulling premium configurations with integrated measurement features.
- EU REACH Compliance:Polymer additive restrictions under REACH are accelerating BPA-Free Plastic formulation upgrades. Suppliers qualifying under these rules gain preferential access to regulated clinical and pharmaceutical end uses.
- E-Commerce Penetration:China's digital retail infrastructure enables direct-to-consumer plasma bottle distribution at scale. Urban clusters with high fitness adoption concentrate demand growth in tier-one cities.
Market Restraints
- Stainless Steel Input Costs:Nickel and chromium price volatility compresses margin pools for premium variants. Manufacturers face margin pressure when raw material spikes coincide with durability-premium pricing expectations.
- Glass Supply Concentration:Laboratory-grade plasma storage capacity clusters with specialized glass-forming expertise. Limited qualified suppliers create bottleneck risk for clinical and pharmaceutical cold-chain applications.
- Multi-Material Recycling Friction:Extended-producer-responsibility frameworks in Europe recast cost structures for bottles combining polymers, metals, and seals. Compliance complexity disadvantages hybrid material platforms.
Strategic Opportunities
- Modular Accessory Ecosystems:Replacement lids, carry loops, and cleaning kits expand addressable revenue per user. Bundling strategies capture aftermarket value beyond the base vessel sale.
- Biologics Transport Configurations:Temperature-stable designs for pharmaceutical cold-chain logistics address an emerging application with stringent performance requirements. This segment commands qualification premiums.
- India PLI Scheme Alignment:Domestic manufacturing incentives for specialty chemicals and polymers could localize BPA-Free Plastic production. Early qualification with BIS standards positions suppliers for import substitution demand.
Industry Challenges
- Polymer Science Talent Gap:Formulation chemists capable of balancing BPA-free performance with cost accessibility remain scarce. Recruitment competition from broader packaging sectors extends R&D timelines.
- SAMR GB Standard Certification:China's plastic food container standards require extended supplier qualification timelines. Documentation and testing protocols delay market entry for new material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Bottle Market |
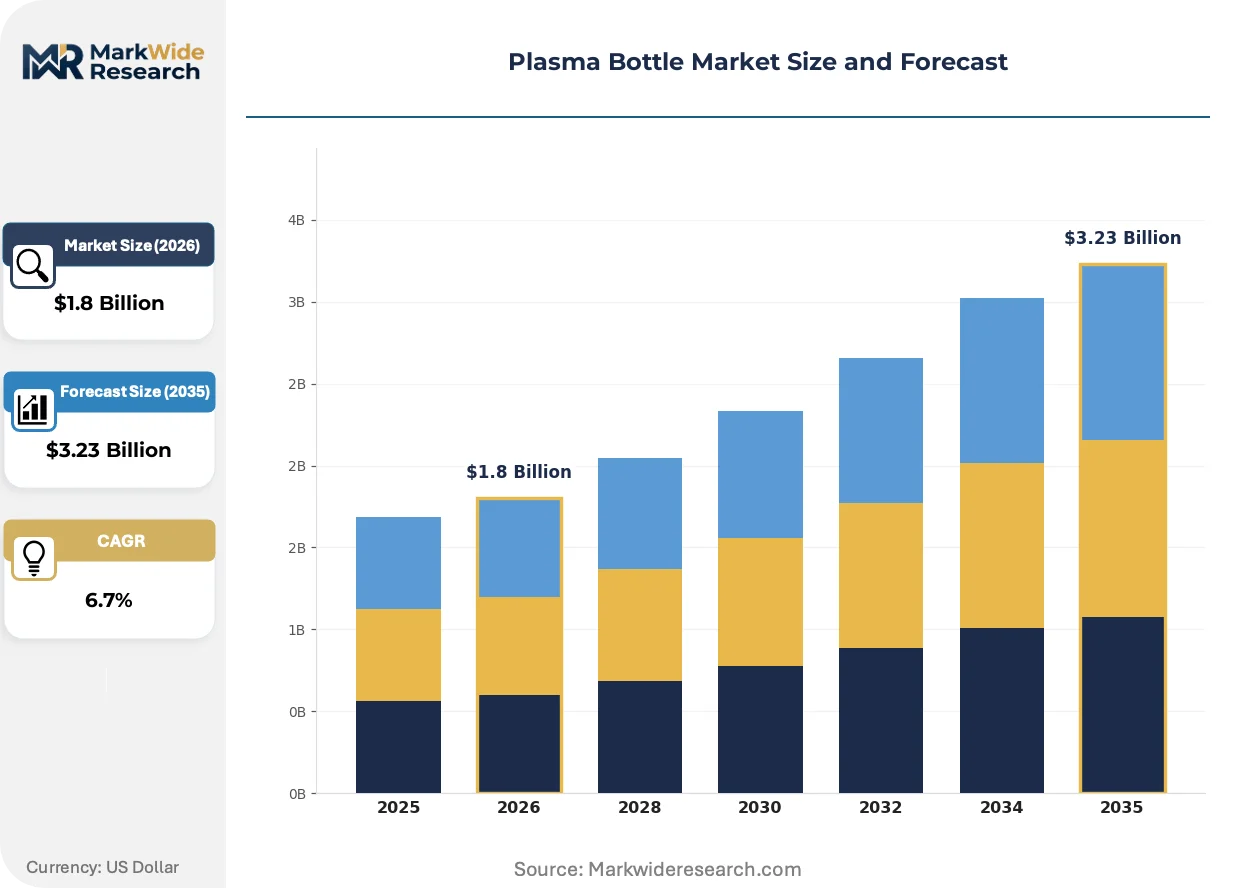
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Insulated, Sports Material: Glass, Stainless Steel, BPA-Free Plastic, Aluminum Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales End User: Fitness Enthusiasts, Students, Office Workers, Travelers |
| Companies Covered | SGD Pharma, Adelphi Group, Amcor Limited, Ball Corporation, Graham Packaging Company Inc, Alpha Packaging, Thermo Fisher Scientific, Corning, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Bottle Market Evolving Landscape
Smart hydration tracking is embedding sensors and connectivity into plasma bottle designs, while regulatory pressure on polymer additives and shifting procurement patterns are redrawing competitive boundaries across material platforms.
Embedded sensor modules is decentralizing quality assurance in plasma bottle manufacturing. Fitness technology integrators are adopting these components rapidly for connected hydration products. The technology is decentralizing validation responsibility from centralized labs to distributed manufacturing nodes, compressing certification timelines.
EU extended-producer-responsibility frameworks are recasting cost structures for multi-material bottles. Industrial consequence includes accelerated investment in mono-material designs and recyclable polymer platforms. Laboratory and pharmaceutical end uses in Germany and France are responding with stricter supplier sustainability scorecards.
Aesthetic customization is displacing standardized procurement in athletic and lifestyle segments. Direct-to-consumer channels and social commerce platforms are replacing traditional retail assortment models. This shift is most visible in China's tier-one cities, where bottle designs function as social signaling devices among fitness enthusiasts.
Plasma Bottle Market Segmentation
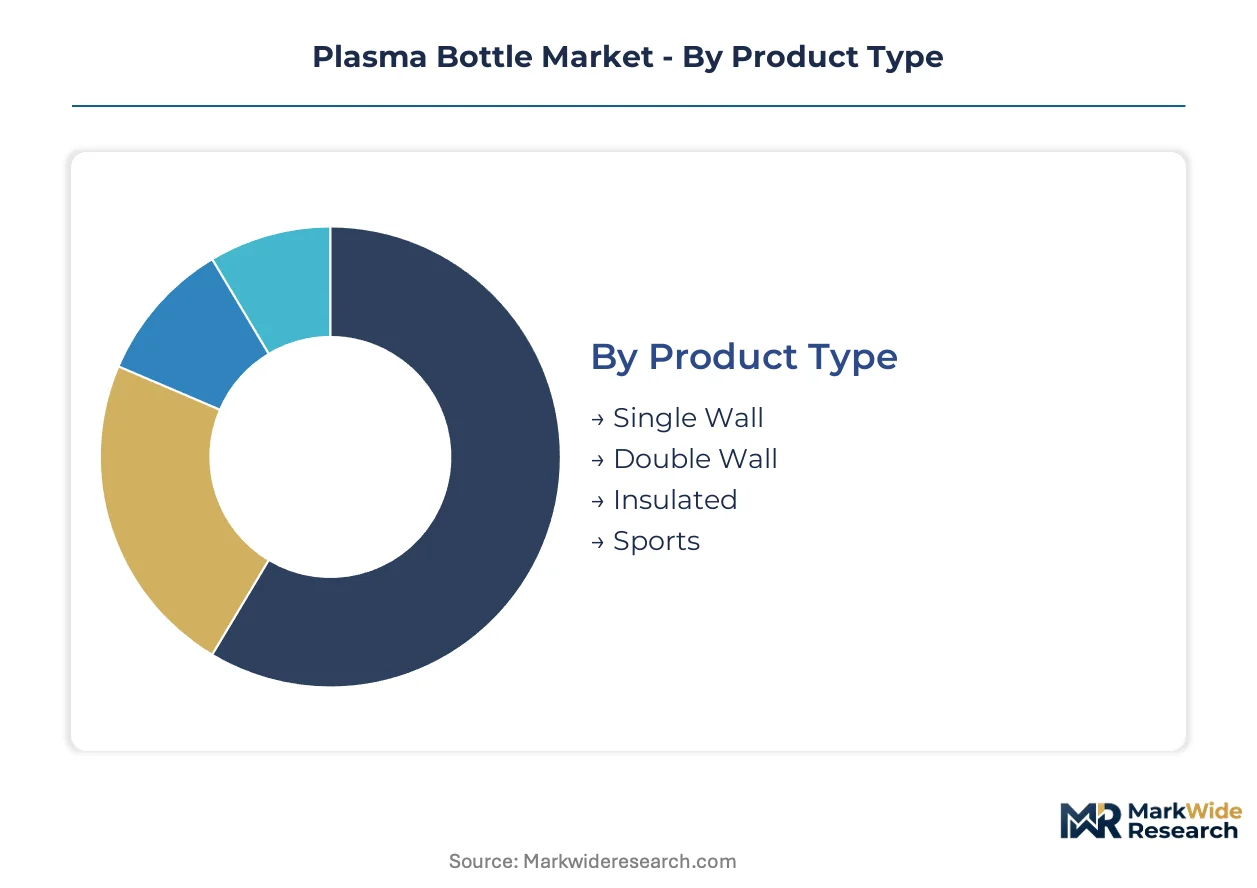
Plasma bottle manufacturers configure product portfolios around thermal performance requirements, material cost tiers, and channel access economics. Each segmentation dimension reveals distinct buyer priorities that reshape pricing power and supplier qualification barriers across end-use applications.
Product Type:
Buyers in this category differentiate primarily by thermal retention needs and mobility intensity rather than base capacity specifications.
- Sports:Engineered with ergonomic grips, leak-proof seals, and integrated measurement markers for high-frequency use during athletic activity. Demand concentrates among urban fitness adopters in China where hydration tracking integrates with workout culture and bottle aesthetics signal social status. This configuration commands premium positioning through performance features and design differentiation.
- Insulated:Constructed with vacuum-sealed double-wall construction maintaining liquid temperature across extended durations. Pharmaceutical cold-chain logistics and clinical specimen transport drive procurement in regulated end uses where thermal stability prevents degradation. FDA food-contact notifications and EU REACH compliance shape supplier qualification timelines for these applications.
- Double Wall:Provides moderate thermal retention through air-gap construction without vacuum sealing. Office workers and commuters in tier-one cities favor this configuration for daily beverage temperature maintenance.
- Single Wall:Lightweight uninsulated construction prioritizing portability and cost accessibility. Students and price-sensitive travelers represent core demand for this entry-tier configuration.
Sports configurations are climbing the fastest as athletic participation rates rise globally; single-wall variants retain the largest unit volumes through mass-market accessibility.
Material:
Raw material selection in this category traces directly to end-use regulatory exposure and durability premium capture potential.
- Stainless Steel:Fabricated from food-grade 18/8 or 304 alloys with nickel and chromium content providing corrosion resistance and structural longevity. Durability premiums and brand differentiation potential concentrate margin pools here, though nickel price volatility compresses manufacturer returns during raw material spikes.
- BPA-Free Plastic:Formulated with alternative polymer additives eliminating bisphenol-A under tightening EU REACH and China SAMR GB standards. Unit volume leadership stems from cost accessibility, color customization range, and lightweight portability that appeals to fitness enthusiasts and students.
- Glass:Borosilicate or soda-lime compositions delivering chemical inertness for laboratory-grade plasma storage and pharmaceutical applications. SGD Pharma and specialized glass-forming suppliers anchor premium positioning where contamination prevention is non-negotiable.
- Aluminum:Rolled or extruded alloys offering weight advantages between plastic and steel with full recyclability. Sustainability-conscious travelers and outdoor enthusiasts drive niche demand for this material platform.
BPA-Free Plastic leads volumes today; stainless steel is gaining share fastest through durability premiums and fitness segment positioning.
Distribution Channel:
Channel strategy in this category determines margin capture versus reach tradeoffs, with digital infrastructure reshaping traditional retail economics.
- Online Retailers:E-commerce platforms enabling direct-to-consumer distribution at scale with personalized configuration options. China's digital retail infrastructure concentrates demand growth in tier-one cities where fitness enthusiasts research and purchase through mobile-first interfaces.
- Specialty Stores:Curated retail environments emphasizing premium positioning, tactile evaluation, and expert guidance. Laboratory and pharmaceutical procurement teams rely on specialized distributors for qualification documentation and cold-chain logistics support.
- Supermarkets:Mass-market retail delivering impulse purchase accessibility and standardized assortment economics. Price-sensitive student and traveler segments dominate this channel through promotional pricing and seasonal display placement.
- Direct Sales:Manufacturer-controlled channels capturing full margin through corporate procurement contracts and institutional relationships. Biologics transport configurations and temperature-stable designs flow through this channel with stringent performance documentation.
Online retailers lead volumes today; specialty stores are expanding most quickly through premium fitness and laboratory segment capture.
End User:
End-user segmentation reveals divergent performance requirements spanning social signaling, regulatory compliance, and basic hydration utility.
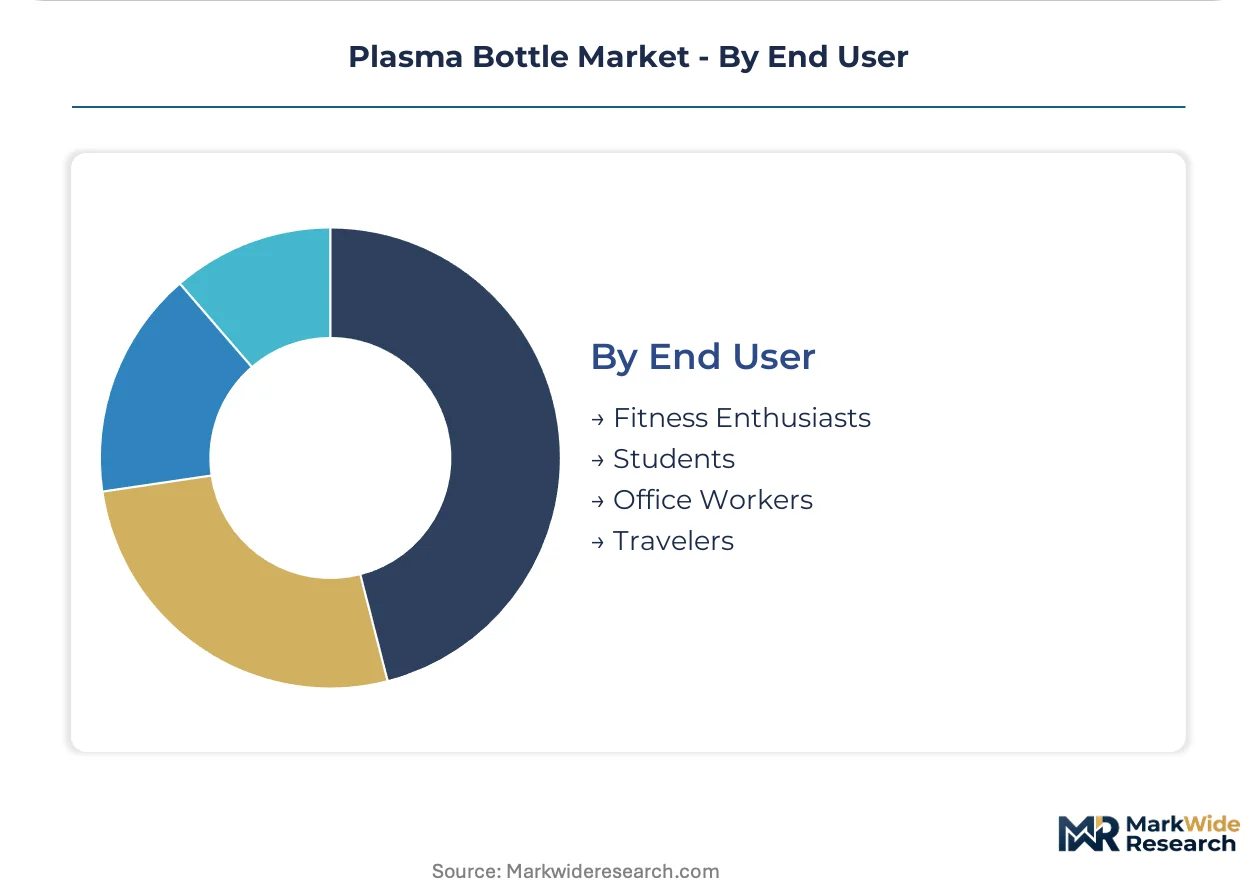
- Fitness Enthusiasts:Athletic participants prioritizing integrated measurement features, ergonomic design, and aesthetic differentiation for workout culture integration. China's urban fitness adoption compresses purchase cycles as hydration tracking becomes embedded in exercise routines.
- Office Workers:Professional environments demanding desk-friendly dimensions, spill prevention, and moderate thermal retention for extended work sessions. Procurement emphasizes durability and workplace appropriateness over performance specifications.
- Students:Price-sensitive demographic prioritizing lightweight portability, color variety, and replacement cost accessibility. Volume concentration in educational institutions drives standardized procurement and promotional bundling strategies.
- Travelers:Mobile users requiring collapsible or compact configurations with TSA compliance and leak-proof reliability for transit environments. Adventure and business travel segments split between durability premiums and weight minimization priorities.
Fitness enthusiasts anchor premium revenue pools today; office workers are gaining share fastest through hybrid work hydration normalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma bottle manufacturing originated in European glass-forming centers before expanding into North American polymer science hubs and Asia-Pacific mass-production corridors. The industry now distributes capacity across specialized clusters serving distinct regulatory environments and end-use requirements.
China
Urban fitness adoption in Shanghai, Beijing, and Shenzhen compresses purchase cycles for sports-configured plasma bottles with integrated measurement features. SAMR enforces GB standards for plastic food containers that directly affect import eligibility and domestic production specifications. The Yangtze River Delta concentrates contract manufacturing capacity serving both domestic e-commerce platforms and export markets.
United States
FDA food-contact notifications shape material selection timelines for manufacturers serving clinical specimen handling and pharmaceutical cold-chain logistics. EPA extended-producer-responsibility frameworks in California and New York recast cost structures for multi-material bottle platforms. The Boston-Cambridge corridor anchors laboratory-grade plasma storage demand from biotech research institutions.
Germany
EU REACH compliance on polymer additives accelerates BPA-Free Plastic formulation upgrades across packaging supply chains. ECHA restrictions force material substitutions that extend supplier qualification timelines for regulated end uses. The Rhine-Ruhr industrial zone hosts specialized glass-forming expertise for pharmaceutical cold-chain applications.
India
Domestic manufacturing incentives under the PLI scheme for specialty chemicals could localize BPA-Free Plastic production for price-sensitive student and traveler segments. BIS certification requirements for food-contact materials delay market entry for new polymer formulations. Maharashtra and Gujarat concentrate polymer processing capacity serving both domestic consumption and regional export markets.
Japan
METI industrial standards and PMDA pharmaceutical regulations enforce stringent performance requirements for temperature-stable biologics transport configurations. JIS standards for food-contact materials shape supplier qualification protocols for clinical applications. The Kanto region around Tokyo anchors precision manufacturing for high-durability stainless steel variants.
Plasma Bottle Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with polymer science capabilities. Consolidation pressure concentrates laboratory-grade plasma storage capacity with specialized glass-forming expertise while fragmentation persists in consumer hydration segments. Three archetypes dominate: diversified materials science conglomerates, specialized clinical packaging specialists, and contract manufacturers serving branded consumer goods companies. Capacity expansion in Asia-Pacific and strategic partnerships for cold-chain logistics represent the dominant competitive moves.
Among diversified packaging conglomerates, Amcor Limited and Ball Corporation exemplify scale-driven positions spanning multiple material platforms and geographic markets. SGD Pharma occupies a specialized tier anchoring premium positioning in laboratory-grade plasma storage through glass-forming expertise. Thermo Fisher Scientific represents the clinical-specialist archetype, with its scientific instrumentation heritage informing temperature-stable configuration development for biologics transport.
| Leading Market Players |
|---|
| SGD Pharma |
| Adelphi Group |
| Amcor Limited |
| Ball Corporation |
| Graham Packaging Company Inc |
| Alpha Packaging |
| Thermo Fisher Scientific |
| Corning |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between laboratory-qualified and consumer-grade plasma bottles bifurcates pricing power and supplier economics across the value chain. FDA food-contact notifications and EU REACH compliance tiers create qualification ladders that concentrate margin capture among polymer science specialists while commodity configurations compete on input cost management.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs plasma bottle procurement, with FDA-tier certification and thermal performance specifications as primary differentiation drivers. Stainless steel variants anchored by nickel-chromium alloy grades command durability premiums from fitness enthusiasts, while BPA-Free Plastic formulations compete on color customization and volume scale. Cost compression in standard-tier configurations intensifies as Chinese contract manufacturers expand polymer processing capacity. Students and price-sensitive travelers exhibit highest price sensitivity; pharmaceutical cold-chain buyers demonstrate lowest sensitivity due to performance non-negotiability.
Supply Chain Analysis
Single-source vulnerability sits with specialized borosilicate glass-forming capacity concentrated in Germany and France for laboratory-grade plasma storage. Raw material feeds draw from nickel mining corridors in Indonesia and the Philippines, polymer resin complexes in China and South Korea, and aluminum smelting in Australia and Canada. Tariff exposure on Chinese-manufactured BPA-Free Plastic components threatens cost structures for North American consumer brands. Distribution runs through direct-to-consumer e-commerce platforms in Chinese tier-one cities, specialty distributors for clinical applications, and mass retail for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in plasma bottles rests on BPA-Free Plastic formulation cost-down trajectories and the premium-tier shift toward temperature-stable biologics transport configurations. Procurement normalization in hybrid work environments and fitness culture embedding sustain volume pull-through.
For Market Incumbents: Cement laboratory-grade qualification barriers by deepening captive polymer formulation capabilities and securing SAMR GB standard pre-certification for next-generation additive packages. Capacity addition in the Yangtze River Delta reinforces proximity to Chinese e-commerce demand clusters. Threat from modular accessory ecosystems demands aftermarket revenue capture through bundled lid and cleaning kit architectures.
For New Entrants and Emerging Players: Specialty distributors serving German and French pharmaceutical cold-chain logistics represent the most penetrable channel partner type for qualification-light market entry. White-space targets include temperature-stable configurations for biologics transport and India PLI scheme-aligned domestic manufacturing for price-sensitive student segments. Direct sales to biotech research institutions in the Boston-Cambridge corridor offers defensible go-to-market positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where glass-forming expertise concentrates with SGD Pharma and specialized European suppliers lacking polymer science diversification. Long-term viability favors diversified materials science conglomerates with cross-platform certification capabilities. Acquisition target archetype: mid-cap BPA-Free Plastic specialists with SAMR qualification progress and stranded laboratory-grade glass capacity. Signal to watch: ECHA polymer additive restriction expansions accelerating supplier qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captive BPA-Free Plastic formulation secures margin control against REACH compliance cost spikes. |
| Modular Accessory Ecosystem Launch | Replacement lid and cleaning kit bundling expands addressable revenue per fitness enthusiast user. |
| India PLI Scheme Manufacturing Alignment | Domestic BPA-Free Plastic production localizes supply for price-sensitive student and traveler demand. |
| Temperature-Stable Biologics Configuration Development | Pharmaceutical cold-chain qualification opens premium pricing pools from Thermo Fisher Scientific procurement standards. |
| SAMR GB Standard Pre-Certification Investment | Accelerated China market entry for next-generation polymer additives ahead of competitor qualification timelines. |
Research Methodology
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each regional cluster combining executive interviews with polymer formulation chemists, procurement managers at biotech research institutions, e-commerce platform category leads, and regulatory affairs specialists at packaging conglomerates. Secondary validation draws from FDA food-contact notification databases, ECHA REACH restriction updates, SAMR GB standard publications, and customs trade flow records. Bottom-up demand modeling triangulates against top-down materials consumption estimates.
Granularity-level framing applies product type, material platform, distribution channel, and end-user segmentation dimensions at the country level across the projection horizon. CAGRs derive from volume trajectory analysis calibrated to urban fitness adoption rates, regulatory compliance timeline assumptions, and e-commerce penetration curves. Industry-specific forecast inputs include nickel price volatility indices for stainless steel margin modeling and SAMR qualification pipeline tracking for BPA-Free Plastic market entry timing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA polymer additive restriction expansions, nickel supply disruption events, and Chinese dual carbon policy implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Dosage Cups Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Can Holders Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Candle Box Market
Packaging Containers
Bottles Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Correx Trays Market
Packaging Containers
Acrylic Boxes Market