
 Food Portion Pack Market | 2026-2036
Food Portion Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Food Portion Pack Market Foresight
Buyer concentration across quick-service chains and institutional foodservice is broadening as regional franchise networks and cloud kitchen operators multiply order volumes for standardized portion formats. Sealed Air leverages barrier-film expertise to capture shelf-life extension contracts with protein processors. DS Smith anchors European demand through molded-fiber tray capacity expansion. Amcor PLC competes across flexible pouch and lidding film portfolios for dairy and condiment applications.
Food portion packs are single-serve containment systems, typically fabricated from coated paper, thermoformed plastic, or aluminum laminate, designed to preserve product integrity, control serving size, and enable consumption without additional utensils or preparation. They function as the terminal interface between processed food manufacturers and end consumers in away-from-home and grab-and-go contexts. Pouches lead value contribution due to retort compatibility and lightweight logistics profiles, while trays capture margin pools in ready-to-eat meals where ovenability and barrier performance command premium positioning. Sachets sustain volume concentration in condiment and sauce distribution, though format commoditization pressures unit economics across private-label supply chains.
The EU Single-Use Plastics Directive and FDA food-contact substance notifications jointly reshape material qualification pathways, extending development timelines for novel barrier coatings while opening substitution opportunities for fiber-based formats. BIS packaging standards in India and China's GB food-contact regulations add compliance layers for exporters targeting emerging consumption clusters. Stakeholders must monitor evolving extended producer responsibility frameworks and pre-qualify alternative substrates before mandate-driven supply switches disrupt existing procurement contracts.
Market Dynamics
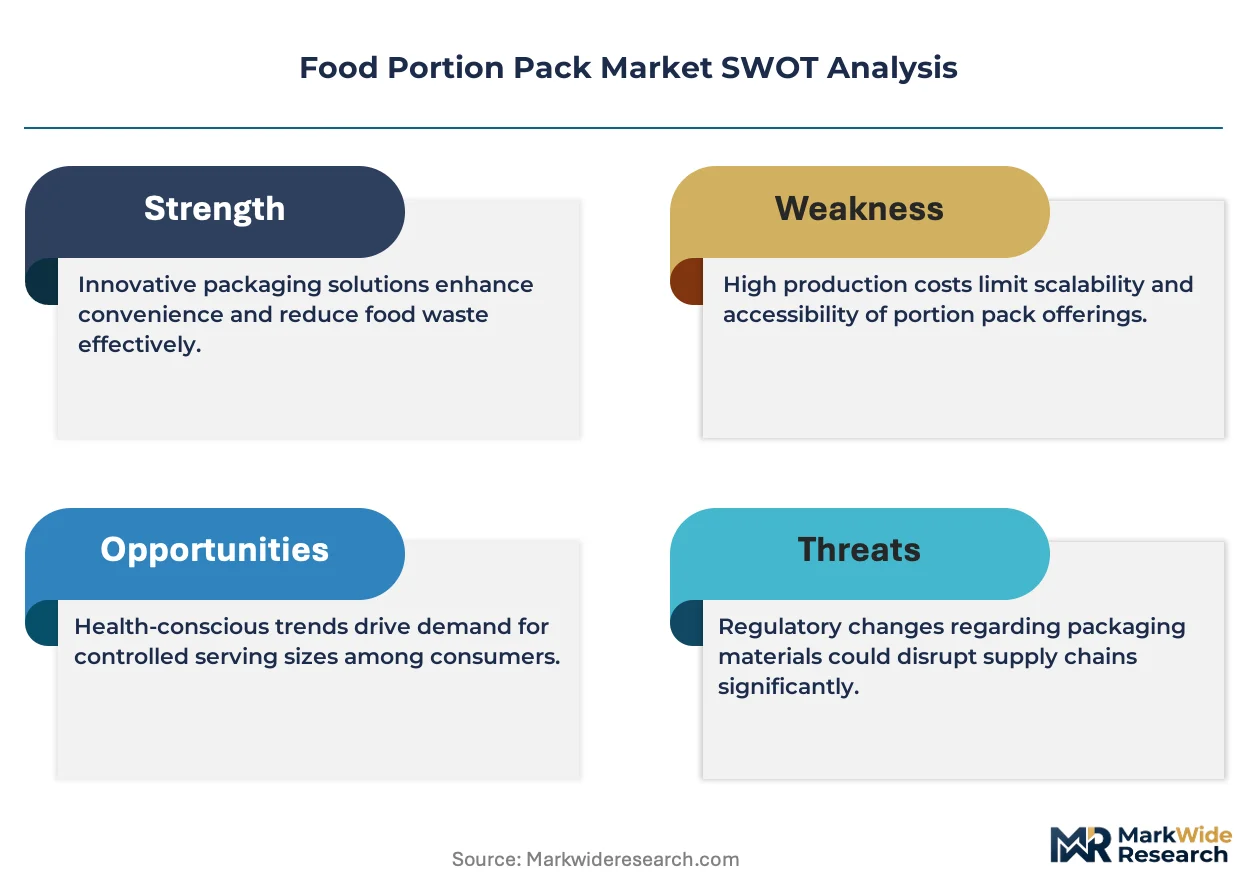
The EU Single-Use Plastics Directive is forcing material transitions across European foodservice supply chains, while quick-service restaurant procurement consolidation reshapes volume allocation toward standardized, shelf-stable formats.
Growth Catalysts
- Regulatory phase-outs:The EU Single-Use Plastics Directive bans expanded polystyrene food containers, accelerating paper and molded fiber substitution in airline catering and institutional foodservice.
- Cloud kitchen proliferation:Dark kitchen operators in urban India and Southeast Asia multiply single-serve sauce and condiment demand for delivery-optimized packaging.
- Barrier coating advances:Water-based and bio-derived coatings for paper substrates achieve grease resistance parity with polyethylene laminates, unlocking ovenable tray applications.
Market Restraints
- Pulp fiber cost volatility:European energy prices and Nordic softwood supply constraints transmit directly to molded fiber tray input costs, compressing margin pools for converters.
- Aluminum laminate supply concentration:Rolling mill capacity for thin-gauge foil concentrates in China and Russia, exposing protein processor contracts to geopolitical supply disruption.
- Retort pouch technical ceiling:Current polyamide barriers face temperature limitations above 135°C, constraining shelf-stable meal penetration into low-acid, low-salt preservation categories.
Strategic Opportunities
- India institutional expansion:The Mid-Day Meal Scheme and corporate cafeteria modernization drive demand for portion-controlled, nutritionally fortified formats in government and IT campus channels.
- Compostable mandate alignment:France's AGEC law and Italy's plastic tax create preferential procurement pathways for home-compostable sachets in premium condiment and cosmetic food adjacencies.
- Active packaging convergence:Oxygen scavenger and moisture regulator integration with flexible pouches extends ready-to-eat protein shelf life without cold chain dependency in African last-mile distribution.
Industry Challenges
- Migration testing bottlenecks:FDA food-contact substance notifications and EFSA dossier reviews extend novel barrier coating qualification timelines to 18-24 months, delaying product launches.
- Legacy equipment retrofit costs:Form-fill-seal lines configured for polyethylene webs require substantial mechanical and thermal modification to run heat-sealable paper substrates at commercial speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Portion Pack Market |
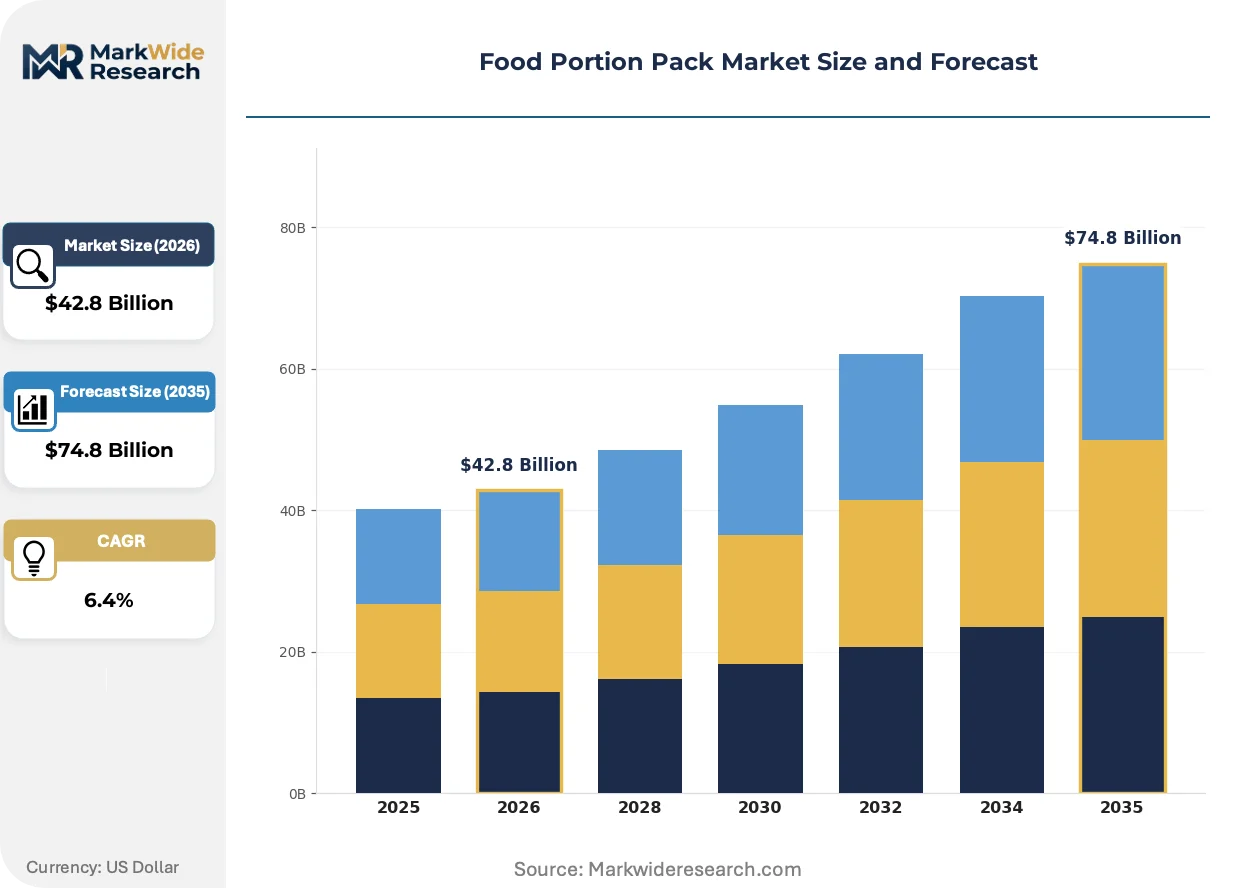
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Pouches, Cups, Trays, Wraps, Sachets Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service, Specialty Shops End User: Children, College Students, Office Workers, Travelers, Seniors Application: Ready-to-Eat Meals, Snacks, Condiments, Dairy Products, Frozen Foods |
| Companies Covered | Sealed Air, DS Smith, Amcor PLC, International Paper, Smurfit Kappa Group PLC, Tetra Pak, Sonoco, Pactiv Evergreen, Berry Global Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Portion Pack Market Shifts & Advancements
Material science breakthroughs and regulatory compliance automation are compressing development cycles while reshaping competitive advantage toward substrate versatility rather than scale economics alone.
Water-based barrier coatings with cellulose nanofiber reinforcement are decentralizing technical capability from multinational chemical suppliers to regional paper converters. Mid-tier European converters now formulate proprietary coating recipes in-house, bypassing laminate film tolling agreements. This capability diffusion compresses lead times for custom portion formats from twelve weeks to four.
France's AGEC anti-waste law mandates recycled content thresholds and standardized recyclability labeling, forcing reformulation of multi-layer pouches toward mono-material polyethylene or polypropylene structures. Dairy and condiment packers face 2025 compliance deadlines, accelerating investment in high-barrier single-substrate webs. German retailers are pre-qualifying suppliers against these specifications ahead of enforcement.
Cloud kitchen operators now specify portion pack formats at the menu development stage rather than accepting standard supplier catalogs. This upstream design involvement shifts power toward packaging-integrated food technology firms in Dubai, Singapore, and São Paulo. Dark kitchen brands in these cities commission bespoke sachet geometries that optimize delivery thermal retention and unboxing experience.
Food Portion Pack Market Segmentation
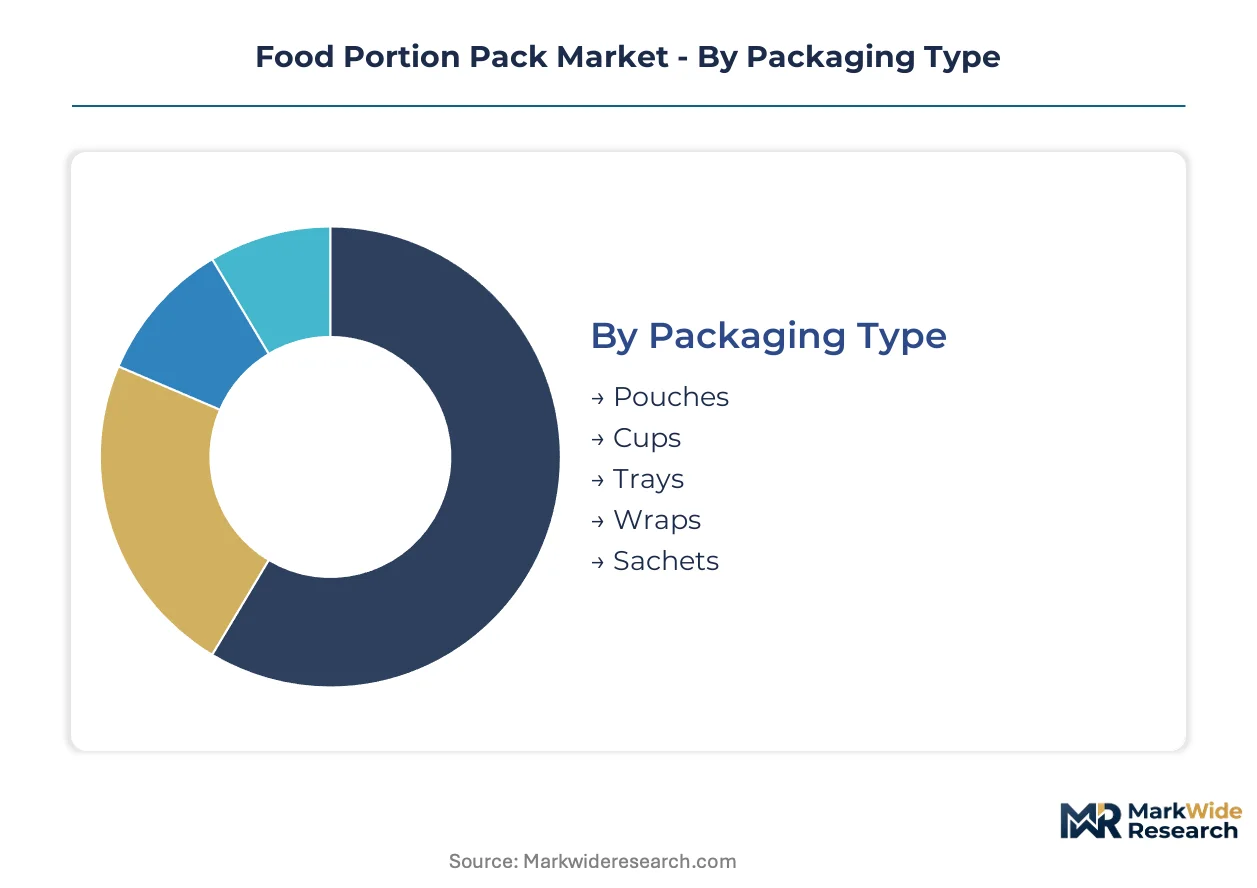
Portion pack segmentation reveals divergent compliance burdens across formats, with retort-compatible pouches and ovenable trays demanding distinct EFSA and FDA food-contact dossiers. Material qualification timelines and end-use temperature requirements fragment procurement strategies across protein processors, dairy packers, and condiment suppliers.
Packaging Type:
Pouches and trays carry the heaviest certification load, with retort pouches requiring EFSA migration testing for polyamide barriers and molded fiber trays needing FDA food-contact notifications for novel grease-resistant coatings.
- Pouches:Multi-layer flexible structures with aluminum or metallized barriers enable shelf-stable protein and sauce distribution. Quick-service chains in Germany and cloud kitchen operators in India concentrate procurement for delivery-optimized formats. Retort compatibility above 121°C demands extended EFSA dossier reviews.
- Trays:Thermoformed plastic or molded fiber substrates with lidding films serve ready-to-eat meals requiring ovenability. Airline caterers and institutional foodservice in France specify these for hot-hold applications. Barrier coating advances for cellulose-based alternatives trigger 18-24 month FDA notification timelines.
- Cups:Single-serve dairy and dessert containment with heat-sealable foil lids.
- Wraps:Grease-resistant paper or film laminates for handheld consumption.
- Sachets:Small-format condiment and sauce distribution with commodity pricing pressure.
Pouches sit at the top of the volume ranking, with trays climbing the fastest.
Distribution Channel:
Channel selection maps directly to cost tier exposure, with food service commanding premium barrier specifications and supermarkets driving standardized, high-volume formats.
- Food Service:Quick-service restaurants, airline caterers, and institutional cafeterias specify custom portion geometries with extended shelf-life requirements. Procurement consolidation across franchise networks favors suppliers with multi-site logistics capability.
- Supermarkets:Retail shelf presence demands mono-material or clearly labeled recyclable structures to meet France's AGEC law and German retailer pre-qualification standards. Private-label concentration compresses margin pools.
- Convenience Stores:Grab-and-go ready-to-eat meals and snack formats with impulse-purchase visibility.
- Online Retail:Direct-to-consumer specialty and subscription formats with unboxing experience specifications.
- Specialty Shops:Premium and ethnic food categories with artisan positioning.
Food service leads absolute volume, with online retail expanding most quickly.
End User:
User-centric design concentrates R&D investment toward portion control precision and consumption ergonomics for mobile and senior populations.
- Office Workers:Desk-ready lunch formats with microwave compatibility and minimal odor emission. Corporate cafeteria modernization in India's IT corridors drives demand for nutritionally labeled, portion-controlled meals.
- Travelers:TSA-compliant, spill-resistant structures for aviation and rail consumption. Airline caterers specify lightweight, stackable formats with extended ambient shelf stability.
- Children:School meal programs with choking hazard compliance and fortified nutritional content.
- College Students:Value-priced, calorie-dense formats for campus retail.
- Seniors:Easy-open features and texture-modified food compatibility.
Office workers represent the largest addressable base, with travelers gaining share fastest on aviation recovery.
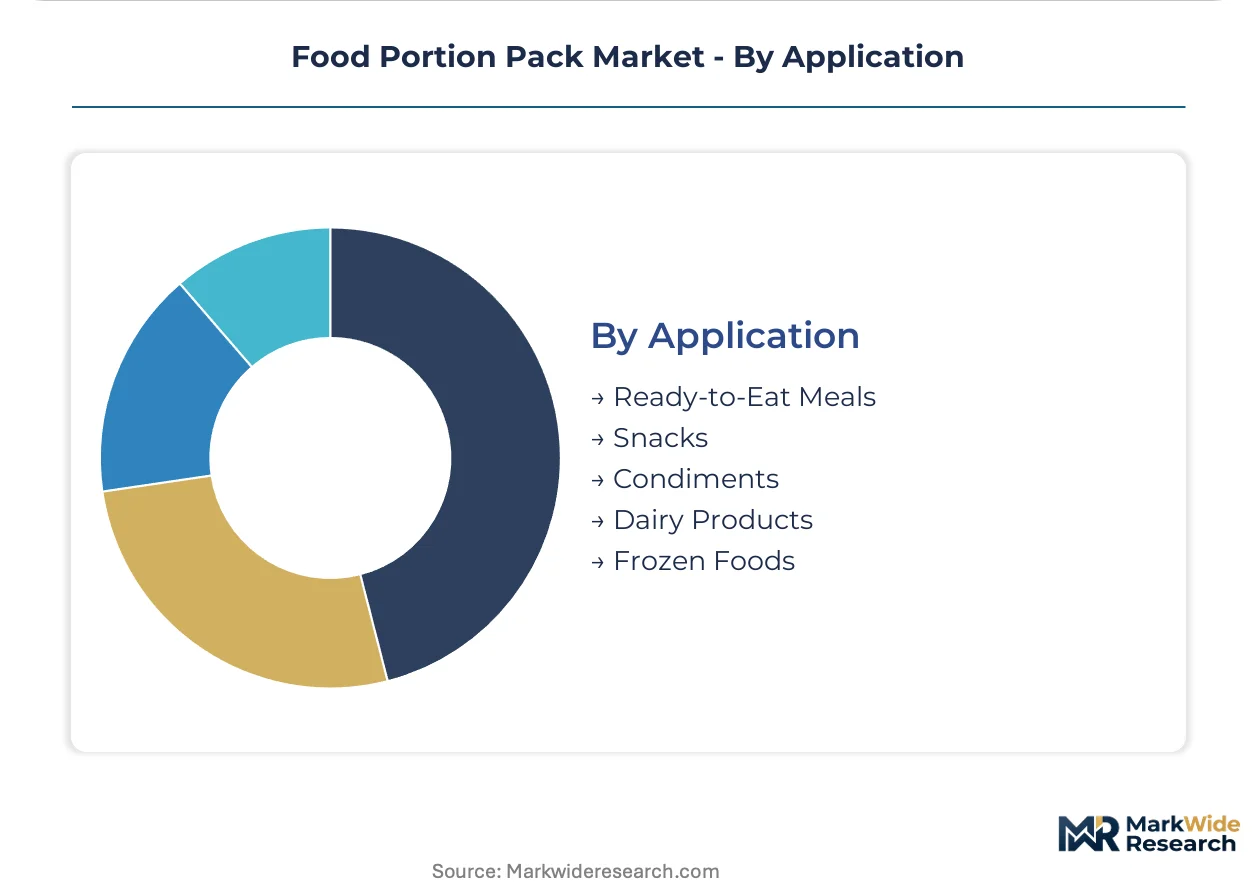
Application:
Application segmentation tracks margin stratification, with ready-to-eat meals capturing premium positioning and condiments facing commoditization pressure.
- Ready-to-Eat Meals:Complete protein-carbohydrate-vegetable combinations in retort pouches or dual-compartment trays. India's Mid-Day Meal Scheme and European airline catering concentrate institutional procurement. Active packaging integration with oxygen scavengers extends shelf life for African last-mile distribution.
- Condiments:Single-serve sauce, dressing, and seasoning sachets in high-volume, low-margin production. Cloud kitchen proliferation in Southeast Asia multiplies order volumes, though format standardization limits pricing power.
- Snacks:Portion-controlled nuts, chips, and confectionery with reseal features.
- Dairy Products:Yogurt, cheese, and creamer formats with cold chain or ambient stability requirements.
- Frozen Foods:Ovenable trays for microwave-to-table convenience.
Ready-to-eat meals command the highest value per unit, with condiments posting the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision-engineered portion formats command institutional premiums, while India's cloud kitchen proliferation multiplies single-serve procurement volumes across urban corridors. Material transition mandates in France and regulatory phase-outs across the EU Single-Use Plastics Directive are redrawing substrate qualification pathways.
Germany
Institutional foodservice and premium retail channels concentrate demand for precision-engineered portion formats. The EU Single-Use Plastics Directive accelerates molded fiber tray adoption in airline catering contracts. Baden-Württemberg's converter cluster supplies barrier-coated paper substrates to protein processors seeking shelf-life extension.
United States
Quick-service restaurant procurement consolidation drives standardized, shelf-stable format volumes. FDA food-contact substance notifications govern novel barrier coating approvals for paper alternatives. Georgia's poultry processing corridor sources retort-compatible pouches for ready-to-eat meal distribution.
France
The AGEC anti-waste law mandates recycled content thresholds and standardized recyclability labeling for mono-material structures. Dairy and condiment packers face compliance deadlines accelerating high-barrier single-substrate web investment. Paris-region retailers pre-qualify suppliers against 2025 enforcement specifications.
India
The Mid-Day Meal Scheme and corporate cafeteria modernization drive portion-controlled, nutritionally fortified format demand. FSSAI packaging standards add compliance layers for molded fiber tray imports. Bengaluru's IT corridor cloud kitchen operators commission bespoke sachet geometries for delivery thermal retention.
China
GB food-contact regulations govern aluminum laminate qualification for protein processor contracts. Dual carbon goals pressure converters toward bio-derived coating formulations. Yangtze River Delta rolling mill capacity supplies thin-gauge foil for barrier film laminators serving export markets.
Food Portion Pack Market Competitive Landscape
North American producers anchor the scale-driven tier; European specialists hold the premium-materials position. Consolidation patterns favor multi-site logistics capability across franchise networks, while regional converters exploit coating formulation diffusion to compress custom format lead times. Three archetypes dominate: multinational film and barrier specialists, molded-fiber capacity expanders, and integrated paper-converter-chemical formulators. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Within the multinational barrier-film tier, Sealed Air and Amcor PLC represent integrated packaging technology positions. DS Smith exemplifies the European molded-fiber capacity expansion archetype. These three entities occupy anchor positions across flexible pouch, lidding film, and tray substrate portfolios respectively.
| Leading Market Players |
|---|
| Sealed Air |
| DS Smith |
| Amcor PLC |
| International Paper |
| Smurfit Kappa Group PLC |
| Tetra Pak |
| Sonoco |
| Pactiv Evergreen |
| Berry Global Group |
| Others |
Supply & Pricing Matrix
Quick-service restaurant procurement consolidation across franchise networks and cloud kitchen operators concentrates buying power toward standardized, high-volume formats. This buyer concentration enforces contract-based long-term offtake pricing with tiered volume discounts, while raw material volatility in pulp fiber and aluminum laminate transmits directly to converter margins.
Pricing Analysis
Capacity additions in Germany and India are reshaping price floors for molded fiber trays and flexible pouches. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified retort formats from commodity sachets. Price differentiation rests on barrier certification tier and volume scale. Pricing pressure stems from private-label concentration in European retail, compressing margin pools for mid-tier converters. Cloud kitchen operators in Southeast Asia exhibit highest price sensitivity; airline caterers in Germany least.
Supply Chain Analysis
France's AGEC law and India's FSSAI packaging standards are reshaping sourcing toward domestic-content-qualified suppliers. Raw material supply concentrates in China for aluminum rolling mill capacity, Sweden and Finland for Nordic softwood pulp, and Germany for barrier coating chemicals. Converter operations draw from polyethylene resin, cellulose nanofiber, and metallized film inputs. Single-source vulnerability concentrates in thin-gauge foil rolling capacity. Distribution runs through regional converter hubs serving franchise network logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's cloud kitchen proliferation offers volume expansion at lower compliance cost than EU regulatory-heavy formats, while European premium positioning captures margin pools unavailable in price-sensitive emerging channels.
For Market Incumbents: Acquire regional coating formulation capabilities to compress custom format lead times from twelve weeks to four. Incumbents must defend against mid-tier European converters bypassing laminate film tolling agreements through proprietary water-based barrier recipes. Capacity addition in Baden-Württemberg anchors barrier-coated paper substrate supply to protein processors.
For New Entrants and Emerging Players: Cloud kitchen operators in Bengaluru's IT corridor represent the most penetrable channel partner type for bespoke sachet geometries. New entrants should target India's Mid-Day Meal Scheme with portion-controlled, nutritionally fortified tray formats. Go-to-market angle: commission delivery-thermal-retention specifications at menu development stage rather than accepting standard supplier catalogs.
For Investors and Strategic Acquirers: Integrated paper-converter-chemical formulators are the most active acquirer in this space. Long-term viability over a multi-year window hinges on substrate versatility rather than scale economics alone. Acquisition target archetype: regional converters with in-house water-based barrier coating capability. Signal to watch: FDA food-contact notification timeline compression for novel grease-resistant paper substrates.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Capacity Expansion | Baden-Württemberg converters capture EFSA-certified retort pouch contracts from protein processors. |
| Backward Integration into Pulp Supply | Nordic softwood sourcing hedges European energy price volatility for molded fiber tray margins. |
| Cloud Kitchen Channel Partnership | Bengaluru IT corridor operators commission bespoke sachet geometries for thermal retention. |
| Mono-Material Web Investment | France AGEC compliance deadlines accelerate high-barrier polyethylene structure qualification. |
| Active Packaging Integration | Oxygen scavenger convergence extends ready-to-eat protein shelf life for African last-mile distribution. |
Research Methodology
Direct dialogue with packaging procurement managers at quick-service chains, converter plant managers in Germany and India, regulatory affairs specialists navigating FDA and EFSA dossier processes, and cloud kitchen operators in Bengaluru and Singapore grounded qualitative insights. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, FSSAI packaging standard notifications, customs data on aluminum laminate trade flows, and SEC filings of listed packaging converters. Bottom-up volume builds across format types triangulated against top-down market sizing from macro foodservice expenditure trends.
Segment-level projections across pouches, trays, cups, wraps, and sachets incorporate end-use temperature requirements, material qualification timelines, and channel-specific procurement patterns. Modeled dimensions span packaging type, distribution channel, end-user archetype, and application category. CAGRs derive from regression analysis of historical volume-price relationships against regulatory mandate implementation schedules. Forecast inputs include cloud kitchen proliferation rates in urban India and EU directive compliance deadline clustering effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pulp fiber cost volatility, aluminum laminate supply disruption, and migration testing bottleneck resolution. Projections reflect assumptions on regulatory enforcement timing and substrate substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Dosage Cups Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Candle Box Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Telescope Box Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Africa Flexitank Market