
 Thermoform Cups Market | 2026-2036
Thermoform Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoform Cups Market Analytics
Quick-service beverage programs is realigning demand toward lighter, stackable cup geometries that reduce freight cube and freezer storage. Dart Container Corporation dominates North American foodservice channels through captive manufacturing scale and direct distributor relationships. Genpak LLC differentiates via specialized cold-drink designs that resist condensation softening in humid climates. Huhtamaki North America leverages integrated European R&D networks to pilot next-generation barrier coatings.
Thermoform cups are thin-walled containers produced by heating plastic sheet—typically polypropylene, polystyrene, PET, or PLA—and vacuum-forming it over a mold, yielding rigid, lightweight vessels for cold beverages, portioned foods, and medical specimens. Wall thickness ranges from 0.15 mm to 0.50 mm, with rim-roll integrity determining stack height and shipping density. Among materials, PET leads in clarity-driven applications like smoothie retail, while PLA posts the fastest structural growth as foodservice chains respond to compostable mandates. Single-use formats still occupy the dominant volume position, though reusable cup deposit systems are carving margin pools in European cafe channels.
The FDA governs food-contact substance migration limits under 21 CFR, while the EPA tracks plastic waste streams that shape state-level extended producer responsibility proposals. The EU Green Deal and REACH chemical restrictions are accelerating PLA and bio-PET qualification timelines for export-bound suppliers. Stakeholders must monitor how fragmented US state legislation on polystyrene bans reshapes regional manufacturing footprints and material sourcing strategies.
Market Dynamics
The EU Single-Use Plastics Directive is forcing a material transition across foodservice supply chains, compressing qualification timelines for bio-based alternatives while reshaping manufacturing footprints toward compostable-capable assets.
Growth Catalysts
- Cold-beverage program expansion:Quick-service restaurant chains are scaling lightweight cup formats that reduce freight cube and freezer storage density. Drive-through and delivery formats sustain high cup throughput in the United States.
- REACH chemical restrictions:The EU Green Deal is accelerating PLA and bio-PET qualification timelines for export-bound suppliers seeking continued European market access.
- Portioned food applications:Medical specimen collection and prepared meal kits are diversifying demand beyond beverage service into precision-dosing formats.
Market Restraints
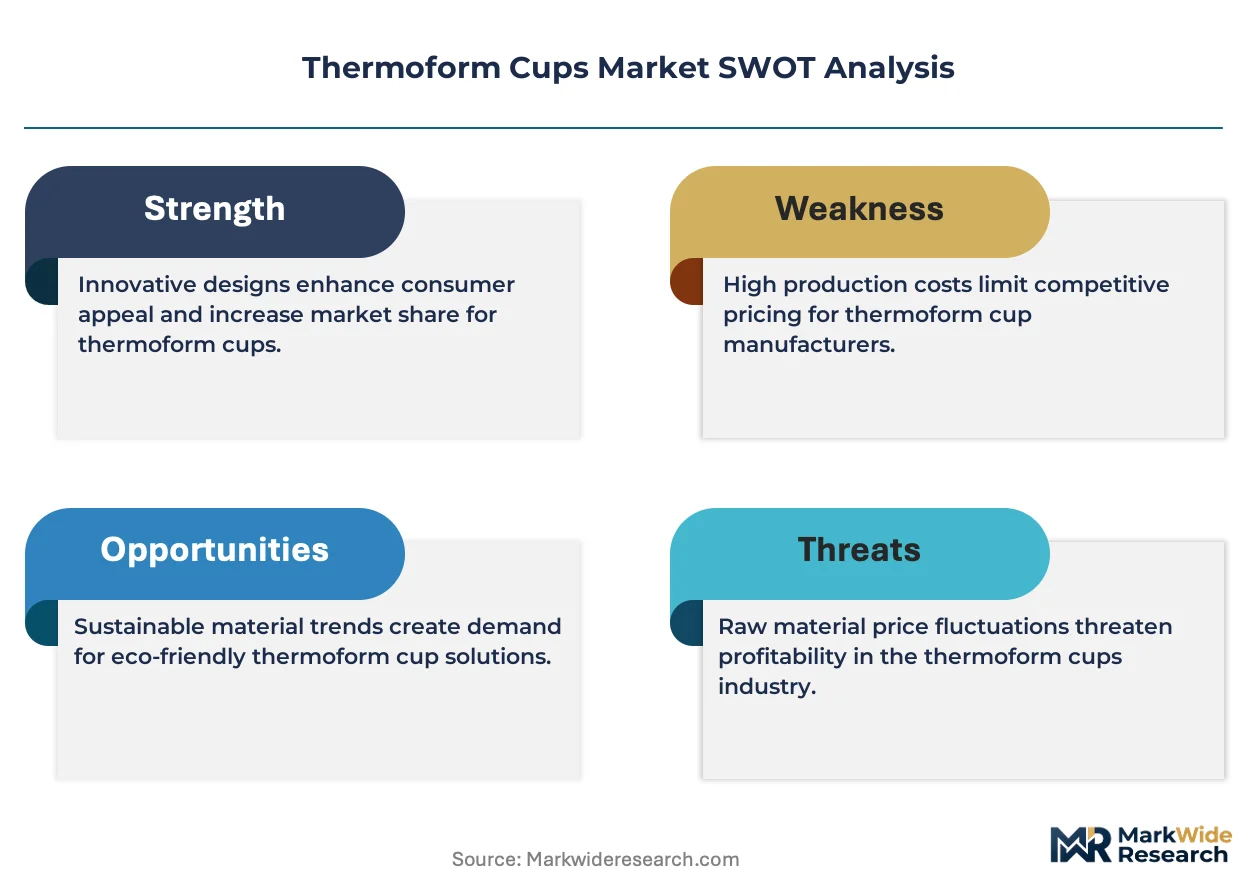
- Polystyrene feedstock volatility:Styrene monomer prices fluctuate with benzene-crude spreads, squeezing margin predictability for commodity cup producers.
- Composting infrastructure gaps:PLA cups require industrial composting facilities that remain concentrated in Germany, the Netherlands, and select US coastal corridors.
- Barrier coating limitations:Current water-based coatings struggle with extended cold-drink hold times, limiting adoption in humid climate markets.
Strategic Opportunities
- Reusable cup deposit systems:European cafe channels are piloting return-loop infrastructure that carves margin pools from single-use volume.
- Barrier coating convergence:Integration of plasma-deposited silicon oxide with bio-based substrates promises extended shelf life without fossil-derived layers.
- India foodservice modernization:Quick-service penetration in tier-2 cities creates first-mover positioning for cold-drink cup suppliers.
Industry Challenges
- Thermoforming technician scarcity:Vacuum-forming process optimization requires specialized calibration skills that outpace vocational training pipeline output.
- Extended producer responsibility compliance:Fragmented US state legislation on polystyrene bans forces redundant SKU proliferation and regional manufacturing reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoform Cups Market |
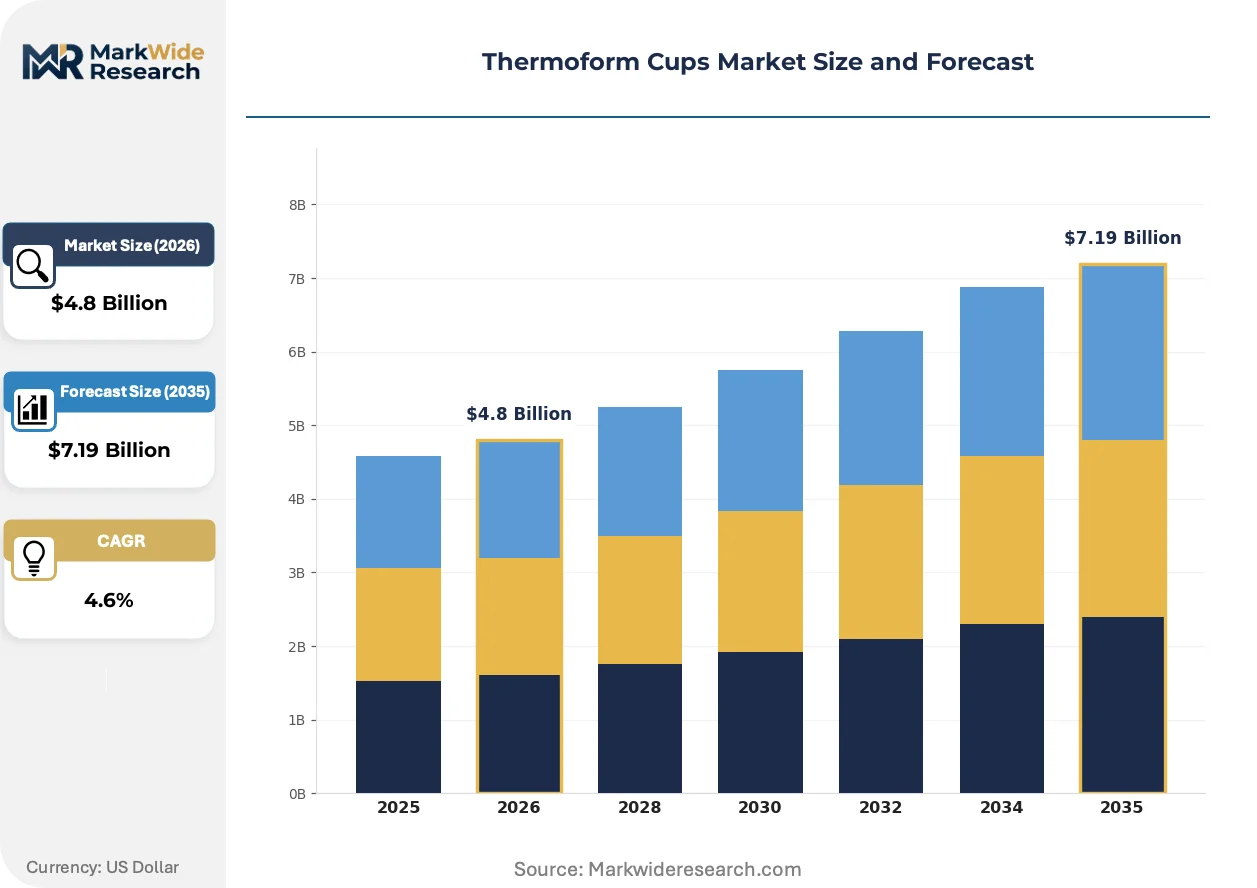
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Biodegradable, Compostable Material: Polypropylene, Polystyrene, PET, PLA Application: Food Service, Healthcare, Retail, Catering End User: Restaurants, Cafes, Food Trucks, Delivery Services |
| Companies Covered | Dart Container Corporation, Genpak LLC, Amcor plc, Huhtamaki North America, Sabert Corporation, Berry Global Inc., Pactiv Evergreen Inc., WNA (Waddington North America), Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoform Cups Market Evolving Landscape
Active investment in automation, barrier science, and circular infrastructure is compressing production economics while elevating performance thresholds for next-generation cup formats.
Robotic pick-and-place systems integrated with vision-guided quality inspection are automating thermoforming line changeovers that previously required manual die alignment. Tier-1 foodservice suppliers in Germany and the United States are deploying these cells to cut format-switch downtime from hours to minutes. The resulting throughput flexibility is automating just-in-sequence production for promotional cup campaigns with compressed lead times.
The EU Green Deal's packaging waste reduction targets are mandating minimum recycled content thresholds that outpace current rPET food-grade availability. Major quick-service chains are responding with binding supplier commitments to 30% post-consumer content by 2030. This regulatory pressure is accelerating chemical recycling pilot investments in the Netherlands and Spain to bridge the food-contact quality gap.
Consolidated procurement by multi-brand restaurant operators is compressing supplier qualification cycles and unbundling tooling ownership from volume commitments. National account teams now specify cup geometries directly, bypassing traditional distributor specification roles. This concentration is most visible in the United States, where three holding companies control procurement for over forty percent of quick-service cold-beverage outlets.
Thermoform Cups Market Segmentation
Thermoform cup procurement decisions hinge on trade-offs between unit economics, regulatory compliance, and operational throughput. Distinct segment profiles emerge across material chemistry, use-case durability, and channel-specific logistics requirements.
Product Type:
Buyer priorities split between lowest landed cost for high-turnover channels and compliance-driven premium formats for regulated environments.
- Single-Use:Thin-walled formats dominate quick-service cold-beverage programs where stack height and shipping density determine distributor economics. Drive-through throughput in the United States sustains massive volume concentration despite mounting EPR pressure in coastal states.
- Reusable:Deposit-return systems in German and Dutch cafe channels require thicker-wall construction with standardized rim geometries for automated washing infrastructure. Margin pools shift from unit sales to logistics fees and breakage insurance.
- Biodegradable:OXO-additive formulations serve markets lacking industrial composting access, though anaerobic landfill decomposition rates remain contested by EU regulators.
- Compostable:PLA-based cups qualify for BPI and TÜV OK compost HOME certifications, commanding price premiums where municipal collection infrastructure exists.
Volume sits with single-use formats; growth tilts toward compostable alternatives as EPR schemes expand.
Material:
Material selection tracks clarity requirements, temperature resistance, and regional feedstock availability.
- PET:Amorphous grades deliver optical clarity for smoothie and specialty beverage retail where visual presentation drives impulse purchase. rPET food-grade qualification bottlenecks constrain post-consumer content claims despite quick-service chain commitments.
- PLA:Fermented corn-starch polymer posts steepest expansion trajectory as EU Single-Use Plastics Directive deadlines approach. Heat-deflection temperature limitations restrict hot-fill applications to sub-50°C service.
- Polypropylene:High melt strength enables deep-draw forming for portioned food containers with snap-fit lids. Gulf Coast propylene monomer supply advantages concentrate North American production.
- Polystyrene:General-purpose crystal grades retain cost leadership in commodity cold-cup segments. Benzene-crude spread volatility compresses margin predictability for integrated producers.
PET commands clarity-premium positioning; PLA gains regulatory tailwinds fastest.
Application:
Use-case specifications diverge on barrier performance, sterilization compatibility, and branding surface area.
- Food Service:Cold-beverage formats prioritize condensation resistance and stack stability for humid climate distribution. Quick-service chains specify direct-print compatible surfaces for promotional campaigns.
- Healthcare:Specimen collection cups require graduated measurement markings and leak-resistant snap seals under FDA 21 CFR quality system regulations. Gamma-sterilizable PP grades dominate clinical laboratory procurement.
- Retail:Private-label yogurt and dessert formats emphasize shelf-appeal through custom color matching and in-mold labeling compatibility.
- Catering:Event-service volumes demand nested stacking for transport efficiency and portion-size standardization across buffet lines.
Food service absorbs highest absolute volume; healthcare maintains strictest qualification barriers.
End User:
Channel-specific logistics and brand positioning reshape cup geometry and order-pattern requirements.
- Restaurants:Full-service establishments favor printed cups reinforcing brand identity, with order patterns tied to menu cycle refreshes rather than daily throughput.
- Cafes:European independent coffee shops pilot return-loop cup systems with RFID tracking, shifting supplier relationships toward fleet-management service contracts.
- Food Trucks:Mobile operators prioritize nested cube efficiency and lid-interchangeability across multiple beverage formats to minimize SKUs in constrained storage.
- Delivery Services:Third-party logistics platforms specify tamper-evident sealing compatibility and insulation performance for extended transit times in aggregator networks.
Delivery services scale fastest through platform consolidation; cafes drive circular-format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters along the US Gulf Coast and in Germany's industrial belt, while consumption concentrates in quick-service corridors across North America and Western Europe. Asia-Pacific markets absorb expanding production from domestic thermoforming lines serving localized cold-beverage programs.
United States
Drive-through beverage throughput sustains massive cup volume across quick-service chains, with Texas and Georgia hosting concentrated thermoforming production corridors. FDA 21 CFR food-contact regulations govern migration limits for all foodservice packaging. The Southeast manufacturing belt—spanning Georgia, Alabama, and Tennessee—houses integrated sheet extrusion and forming operations serving national distributor networks.
Germany
Deposit-return cafe systems in Berlin and Hamburg generate specialized demand for thicker-wall reusable formats with standardized rim geometries. EU Green Deal packaging waste targets mandate minimum recycled content thresholds that reshape supplier qualification timelines. The North Rhine-Westphalia industrial cluster hosts pilot chemical recycling investments bridging rPET food-grade availability gaps.
China
Tier-2 city quick-service penetration creates first-mover positioning for cold-drink cup suppliers targeting emerging foodservice modernization. SAMR food-contact material standards and GB national standards regulate plastic migration limits for domestic and export-bound production. The Yangtze River Delta manufacturing corridor—centered on Shanghai and Jiangsu Province—integrates sheet extrusion, thermoforming, and downstream printing for regional quick-service chains.
India
Quick-service restaurant expansion in Mumbai, Bangalore, and Hyderabad drives demand for lightweight, nested cup formats suited to humid climate distribution. FSSAI food safety regulations govern plastic food-contact materials across centralized and distributed production models. The Maharashtra-Gujarat industrial corridor hosts emerging thermoforming capacity serving domestic foodservice and pharmaceutical specimen collection markets.
Brazil
Food truck and street vending culture in São Paulo and Rio de Janeiro prioritizes cube-efficient nested stacking and lid interchangeability across constrained mobile storage. ANVISA pharmaceutical and food-contact regulations establish compliance baselines for healthcare and foodservice applications. The São Paulo state manufacturing cluster concentrates domestic sheet extrusion and vacuum-forming operations serving Latin American export markets.
Thermoform Cups Market Competitive Landscape
Top-tier vendors anchor North American foodservice channels through captive manufacturing scale, while mid-tier specialists occupy regional niches and material-specific segments. The vendor base stratifies across integrated resin-to-cup producers, independent thermoforming specialists, and diversified packaging conglomerates with beverage-format divisions. Strategic archetypes include scale-driven commodity producers, compliance-focused bio-based innovators, and logistics-integrated service providers. Competitive moves concentrate on capacity expansion in compostable-capable assets and strategic partnerships with quick-service chains for direct specification relationships.
Among North American foodservice suppliers, Dart Container Corporation, Genpak LLC, and Huhtamaki North America exemplify distinct strategic positioning within the tiered competitive structure. Dart Container Corporation represents the scale-anchored archetype with integrated resin handling and captive distributor relationships. Genpak LLC occupies the specialized-format position, with company nomenclature signaling focused thermoforming expertise rather than diversified packaging breadth. Huhtamaki North America exemplifies the transnational R&D-integrated model, leveraging cross-border technical networks to pilot next-generation barrier coatings and bio-based substrates.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Genpak LLC |
| Amcor plc |
| Huhtamaki North America |
| Sabert Corporation |
| Berry Global Inc. |
| Pactiv Evergreen Inc. |
| WNA (Waddington North America) |
| Silgan Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Benzene-crude spread volatility cascades through styrene monomer pricing into commodity polystyrene cup tiers, compressing margins for integrated producers while bio-based PLA alternatives capture premium positioning in EU-mandated transitions.
Pricing Analysis
Margin tightening in standard-grade polystyrene cups reflects feedstock cost instability and regional ban proliferation, while PET clarity-premium tiers hold firmer. Three-tier pricing structure across compostable-certified, food-grade standard, and economy polystyrene levels separates buyers by regulatory exposure and brand positioning needs. Cost-down pressure on commodity tiers accelerates because quick-service chains consolidate procurement under national account structures. Price sensitivity concentrates among high-volume distributor intermediaries, whereas healthcare specimen cup buyers prioritize sterilization compatibility over unit cost.
Supply Chain Analysis
Thermoforming technician scarcity across the US Southeast and Germany's industrial belt constrains capacity expansion timelines for next-generation barrier coating lines. Supply concentrates in the United States, Germany, and China, with Gulf Coast propylene feedstock advantages anchoring North American polypropylene output. Raw material flows draw from benzene derivatives, fermented corn-starch biopolymer feedstocks, and post-consumer PET flake streams. Single-source vulnerability sits with industrial composting infrastructure gaps that strand PLA cup value in landfill-bound regions. Distribution runs through captive distributor networks and direct quick-service chain specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoform cups market is becoming a vertical-integration race, with upstream resin handling and downstream direct specification relationships representing the decisive control points for margin capture.
For Market Incumbents: Acquire compostable-capable thermoforming assets in EU-adjacent production corridors to preempt qualification bottlenecks as the EU Single-Use Plastics Directive deadlines approach. Secure captive rPET food-grade supply through chemical recycling partnerships in the Netherlands or Spain, insulating against post-consumer content mandates that outpace mechanical recycling availability. For New Entrants and Emerging Players: Quick-service penetration in India's tier-2 cities offers white-space positioning for lightweight cold-drink cup formats suited to humid climate distribution. Target deposit-return system logistics contracts in German and Dutch cafe channels, where fleet-management service models displace traditional unit sales. Lead with barrier coating innovation that extends cold-drink hold times without fossil-derived layers. For Investors and Strategic Acquirers: Binding supplier commitments to 30% post-consumer content by 2030 from major quick-service chains is the leading indicator that chemical recycling infrastructure will command scarcity premiums. Position for mid-cap thermoforming specialists with integrated sheet extrusion and direct distributor relationships, as consolidation accelerates under national account procurement concentration. Watch for state-level extended producer responsibility legislation triggering redundant SKU proliferation and regional manufacturing reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Bridges food-contact quality gaps for rPET mandates under EU Green Deal targets. |
| Compostable Asset Expansion | Qualifies suppliers for BPI and TÜV OK compost certifications in EPR-regulated states. |
| Direct Specification Relationship | Bypasses distributor intermediaries as three holding companies control 40% of US quick-service procurement. |
| Barrier Coating Convergence | Integrates plasma-deposited silicon oxide with bio-based substrates for extended shelf life. |
| Deposit-Return System Pilot | Shifts margin pools from unit sales to logistics fees in Berlin and Hamburg cafe channels. |
Research Methodology
Document review covered FDA 21 CFR filings, EU Green Deal packaging waste directives, SEC 10-K disclosures from packaging conglomerates, and trade data from USITF and Eurostat, complemented by interviews with thermoforming plant managers, quick-service chain procurement directors, distributor category buyers, and chemical recycling technology leads. Secondary validation drew from SAMR food-contact standards, BPI certification databases, and state-level EPR legislative trackers. Bottom-up capacity estimates triangulated against top-down demand modeling from quick-service cold-beverage throughput data.
Segment-level outputs across material chemistry, use-case durability, and channel-specific logistics requirements were generated through structured forecasting. The analytical framework modeled volume trajectories across single-use, reusable, biodegradable, and compostable product types; PET, PLA, polypropylene, and polystyrene materials; and food service, healthcare, retail, and catering applications. CAGRs were derived from regression analysis against quick-service chain expansion rates, regulatory deadline schedules, and composting infrastructure buildout timelines. Feedstock price elasticity and barrier coating adoption curves informed sensitivity bounds.
Several conditions sit outside the modeled scope, including unannounced national bans on polystyrene, breakthroughs in home-compostable polymer formulations, and abrupt shifts in crude oil pricing affecting virgin resin economics. Forecasts reflect assumptions about regulatory implementation pacing and industrial composting facility deployment. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Telescope Box Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Candle Box Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Bottles Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Cluster Packaging Market