
 Slide Tray Box Market | 2026-2036
Slide Tray Box Market Size, Share, and Industry Trends Forecast 2026-2036
Slide Tray Box Market Outlook
Consolidation among pharmaceutical distributors and clinical laboratory networks is repositioning procurement leverage toward volume buyers with standardized specifications. Smurfit Kappa Group leverages its European corrugated footprint to serve temperature-sensitive diagnostic workflows. Mondi Group sustains innovation in barrier-coated paperboard that competes with plastic alternatives in regulated transport. WestRock anchors North American supply through integrated containerboard and converting assets.
A slide tray box is a rigid packaging format engineered with layered compartments or sliding drawer mechanisms to organize, protect, and present flat items such as microscope slides, product samples, or retail merchandise, typically constructed from corrugated fiberboard, solid bleached sulfate, or extruded polymer substrates with critical tolerances for dimensional stability and contamination resistance. Cardboard variants dominate current volume given recyclability alignment with EU packaging regulations and US EPA waste reduction guidelines, while plastic formulations lead in moisture-barrier applications for pathology specimen transport where sterility protocols apply. The custom capacity tier captures premium margin pools as healthcare and precision instrument sectors specify anti-static coatings, foam inserts, and serialized tracking features that standard sizes cannot accommodate.
The US EPA and FDA jointly shape domestic product requirements through hazardous material transport rules and medical device packaging standards, while REACH and the EU Green Deal mandate recyclability disclosures and recycled content minimums for European market access. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as compliance costs will increasingly determine supplier selection and material substitution timelines.
Market Dynamics
Consolidation among pharmaceutical distributors and clinical laboratory networks concentrates procurement leverage toward volume buyers demanding standardized specifications with integrated temperature-monitoring capabilities.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability disclosures and recycled content minimums accelerate cardboard tray box adoption over plastic alternatives in German pharmaceutical distribution.
- Specimen transport protocols:Clinical laboratories and biobanks in the United States drive specialized cold-chain compliant procurement for pathology workflows.
- Barrier-coated paperboard innovation:Moisture-resistant fiberboard formulations displace polymer substrates in regulated diagnostic transport without sacrificing sterility standards.
Market Restraints
- Pulp fiber cost volatility:Containerboard input prices fluctuate with energy and recovered paper availability, compressing converter margins on standard-grade slide tray boxes.
- Plastic substitution in moisture-critical applications:Extruded polymer substrates retain dominance where sterility protocols mandate absolute barrier performance, limiting fiberboard penetration.
- REACH compliance complexity:Chemical substance registration requirements for coatings and adhesives create friction for smaller European converters serving healthcare markets.
Strategic Opportunities
- Serialized tracking integration:Anti-static coatings combined with RFID and blockchain-enabled traceability create premium positioning for precision instrument sectors requiring chain-of-custody documentation.
- Extended producer responsibility frameworks:Evolving EPR schemes in multiple jurisdictions reward suppliers with closed-loop material recovery systems and documented circularity credentials.
- Custom foam insert specialization:Healthcare and diagnostic equipment sectors specify engineered cushioning and anti-static properties that standard sizes cannot accommodate.
Industry Challenges
- Cleanroom manufacturing certification:ISO 14644 compliance for particle control adds capital intensity and timeline risk for converters entering medical device packaging tiers.
- Multi-jurisdiction regulatory synchronization:Stakeholders must reconcile FDA medical device packaging standards with EPA hazardous material transport rules and EU MDR requirements simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slide Tray Box Market |
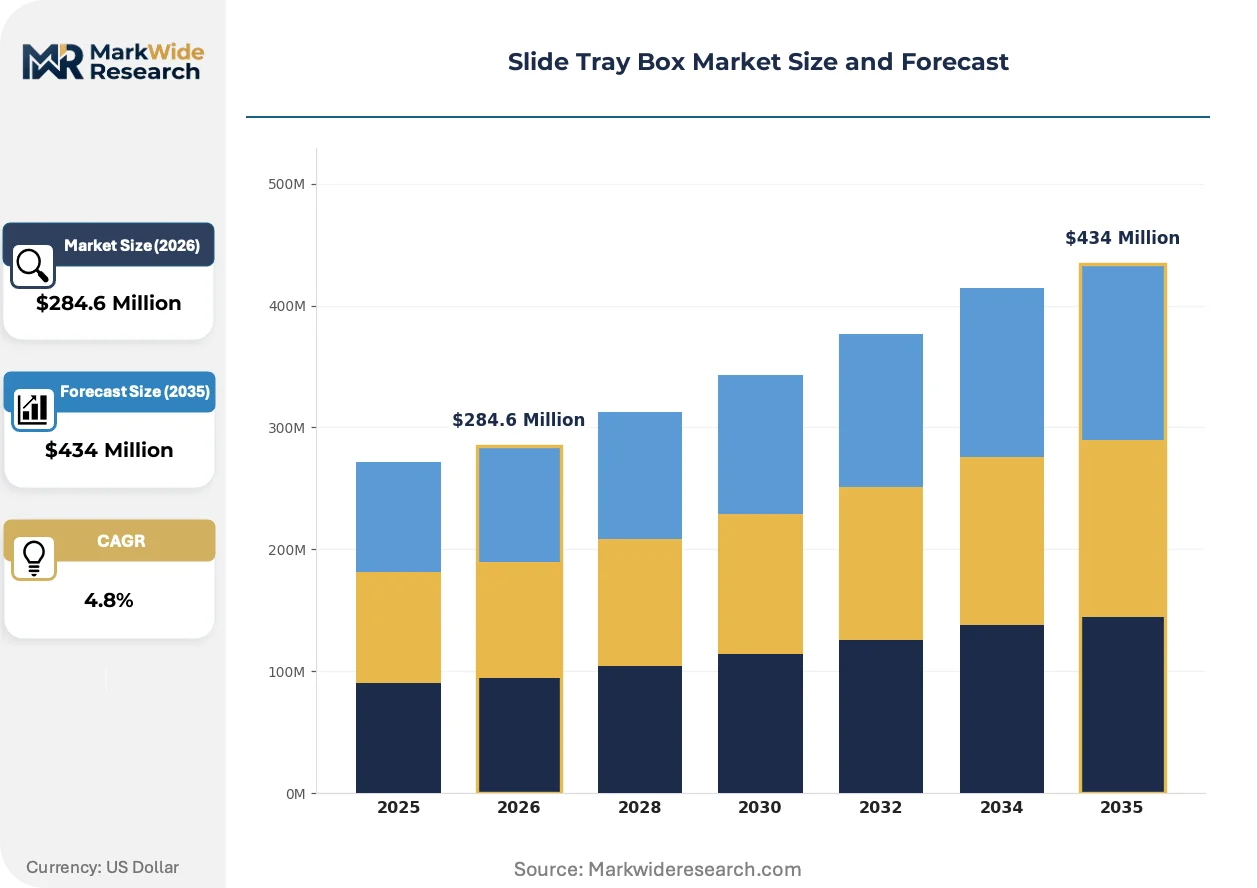
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $434 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Wood, Metal Capacity: Small, Medium, Large, Custom End User: Retail, E-commerce, Manufacturing, Healthcare Distribution Channel: Online, Offline, Direct, Wholesalers |
| Companies Covered | Smurfit Kappa Group, Mondi Group, WestRock, DS Smith Packaging, VPK Packaging Group, Stora Enso Oyj, International Paper Company, Smurfit Kappa Group Plc, Mondi Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slide Tray Box Market Strategic Shifts
Active reshaping of the slide tray box market centers on material science breakthroughs, regulatory disclosure mandates, and procurement centralization among consolidated healthcare networks.
Barrier-coated solid bleached sulfate is expanding into moisture-sensitive diagnostic workflows previously reserved for polymer constructions. Clinical laboratories in the United States adopt these fiberboard alternatives at accelerating pace as FDA packaging validation protocols accommodate paper-based sterility claims. This expansion is compressing addressable demand for extruded plastic tray boxes in regulated transport segments.
REACH and the EU Green Deal mandate granular recyclability disclosures and recycled content minimums for European market access. Industrial consequence falls heaviest on pharmaceutical distributors sourcing temperature-compliant packaging, who now require supplier documentation of circular material flows. German distribution networks respond by consolidating procurement around converters with integrated recovered fiber streams and EPR-compliant take-back programs.
Centralized procurement among merged laboratory networks displaces fragmented purchasing across independent clinical sites. Group purchasing organizations negotiate standardized slide tray specifications with embedded temperature indicators and serialized tracking, squeezing regional converters lacking scale or certification breadth. This concentration is most visible in United States metropolitan healthcare clusters where hospital system consolidation has advanced furthest.
Slide Tray Box Market Segmentation
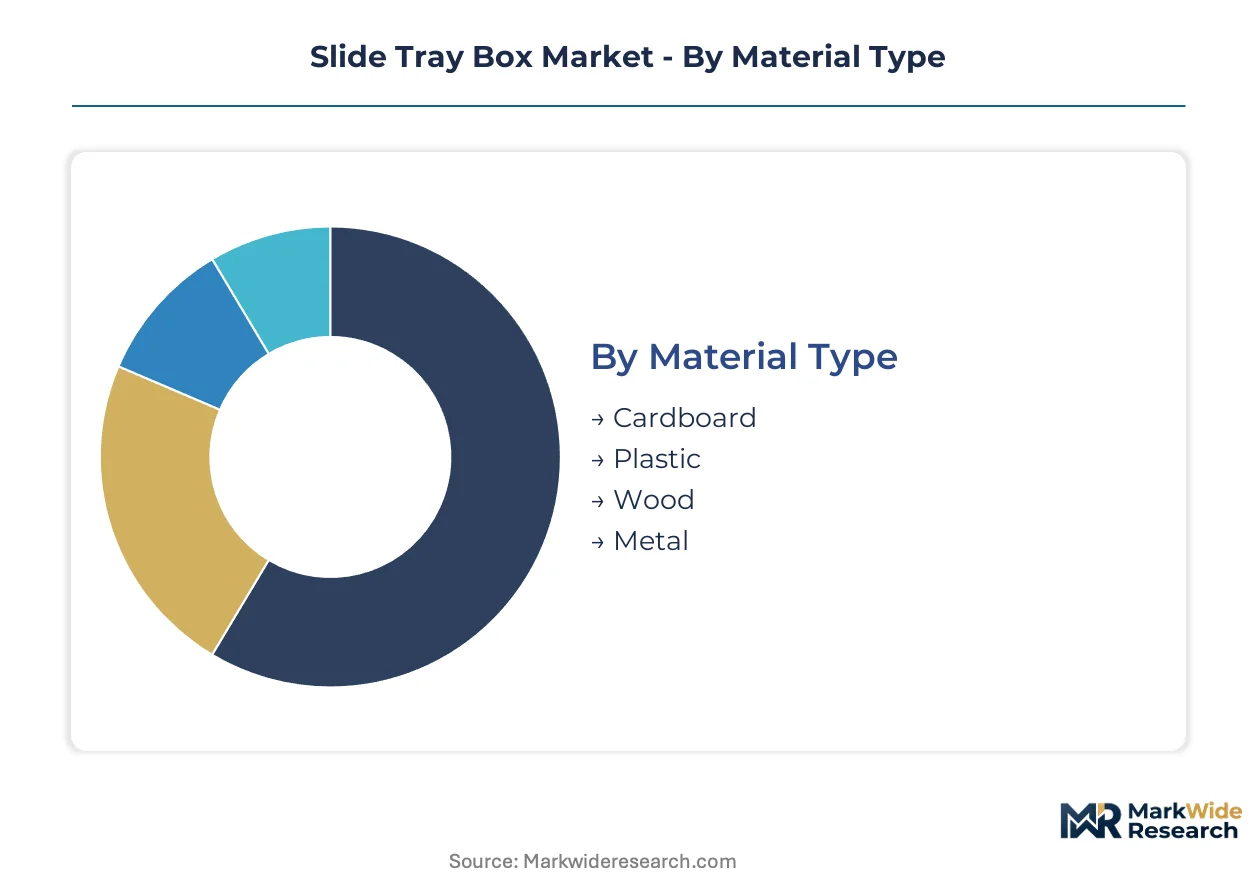
Material composition and capacity configuration determine regulatory compliance pathways and margin structures for slide tray box procurement. Healthcare and diagnostic sectors impose sterility and dimensional tolerances that fragment demand across substrate categories and custom fabrication tiers.
Material Type:
Volume concentrates in recyclable fiberboard formats while premium moisture barriers sustain polymer relevance in regulated transport.
- Cardboard:Corrugated fiberboard and solid bleached sulfate formulations align with EU Green Deal recyclability mandates and US EPA waste reduction protocols. German pharmaceutical distributors are consolidating procurement around converters with integrated recovered fiber streams and documented circularity credentials.
- Plastic:Extruded polymer substrates deliver absolute moisture barrier performance for pathology specimen transport where FDA sterility protocols apply. Clinical laboratories in the United States retain polymer specifications for cold-chain compliant workflows despite fiberboard innovation.
- Wood:Precision-milled hardwood constructions serve microscopy slide archiving in academic and museum collections requiring dimensional stability over multi-decade horizons.
- Metal:Aluminum and stainless steel fabrications address cleanroom manufacturing environments demanding ISO 14644 particle control and electromagnetic shielding for sensitive instrumentation.
Today's leader: Cardboard. Tomorrow's challenger: Plastic.
Capacity:
Standardized dimensions serve consolidated laboratory networks while engineered custom formats capture healthcare premium tiers.
- Small:Compact slide tray boxes organize 25-50 microscope slides for individual diagnostic procedures and field collection protocols.
- Medium:Intermediate formats balance transport efficiency with handling ergonomics for mid-volume clinical laboratory workflows.
- Large:High-capacity constructions serve biobank archival and bulk specimen distribution with integrated temperature-monitoring capabilities.
- Custom:Engineered specifications with anti-static coatings, foam inserts, and serialized tracking features command premium positioning in precision instrument sectors. Group purchasing organizations in United States metropolitan healthcare clusters negotiate these configurations with embedded RFID and blockchain-enabled traceability.
Standard sizes dominate procurement volume. Custom formats expand most quickly as chain-of-custody documentation requirements intensify.
End User:
Healthcare procurement concentrates technical specifications while retail and e-commerce segments prioritize presentation and fulfillment efficiency.
- Retail:Visual merchandising formats emphasize product presentation with sliding drawer mechanisms for cosmetics, jewelry, and premium consumer goods.
- E-commerce:Protective constructions balance dimensional efficiency with damage resistance for last-mile delivery of flat merchandise and sample kits.
- Manufacturing:Industrial slide trays organize component parts and quality control specimens with tolerance-critical compartment spacing.
- Healthcare:Clinical laboratories and biobanks in the United States drive specialized cold-chain compliant procurement for pathology workflows. FDA packaging validation protocols and specimen transport regulations shape material selection and sterility documentation requirements.
Healthcare commands specification intensity. E-commerce represents the steepest expansion trajectory as direct-to-consumer diagnostic sampling proliferates.
Distribution Channel:
Procurement centralization among merged laboratory networks displaces fragmented purchasing across independent clinical sites.
- Online:Digital procurement platforms serve independent laboratories and research facilities with standardized specifications and rapid replenishment cycles.
- Offline:Traditional distributor relationships sustain regional converter access for healthcare systems with legacy supply arrangements.
- Direct:Converter-direct contracts capture volume concentration among consolidated pharmaceutical distributors and clinical laboratory networks negotiating standardized slide tray specifications.
- Wholesalers:Medical supply distributors aggregate demand across fragmented independent sites with inventory pooling and consolidated logistics.
Direct channels strengthen with buyer consolidation. Wholesalers defend position through inventory proximity and service breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled packaging engineers and cold-chain logistics specialists cluster around pharmaceutical manufacturing corridors in Germany, the United States, and Switzerland. These talent concentrations anchor regional procurement patterns for temperature-compliant slide tray specifications.
United States
Clinical laboratory networks in Boston and San Diego drive specialized specimen transport procurement with embedded temperature-monitoring capabilities. FDA packaging validation protocols for medical devices shape material selection and sterility documentation requirements. Consolidated hospital systems in metropolitan healthcare clusters negotiate standardized specifications through group purchasing organizations.
Germany
Pharmaceutical distributors in Bavaria and North Rhine-Westphalia expand cold-chain compliant slide tray box procurement as sustainability mandates tighten. REACH chemical substance registration requirements for coatings and adhesives create compliance friction for smaller converters. The country's national pharmaceutical regulator enforces granular recyclability disclosures that reward suppliers with documented circular material flows.
Switzerland
Precision instrument manufacturers in Basel and Zurich specify anti-static coatings and serialized tracking features for microscopy slide archiving. Swissmedic medical device standards align with EU MDR requirements while maintaining distinct national sterility protocols. The Lake Geneva corridor hosts specialized converters serving pharmaceutical and diagnostic equipment sectors.
China
Domestic diagnostic equipment producers in Shanghai and Suzhou source slide tray boxes for export-oriented manufacturing of microscopy and pathology instruments. NMPA medical device packaging standards increasingly reference international sterility protocols. The Yangtze River Delta concentration of contract manufacturers drives standard-grade volume procurement with accelerating custom specification adoption.
Japan
Academic research institutions in Tokyo and Osaka maintain demand for precision-milled hardwood slide tray constructions requiring multi-decade dimensional stability. PMDA pharmaceutical regulations influence packaging material selection for diagnostic specimen transport. The Kansai region's microscopy equipment heritage sustains niche demand for archival-grade storage formats.
Slide Tray Box Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material substrate categories and geographic footprints. The vendor base organizes into three tiers: integrated containerboard producers with converting assets, specialty paperboard converters with barrier-coating capabilities, and regional fabricators serving localized healthcare networks. Two dominant competitive moves define current positioning: backward integration into recovered fiber streams to satisfy EPR compliance requirements, and strategic partnerships with temperature-monitoring technology providers to embed smart logistics features.
Within the integrated European tier, Smurfit Kappa Group and Mondi Group exemplify converters leveraging corrugated footprint scale to serve temperature-sensitive diagnostic workflows. WestRock anchors North American supply through integrated containerboard and converting assets. These three companies occupy positions that reflect the market's bifurcation between recyclability-mandated fiberboard adoption and moisture-critical polymer retention.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Mondi Group |
| WestRock |
| DS Smith Packaging |
| VPK Packaging Group |
| Stora Enso Oyj |
| International Paper Company |
| Smurfit Kappa Group Plc |
| Mondi Group plc |
| Others |
Value Chain & Pricing Dynamics
Packaging engineers and cold-chain logistics specialists concentrated in Germany's Bavaria region and the United States' Boston corridor create labor-cost differentials that widen pricing-tier spreads between premium custom specifications and standard-grade volume procurement.
Pricing Analysis
Bundled temperature-monitoring and serialized tracking services separate premium-tier contracts from unbundled standard-grade procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with FDA-validated medical device packaging commanding substantial premiums over EPA-compliant general transport formats. Cost compression in standard-grade fiberboard is intensifying because pulp fiber input volatility squeezes converter margins. Group purchasing organizations in United States metropolitan healthcare clusters exhibit lowest price sensitivity, while independent clinical laboratories in fragmented European markets negotiate hardest on unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated pharmaceutical distributors, while medical supply wholesalers aggregate fragmented independent laboratory demand with inventory pooling. Geographic supply concentrates in Germany, the United States, and China, with recovered fiber streams and barrier-coating chemical inputs drawing from Nordic pulp producers and Asian petrochemical complexes. Single-source vulnerability in specialized anti-static coating formulations creates structural risk for converters serving precision instrument sectors. Distribution runs through converter-direct contracts for volume buyers and traditional distributor relationships for regional healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slide tray box market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany exceed EPA waste reduction requirements in the United States, creating margin expansion opportunities for North American exporters.
For Market Incumbents: Cement backward integration into recovered fiber streams to satisfy extended producer responsibility mandates before REACH chemical registration requirements tighten. Capture scale advantages in barrier-coated paperboard R&D to defend against polymer substitution in moisture-critical pathology applications. Prioritize ISO 14644 cleanroom certification investments to lock out regional competitors from medical device packaging tiers.
For New Entrants and Emerging Players: Capture whitespace in custom foam insert specialization for precision instrument sectors where anti-static and serialized tracking specifications outpace incumbent converter capabilities. Target independent clinical laboratories in European markets fragmented by national pharmaceutical regulator variations. Pursue digital procurement platform partnerships to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Specialty paperboard converters with barrier-coating capabilities are the most active acquirer targets in this space, as diversified packaging conglomerates seek technical differentiation. Long-term viability hinges on circular material flow documentation and EPR-compliant take-back infrastructure. Watch for inflection when FDA packaging validation protocols formally recognize fiberboard sterility claims in cold-chain diagnostic transport.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber | Captures EPR compliance advantage as EU Green Deal mandates tighten recyclability disclosures. |
| Barrier-Coating R&D Partnership | Accelerates fiberboard penetration into FDA-regulated pathology specimen transport workflows. |
| Temperature-Monitoring Technology Embedding | Differentiates premium tier for biobank and clinical laboratory GPO contracts. |
| ISO 14644 Cleanroom Certification | Unlocks medical device packaging revenue pools with particle control requirements. |
| Serialized Tracking Integration | Enables blockchain-enabled chain-of-custody documentation for precision instrument sectors. |
Study Parameters
Direct dialogue with packaging procurement managers at pharmaceutical distributors, clinical laboratory operations directors, biomedical engineers, and corrugated converter plant managers grounded this analysis in operational reality. Secondary validation drew from FDA 510(k) filings, EPA hazardous material transport rulemakings, EU Green Deal implementation texts, and hospital group purchasing organization contract databases. Bottom-up volume modeling triangulated against top-down market sizing across material type, capacity configuration, and end-user segmentation.
Bottom-up demand modeling tracked procurement patterns across the analysis window, while top-down macro validation anchored projections in healthcare infrastructure investment cycles and diagnostic testing volume trends. Segmentation dimensions included material substrate, capacity tier, end-use application, and distribution channel, with regional regulatory clusters treated as distinct adoption corridors. CAGRs derived from elasticity-adjusted volume trajectories incorporating pulp fiber cost volatility and compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; healthcare end-use data carries tighter precision than retail and e-commerce applications given procurement transparency through GPO contracts. Forecasts reflect assumptions about REACH chemical registration timelines and FDA packaging validation protocol evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Can Holders Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Cooler Box Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Sanitizer Bottles Market